
 Inflammatory Diseases Market | 2026-2036
Inflammatory Diseases Market Size, Share, and Industry Trends Forecast 2026-2036
Inflammatory Diseases Market Foresight
Multi-source biologic supply is decoupling from legacy single-source dependencies as manufacturers diversify active pharmaceutical ingredient networks. Pfizer anchors its position through backward integration into monoclonal antibody production. AbbVie leverages extensive immunology pipelines to sustain market presence across rheumatoid arthritis and psoriasis. Novartis differentiates through cell therapy manufacturing capabilities that extend beyond traditional small-molecule infrastructure.
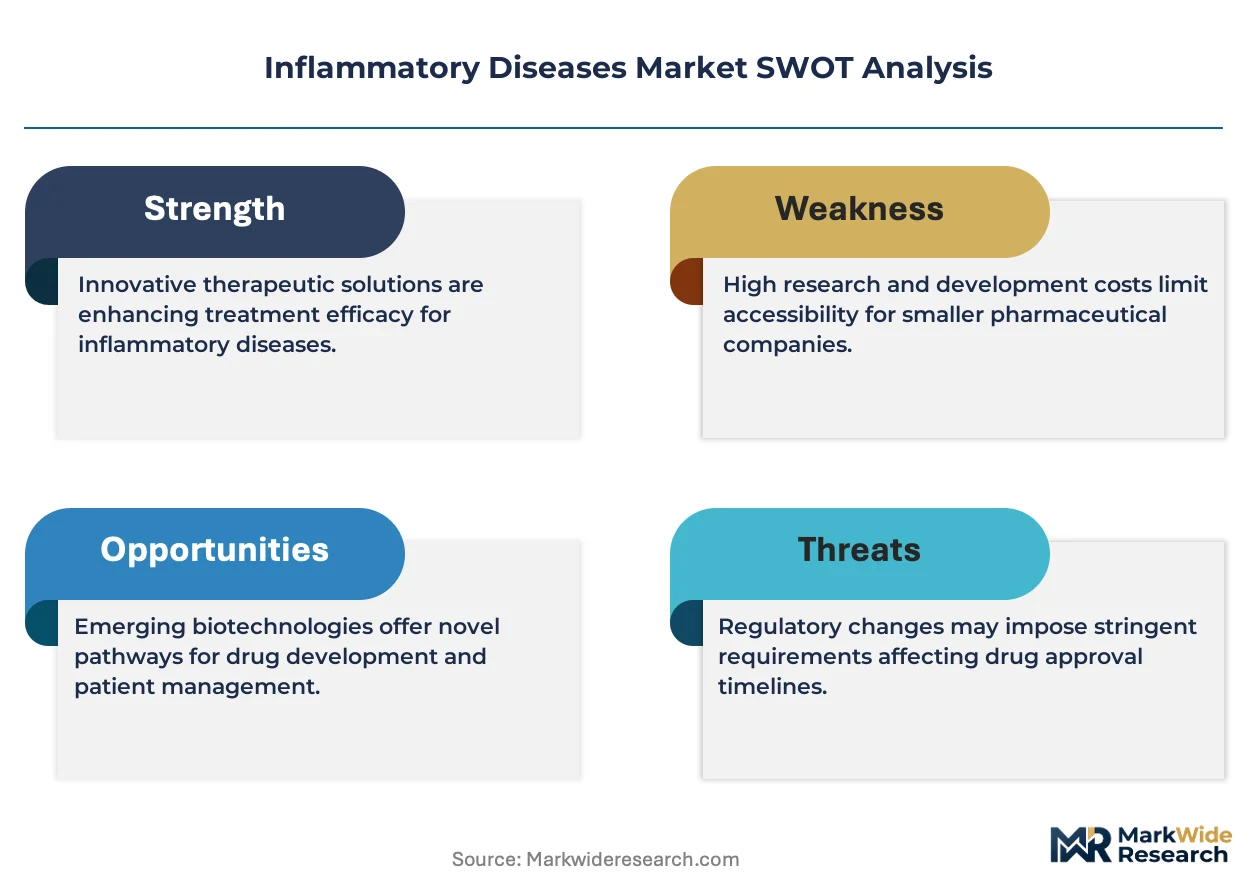
Inflammatory diseases encompass chronic immune-mediated conditions characterized by dysregulated cytokine signaling, tissue infiltration by activated leukocytes, and persistent activation of NF-κB and JAK-STAT pathways; therapeutic intervention targets specific inflammatory mediators to halt tissue destruction and restore immune homeostasis. Biologics command premium positioning due to validated clinical outcomes in refractory patient populations, while small molecules retain cost-access advantages in earlier treatment lines. Injectable delivery dominates hospital and specialty clinic administration, though oral formulations gain traction in maintenance therapy settings where patient self-management priorities shift.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape competitive entry dynamics for novel mechanisms. WHO prequalification standards and national pharmacovigilance requirements in major markets govern post-market surveillance obligations for immunomodulatory agents. Stakeholders must monitor biosimilar substitution policies and interchangeability designations as these regulatory determinations reshape procurement economics and brand defense strategies.
Market Dynamics
Specialty pharmacy networks are consolidating distribution control as biologic formularies expand, creating a structural bottleneck where formulary placement determines patient access more than clinical differentiation alone.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated approval timelines compress development cycles from ten years to six, enabling earlier revenue recognition for novel mechanisms targeting refractory autoimmune populations.
- Cell Therapy Manufacturing:Autologous CAR-T infrastructure originally built for oncology is repurposing toward autoimmune indications, leveraging existing cleanroom capacity and apheresis networks.
- Japan's Sakigake Designation:Priority review for first-in-Japan therapies creates a parallel fast-track that rewards simultaneous US-Japan development strategies with twelve-month regulatory advantages.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over seventy percent of monoclonal antibody drug substance originates from contract manufacturers in South Korea and Singapore, creating single-point-of-failure exposure.
- EMA Pharmacovigilance Burden:Post-authorization safety study mandates for immunomodulators extend surveillance obligations to fifteen years, elevating compliance costs and litigation reserves.
- Biosimilar Substitution Policies:State-level automatic substitution laws in the United States trigger immediate price erosion upon interchangeability designation, compressing brand defense windows.
Strategic Opportunities
- Oral JAK Inhibitor Expansion:Maintenance therapy settings favor self-administered small molecules over injectable biologics, opening positioning in Crohn's disease and ulcerative colitis where patient preference data shows sixty percent switching intent.
- India's PLI Scheme for Biologics:Production-linked incentives for biosimilar manufacturing create cost-competitive export capacity targeting Southeast Asian and African markets with unmet rheumatology demand.
- Digital Therapeutic Adjuncts:FDA-cleared prescription digital therapeutics for pain modulation are converging with pharmacotherapy protocols, enabling bundled reimbursement codes that capture adherence data.
Industry Challenges
- Cell Therapy Talent Scarcity:Vector production and cryopreservation specialists command premium compensation that outpaces standard biologics manufacturing wages by forty percent, constraining scale-up velocity.
- Legacy IT Integration:Real-world evidence platforms require interoperability with hospital electronic health record systems running Epic or Cerner architectures, forcing custom API development per health system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflammatory Diseases Market |
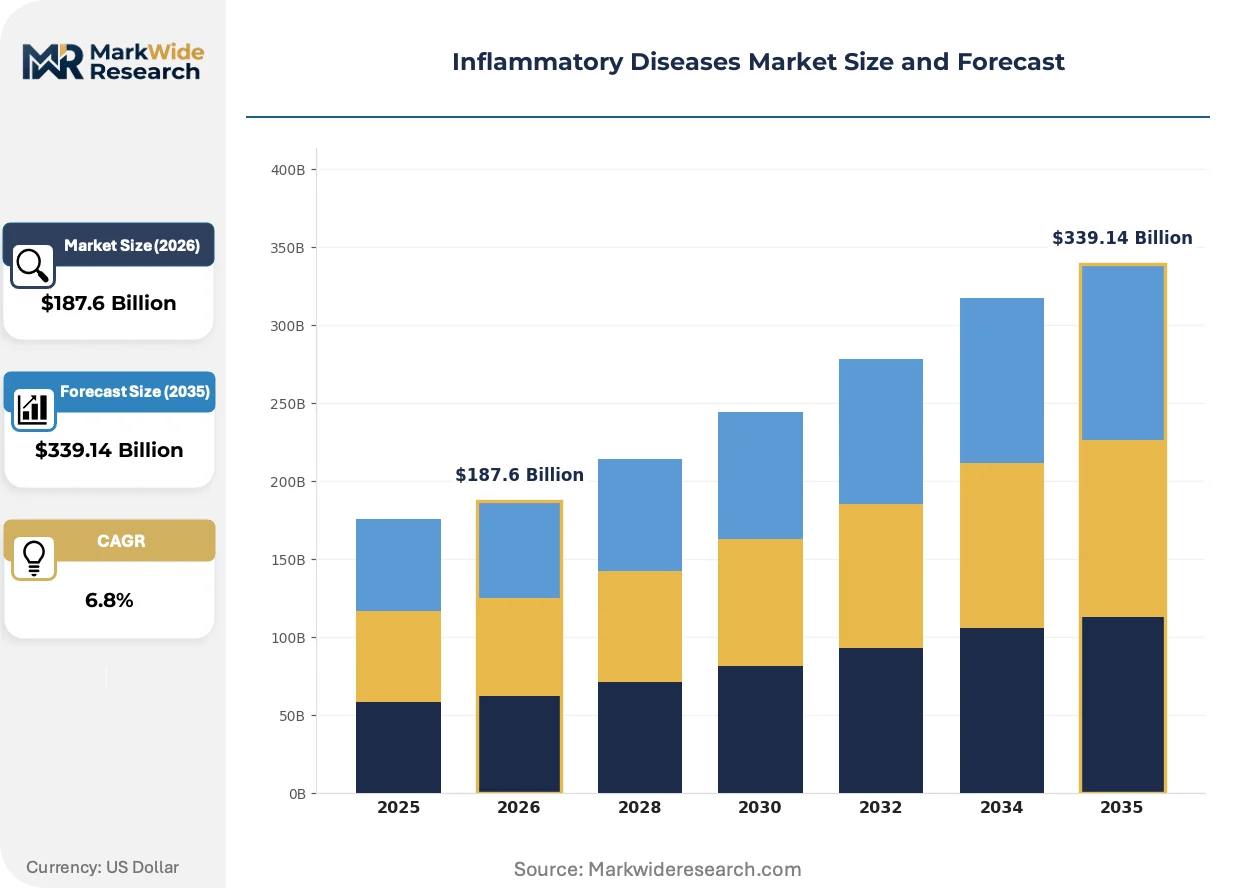
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Corticosteroids, Non-Steroidal Anti-Inflammatory Drugs Indication: Rheumatoid Arthritis, Crohn's Disease, Psoriasis, Ulcerative Colitis Therapy Area: Immunology, Gastroenterology, Dermatology, Pain Management Delivery Mode: Injectable, Oral, Topical, Intravenous |
| Companies Covered | F. Hoffmann-La Roche, Pfizer, AbbVie, AstraZeneca, Amgen, Johnson & Johnson, Novartis, Bristol-Myers Squibb, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflammatory Diseases Market Shifts & Advancements
Mechanism diversification is fragmenting the historical TNF-alpha dominance as developers pursue orthogonal pathways including IL-23, IL-17, and JAK-STAT modulation with comparable efficacy profiles.
Artificial intelligence-driven target identification is converging with high-throughput single-cell sequencing to compress lead optimization timelines. Biotech platforms including Recursion and Insitro are deploying neural networks to predict cytokine-receptor binding kinetics, reducing wet-lab validation cycles from eighteen months to four. This convergence is enabling smaller discovery teams to compete with established immunology giants on pipeline breadth.
REACH Annex XIV authorization requirements for novel chemical entities are forcing reformulation of small-molecule immunomodulators to eliminate persistent bioaccumulative toxic substances. ECHA's 2024 restriction proposal on per- and polyfluoroalkyl substances affects oral formulation coatings, driving migration toward cellulose-based alternatives. European manufacturers are responding by qualifying alternative excipient suppliers ahead of 2026 enforcement deadlines.
Hospital procurement committees are consolidating vendor relationships through single-source agreements that bundle biologic supply with infusion center management services. Specialty pharmacy networks including CVS Specialty and Accredo are displacing traditional wholesale distribution for maintenance therapies, capturing patient data that informs formulary negotiations. This consolidation is most visible in United States Medicare Part B reimbursement settings where site-of-care regulations favor hospital outpatient departments over physician offices.
Inflammatory Diseases Market Segmentation
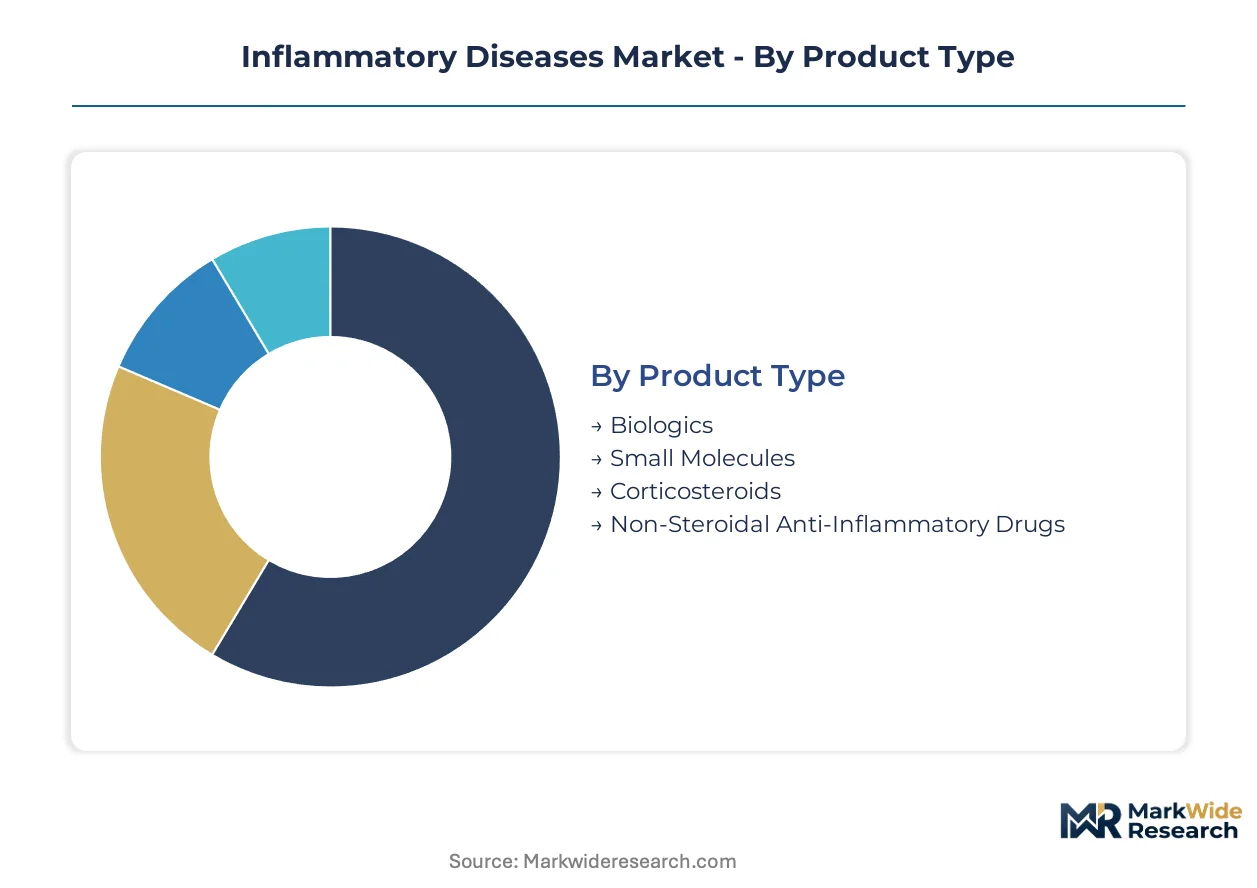
Segmentation in inflammatory diseases reflects divergent reimbursement economics and site-of-care requirements. Product type determines pricing architecture, while delivery mode shapes distribution partnerships and patient adherence programs.
Product Type:
Cost tier drives procurement committee decisions, with biologics commanding premium positioning against commoditized alternatives.
- Biologics:Engineered proteins including monoclonal antibodies and fusion proteins that target specific cytokine pathways. Hospital specialty pharmacies in the United States concentrate demand for TNF-alpha and IL-17 inhibitors where prior authorization requirements favor established efficacy data. These agents face biosimilar pressure as interchangeability designations expand.
- Small Molecules:Synthetic compounds modulating intracellular signaling through JAK-STAT or other kinase pathways. Oral bioavailability attracts patient self-management preference in maintenance settings, particularly where Medicare Part D coverage reduces out-of-pocket exposure versus infused biologics.
- Corticosteroids:Glucocorticoid compounds suppressing broad immune activation through nuclear receptor translocation.
- Non-Steroidal Anti-Inflammatory Drugs:Cyclooxygenase inhibitors providing symptomatic relief without disease modification.
Volume sits with small molecules; growth tilts toward biologics.
Indication:
Application severity determines treatment line positioning and formulary access tiering.
- Rheumatoid Arthritis:Systemic autoimmune joint destruction with established TNF-alpha and JAK inhibitor treatment algorithms. United States rheumatology practices drive demand concentration where Medicare Advantage plans increasingly require step therapy through small molecules before biologic authorization.
- Crohn's Disease:Transmural gastrointestinal inflammation with fistulizing complications. Pediatric and adult gastroenterology clinics favor anti-integrin biologics where mucosal healing endpoints justify premium pricing against corticosteroid induction regimens.
- Psoriasis:Skin and joint manifestations with IL-23 and IL-17 pathway blockade demonstrating superior skin clearance rates.
- Ulcerative Colitis:Mucosal-limited colonic inflammation with emerging oral S1P receptor modulators expanding maintenance options.
Revenue concentrates in rheumatoid arthritis; ulcerative colitis expands most quickly on new oral mechanisms.
Therapy Area:
Customer type dictates prescriber specialty and corresponding detail force deployment.
- Immunology:Rheumatology and allergy-immunology specialists managing systemic autoimmune conditions with biologic-heavy protocols.
- Gastroenterology:Inflammatory bowel disease specialists with endoscopy-driven treatment response monitoring.
- Dermatology:Psoriasis and hidradenitis suppurativa management with phototherapy combination protocols.
- Pain Management:Anesthesiology and physical medicine specialists addressing inflammatory pain without disease modification.
Prescription volume clusters in immunology; gastroenterology gains share fastest on IBD biologic expansion.
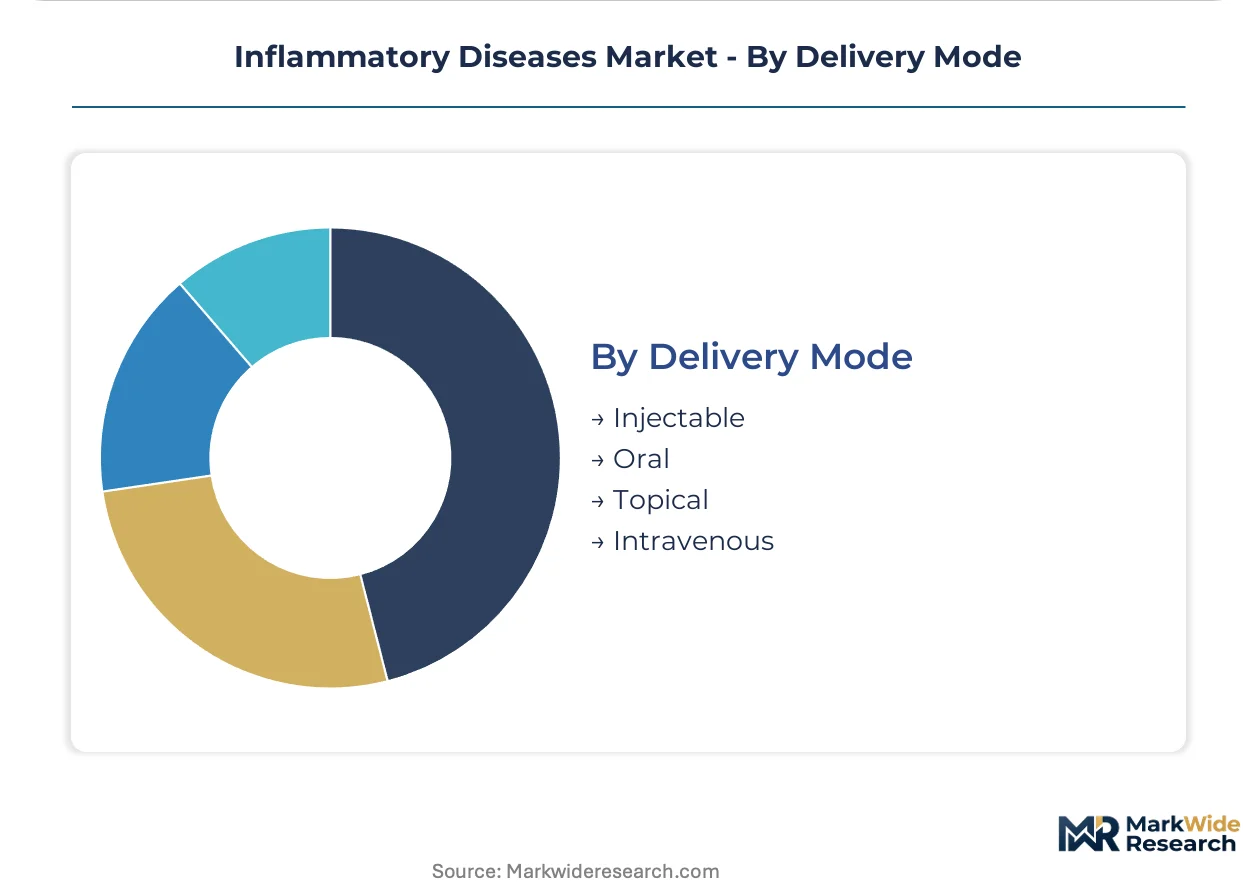
Delivery Mode:
Supply concentration shapes distribution economics and cold chain requirements.
- Injectable:Subcutaneous and intramuscular administration requiring refrigeration and patient training. Specialty pharmacy networks including CVS Specialty and Accredo control United States distribution, capturing adherence data that informs payer formulary negotiations.
- Oral:Self-administered tablets and capsules enabling retail pharmacy fulfillment. Japan's Sakigake designation accelerates approval for first-in-class oral immunomodulators, compressing development timelines against injectable competitors.
- Topical:Localized skin and mucosal application with limited systemic absorption.
- Intravenous:Hospital and infusion center administration with higher reimbursement rates under Medicare Part B.
Injectable formats dominate current revenue; oral delivery climbs the fastest on patient preference and site-of-care cost pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monoclonal antibody drug substance production clusters in South Korea and Singapore anchor supply-side geography for inflammatory disease therapeutics. Contract manufacturers in these jurisdictions feed formulation facilities across North America, Europe, and Asia-Pacific. Patient demand concentrates in markets with mature specialty pharmacy infrastructure and favorable biologic reimbursement.
United States
Medicare Advantage step-therapy requirements drive prior authorization volume for TNF-alpha inhibitors. FDA breakthrough therapy designations compress development timelines for novel JAK inhibitors and IL-23 blockers. The Greater Boston corridor hosts dense clinical trial infrastructure, with Massachusetts General Hospital and Brigham and Women's Hospital enrolling substantial autoimmune populations.
Germany
EMA centralized marketing authorization procedures position Germany as the reference member state for immunomodulatory approvals. REACH Annex XIV restrictions on per- and polyfluoroalkyl substances force reformulation of oral small-molecule coatings. The Rhine-Main biotech cluster around Frankfurt accommodates contract manufacturing organizations serving pan-European distribution.
Japan
PMDA Sakigake designation creates twelve-month regulatory advantages for first-in-Japan therapies. METI production-linked incentives support domestic biologics manufacturing capacity expansion. The Kansai region around Osaka maintains specialized infusion center networks for inflammatory bowel disease management.
India
CDSCO accelerated approval pathways for biosimilars enable rapid market entry for TNF-alpha copycats. The PLI scheme for biologics production subsidizes export-oriented manufacturing in Telangana and Karnataka. Hyderabad's Genome Valley hosts contract development organizations serving Southeast Asian and African rheumatology markets.
Switzerland
Swissmedic parallel review procedures with EMA streamline access for innovative immunomodulators. Basel's pharmaceutical corridor concentrates monoclonal antibody discovery operations with proximity to Rhine logistics. The country's pharmacovigilance requirements align with EMA fifteen-year post-authorization surveillance mandates.
Inflammatory Diseases Market Competitive Landscape
Backward integration into monoclonal antibody production dominates the current landscape as manufacturers secure captive supply chains against API concentration risks. The market structure consolidates around integrated pharmaceutical conglomerates with immunology heritage, mid-cap biotechs with platform technologies, and emerging biosimilar specialists with cost-engineered manufacturing. Three archetypes define positioning: legacy immunology giants with rheumatology sales infrastructure, cell therapy platforms repurposing oncology infrastructure, and contract manufacturers scaling GMP biologics capacity. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as firms build redundancy into drug substance networks.
Among integrated pharmaceutical conglomerates, F. Hoffmann-La Roche, Pfizer, and AbbVie exemplify distinct archetypes within the inflammatory diseases competitive set. F. Hoffmann-La Roche represents the legacy biologics specialist with deep rheumatology franchise experience. Pfizer occupies a position emphasizing small-molecule and biologic combination portfolios across immunology indications. AbbVie anchors the immunology-heavy revenue concentration archetype with sustained presence in psoriasis and rheumatoid arthritis markets. These three firms collectively illustrate the strategic spectrum from biologic-dominant to diversified-modality competitive positioning in autoimmune therapeutics.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Pfizer |
| AbbVie |
| AstraZeneca |
| Amgen |
| Johnson & Johnson |
| Novartis |
| Bristol-Myers Squibb |
| Sanofi |
| Others |
Supply & Pricing Matrix
Vector production and cryopreservation specialists concentrated in the Greater Boston corridor command compensation premiums that outpace standard biologics manufacturing wages, widening spreads between premium cell therapy tiers and commoditized small-molecule alternatives. This labor-cost differential forces manufacturers to tier pricing architectures that recover specialized workforce investments through bundled service models while maintaining access-tier affordability for maintenance therapies.
Pricing Analysis
Infusion center management services bundled with biologic supply create the primary pricing differentiation, with unbundled product-only contracts commanding lower reimbursement rates under Medicare Part B. Three-tier pricing structure across premium, standard, and economy levels separates originator biologics with comprehensive patient support programs from biosimilars with limited services and generic small molecules with no wraparound care. Price compression runs through the biosimilar tier as state-level automatic substitution laws trigger immediate erosion upon interchangeability designation. Hospital procurement committees exhibit highest price sensitivity for maintenance therapies where oral alternatives reduce site-of-care costs, while academic medical centers remain least sensitive for refractory populations requiring novel mechanisms.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement committees now extend to monoclonal antibody drug substance, forcing qualification of secondary contract manufacturers beyond primary South Korean and Singaporean suppliers. Active pharmaceutical ingredient networks draw from South Korea, Singapore, and emerging Indian capacity under PLI scheme subsidies, with formulation fill-finish distributed across North American and European sites. Single-source vulnerability persists in viral vector production for cell therapies, where cleanroom capacity constraints create bottleneck exposure. Distribution runs through consolidating specialty pharmacy networks including CVS Specialty and Accredo, displacing traditional wholesale channels for maintenance biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflammatory diseases market sits in a mechanism-transition phase as JAK-STAT and IL-23 pathway inhibitors displace legacy TNF-alpha dominance across rheumatoid arthritis and psoriasis treatment algorithms.
For Market Incumbents: Hedge biosimilar erosion risk by accelerating backward integration into monoclonal antibody production and securing captive supply chains against API concentration in South Korea and Singapore. Prioritize formulary defense through bundled infusion center management contracts that create switching friction beyond clinical differentiation alone. Expand oral small-molecule pipelines to capture maintenance therapy preference where patient self-management priorities shift. For New Entrants and Emerging Players: Launch via India's PLI-subsidized biosimilar manufacturing base to target Southeast Asian and African rheumatology markets with unmet demand and limited originator presence. Penetrate ulcerative colitis maintenance settings fastest through oral S1P receptor modulators where sixty percent patient switching intent favors self-administration over injectable biologics. Pursue digital therapeutic adjunct partnerships to capture bundled reimbursement codes with adherence data monetization. For Investors and Strategic Acquirers: The window for entry favors cell therapy platforms repurposing oncology infrastructure toward autoimmune indications, leveraging existing cleanroom capacity and apheresis networks. Long-term viability hinges on manufacturing scale-up velocity as vector production talent scarcity constrains expansion. Watch FDA breakthrough therapy designation velocity as the inflection signal indicating compressed competitive entry timelines for novel mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive monoclonal antibody production insulates against South Korean and Singaporean supply concentration. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines from ten years to six for novel mechanisms. |
| Pipeline Diversification | Oral JAK inhibitor expansion captures patient preference in Crohn's disease and ulcerative colitis maintenance. |
| Licensing Agreement | Digital therapeutic adjunct partnerships enable bundled reimbursement codes with adherence data capture. |
| Clinical Trial Advancement | Greater Boston corridor infrastructure accelerates autoimmune population enrollment for phase III programs. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and SEC 10-K disclosures from integrated pharmaceutical conglomerates. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated pipeline timelines and access barriers. Bottom-up patient population modeling triangulated against top-down revenue estimates across the analysis window.
Historical trendline analysis of treatment algorithm evolution informed projection assumptions for mechanism substitution patterns. The analytical framework segmented by product type, indication severity, delivery mode, and regional regulatory cluster throughout the forecast period. CAGRs derived from patent expiry schedules, biosimilar entry assumptions, and oral formulation adoption curves. Forecast inputs incorporated Medicare Advantage step-therapy penetration and specialty pharmacy network consolidation velocity.
The model assumes a particular technology adoption path; alternative pathways for cell therapy manufacturing scale-up would alter the outlook if vector production talent scarcity resolves faster than projected. Forecasts reflect assumptions regarding interchangeability designation timelines and state-level substitution law expansion. Deviation in FDA breakthrough therapy approval velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market