
 Palmoplantar Pustulosis Market | 2026-2036
Palmoplantar Pustulosis Market Size, Share, and Industry Trends Forecast 2026-2036
Palmoplantar Pustulosis Market Analytics
Topical corticosteroid dependence is expanding as physicians seek to minimize systemic exposure in chronic Palmoplantar Pustulosis management. AbbVie Inc. leverages its immunology infrastructure to sustain R&D intensity across novel cytokine pathways. Bristol-Myers Squibb Company anchors its position through biologics manufacturing scale and established dermatology sales networks. Novartis International AG differentiates via IL-17 pathway specialization and broad European market access.
Palmoplantar Pustulosis is a chronic inflammatory dermatosis characterized by sterile neutrophilic pustules localized to palms and soles, with histopathology showing spongiform pustules of Kogoj and acanthosis. The condition primarily serves commercial purpose through sustained pharmaceutical intervention for recurrent, treatment-resistant presentations that impair occupational function and quality of life. Biologics command the fastest-expanding segment as IL-17 and IL-23 inhibitors displace conventional systemic immunosuppressants in refractory cases. Topical therapies retain volume leadership in first-line settings but face margin compression from generic commoditization. Injectable administration modes concentrate value capture where patient compliance and bioavailability requirements favor subcutaneous delivery over oral alternatives.
FDA oversight shapes biologics approval pathways and post-market risk evaluation for Palmoplantar Pustulosis therapeutics, while EMA's MDR framework governs device-drug combination products in European markets. Japan's PMDA maintains distinct efficacy benchmarks that filter which biologics achieve reimbursement listing in its national health insurance system. Stakeholders must monitor evolving payer evidence requirements across these jurisdictions as real-world data substitutes for traditional trial endpoints in access negotiations.
Market Dynamics
Biologics targeting IL-17 and IL-23 cytokine pathways are displacing methotrexate and cyclosporine in refractory Palmoplantar Pustulosis cases, compressing the addressable market for conventional systemic immunosuppressants while expanding specialty pharmaceutical value capture.
Growth Catalysts
- EMA MDR framework:Post-market surveillance requirements for biologics are accelerating real-world evidence collection, strengthening payer negotiation positions for advanced therapies in European markets.
- Specialist referral networks:Dermatology clinics in the United States, Germany, and Japan are consolidating treatment protocols around subcutaneous biologics administration, standardizing patient pathways for refractory presentations.
- Topical corticosteroid minimization:Physician preference for reducing systemic exposure in chronic management is sustaining demand for localized corticosteroid formulations alongside biologic escalation.
Market Restraints
- Biologics manufacturing concentration:Production of IL-17 and IL-23 inhibitors concentrates among a limited set of contract manufacturing organizations, creating supply vulnerability for dose-intensive chronic therapies.
- FDA post-market surveillance expansion:Enhanced pharmacovigilance requirements for immunomodulatory agents extend trial timelines and inflate regulatory compliance costs for new market entrants.
- Generic topical commoditization:Patent expirations on first-line corticosteroid formulations compress margins for established topical portfolios, constraining R&D reinvestment capacity.
Strategic Opportunities
- PMDA reimbursement benchmarks:Japan's distinct efficacy thresholds for national health insurance listing create a filter mechanism that rewards differentiated clinical profiles with premium positioning.
- Device-drug combination products:Integration of precision delivery systems with biologic formulations opens white space in patient compliance and dosing accuracy for chronic dermatologic conditions.
- Real-world data substitution:Evolving payer evidence requirements across FDA, EMA, and PMDA jurisdictions enable access negotiations grounded in observational studies rather than traditional randomized endpoints.
Industry Challenges
- Specialized dermatology sales force scaling:Biologics promotion requires field teams with immunology expertise and established relationships with academic medical centers, constraining geographic expansion velocity.
- Legacy electronic health record integration:Biologic prescribing workflows must interface with hospital systems optimized for conventional systemic therapies, creating administrative friction in specialist clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palmoplantar Pustulosis Market |
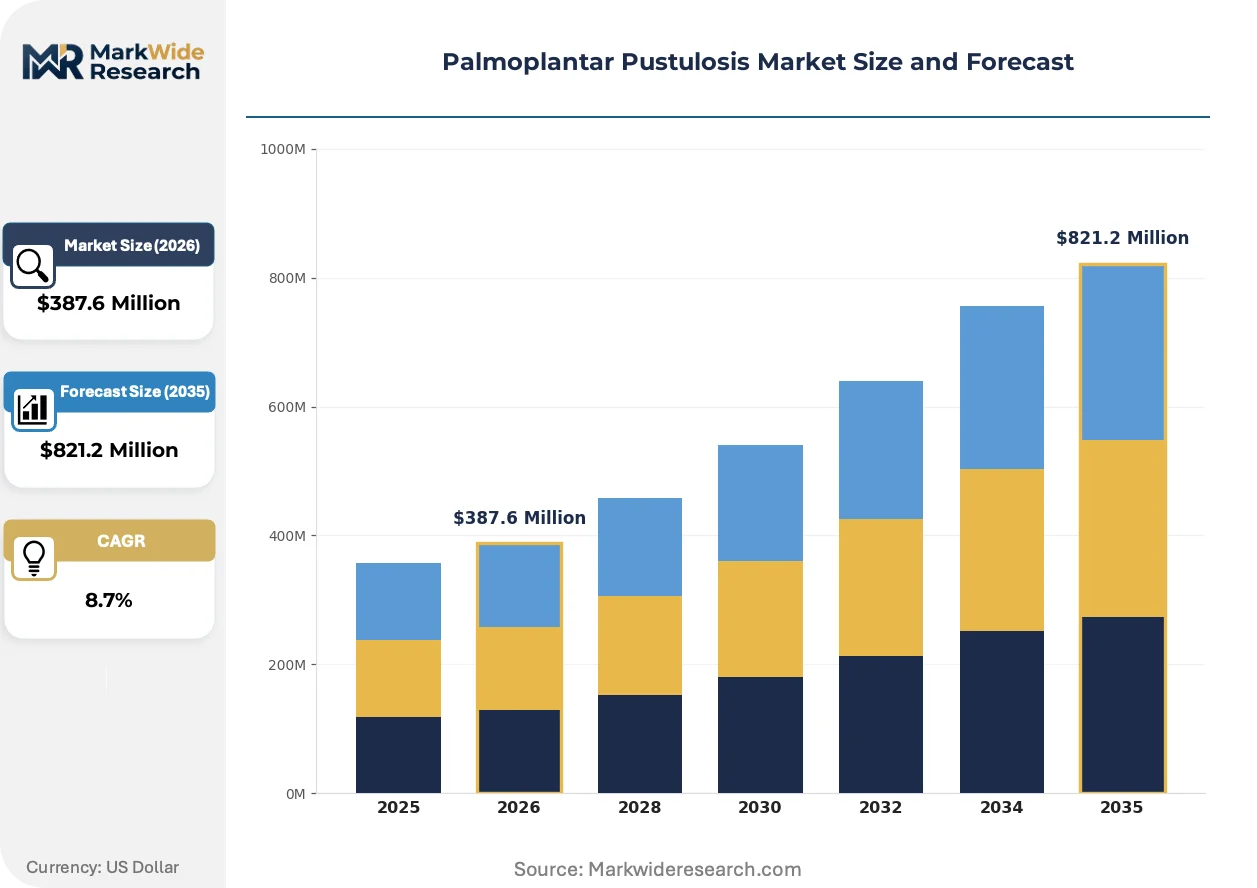
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Therapies, Systemic Treatments, Biologics, Phototherapy Therapy Area: Dermatology, Immunology, Internal Medicine, Chronic Conditions End User: Hospitals, Clinics, Homecare Settings, Outpatient Facilities Administration Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | Bristol-Myers Squibb Company, Amgen Inc., Pfizer Inc., Janssen Pharmaceuticals Inc., GlaxoSmithKline PLC, AbbVie Inc., Novartis International AG, Kyowa Kirin Co. Ltd., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palmoplantar Pustulosis Market Evolving Landscape
Novel cytokine pathway modulation is compressing treatment paradigms for chronic inflammatory dermatoses, with technology convergence between molecular engineering and delivery systems reshaping competitive positioning across first-line and refractory settings.
Biosensor-enabled adherence monitoring is integrating with subcutaneous biologic delivery platforms to capture real-time injection data. Specialty pharmacies serving academic dermatology centers are deploying these systems to reduce discontinuation rates in chronic Palmoplantar Pustulosis management. The structural consequence is a shift from episodic prescription fulfillment toward continuous patient engagement models that capture value through outcome persistence.
EMA's tightened MDR requirements for device-drug combinations are extending certification timelines for novel delivery systems in European markets. Manufacturers must demonstrate biocompatibility and dose accuracy across variable patient populations before CE marking approval. Dermatology clinics in Germany and France are responding by consolidating procurement around established platform technologies with cleared regulatory histories.
Patient-driven switching between topical and systemic modalities is compressing brand loyalty cycles in chronic disease management. Digital health platforms connecting Palmoplantar Pustulosis patients with specialist prescribers are displacing traditional primary care referral pathways in the United States. This behavioral shift concentrates demand capture among telemedicine-enabled dermatology networks with integrated specialty pharmacy fulfillment.
Palmoplantar Pustulosis Market Segmentation
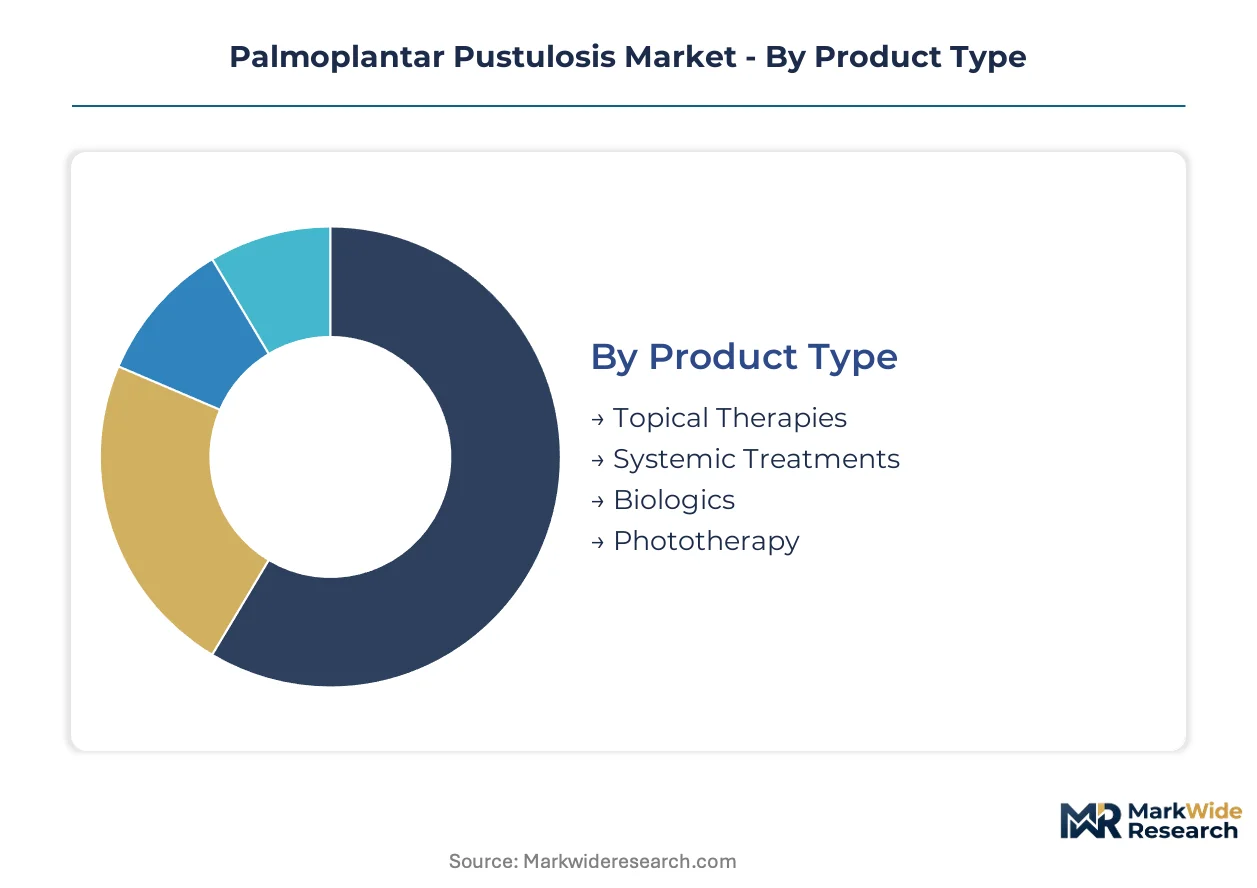
Product differentiation in Palmoplantar Pustulosis therapeutics hinges on treatment resistance severity and physician risk tolerance for systemic exposure. Patient pathway design varies sharply across administration modes and care settings, with reimbursement access governing commercial viability more than clinical efficacy alone.
Product Type:
Cost tier determines initial prescribing authority, with first-line options facing generic erosion while specialty biologics capture premium positioning through restricted distribution.
- Topical Therapies:Corticosteroid and calcipotriene formulations dominate first-line protocols through localized action and minimal systemic absorption. Demand concentrates in primary care networks across Germany and Japan where physicians prioritize risk minimization for occupational hand involvement.
- Biologics:IL-17 and IL-23 inhibitors command the steepest expansion trajectory through subcutaneous delivery and sustained remission in refractory presentations. Specialist dermatology clinics in the United States drive adoption where prior authorization pathways for advanced therapies are most streamlined.
- Systemic Treatments:Methotrexate and cyclosporine retain volume in resource-constrained settings despite monitoring burdens.
- Phototherapy:Narrowband UVB and PUVA serve select academic centers with dedicated equipment infrastructure.
Topical Therapies lead on scale; Biologics lead on momentum.
Therapy Area:
Volume concentration tracks referral network density, with academic medical centers anchoring complex case management.
- Dermatology:Board-certified specialists control biologic prescribing through established relationships with AbbVie, Bristol-Myers Squibb, and Novartis field teams. Patient capture depends on integrated specialty pharmacy partnerships that streamline prior authorization and home delivery logistics.
- Immunology:Cross-trained rheumatologists and dermatologists manage refractory cases with overlapping psoriatic arthritis, expanding addressable patient pools through dual-diagnosis protocols in tertiary referral centers.
- Internal Medicine:Generalists handle stable maintenance therapy with conventional systemics.
- Chronic Conditions:Long-term disease management programs incorporate occupational therapy for palm and sole functional preservation.
Dermatology anchors revenue concentration; Immunology is climbing the fastest through diagnostic overlap expansion.
End User:
Margin structure varies by procurement sophistication, with integrated delivery networks extracting price concessions unavailable to independent practices.
- Clinics:Dermatology-focused ambulatory centers concentrate biologic administration through in-office injection programs and patient assistance coordination. United States metropolitan clusters in Boston, New York, and Los Angeles generate disproportionate volume through density of academic-affiliated specialists.
- Hospitals:Inpatient consultation services manage acute flares with pustular eruption complications, though chronic revenue capture remains limited by length-of-stay constraints.
- Homecare Settings:Self-administered subcutaneous biologics shift infusion center dependence toward specialty pharmacy support models.
- Outpatient Facilities:Community-based access points extend reach for phototherapy and topical dispensing.
Clinics dominate value capture; Homecare Settings are gaining share fastest through patient convenience prioritization.
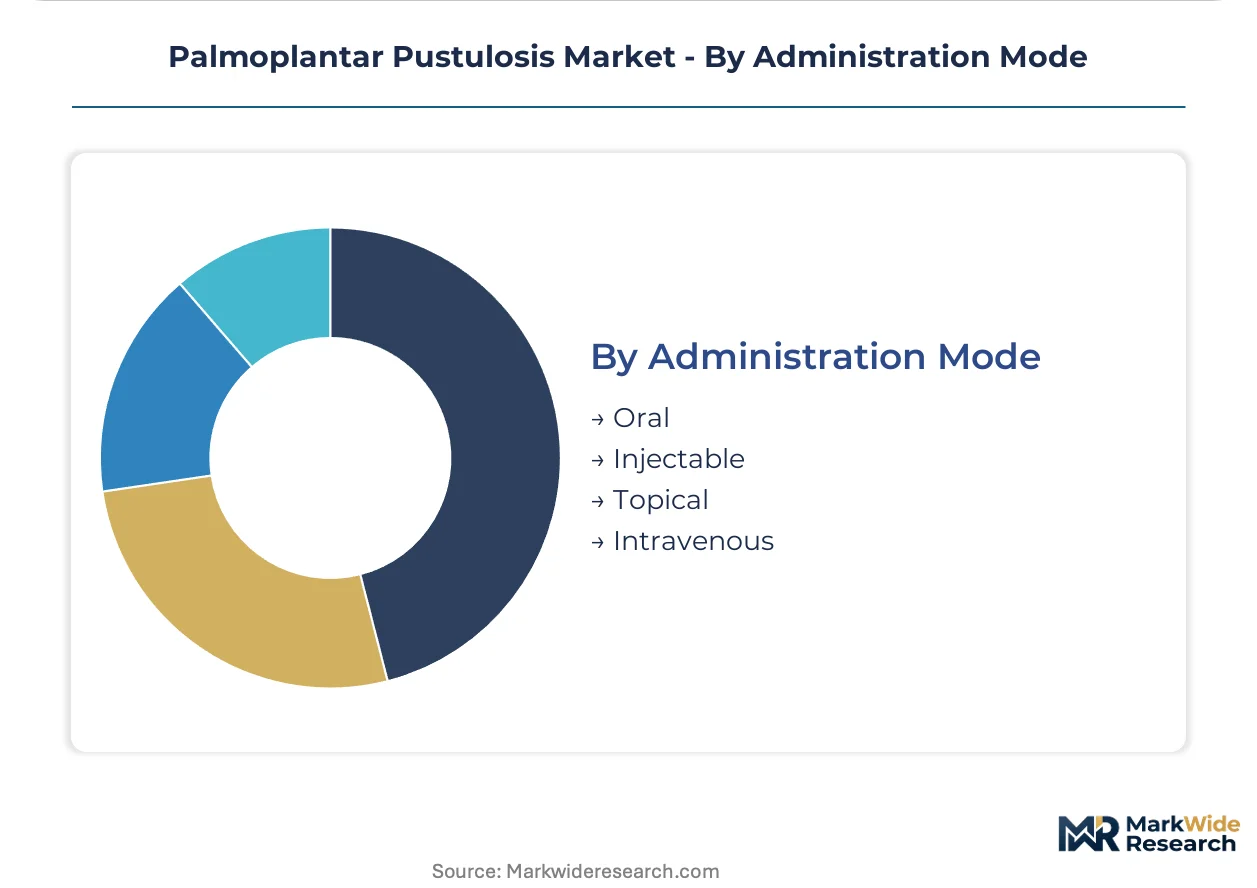
Administration Mode:
Patient compliance requirements and bioavailability demands reshape competitive positioning across chronic disease management.
- Injectable:Subcutaneous biologics with extended dosing intervals reduce treatment burden and improve persistence metrics. Prefilled syringe and auto-injector platforms from established manufacturers anchor procurement decisions in German and Japanese reimbursement systems.
- Topical:Cream, ointment, and foam vehicles require multiple daily applications, creating adherence gaps that manufacturers address through combination packaging with corticosteroid-calcipotriene fixed-dose products.
- Oral:Systemic immunosuppressants retain role in transitioning patients between topical failure and biologic escalation.
- Intravenous:Infusion center dependence limits this mode to acute intervention and specific biologic loading protocols.
Injectable administration commands premium positioning; Topical delivery sustains volume leadership through access breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic dermatology corridor concentrates biologic prescribing volume through Mass General Brigham and Harvard-affiliated specialty networks. FDA prior authorization pathways for IL-17 and IL-23 inhibitors streamline patient access in this cluster. The United States anchors value capture through integrated specialty pharmacy fulfillment and telemedicine-enabled referral networks.
United States
Specialist referral density in metropolitan corridors drives biologic adoption curves. FDA post-market surveillance requirements for immunomodulatory agents extend pharmacovigilance obligations for manufacturers. New York and Los Angeles academic medical centers anchor patient capture through AbbVie, Bristol-Myers Squibb, and Novartis field team relationships.
Germany
Dermatology clinic consolidation around subcutaneous administration protocols standardizes treatment pathways. EMA MDR framework governs device-drug combination certification timelines for novel delivery systems. Munich and Berlin hospital networks concentrate procurement decisions for established auto-injector platforms with cleared regulatory histories.
Japan
Occupational hand involvement prevalence sustains demand for localized corticosteroid formulations in primary care. PMDA maintains distinct efficacy benchmarks that filter biologics achieving national health insurance reimbursement listing. Tokyo and Osaka specialist centers drive IL-17 pathway inhibitor adoption through streamlined prior authorization.
United Kingdom
NHS England commissioning frameworks concentrate biologic prescribing authority in tertiary dermatology centers. NICE technology appraisals govern access negotiations for advanced therapies against traditional systemic immunosuppressants. London and Manchester academic units anchor real-world evidence collection for payer submission requirements.
France
ANSM pharmacovigilance reporting obligations shape post-market surveillance infrastructure for biologic manufacturers. Hospital pharmacy procurement consolidation extracts price concessions through tender mechanisms. Paris and Lyon dermatology departments concentrate refractory case management through academic referral networks.
Palmoplantar Pustulosis Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend cytokine pathway specialization across dermatologic indications. The vendor base concentrates among integrated pharmaceutical conglomerates with established immunology infrastructure and biologics manufacturing scale. Three archetypes define positioning: cytokine pathway specialists with IL-17 and IL-23 inhibitor depth, diversified immunology platforms spanning multiple autoimmune indications, and regional players leveraging local market access relationships. M&A activity and strategic partnerships represent the primary competitive vectors as manufacturers seek to backfill pipeline gaps and secure specialty pharmacy distribution channels.
Within the cytokine pathway specialist tier, Novartis International AG and AbbVie Inc. exemplify positioning through concentrated IL-17 and IL-23 inhibitor development. Bristol-Myers Squibb Company occupies a scale-driven position leveraging biologics manufacturing infrastructure and dermatology sales network density. These three anchors represent the competitive core around which second-tier players and regional specialists orbit, each archetype commanding distinct negotiation leverage with integrated delivery networks and academic medical centers.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Pfizer Inc. |
| Janssen Pharmaceuticals Inc. |
| GlaxoSmithKline PLC |
| AbbVie Inc. |
| Novartis International AG |
| Kyowa Kirin Co. Ltd. |
| Sanofi S.A. |
| Others |
Value Network & Pricing Analysis
Specialized immunology manufacturing talent concentration in the Boston-Cambridge corridor and Basel, Switzerland creates labor-cost differentials that widen pricing spreads between originator biologics and biosimilar entrants. Contract manufacturing organizations in these clusters command premium rates for cell-line development and sterile fill-finish capabilities, compressing margins for dose-intensive chronic therapies while sustaining tiered pricing structures.
Pricing Analysis
Input-cost pass-through from recombinant protein production and cold-chain logistics anchors pricing stratification across premium, standard, and economy tiers. FDA certification tier and volume scale serve as primary price differentiation drivers. Pricing pressure stems from generic topical commoditization in first-line settings. Primary care networks exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to restricted distribution and patient assistance programs.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled biologic returns and patient support program coordination adds complexity to distribution economics. Manufacturing concentrates in the United States, Switzerland, and Ireland for active pharmaceutical ingredient production, with fill-finish operations in Germany and Japan. Supply chains draw from recombinant cell banks, single-use bioreactor systems, and specialized elastomeric closure components. Single-source vulnerability for IL-17 and IL-23 inhibitor cell lines creates concentration risk. Distribution runs through specialty pharmacy networks with direct-to-patient cold-chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palmoplantar Pustulosis therapeutics function as a stable compounder anchored by chronic disease management requirements and biologic substitution cycles that sustain recurring revenue streams.
For Market Incumbents: Anchor market position through backward integration into bioreactor manufacturing capacity and captive fill-finish operations in Basel or Boston. Biosimilar pipeline threats from Korean and Indian manufacturers demand accelerated real-world evidence generation for payer defense. Prior authorization automation with specialty pharmacies preserves access moats against emerging entrants. For New Entrants and Emerging Players: EMA MDR framework in Europe opens a window for device-drug combination products with novel delivery mechanisms. White-space targets include homecare biosensor-enabled adherence platforms and Japanese market entry through PMDA efficacy benchmark differentiation. Go-to-market execution should prioritize dermatology telemedicine networks with integrated specialty pharmacy partnerships over traditional hospital formulary access. For Investors and Strategic Acquirers: Large-cap immunology conglomerates are the most active acquirer in this space, seeking pipeline backfill for expiring biologic patents. Long-term viability rests on cytokine pathway diversification beyond IL-17 and IL-23 toward novel targets. Acquisition target archetype: mid-stage biologics with cleared regulatory histories in European markets. Signal to watch: PMDA reimbursement listing decisions for differentiated clinical profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Real-world evidence substitution strengthens EMA and FDA payer negotiation positions for IL-23 inhibitors. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Switzerland reduces single-source vulnerability for dose-intensive chronic therapies. |
| Regulatory Approval Pathway | PMDA distinct efficacy benchmarks filter biologics achieving Japan national health insurance premium positioning. |
| Licensing Agreement | Specialty pharmacy distribution partnerships streamline prior authorization workflows in United States academic centers. |
| Pipeline Diversification | Novel cytokine pathway modulation beyond IL-17 extends competitive positioning as existing patents approach expiration. |
Research Methodology
Multiple input streams — dermatology prescribing data, biologics manufacturing capacity reports, and payer access documentation — were reconciled through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and specialty pharmacy operations managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and national formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates across administration modes and therapy settings.
Cross-referencing historical biologic adoption curves against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment line, administration route, patient population severity, and regional regulatory cluster. CAGRs were derived from patient prevalence projections, biologic penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporated PMDA reimbursement listing timelines and EMA MDR certification velocity for device-drug combinations.
Revisions become necessary when regulatory approval delays, manufacturing capacity constraints, or payer access restrictions materialize beyond base-case assumptions. Forecasts reflect documented assumptions regarding biologic substitution rates and topical generic erosion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market