
 Asbestosis Treatment Market | 2026-2036
Asbestosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asbestosis Treatment Market Intelligence
Long-term patient monitoring programs for chronic respiratory conditions are realigning the value proposition beyond the initial drug prescription. Boehringer Ingelheim leverages its established respiratory disease portfolio to offer integrated care pathways. Roche competes by developing targeted therapies for asbestos-related lung cancer, a severe complication. These strategies shift the commercial focus from single-treatment sales to comprehensive disease management.
Asbestosis treatment encompasses a range of therapeutic interventions aimed at managing symptoms and slowing the progression of lung scarring, or pulmonary fibrosis, caused by inhaled asbestos fibers. The primary clinical goal is palliative, focusing on improving respiratory function and quality of life, as there is no existing cure. Oxygen therapy and corticosteroids form the cornerstone of symptomatic management across patient populations. Specialized respiratory centers are becoming the primary end-user for advanced interventions like immunomodulators.
Regulatory pathways for new antifibrotic drugs are governed by agencies like the US FDA, the EMA in Europe, and Japan's PMDA. Concurrently, national occupational safety standards, such as those enforced by OSHA in the United States, indirectly influence the patient pool by mandating workplace safety and monitoring. Future market evolution will depend on the clinical success of pipeline immunomodulators and the broader adoption of early diagnostic screening protocols.
Market Dynamics
The asbestosis treatment market's central dynamic is the clinical and commercial tension between established, low-cost palliative care and the high-cost development of disease-modifying antifibrotic therapies. This force shapes investment in research, reimbursement negotiations, and the evolution of care delivery models toward specialized centers.
Growth Catalysts
- Advanced Immunomodulators:The development of therapies targeting specific fibrotic pathways, such as those involved in pulmonary fibrosis, provides a mechanism to potentially slow disease progression beyond simple symptom management.
- Legacy Exposure Cohorts:Concentrated patient populations in countries with a history of heavy asbestos use, including the United States, Australia, and the United Kingdom, create a defined and predictable demand for long-term care.
- Occupational Safety Regulations:Mandates from bodies like the Occupational Safety and Health Administration (OSHA) for workplace monitoring and long-term health surveillance of exposed workers ensure a steady stream of diagnosed patients entering the treatment ecosystem.
Market Restraints
- Lack of Curative Therapies:The absence of a cure for asbestosis fundamentally limits the market to palliative and disease management interventions, capping the ultimate therapeutic value proposition for patients and payers.
- High R&D Investment:The significant capital and long timelines required for developing, testing, and securing regulatory approval for novel antifibrotic drugs represent a substantial barrier to entry for new market participants.
- Stringent Clinical Pathways:Regulatory agencies such as the US FDA and the EMA impose rigorous and lengthy clinical trial requirements for drugs targeting interstitial lung diseases, delaying market access for new treatments.
Strategic Opportunities
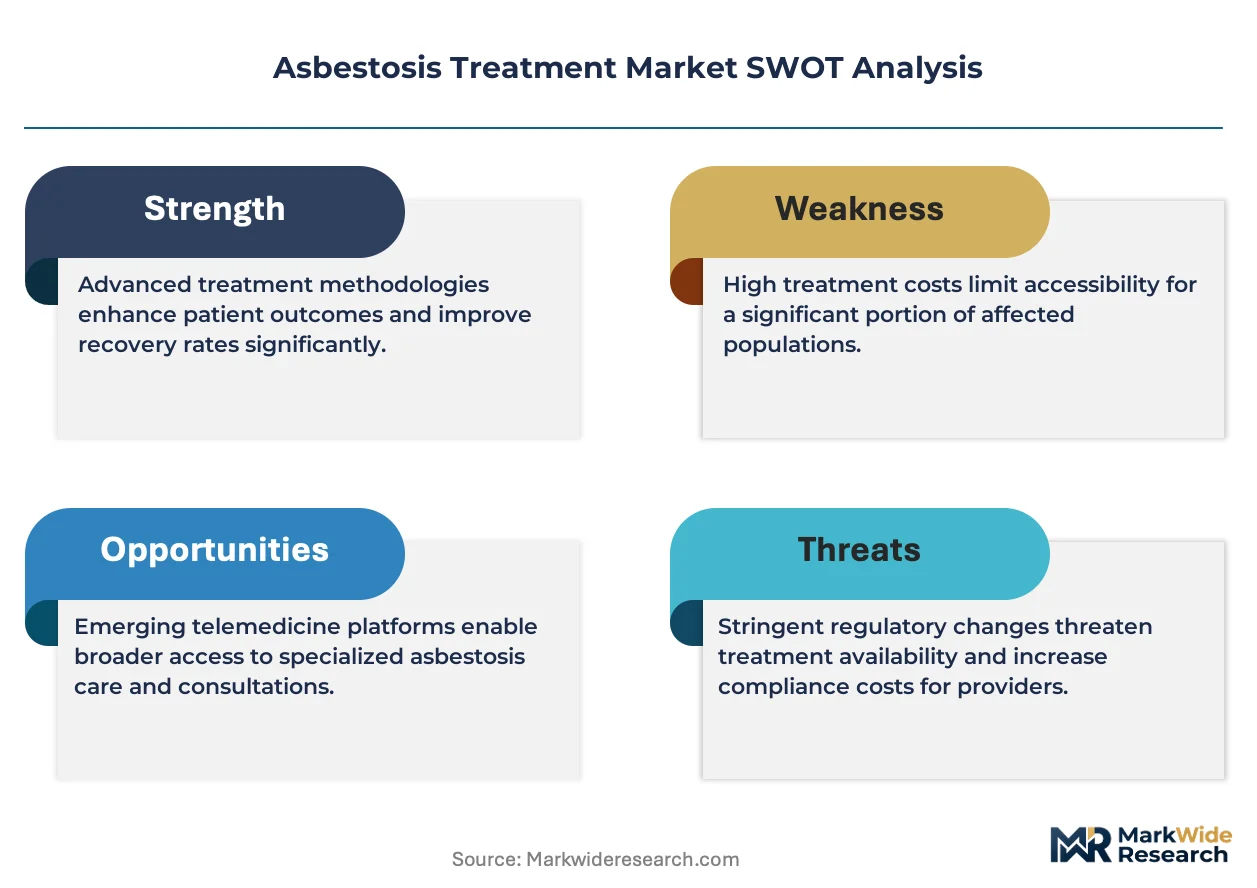
- Diagnostic and Therapeutic Convergence:Integrating early diagnostic screening protocols, such as low-dose computed tomography, with targeted immunomodulatory therapies creates an opportunity for earlier intervention and improved long-term outcomes.
- Specialized Care Channels:The growth of dedicated respiratory centers provides a concentrated and efficient channel for the dissemination and administration of advanced, high-cost treatments that require specialized expertise.
- Digital Health Integration:The deployment of remote patient monitoring platforms for tracking respiratory function offers a new service layer to enhance disease management, improve data collection for clinical studies, and justify premium pricing.
Industry Challenges
- Reimbursement Complexity:Securing favorable reimbursement status for high-cost novel immunomodulators from diverse national and private payers presents a significant hurdle, particularly when competing against established, cheaper palliative options.
- Specialist Scarcity:A limited pool of pulmonologists and researchers with specific expertise in interstitial lung diseases, particularly in non-specialized healthcare settings, can constrain the adoption of complex new treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asbestosis Treatment Market |
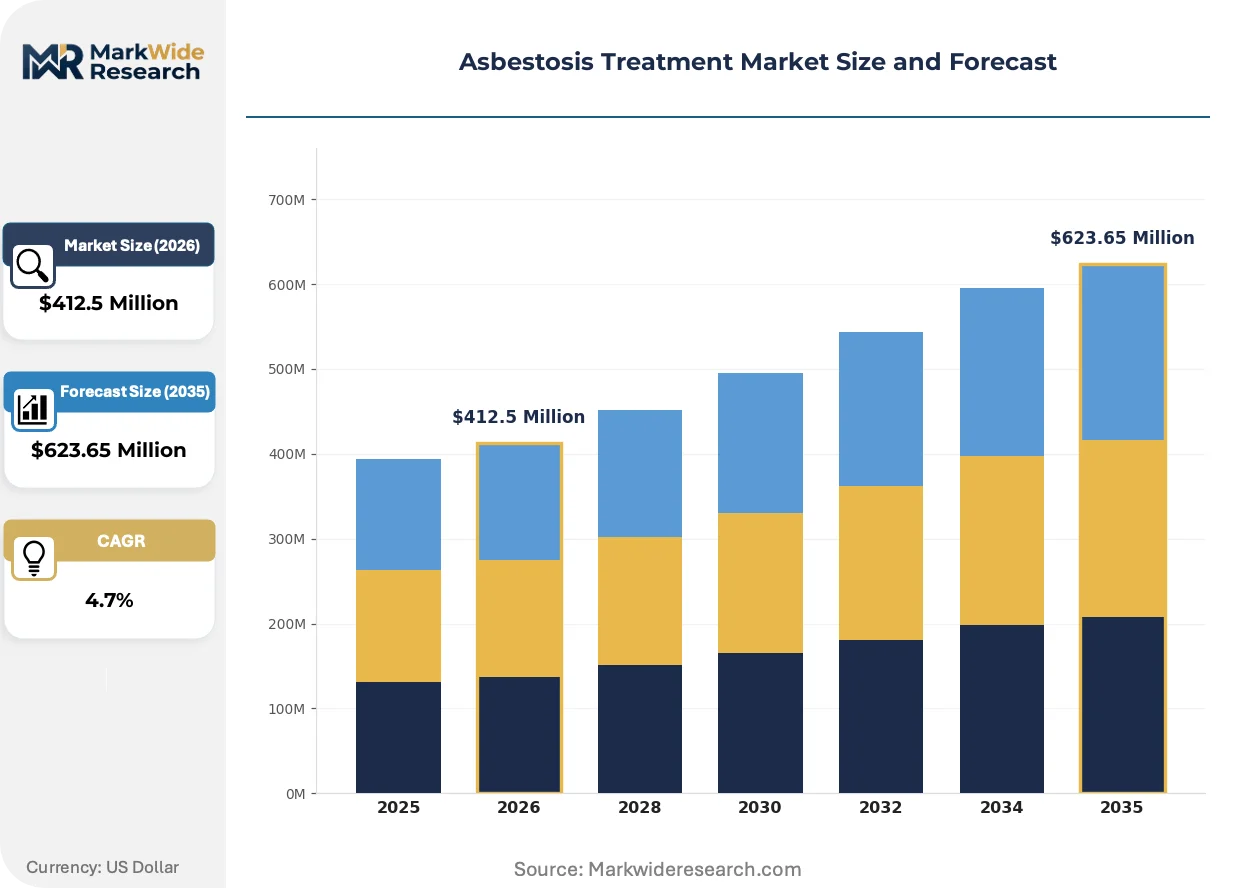
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $623.65 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Oxygen Therapy, Pulmonary Rehabilitation, Lung Transplantation, Immunomodulators Application: Severe Pulmonary Fibrosis, Chronic Respiratory Failure, Pleural Thickening, Asbestos-Related Lung Cancer, Bronchiectasis End User: Pulmonology Clinics, Specialized Respiratory Centers, University Hospitals, Research Institutes Delivery Mode: Inhalation, Oral Medication, Intravenous Injection, Surgical Procedure, Physical Therapy |
| Companies Covered | Pfizer, Bristol-Myers Squibb, AstraZeneca, Novartis, Merck, Sanofi, Roche, Gilead Sciences, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asbestosis Treatment Market Strategic Shifts & Innovations
The market is transitioning from a focus on broad symptomatic relief to a more precise approach targeting the underlying biological mechanisms of pulmonary fibrosis. This evolution is driven by breakthroughs in immunology and a deeper understanding of the cellular pathways activated by asbestos fibers.
Targeted Immunomodulator Platforms
New therapeutic platforms are designed to inhibit specific cytokines and growth factors involved in the fibrotic cascade. Specialized respiratory centers and academic research hospitals are the primary adopters of these advanced treatments. This technology is modularizing the therapeutic strategy, allowing clinicians to combine agents that target different pathological processes, moving beyond the monolithic use of corticosteroids.
Regulatory Acceleration Pathways
The European Medicines Agency's PRIME (PRIority MEdicines) scheme offers a framework for accelerated assessment of drugs for unmet medical needs. This regulatory tailwind provides earlier and enhanced scientific and regulatory support, potentially shortening development timelines. Developers of pipeline antifibrotic drugs for rare conditions like asbestosis are most affected, gaining a faster potential route to market access within the EU.
Integrated Disease Management Models
A shift is occurring toward bundling long-term patient monitoring programs with the provision of therapeutics. This model displaces the traditional, transactional sale of a single drug with a comprehensive service contract focused on managing disease progression and patient quality of life. The trend is most prominent in developed healthcare systems in the United States and Australia, where large providers manage chronic patient cohorts.
Asbestosis Treatment Market Segmentation
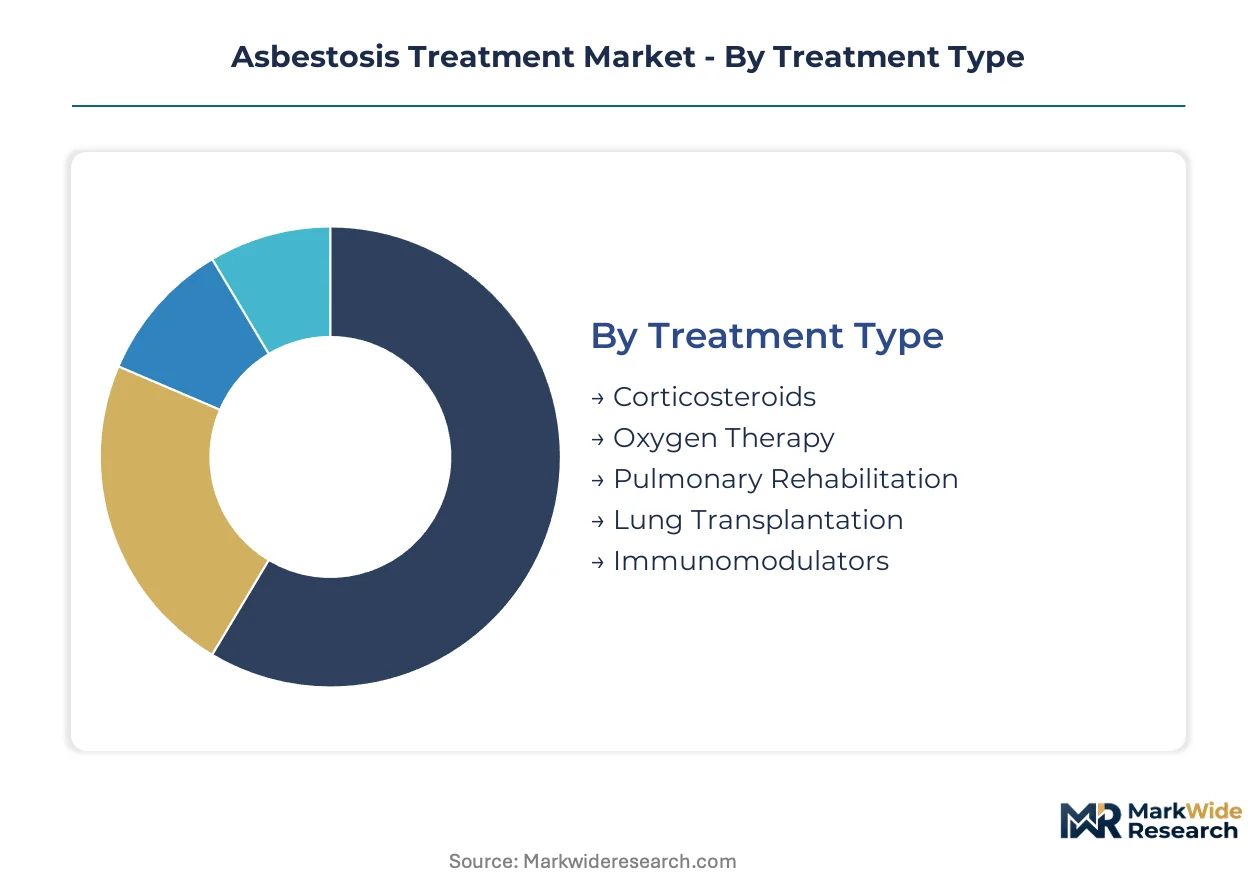
The asbestosis treatment market segments illuminate distinct patient needs, therapeutic approaches, and delivery mechanisms. This detailed breakdown helps stakeholders understand where clinical development is focused and where patient care resources are most concentrated. Analyzing these categories provides a clearer picture of both established practices and emerging innovations across the disease management spectrum.
Treatment Type:
Buyer decisions for asbestosis treatment depend heavily on disease severity, patient comorbidities, and the potential for disease modification versus palliative care.
- Immunomodulators:These advanced therapies target specific fibrotic pathways, aiming to slow the progression of pulmonary fibrosis. Demand concentrates in specialized respiratory centers across the United States and Australia, driven by their potential to offer disease-modifying benefits.
- Oxygen Therapy:This intervention provides supplemental oxygen to improve respiratory function and alleviate hypoxemia, a common symptom. Its demand is widespread, particularly within home care settings and long-term patient monitoring programs for chronic respiratory failure.
- Corticosteroids:These anti-inflammatory agents help manage symptoms and reduce lung inflammation.
- Pulmonary Rehabilitation:Structured exercise and education programs improve lung function and quality of life for patients.
- Lung Transplantation:A surgical option considered for select patients with end-stage asbestosis and severe respiratory impairment.
Immunomodulators lead on scale; Oxygen Therapy leads on momentum.
Application:
The volume of treatment varies significantly based on the specific manifestation and severity of asbestos-related lung conditions.
- Severe Pulmonary Fibrosis:This application addresses advanced lung scarring where significant tissue damage has occurred, often necessitating aggressive therapeutic interventions. Demand concentrates in academic medical centers and clinical trials for novel antifibrotic drugs.
- Asbestos-Related Lung Cancer:This category involves the diagnosis and treatment of malignancies directly linked to asbestos exposure, including mesothelioma. Demand is particularly high in oncology centers located in regions with a legacy of heavy asbestos use, such as the United Kingdom.
- Chronic Respiratory Failure:Patients with this condition require ongoing support to maintain adequate breathing, frequently involving long-term oxygen therapy.
- Pleural Thickening:This involves non-malignant scarring of the lung lining, which can cause pain and restrict lung expansion.
- Bronchiectasis:A chronic lung condition characterized by permanent widening of the airways, which can sometimes co-occur with asbestosis.
Severe Pulmonary Fibrosis holds the largest share; Asbestos-Related Lung Cancer shows the steepest expansion trajectory.
End User:
Customer type dictates the sophistication of treatment required and the infrastructure available for patient management.
- Specialized Respiratory Centers:These dedicated facilities focus on complex lung diseases, providing multidisciplinary care and access to advanced therapies. They drive demand for high-cost, advanced immunomodulators and integrated care pathways.
- Pulmonology Clinics:Outpatient facilities manage general lung conditions, offering symptomatic management, diagnostic services, and long-term patient monitoring. They represent a significant end-user for corticosteroids and oxygen therapy.
- University Hospitals:Academic institutions contribute to both patient care and research, often participating in clinical trials for new treatments.
- Research Institutes:These entities focus primarily on drug discovery, preclinical studies, and clinical trials for novel therapeutic agents.
Specialized Respiratory Centers represent the largest end-user segment; Pulmonology Clinics are climbing the fastest.
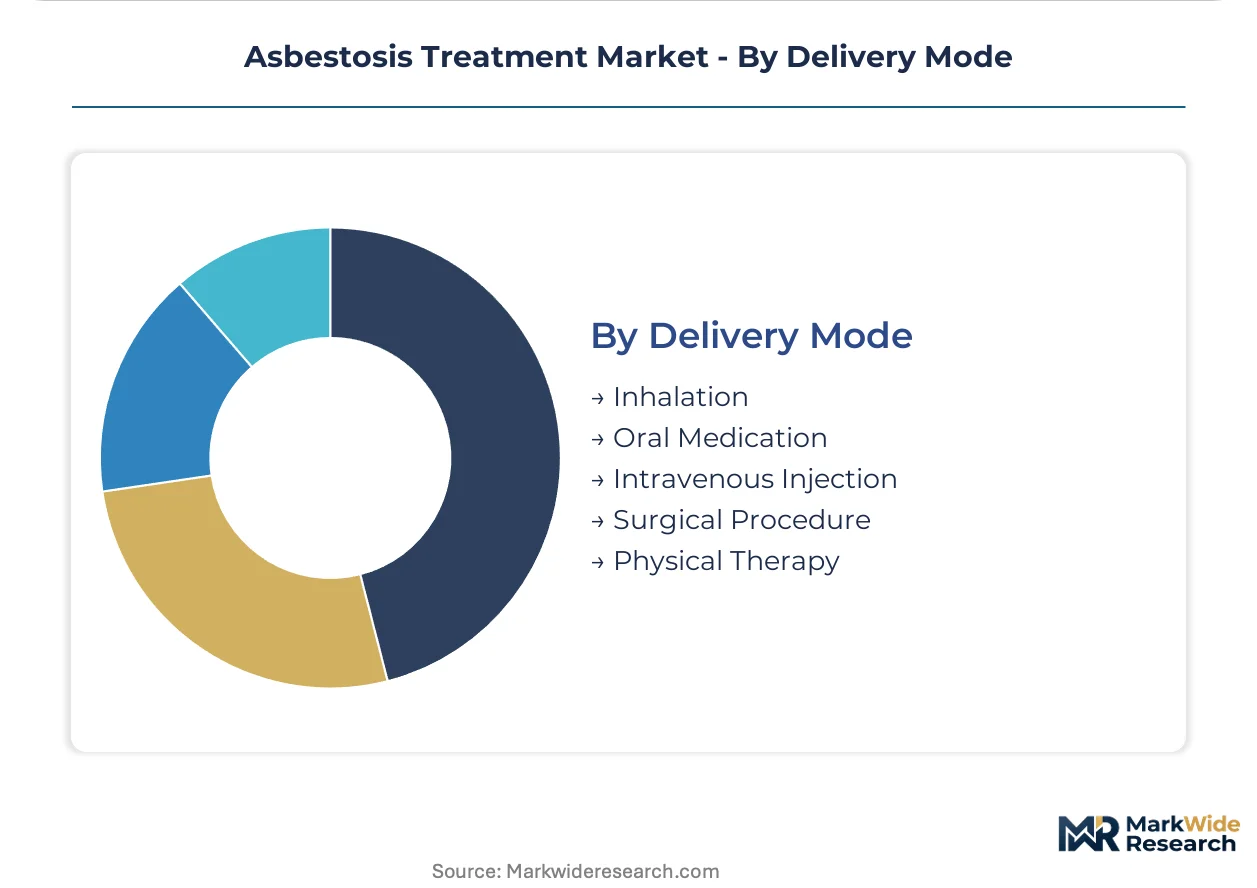
Delivery Mode:
The cost tier of treatment is often influenced by the method of drug administration and the associated infrastructure requirements.
- Oral Medication:This mode offers convenient systemic drug administration, suitable for long-term management at home. Demand is high for antifibrotic regimens and supportive medications prescribed for chronic use.
- Inhalation:Direct delivery of medication to the lungs provides localized effects, minimizing systemic side effects. This method is crucial for bronchodilators and inhaled corticosteroids used in symptomatic relief.
- Intravenous Injection:This delivery mode is typically used for biologics or high-dose corticosteroids, administered in a hospital or clinic setting.
- Surgical Procedure:Invasive interventions like lung transplantation or pleurectomy are reserved for specific advanced cases.
- Physical Therapy:Non-pharmacological interventions focus on improving respiratory muscle strength and overall physical conditioning.
Oral Medication commands the largest market share; Inhalation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory pathways for new treatments create varying market access speeds, influencing where advanced immunomodulators are first adopted. This disparity shapes the global distribution of R&D investment and influences where specialized care centers can offer cutting-edge therapies. The high cost and complexity of novel antifibrotic drugs mean their initial deployment often occurs in regions with robust healthcare infrastructure and established reimbursement mechanisms.
United States
The United States drives demand for novel asbestosis treatments due to a substantial legacy asbestos exposure cohort and significant R&D investment. The US FDA maintains stringent requirements for new antifibrotic drugs, influencing development timelines. Boston's biotech hub actively drives clinical trials for pipeline immunomodulators targeting pulmonary fibrosis.
United Kingdom
The United Kingdom exhibits high demand for asbestosis treatment, particularly for asbestos-related lung cancer, due to its industrial history. The Health and Safety Executive (HSE) mandates workplace safety and long-term health monitoring for exposed individuals. London-based specialized respiratory centers manage complex asbestos-related lung conditions and conduct advanced therapeutic research.
Australia
Australia represents a significant market for asbestosis treatment, stemming from extensive historical asbestos use and a strong focus on integrated disease management. The Therapeutic Goods Administration (TGA) approves advanced therapies for chronic respiratory conditions, including immunomodulators. Melbourne's medical research precincts contribute to long-term patient monitoring programs and clinical studies.
Japan
Japan's market for asbestosis treatment is characterized by an aging population and a well-developed healthcare infrastructure for chronic diseases. The PMDA accelerates assessment for drugs addressing unmet medical needs, potentially shortening market entry for novel therapies. Tokyo's university hospitals actively participate in clinical studies for new immunomodulators and advanced diagnostic protocols.
Germany
Germany maintains a strong position in the asbestosis treatment market, supported by a well-funded healthcare system and early adoption of advanced medical technologies. The EMA's PRIME scheme facilitates faster market access for innovative treatments within the European Union. Munich's research institutions actively collaborate on antifibrotic drug development and specialized respiratory care.
Asbestosis Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in the asbestosis treatment market. The landscape remains fragmented, with numerous players focusing on distinct therapeutic modalities. Archetypes include large pharmaceutical innovators developing novel immunomodulators and established generics manufacturers providing palliative care options. Strategic partnerships for R&D and targeted acquisitions of promising pipeline assets represent dominant competitive moves.
Global pharmaceutical leaders such as Pfizer exemplify broad portfolio diversification across multiple therapeutic areas. Roche, known for its oncology focus, anchors the development of targeted therapies for asbestos-related lung cancer, a severe complication. Boehringer Ingelheim, a privately held German company, occupies a strong position within respiratory diseases, leveraging its established portfolio for integrated care pathways in chronic conditions.
| Leading Market Players |
|---|
| Pfizer |
| Bristol-Myers Squibb |
| AstraZeneca |
| Novartis |
| Merck |
| Sanofi |
| Roche |
| Gilead Sciences |
| Boehringer Ingelheim |
| Others |
Cost & Logistics Intelligence
The significant therapeutic divergence between high-cost advanced immunomodulators and established, low-cost palliative care fundamentally shapes pricing and supply chain configurations. This bifurcation influences where R&D investment flows and how treatments reach patients.
Pricing Analysis
Hospital pharmacy margins significantly impact the final cost of advanced asbestosis treatments, particularly for novel immunomodulators. The dominant pricing structure is value-based for these high-cost therapies, contrasting with transactional per-unit pricing for older palliative drugs like corticosteroids. Price differentiation stems from regulatory approval status and the level of clinical evidence supporting disease modification. Pricing softness reflects the strong competition from established, cheaper palliative options. Patients requiring oxygen therapy are often the most price-sensitive buyers.
Supply Chain Analysis
Cold chain logistics for biologic immunomodulators represent a significant cost component, influencing distribution networks globally. Geographic supply concentration for active pharmaceutical ingredients (APIs) draws from manufacturing hubs in India and China, while finished drug production often occurs in the United States and Europe. Raw material dependencies include specialized biochemical precursors and sterile packaging components. Single-source vulnerability for proprietary drug compounds presents a structural supply chain risk. Distribution runs through specialized pharmaceutical wholesalers directly to advanced respiratory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asbestosis treatment market is evolving into a late-cycle quality story, driven by a demand-shift toward premium immunomodulatory therapies. This transition emphasizes disease modification over basic symptomatic relief.
For Market Incumbents: Acquire specialized clinical trial data platforms to accelerate pipeline development for antifibrotic agents. Incumbents like Boehringer Ingelheim must deepen R&D investment into novel immunomodulators to counter the threat of emerging biotech firms. Expand integrated care pathways to enhance patient retention and justify premium pricing for advanced therapies. Invest in digital health platforms for remote patient monitoring to create a competitive advantage.
For New Entrants and Emerging Players: Precision diagnostic technologies offer a technology-first wedge into the asbestosis treatment market by enabling early disease detection. Focus on developing highly targeted therapies for specific fibrotic pathways, particularly in severe pulmonary fibrosis. The most penetrable segment remains early-stage patients who can benefit most from disease-modifying interventions. Go-to-market strategies should emphasize partnerships with specialized respiratory centers for clinical validation and adoption.
For Investors and Strategic Acquirers: Consolidation pressure builds where significant R&D investment is required for novel antifibrotic drug development. Long-term viability hinges on companies with robust clinical pipelines and strong regulatory approval capabilities over a 5-10 year window. Acquisition targets should be biotech firms possessing advanced immunomodulator platforms or specialized diagnostic tools. The signal to watch is successful Phase 3 trial readouts for pipeline therapies targeting pulmonary fibrosis.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel immunomodulators addressing unmet medical needs. |
| Integrated Care Pathway Development | Enhances patient outcomes and strengthens commercial ties with specialized respiratory centers. |
| Digital Health Platform Integration | Improves remote patient monitoring capabilities and generates valuable real-world evidence. |
| Targeted Therapy Licensing Agreements | Expands product portfolios with innovative treatments for specific fibrotic pathways. |
| Early Diagnostic Screening Investments | Facilitates earlier intervention and broadens the patient pool eligible for advanced therapies. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and regulatory filings — were reconciled to construct a comprehensive market view. This involved engaging drug development executives, regulatory affairs leads, and pulmonologists across key geographies. Secondary data sources included US FDA filings, EMA submissions, and academic research papers focusing on pulmonary fibrosis. A combination of bottom-up and top-down triangulation validated all market estimates.
Historical market trends were cross-referenced with expert panel input to project future market trajectories across the analysis window. The model segmented demand by treatment type, application, end-user, and delivery mode, alongside regional regulatory clusters. Compound annual growth rates were derived from a detailed assessment of pipeline drug progression and patient population dynamics. Key forecast inputs included clinical trial success rates and evolving occupational safety standards.
The model holds under current regulatory landscapes and projected clinical development timelines; deviation in major drug approvals or reimbursement policies would shift market outcomes. Forecasts reflect assumptions regarding disease prevalence and treatment efficacy. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market