
 3D Printing in Healthcare Market | 2026-2036
3D Printing in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Healthcare Market Intelligence
MDR's tightened quality management requirements for patient-matched devices is consolidating the cost-of-entry calculus for European market participants. Formlabs leverages its desktop resin platform to compete in dental and surgical guide segments across ambulatory settings. Stratasys Ltd anchors polymer-based anatomical modeling through hospital-integrated service programs in North America. Materialise NV dominates surgical planning software that bridges imaging data to printer-ready file preparation.
3D printing in healthcare encompasses additive manufacturing processes that construct patient-specific anatomical models, surgical instruments, prosthetics, implants, and biocompatible tissue scaffolds from digital medical imaging data using layer-by-layer deposition of polymers, metals, ceramics, or living cell suspensions. Selective laser sintering of titanium alloys produces orthopedic implants with porosity gradients that promote osseointegration, while stereolithography fabricates surgical guides with sub-millimeter accuracy for drilling and cutting trajectories. Application segmentation reveals prosthetics and implants as the established revenue base, whereas organ bioprinting occupies the frontier where research institutions channel grants toward vascularized tissue constructs. Material segmentation shows polymers sustaining the highest volume throughput in dental and hearing aid production, while metals capture premium pricing in load-bearing orthopedic and cranio-maxillofacial applications.
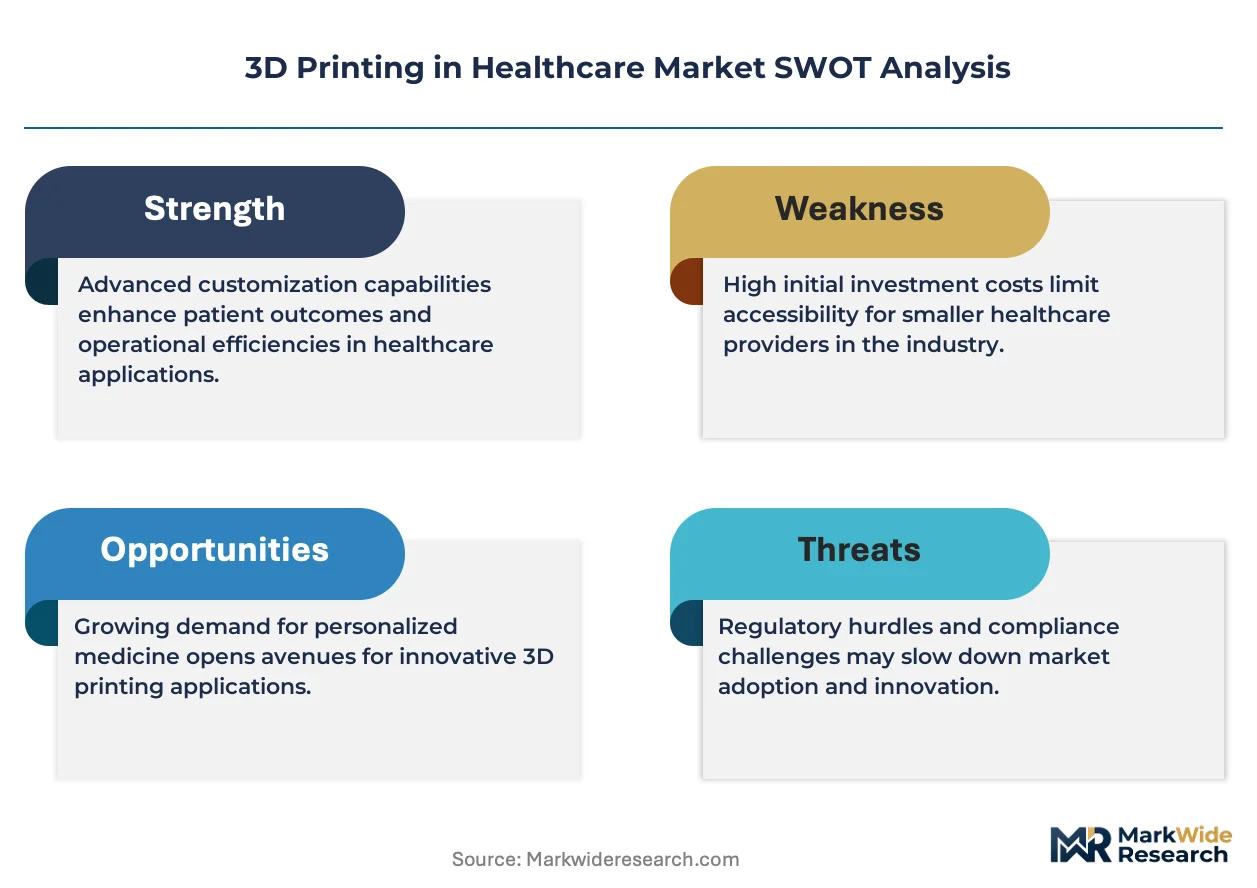
FDA's 510(k) framework, the EU MDR's Annex XVI expansion into custom-made devices, and ISO 13485 quality system standards collectively shape product development cycles, post-market surveillance obligations, and cross-border commercialization pathways for device manufacturers. Health Canada and Australia's TGA maintain mutual recognition arrangements that streamline parallel market access for firms holding US or EU approvals. Stakeholders must monitor evolving reimbursement codes for patient-specific implants and decide whether to build in-house printing capacity or outsource through contract manufacturing organizations as clinical evidence accumulates.
Market Dynamics
Point-of-care manufacturing programs at major hospital systems are compressing supply chains and redefining procurement relationships between device makers and clinical buyers. This structural shift is forcing manufacturers to choose between building distributed production networks or ceding control to hospital-integrated service models.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined clearance for patient-matched titanium implants reduces commercialization timelines and lowers regulatory capital requirements for orthopedic device entrants.
- Resin Desktop Platforms:Low-cost stereolithography systems enable ambulatory surgical centers to fabricate patient-specific surgical guides without centralized manufacturing contracts.
- Cleveland-Pittsburgh-Boston Hospital Clusters:Concentrated point-of-care adoption creates demonstration effects that accelerate technology diffusion into peer institutions.
Market Restraints
- Titanium Powder Supply Concentration:Limited qualified suppliers of medical-grade spherical Ti-6Al-4V powder in North America creates input vulnerability for implant manufacturers.
- EU MDR Annex XVI Expansion:Tightened quality management requirements for custom-made devices extend certification timelines and consolidate cost-of-entry barriers for European participants.
- Bioprinting Technical Limitations:Vascularized tissue constructs remain confined to research institutions due to unresolved perfusion architecture challenges in multi-cellular deposition.
Strategic Opportunities
- Underpenetrated Australian Market:TGA mutual recognition arrangements with FDA create streamlined parallel access for US-cleared patient-specific implants.
- AI-Imaging Convergence:Automated segmentation algorithms paired with surgical planning software reduce file preparation labor and expand anatomical modeling throughput.
- Contract Manufacturing Channel:Hospital systems lacking capital for in-house metal printing capacity present white space for outsourced point-of-care production services.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Shortage of professionals trained in both additive manufacturing process control and ISO 13485 quality system implementation constrains production scaling.
- Post-Market Surveillance Burden:FDA's real-world performance data requirements for 3D-printed implants demand dedicated regulatory affairs infrastructure that mid-size device firms struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Healthcare Market |
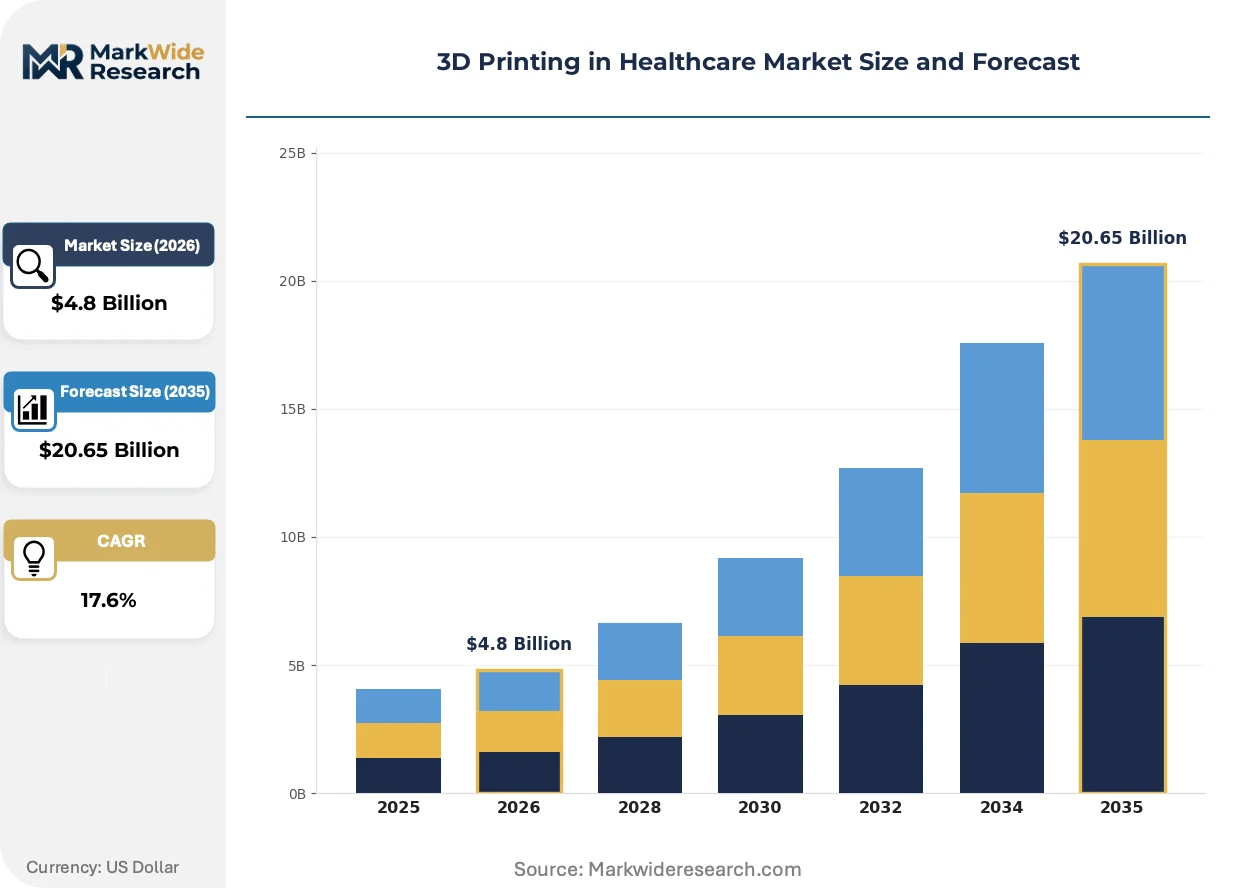
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Prosthetics, Implants, Surgical Models, Organ Bioprinting Material: Polymers, Metals, Ceramics, Bioprinting Materials Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Clinics, Research Institutions, Contract Manufacturing Organizations |
| Companies Covered | Formlabs, General Electric, 3D Systems Corporation, SLM Solutions Group, Renishaw plc, Materialise NV, EnvisionTEC, Organovo Holdings, Stratasys Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Healthcare Market Strategic Shifts & Innovations
Multi-material deposition capabilities and regulatory digitization are converging to transform how patient-specific devices move from imaging data to clinical implantation. These developments are compressing traditional manufacturing lead times while expanding the anatomical complexity addressable through additive methods.
Selective laser melting of functionally graded titanium alloys is rewriting load-bearing implant design by enabling porosity gradients that match bone stiffness variation from cortical to cancellous regions. Orthopedic trauma centers in the United States are adopting these osseointegration-optimized fixtures at accelerating rates. The technology is rewriting competitive positioning by allowing manufacturers to command premium pricing for patient-matched geometries that off-the-shelf inventory cannot replicate.
EU MDR's enhanced scrutiny of custom-made device technical documentation is forcing manufacturers to restructure quality management systems around design history file traceability. The regulation compresses product development cycles as firms front-load clinical evidence generation to preempt notified body queries. Cranio-maxillofacial reconstruction segments face the steepest compliance burden due to the high variability of patient-specific anatomical defects.
Hospital procurement departments are consolidating vendor relationships around integrated service providers capable of delivering imaging-to-implant workflows. Traditional device distributors lose relevance as buyers demand direct software-hardware-material bundles with embedded training and maintenance. This pattern concentrates in the United States where health system consolidation creates purchasing leverage that fragmented regional suppliers cannot match.
3D Printing in Healthcare Market Segmentation
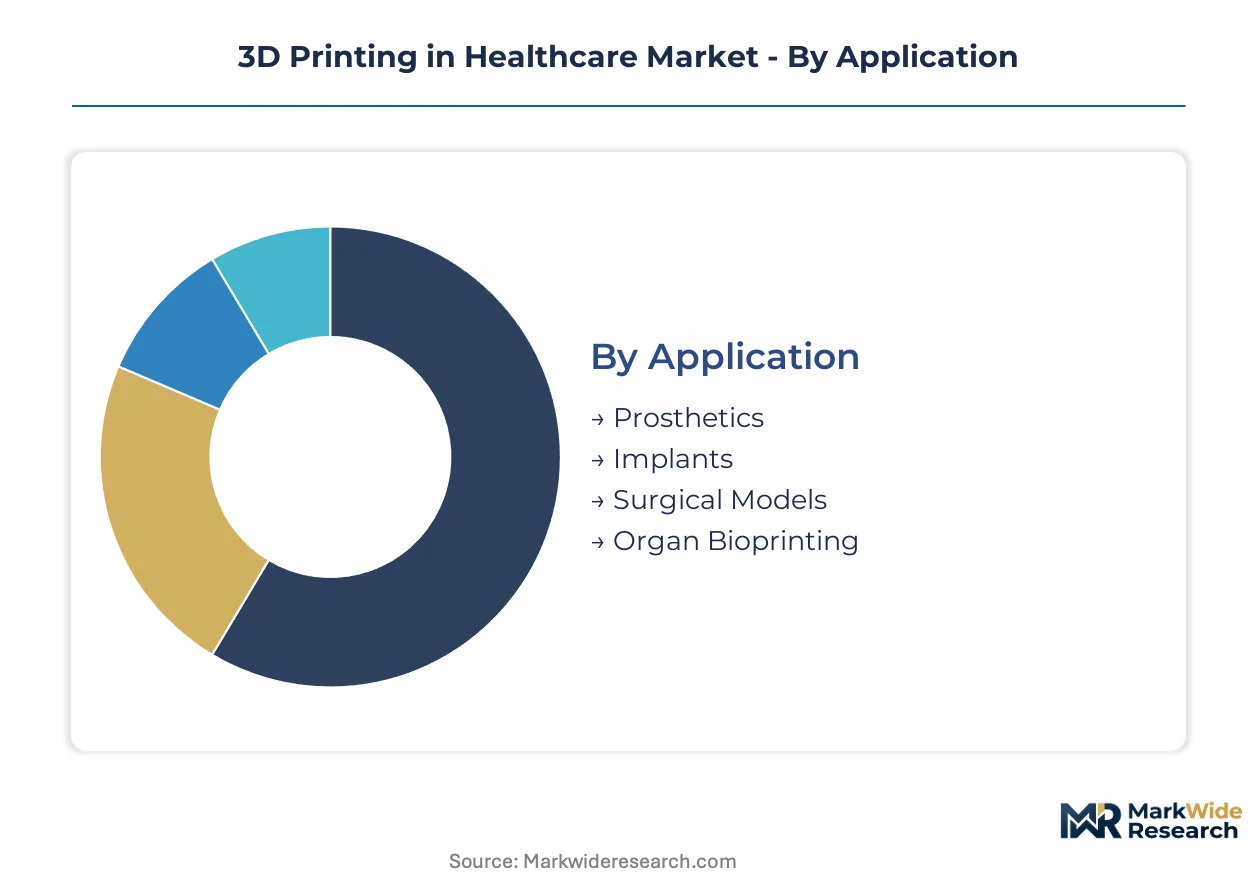
Segmentation in healthcare additive manufacturing reveals how regulatory pathways, material properties, and clinical workflows intersect to determine commercial viability. Understanding these divisions helps stakeholders align production capabilities with reimbursement codes and point-of-care deployment models.
Application:
FDA 510(k) clearances concentrate in prosthetics and implants, while organ bioprinting operates outside commercial regulatory frameworks. Each segment carries distinct clinical evidence requirements and post-market surveillance obligations.
- Prosthetics:Patient-matched socket interfaces and limb components fabricated from nylon and carbon-fiber composites. Demand clusters at Veterans Affairs medical centers in the United States and specialized rehabilitation hospitals in Germany, driven by personalized fit requirements that reduce revision surgeries.
- Implants:Load-bearing titanium fixtures with topology-optimized geometries and controlled porosity for osseointegration. Orthopedic trauma units at Cleveland Clinic and Massachusetts General Hospital represent concentrated adoption centers, replacing off-the-shelf inventory with patient-specific plates and cages.
- Surgical Models:Anatomical replicas for preoperative planning and resident training.
- Organ Bioprinting:Vascularized tissue constructs for drug screening and transplant research, confined to academic medical centers.
Prosthetics sits at the top of the volume ranking, with organ bioprinting climbing the fastest despite remaining pre-commercial.
Material:
Cost tiers separate commodity polymers from premium metals, with ceramics occupying a narrow middle band for dental and cranio-maxillofacial applications.
- Polymers:ABS, PLA, and photopolymer resins dominate dental aligners, hearing aid shells, and surgical guides. Ambulatory surgical centers in the United States deploy desktop stereolithography systems for same-day guide fabrication, eliminating centralized manufacturing lead times.
- Metals:Titanium alloys and cobalt-chrome powders command premium pricing in spinal fusion cages and acetabular cups. Supply concentration in spherical Ti-6Al-4V powder creates input vulnerability for implant manufacturers dependent on qualified suppliers.
- Ceramics:Zirconia and hydroxyapatite for dental crowns and bone graft substitutes.
- Bioprinting Materials:Cell-laden hydrogels and decellularized extracellular matrix for tissue engineering research.
Polymers capture the highest throughput, with bioprinting materials expanding most quickly in grant-funded research settings.
Technology:
Maturity curves separate decades-old deposition methods from emerging light-based systems, with each technology carrying distinct capital requirements and regulatory validation histories.
- Fused Deposition Modeling:Thermoplastic extrusion systems for low-cost anatomical models and surgical training phantoms. Medical schools and simulation centers represent primary demand nodes, prioritizing affordability over surface finish precision.
- Selective Laser Sintering:Powder-bed fusion of polymers and metals for end-use implants with isotropic mechanical properties. FDA's 510(k) database shows concentrated clearances for SLS-produced cranial implants and pelvic reconstruction plates.
- Stereolithography:Photopolymer vat polymerization for surgical guides and dental appliances requiring sub-millimeter accuracy.
- Digital Light Processing:Projector-based resin curing for high-throughput dental production.
Fused deposition modeling leads in installed base, with selective laser sintering gaining share fastest in metal implant production.
End User:
Procurement authority and capital access determine which settings adopt in-house printing versus outsourced production models.
- Hospitals:Integrated point-of-care manufacturing programs at health systems with dedicated biomedical engineering departments. Cleveland Clinic, University of Pittsburgh Medical Center, and Brigham and Women's Hospital maintain active metal printing capacity for orthopedic and cranio-maxillofacial applications.
- Research Institutions:Academic medical centers and national laboratories advancing bioprinting and multi-material deposition. NIH and NSF grant portfolios concentrate at Wake Forest Institute for Regenerative Medicine and Harvard Wyss Institute.
- Clinics:Private dental and orthopedic practices with limited capital for metal systems.
- Contract Manufacturing Organizations:Outsourced production partners for hospitals lacking ISO 13485 infrastructure.
Hospitals command the highest revenue per site, with contract manufacturing organizations expanding most quickly as health systems defer capital investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineers trained in additive manufacturing and ISO 13485 quality systems concentrate in the United States, Germany, and Japan, anchoring regional production capabilities. Hospital systems and research institutions compete aggressively for this scarce talent pool. Regulatory divergence across FDA, EMA, and PMDA jurisdictions shapes where manufacturers choose to commercialize first.
United States
Cleveland Clinic, Massachusetts General Hospital, and University of Pittsburgh Medical Center operate point-of-care metal printing programs for orthopedic implants. FDA's 510(k) clearance pathway compresses approval timelines for patient-matched titanium devices. The Boston-Cleveland-Pittsburgh corridor generates demonstration effects that accelerate adoption into peer academic medical centers.
Germany
Industrial machinery heritage feeds precision powder-bed fusion equipment manufacturing for medical applications. EU MDR Annex XVI tightened quality management requirements for custom-made devices, extending certification timelines for cranio-maxillofacial reconstruction segments. The Baden-Württemberg and Bavaria industrial clusters host concentrated orthopedic implant research programs at university hospitals.
Japan
PMDA maintains stringent clinical evidence requirements for 3D-printed load-bearing implants that lag FDA clearance volumes. METI funding programs target regenerative medicine applications including vascularized tissue constructs. The Kanto region around Tokyo hosts the highest density of dental 3D printing adoption for aligner and crown production.
Australia
TGA mutual recognition arrangements with FDA create streamlined parallel market access for US-cleared patient-specific implants. The underpenetrated hospital market presents white space for outsourced point-of-care production services. Sydney and Melbourne academic medical centers channel NHMRC grants toward bioprinting research for drug screening applications.
China
NMPA regulatory pathways for patient-matched devices remain less standardized than FDA or EMA frameworks, creating commercialization uncertainty. Domestic powder suppliers are qualifying spherical Ti-6Al-4V production for medical-grade implant applications. The Yangtze River Delta region concentrates dental 3D printing equipment manufacturing for export markets.
3D Printing in Healthcare Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates and specialized additive manufacturing pure-plays rather than traditional orthopedic device incumbents. Market entry costs separate capital-intensive metal powder-bed fusion system builders from desktop resin platform competitors. Two strategic archetypes dominate: integrated hardware-software-materials providers and contract manufacturing service specialists. Competitive moves concentrate on hospital-integrated service program expansion and regulatory clearance portfolio accumulation.
Among hardware-software integrators, Materialise NV and Stratasys Ltd exemplify divergent positioning within surgical planning and polymer-based anatomical modeling respectively. Formlabs occupies the desktop resin tier competing across ambulatory surgical settings. These three entities represent how geographic origin and corporate structure correlate with archetype selection — Belgian NV structures anchoring software-heavy models, US Inc. and Ltd. formations backing hardware platform plays.
| Leading Market Players |
|---|
| Formlabs |
| General Electric |
| 3D Systems Corporation |
| SLM Solutions Group |
| Renishaw plc |
| Materialise NV |
| EnvisionTEC |
| Organovo Holdings |
| Stratasys Ltd |
| Others |
Cost & Logistics Intelligence
Hospital systems with integrated point-of-care manufacturing programs command substantial pricing leverage through bundled imaging-to-implant service contracts that displace traditional device distributors. This buyer concentration forces manufacturers to compete on total workflow value rather than per-unit implant pricing alone.
Pricing Analysis
Bundled service contracts dominate hospital procurement while unbundled component sales persist in ambulatory clinic settings. Pricing stratifies across premium patient-matched titanium implants, standard polymer surgical guides, and economy-grade anatomical training models. Cost compression in desktop resin systems intensifies as Formlabs and competitors race for ambulatory surgical center adoption. Dental clinics exhibit highest price sensitivity due to thin procedure margins, whereas orthopedic trauma centers prioritize osseointegration performance over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle concentrated demand from Cleveland Clinic, UPMC, and Mass General while distributor networks serve fragmented dental and orthopedic practices. Spherical Ti-6Al-4V powder supply concentrates in Germany, China, and the United States, with medical-grade qualification limiting qualified suppliers. Production draws from photopolymer resin feedstocks anchored in Belgian and US chemical manufacturing. Single-source vulnerability in qualified titanium powder creates input risk for implant manufacturers scaling metal printing capacity. Distribution runs through ISO 13485-certified contract manufacturers for hospital systems lacking in-house quality infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement committees elevate ISO 13485 certification and FDA 510(k) clearance history above unit cost in supplier selection. Patient-specific implant demand shifts toward premium specifications that guarantee osseointegration performance and reduce revision liability.
For Market Incumbents: Hedge against hospital vertical integration by acquiring contract manufacturing capabilities in the Boston-Cleveland-Pittsburgh corridor. Secure captive supply of medical-grade spherical Ti-6Al-4V powder through backward integration or long-term offtake agreements with German and US suppliers. Build regulatory affairs infrastructure capable of sustaining FDA real-world performance data submissions without margin erosion. For New Entrants and Emerging Players: Enter via the underpenetrated Australian hospital market where TGA-FDA mutual recognition creates streamlined parallel access for US-cleared devices. Target outsourced point-of-care production services for mid-size health systems lacking capital for in-house metal printing capacity. Pursue software-heavy positioning through AI-imaging convergence partnerships that reduce file preparation labor for anatomical modeling. For Investors and Strategic Acquirers: Hospital systems and industrial conglomerates with healthcare divisions are the most active acquirers in this space, consolidating point-of-care manufacturing capabilities. Five-to-ten year viability hinges on regulatory clearance portfolio depth rather than hardware scale. Target acquisition profile centers on ISO 13485-certified contract manufacturers with embedded biomedical engineering talent. Watch FDA 510(k) clearance velocity for patient-matched titanium implants as the inflection signal for orthopedic segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures long-term imaging-to-implant workflow contracts with Cleveland Clinic and UPMC. |
| FDA 510(k) Submission | Accelerates patient-matched titanium implant commercialization through streamlined clearance pathway. |
| CE Marking Pathway | Unlocks EU market access despite MDR Annex XVI tightened quality management requirements. |
| Software Companion Development | Automates segmentation algorithms that bridge DICOM imaging to printer-ready file preparation. |
| Reimbursement Strategy | Secures dedicated CPT codes for patient-specific implants that justify premium hospital pricing. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down additive manufacturing equipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at orthopedic device manufacturers combined with secondary validation from FDA 510(k) database filings, CMS Medicare reimbursement schedules, hospital procurement databases, and ISO 13485 certification registries. Triangulation between demand-side adoption metrics and supply-side production capacity estimates ensures cross-verified outputs.
Historical trendline analysis of patient-specific implant adoption rates and point-of-care manufacturing program expansion informs the projection framework. Segmentation modeling spans application type, material category, technology platform, and end-user setting across the analysis window. CAGRs derive from fitted growth curves applied to hospital capital expenditure patterns and regulatory clearance velocity. Forecast inputs include FDA review timeline compression effects and EU MDR implementation cost burdens on European market participants.
Inputs from FDA 510(k) filings and hospital procurement databases were available through the study window; gaps in real-time point-of-care production volume data introduce uncertainty bands around near-term adoption estimates. Forecasts reflect assumptions regarding continued titanium powder supply qualification and biomedical engineer talent pipeline expansion. Periodic stress-testing of base assumptions is recommended against FDA guidance document revisions and EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Lactate Meter Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Global Breast Biopsy Devices Market