
 Implantable Port Market | 2026-2036
Implantable Port Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Port Market Intelligence
Oncology infusion therapy is repositioning hospital procurement priorities toward long-dwelling port systems that reduce catheter-related complications. B. Braun Melsungen AG leverages its European manufacturing base to sustain supply continuity across Western European hospital networks. Cook Medical anchors its competitive stance through deep specialization in minimally invasive vascular access technologies. Medtronic competes by extending its cardiac rhythm management channel relationships into interventional oncology segments.
An implantable port is a subcutaneously placed reservoir connected to a central venous catheter, typically constructed from titanium, silicone, or polyurethane with a self-sealing septum capable of withstanding hundreds of needle punctures. The device enables repeated vascular access for chemotherapy, parenteral nutrition, or blood sampling while reducing infection risk versus external catheters. Centrally inserted ports dominate acute hospital settings where surgical placement under fluoroscopy ensures tip positioning in the superior vena cava, while peripherally inserted ports gain traction in outpatient clinics seeking to avoid surgical suite costs. Silicone and polyurethane material segments split along dwell-time requirements, with polyurethane offering thinner wall profiles for pediatric applications and silicone preferred for multi-year oncology protocols where chemical stability matters most.
FDA 510(k) clearance pathways and ISO 10993 biocompatibility testing frameworks govern material selection and sterilization validation for all commercially distributed devices in the United States. The EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable ports than preceding directives, reshaping European market access timelines for non-CE-marked manufacturers. Stakeholders must monitor evolving CMS reimbursement codes for ambulatory surgical center placement procedures, as payment parity shifts between hospital outpatient and freestanding settings will determine volume allocation across end-user channels.
Market Dynamics
Oncology infusion protocols are compressing catheter replacement cycles, forcing manufacturers to engineer multi-year dwell systems that withstand aggressive chemical exposure without material degradation. This pressure is restructuring R&D allocation across the implantable vascular access supply base.
Growth Catalysts
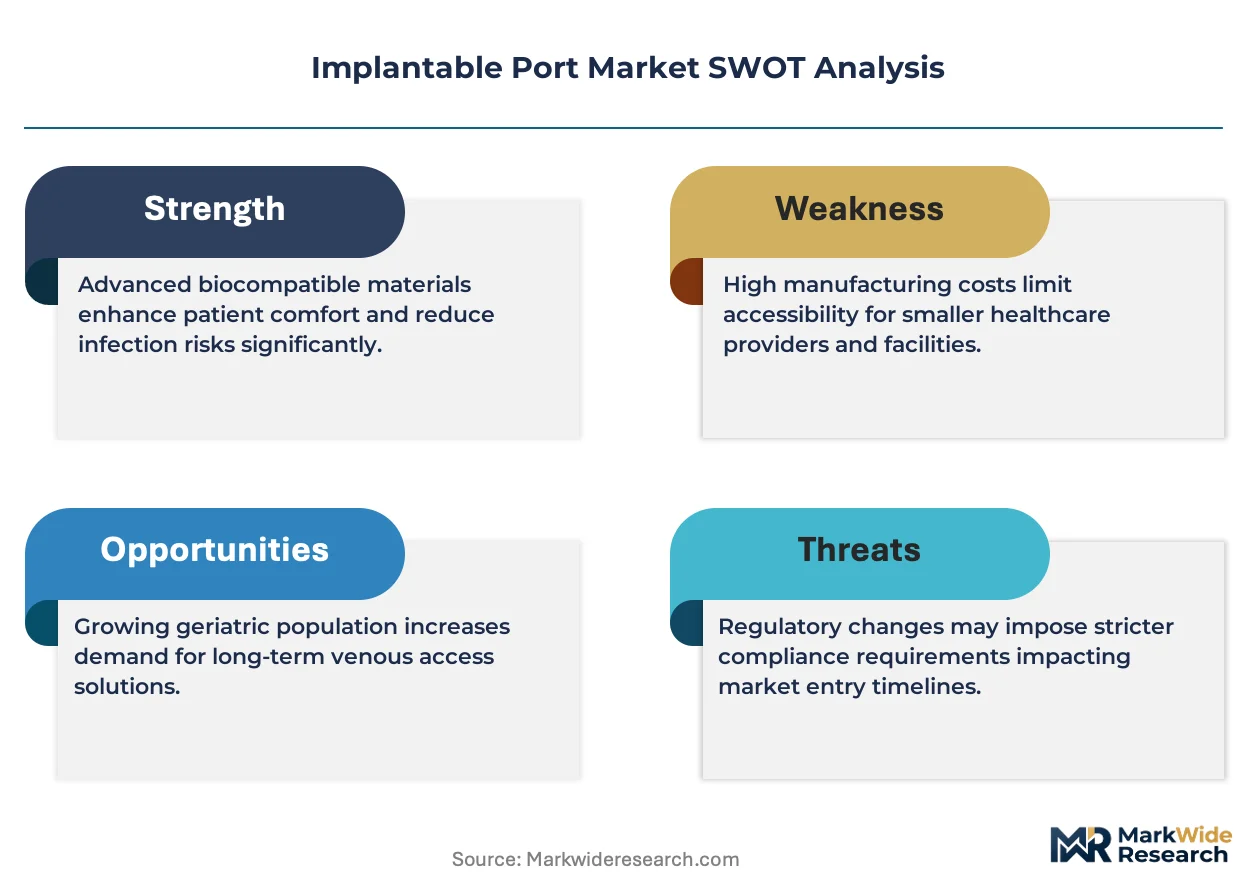
- ISO 10993-5 cytotoxicity testing:Biocompatibility validation requirements are filtering out substandard material suppliers, elevating device reliability benchmarks for long-term implantation.
- Ambulatory surgical center expansion:Medicare reimbursement parity between hospital outpatient and freestanding settings is redirecting port placement volume toward lower-cost procedural venues.
- Silicone septum engineering:Self-sealing polymer formulations capable of 2,000+ puncture cycles are extending functional device lifespan and reducing replacement surgery frequency.
Market Restraints
- Titanium raw material concentration:Medical-grade titanium sponge supply chains cluster in Chinese and Russian smelting operations, exposing manufacturers to geopolitical input volatility.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations are extending European market access timelines and inflating regulatory compliance costs for smaller manufacturers.
- Peripherally inserted central catheter substitution:PICC lines retain cost and placement simplicity advantages for short-duration therapy, capping port adoption in sub-90-day treatment windows.
Strategic Opportunities
- Pediatric polyurethane thin-wall designs:Smaller-diameter catheter construction for low-body-weight patients remains underdeveloped, with few competitors mastering kink-resistant low-profile geometries.
- India CDSCO streamlined Class C device pathways:Regulatory harmonization efforts are reducing import approval friction for established US and EU manufacturers seeking Asian market entry.
- Remote patient monitoring convergence:Integration of pressure-sensing telemetry into port reservoirs promises real-time flow obstruction detection, creating service revenue streams beyond device sale.
Industry Challenges
- Interventional radiology technician scarcity:Fluoroscopy-guided placement requires specialized surgical support staff, constraining placement capacity expansion in community hospital settings.
- Legacy EMR integration complexity:Port-specific implant registries must interface with hospital information systems lacking standardized vascular access device data fields, complicating patient tracking.
- FDA 510(k) predicate device erosion:Substantial equivalence pathways are narrowing as predicate devices age out of distribution, forcing more de novo submissions with extended review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Port Market |
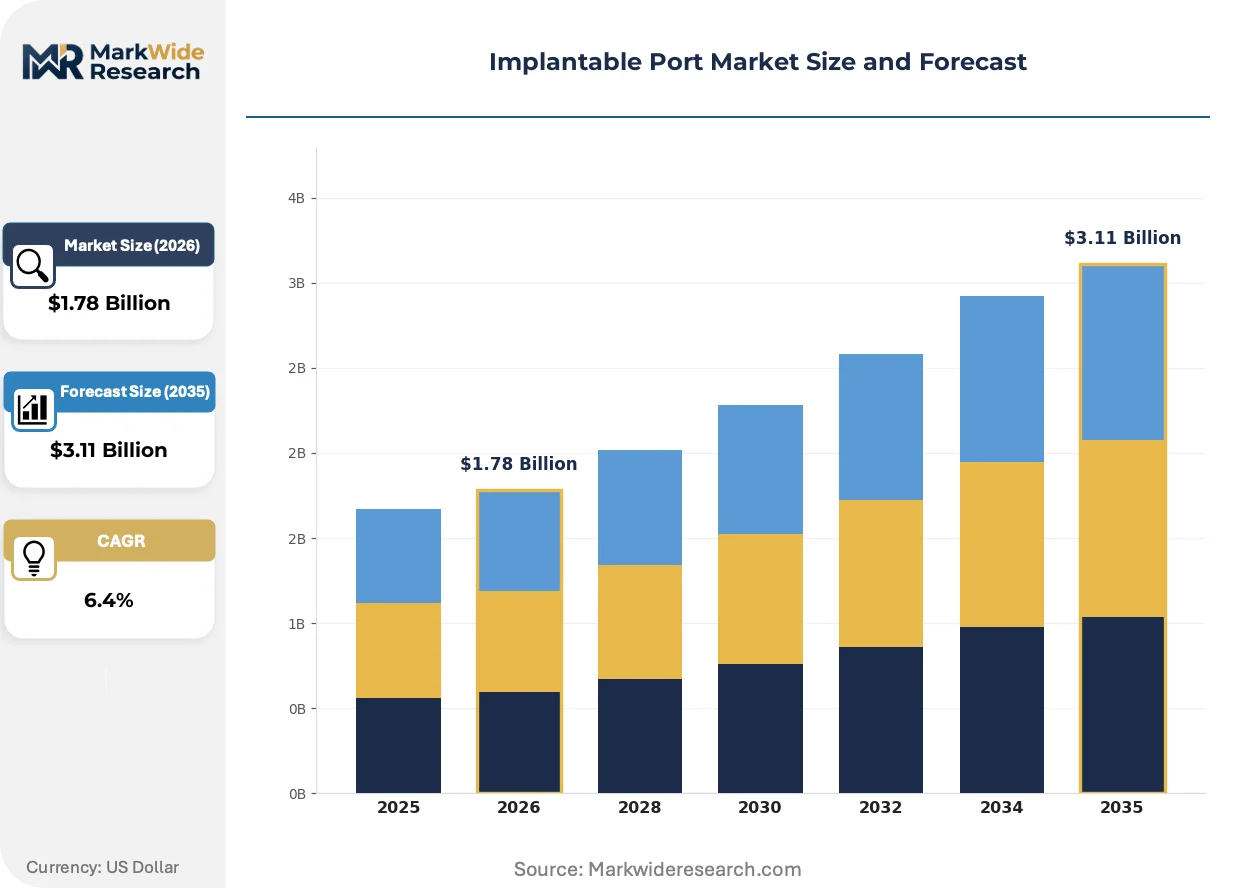
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrally Inserted Ports, Peripherally Inserted Ports, Tunneled Ports, Non-Tunneled Ports Material: Silicone, Polyurethane, PVC, Titanium End User: Hospitals, Outpatient Clinics, Home Healthcare, Long-Term Care Facilities Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Epidural |
| Companies Covered | B. Braun Melsungen AG, Cook Medical, Becton, Dickinson and Company, Vygon, Medtronic, Teleflex Incorporated, AngioDynamics, ICU Medical, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Port Market Strategic Shifts & Innovations
Material science advances and procedural venue migration are compressing the gap between acute and chronic care device specifications. Manufacturers now engineer single platforms spanning surgical suite placement through multi-year ambulatory management.
Antimicrobial-impregnated polymers are electrifying infection prevention strategies in long-dwelling vascular access. Pediatric oncology centers in Boston and Houston are piloting silver-ion dosed silicone reservoirs that suppress biofilm formation across 18-month chemotherapy protocols. This chemistry is compressing hospital-acquired bloodstream infection rates and reducing emergency department visits for suspected port sepsis.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market performance data beyond pre-market bench testing. German notified bodies are rejecting legacy predicate-based submissions for titanium-bodied ports lacking real-world implant duration evidence. French and Italian hospital procurement committees now prioritize CE-marked devices with published 5-year follow-up cohorts, penalizing newer market entrants.
Hospital supply chain directors are unbundling device procurement from placement service contracts, reversing decade-old bundled payment structures. Academic medical centers in Philadelphia and Cleveland now separately negotiate port device pricing through group purchasing organizations while contracting interventional radiology placement through distinct professional service agreements. This bifurcation is most visible in US markets where Medicare's hospital outpatient prospective payment system creates transparent cost accounting pressure.
Implantable Port Market Segmentation
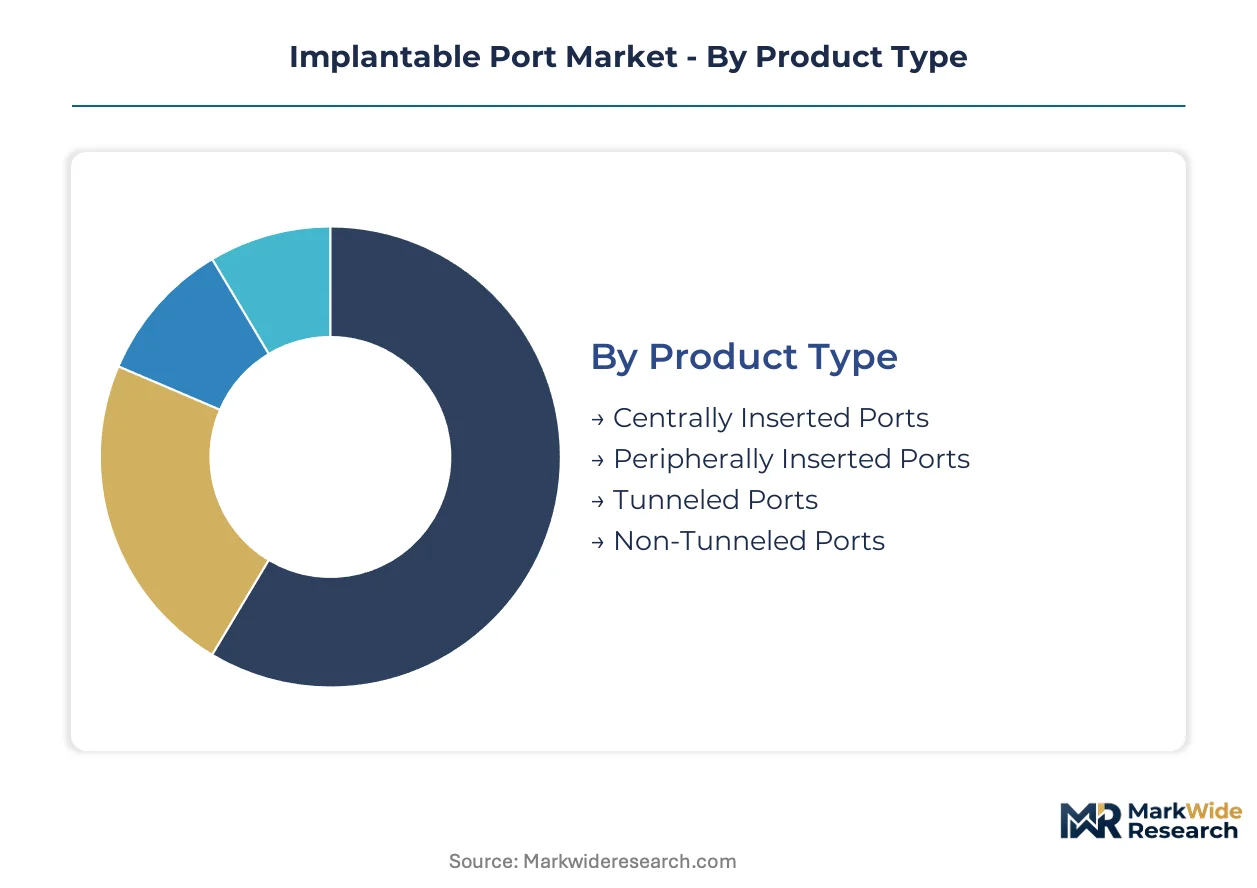
Implantable port purchasing decisions split across dwell-time requirements, material biocompatibility, and procedural venue economics. Manufacturers configure product portfolios to capture volume in acute hospital settings while defending margin in specialized outpatient and home-based infusion channels.
Product Type:
Volume concentrates in surgically placed systems, while premium positioning shifts toward minimally invasive alternatives that reduce facility fees.
- Centrally Inserted Ports:Titanium-bodied reservoirs with silicone septums positioned in the superior vena cava under fluoroscopic guidance. Demand clusters in United States academic medical centers managing multi-year oncology protocols, where tip placement precision reduces thrombotic complications and repeat intervention costs.
- Peripherally Inserted Ports:Smaller-diameter catheter systems placed via arm veins without surgical suite requirements. Outpatient clinics in Germany and France are adopting these for 6-12 month chemotherapy windows, bypassing hospital outpatient prospective payment system reimbursement tiers.
- Tunneled Ports:Catheter segments buried within subcutaneous tissue to create biological barriers against ascending infection.
- Non-Tunneled Ports:Direct vascular entry configurations reserved for acute inpatient settings with intensive nursing surveillance.
Today's leader: Centrally Inserted Ports. Tomorrow's challenger: Peripherally Inserted Ports.
Material:
Silicone commands extended-dwell oncology applications, while polyurethane gains share in pediatric and ambulatory segments demanding mechanical flexibility.
- Silicone:Elastomeric polymer with exceptional chemical stability against lipophilic chemotherapy agents and self-healing septum properties. United States oncology centers specify medical-grade silicone for ports intended to withstand 2,000+ access cycles across 18-24 month treatment durations.
- Polyurethane:Thermoplastic elastomer enabling thinner wall construction without kink resistance loss. Pediatric hospitals in Boston and Houston specify low-durometer polyurethane formulations for patients under 30 kilograms, where catheter diameter constraints dominate device selection.
- PVC:Cost-competitive thermoplastic with established extrusion processing but limited long-term implant acceptance due to plasticizer leaching concerns.
- Titanium:Biocompatible metal alloy forming port reservoir bodies and anchoring mechanisms, prized for magnetic resonance imaging compatibility and fatigue resistance.
Silicone dominates current procurement specifications. Polyurethane is climbing the fastest in pediatric and thin-wall design applications.
End User:
Hospital purchasing power shapes base volume, while site-of-care migration redirects growth toward lower-acuity settings.
- Hospitals:Integrated delivery networks with interventional radiology suites and cardiac catheterization laboratories. These facilities capture complex placement cases requiring real-time imaging guidance and immediate complication management capability.
- Outpatient Clinics:Freestanding infusion centers operating under Medicare's ambulatory surgical center reimbursement framework. United States market expansion here depends on procedural volume thresholds that justify dedicated vascular access staffing.
- Home Healthcare:Skilled nursing services managing port maintenance and medication administration in residential settings, constrained by reimbursement for routine access procedures.
- Long-Term Care Facilities:Extended-care institutions serving chronically ill populations with parenteral nutrition requirements, where infection control protocols lag acute care standards.
Hospitals retain procurement leverage today. Outpatient Clinics represent the steepest expansion trajectory as site-of-care economics shift.
Delivery Mode:
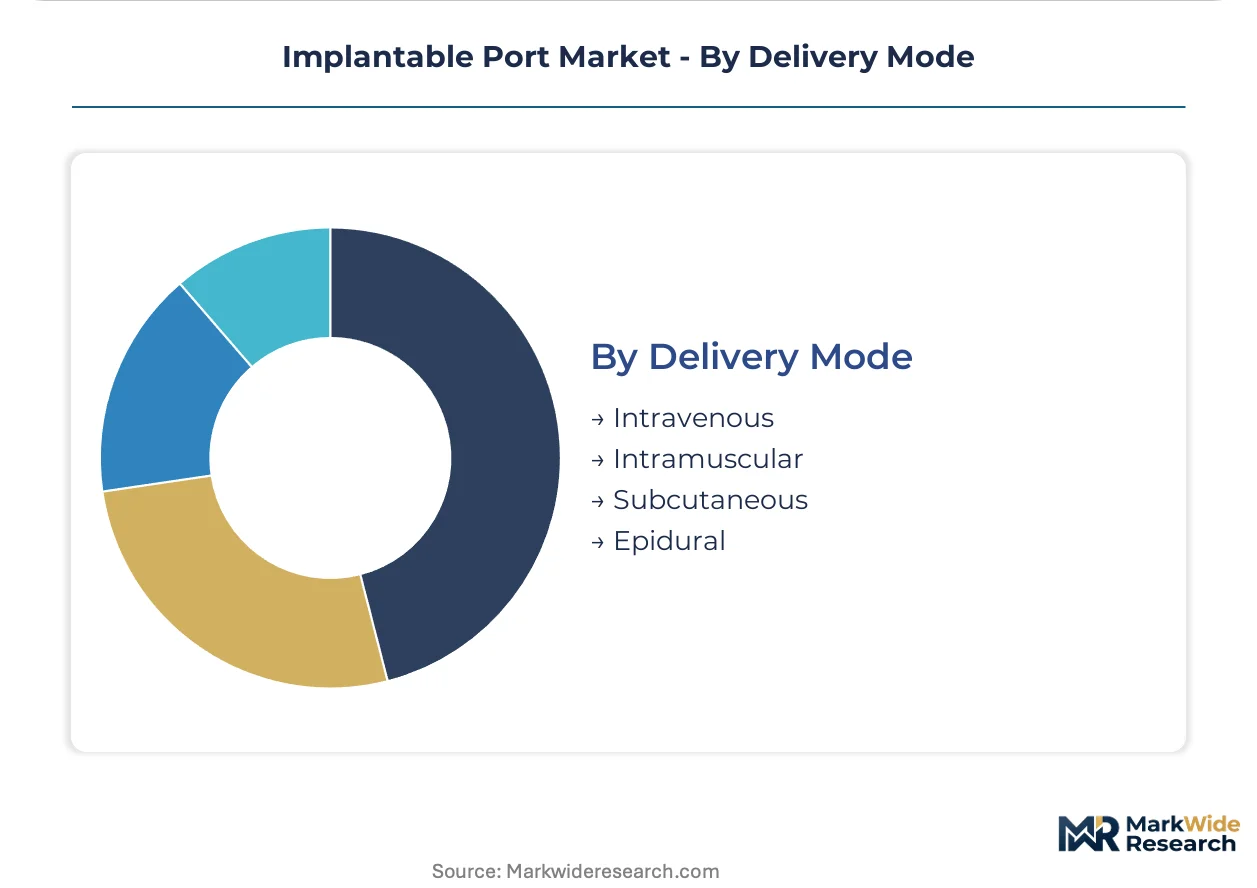
Intravenous access generates overwhelming procedure volume, while alternative routes serve narrow therapeutic niches with specialized reimbursement.
- Intravenous:Central venous administration pathway enabling rapid dilution of vesicant chemotherapy agents and total parenteral nutrition delivery. This mode anchors virtually all implantable port utilization in oncology and critical care applications.
- Intramuscular:Deep tissue drug deposition route with limited port-based adoption, primarily experimental in sustained-release hormonal therapy protocols.
- Subcutaneous:Reservoir access for insulin delivery and immunoglobulin infusion, competing against dedicated insulin pumps and infusion sets.
- Epidural:Neuraxial drug delivery for chronic pain management and obstetric anesthesia, requiring specialized catheter engineering and sterile technique protocols distinct from vascular access.
Intravenous delivery defines current clinical practice. Subcutaneous applications are gaining share fastest in diabetes and immunology therapeutic categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions where FDA 510(k) equivalency and EU MDR compliance costs diverge most sharply, exploiting regulatory-arbitrage gaps between mature and emerging medical device oversight frameworks.
United States
Academic medical centers in Philadelphia and Cleveland drive procurement volume for multi-year oncology protocols. Medicare's hospital outpatient prospective payment system shapes reimbursement parity discussions between hospital and ambulatory surgical center placement. The FDA's tightening 510(k) predicate device requirements are extending review timelines for new market entrants.
Germany
Notified bodies in Berlin and Munich are rejecting legacy predicate-based submissions for titanium-bodied ports lacking real-world implant duration evidence. The EU MDR Article 10 clinical evaluation framework is inflating compliance costs for smaller manufacturers. Bavarian hospital networks prioritize CE-marked devices with published 5-year follow-up cohorts.
France
Hospital procurement committees in Paris and Lyon now penalize newer market entrants lacking post-market surveillance data. ANSM oversight of vascular access device vigilance reporting is reshaping supplier qualification criteria. French outpatient clinics are adopting peripherally inserted ports to bypass hospital outpatient reimbursement tiers.
India
CDSCO streamlined Class C device pathways are reducing import approval friction for established US and EU manufacturers. Maharashtra and Karnataka host expanding interventional radiology capacity in Mumbai and Bengaluru private hospital networks. Domestic production incentives are attracting contract manufacturers serving Asian market entry strategies.
Japan
PMDA marketing authorization timelines for implantable vascular access devices remain among the longest in developed markets. Tokyo and Osaka academic medical centers specify medical-grade silicone for ports intended to withstand 2,000+ access cycles. METI industrial policy is supporting domestic catheter manufacturing capability expansion.
Implantable Port Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbent device manufacturers extend cardiac rhythm management and minimally invasive surgery channel relationships into interventional oncology segments. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with deep hospital contracting relationships, specialized vascular access manufacturers with fluoroscopy-guided placement expertise, and regional European suppliers leveraging proximity to German and French hospital networks. M&A activity and strategic partnerships represent the dominant competitive moves, with targets selected for regulatory approval portfolio depth and interventional radiology specialist sales force access.
Among diversified medical technology conglomerates, B. Braun Melsungen AG exemplifies the European manufacturing base archetype, while Medtronic occupies a position representing channel extension from cardiac rhythm management into oncology segments. Cook Medical sits within the specialized vascular access tier, anchoring competitive positioning through minimally invasive technology focus. These three represent distinct strategic postures rather than exhaustive market coverage, with each archetype commanding different procurement committee access points across hospital, outpatient clinic, and ambulatory surgical center channels.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Cook Medical |
| Becton, Dickinson and Company |
| Vygon |
| Medtronic |
| Teleflex Incorporated |
| AngioDynamics |
| ICU Medical |
| Smiths Medical |
| Others |
Cost & Logistics Intelligence
Oncology procurement committees in Philadelphia and Cleveland academic medical centers now mandate 5-year implant duration guarantees, forcing manufacturers to absorb extended warranty costs and recalibrate pricing models around total cost-of-ownership rather than upfront device transaction value.
Pricing Analysis
Distributor margin compression runs through the US hospital supply chain as group purchasing organizations consolidate procurement volume and demand transparent cost-plus pricing. Three-tier pricing structure across premium titanium-silicone systems, standard polyurethane configurations, and economy PVC alternatives reflects ISO 10993 certification tier and dwell-time specification differentiation. Pricing pressure stems from Medicare's site-of-care reimbursement parity between hospital outpatient and ambulatory surgical center settings, compressing facility fee allocations available for device procurement. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize clinical outcome metrics over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Germany and the United States maintain hub-and-spoke patterns serving Western European and North American hospital networks with 48-hour replenishment cycles. Medical-grade titanium sponge supply draws from Chinese and Russian smelting operations, silicone polymer production concentrates in Germany and Japan, and polyurethane resin manufacturing anchors in the United States and Belgium. Single-source vulnerability in titanium raw material exposure creates geopolitical risk amplification for device body fabrication. Distribution runs through specialized medical device distributors with cold-chain and sterile handling capabilities rather than general industrial logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The implantable port market functions as a stable compounder anchored by irreversible oncology protocol standardization that embeds vascular access devices into multi-year treatment pathways with predictable replacement cycles.
For Market Incumbents: Extend fluoroscopy-guided placement service contracts into ambulatory surgical center channels to capture site-of-care migration volume before competitors establish GPO relationships. Deepen backward integration into medical-grade titanium sponge sourcing through long-term offtake agreements with German and Japanese alloy suppliers to insulate against Chinese supply disruption. Lock in silicone polymer supply through captive arrangements with Bavarian chemical manufacturers facing EU MDR compliance cost inflation that will squeeze smaller competitors. For New Entrants and Emerging Players: Begin with pediatric polyurethane thin-wall designs where kink-resistant low-profile geometries remain underdeveloped and procurement specifications lack entrenched incumbent relationships. Target Maharashtra and Karnataka private hospital networks in India where CDSCO streamlined Class C pathways reduce regulatory friction for established US and EU manufacturers. Pursue direct hospital contracting bypassing distributor markup layers to compensate for lack of legacy GPO access. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized vascular access manufacturers possessing fluoroscopy-guided placement expertise and interventional radiology specialist sales force access rather than diversified conglomerates with diluted channel focus. The 5-10 year viability window favors targets with EU MDR Article 10 clinical evaluation dossiers already approved by German notified bodies, eliminating regulatory timeline risk. Monitor CMS reimbursement code revisions for ambulatory surgical center placement procedures as the critical inflection signal determining volume allocation between hospital and freestanding settings.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks Bavarian and Paris hospital procurement committee access. |
| Hospital System Partnership | Integrated delivery network contracts secure interventional radiology suite placement volume. |
| Software Companion Development | Pressure-sensing telemetry integration enables real-time flow obstruction detection services. |
| Reimbursement Strategy | Medicare ASC payment parity alignment redirects volume toward lower-cost procedural venues. |
| Backward Integration | Captive titanium sponge sourcing insulates against Chinese and Russian supply volatility. |
Research Approach
Bottom-up oncology infusion protocol modeling reconciled against top-down vascular access device supply tracking forms the analytical core of this study. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility test registries. Triangulation across clinician-reported implant duration data and manufacturer shipment records ensures volume reconciliation.
Historical trendline analysis of implantable port utilization rates by oncology treatment center type established baseline penetration patterns across the projection horizon. Segmentation modeling incorporated product type, material composition, end-user facility category, and procedural venue economics as dimensional drivers. CAGRs were derived from weighted average of protocol-driven replacement cycle assumptions and site-of-care migration elasticity parameters. Forecast inputs included fluoroscopy suite capacity expansion trajectories and EU MDR compliance cost pass-through coefficients.
Several conditions sit outside the modeled scope, including unforeseen regulatory revocation of predicate device pathways, abrupt titanium export restrictions, and pandemic-related interventional radiology staffing shortages. Forecasts reflect documented assumptions regarding reimbursement stability and material biocompatibility standard continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stimulation Therapies Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Medical Electrodes Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Single-Use Assemblies Market