
 Positive Air Pressure Devices Market | 2026-2036
Positive Air Pressure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Air Pressure Devices Market Analysis
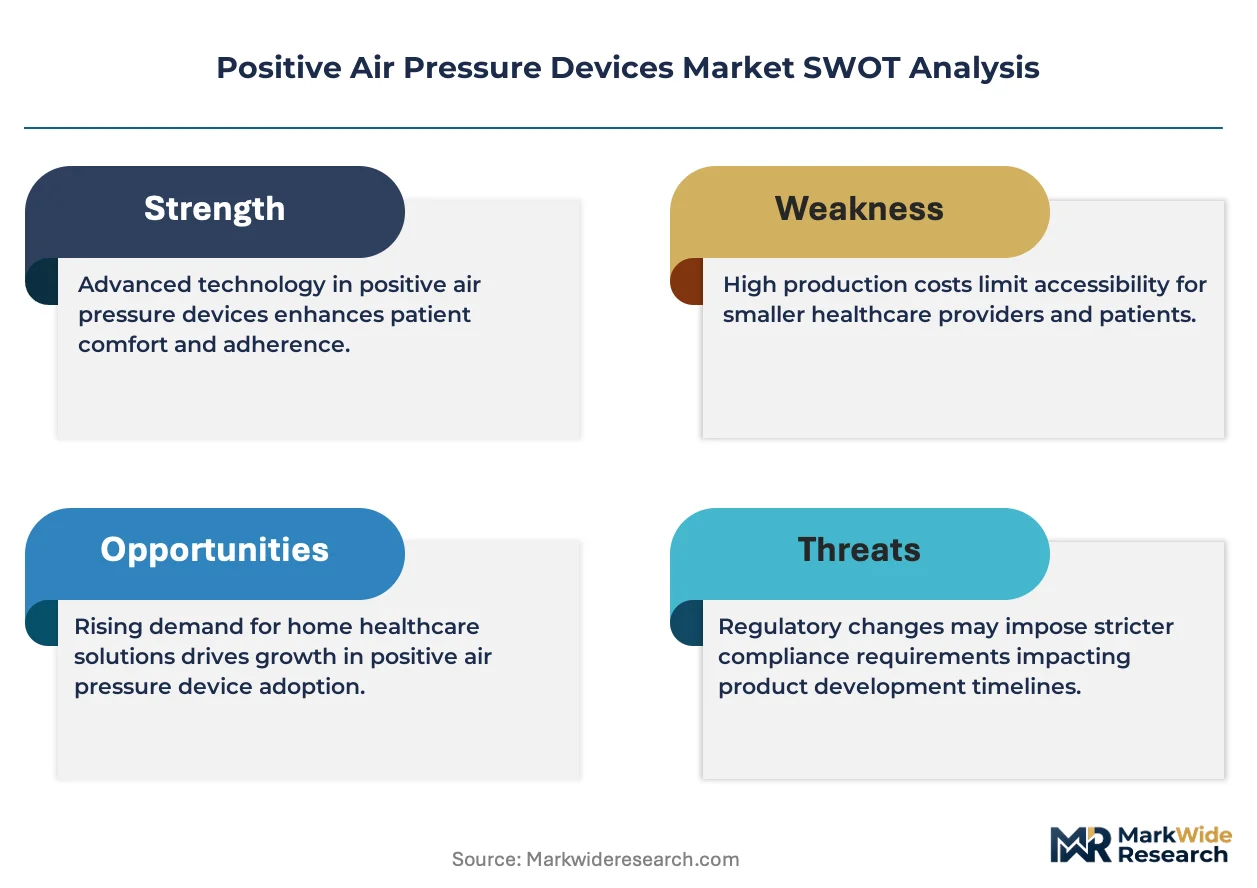
ISO 80601-2-70 certification for sleep apnea breathing equipment is unwinding competitive access across the positive air pressure devices sector, forcing manufacturers to recalibrate quality management systems before commercial entry. ResMed Inc leverages its vertically integrated cloud-connected platform to sustain recurring revenue streams beyond hardware sales. Koninklijke Philips N.V. anchors its position through hospital procurement networks spanning North American and European acute care facilities. Fisher & Paykel Healthcare Limited differentiates via humidification technology integration that reduces airway dryness complications in long-term home therapy.
Positive air pressure devices generate mechanically assisted airflow at calibrated pressures between 4 and 20 cm H₂O to maintain patent upper airways during sleep or respiratory insufficiency, typically incorporating blower motors, humidification chambers, and mask interfaces in sealed systems. CPAP machines occupy the mature volume base with compressed margin structures, while auto-adjusting pressure technology commands premium positioning through real-time apnea-hypopnea index responsiveness. BiPAP machines concentrate margin pools in COPD and neuromuscular indication subsets where dual-pressure cycling proves clinically necessary.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation's Class IIa classification requirements shape design control documentation and clinical evaluation obligations for market authorization. ISO 80601-2-70 electrical safety standards and HIPAA data transmission protocols govern software-enabled remote monitoring features that manufacturers increasingly embed. Stakeholders must weigh reimbursement policy shifts against direct-to-consumer channel expansion as payor constraints tighten across Medicare and national health service programs.
Market Dynamics
Cloud-connected remote monitoring capabilities are restructuring competitive economics in the positive air pressure devices sector, transforming hardware vendors into recurring-revenue service platforms while tightening data security compliance burdens under HIPAA and GDPR frameworks.
Growth Catalysts
- ISO 80601-2-70 certification mandates:Electrical safety standardization for sleep apnea breathing equipment is accelerating quality system investments among manufacturers seeking commercial access across regulated markets.
- Germany's homecare respiratory services network:Dense reimbursement infrastructure for long-term therapy devices sustains patient acquisition pipelines and durable equipment supplier relationships.
- Auto-adjusting pressure algorithms:Real-time apnea-hypopnea index responsiveness technology commands premium positioning and extends replacement cycles through software-enabled feature upgrades.
Market Restraints
- Motor and blower component concentration:Precision pneumatic subassembly sourcing clusters among East Asian contract manufacturers, exposing supply continuity risks during trade policy fluctuations.
- BiPAP machine technical limitations:Dual-pressure cycling systems require specialized clinical training for titration, constraining deployment velocity outside pulmonologist-supervised settings.
- FDA 510(k) clearance timelines:Premarket notification documentation requirements for continuous positive airway pressure systems extend product entry schedules by 12-18 months.
Strategic Opportunities
- Direct-to-consumer channel expansion:Sleep clinic bypass models are capturing cash-pay patients outside Medicare reimbursement constraints, particularly in urban US markets.
- Humidification technology convergence:Integration of heated humidification chambers with mask interfaces reduces airway dryness complications and differentiates long-term home therapy offerings.
- EU Medical Device Regulation Class IIa pathway:Streamlined conformity assessment procedures for software-enabled remote monitoring features create first-mover advantages for cloud-platform vendors.
Industry Challenges
- Clinical respiratory therapist talent scarcity:Specialized titration expertise for complex COPD and neuromuscular indications limits patient onboarding capacity at sleep centers.
- HIPAA data transmission protocol compliance:Encryption and audit-trail requirements for cloud-connected devices impose ongoing software maintenance costs and liability exposure.
- Legacy mask interface standardization gaps:Proprietary connector designs across manufacturer ecosystems fragment accessory markets and complicate patient switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Air Pressure Devices Market |
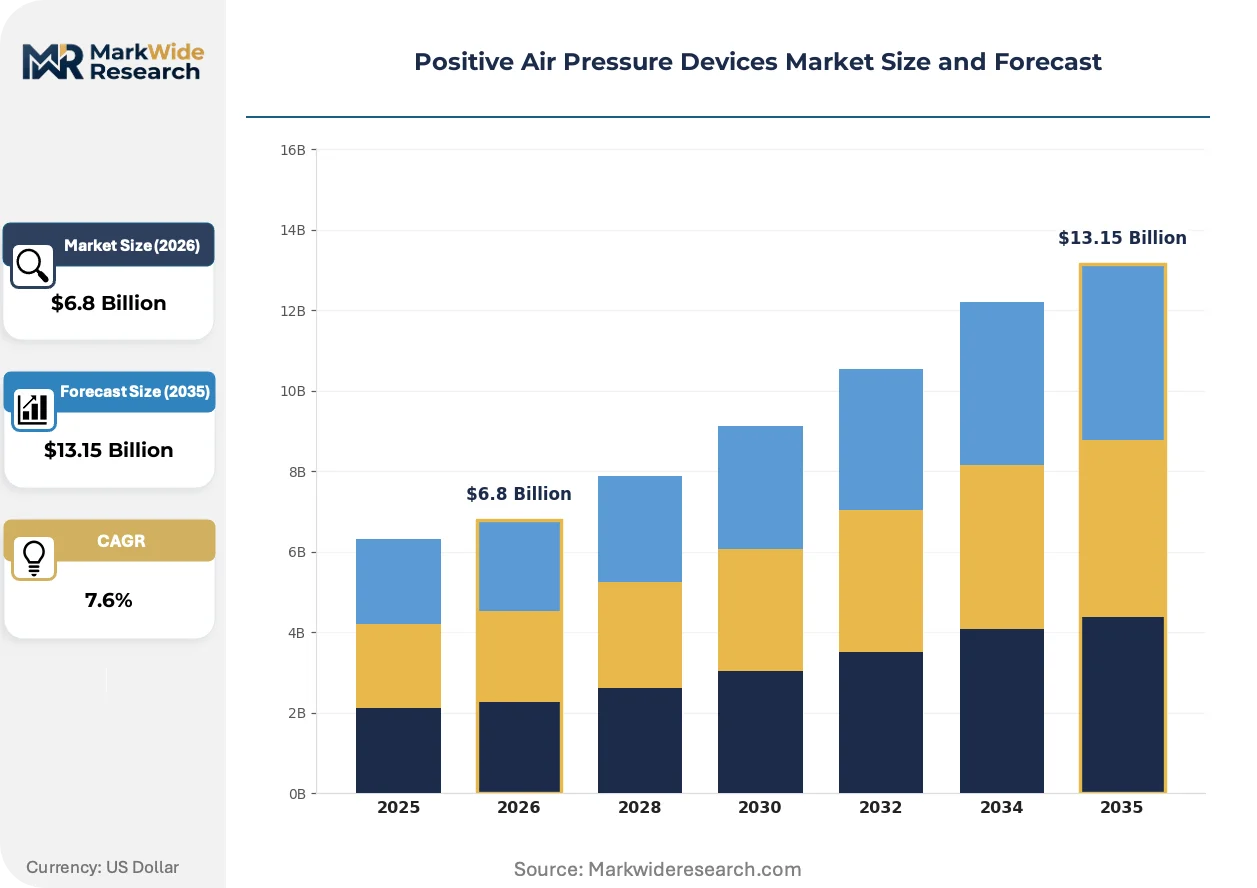
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPAP Machines, BiPAP Machines, APAP Machines, Ventilators End User: Hospitals, Homecare, Sleep Clinics, Rehabilitation Centers Application: Sleep Apnea, COPD, Asthma, Acute Respiratory Distress Technology: Auto-Adjusting Pressure, Humidification, Data Monitoring, Wireless Connectivity |
| Companies Covered | ResMed Inc, Koninklijke Philips N.V., Fisher & Paykel Healthcare Limited, Smiths Group Plc, React Health, Wellell Inc., BMC Medical Co. Ltd., Breas Medical AB, Drive DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Air Pressure Devices Market Emerging Trajectories
Software-defined functionality is displacing hardware-centric business models across the positive air pressure devices landscape, with algorithmic pressure adjustment and remote compliance monitoring becoming primary value drivers rather than mechanical reliability alone.
Auto-adjusting pressure technology is displacing fixed-pressure CPAP systems in new patient prescriptions. Sleep clinics in the United States and Germany are prioritizing devices with real-time respiratory event detection. This displacement is compressing margin structures for basic CPAP hardware while expanding recurring revenue pools through cloud-based therapy management subscriptions.
The EU Medical Device Regulation's Class IIa classification requirements are reshaping clinical evaluation obligations for software-enabled devices. Manufacturers must now submit design control documentation and post-market surveillance data for algorithm updates. North American vendors with established FDA 510(k) quality systems are adapting EU MDR technical file requirements to maintain parallel market access.
Patients are initiating therapy journeys through direct-to-consumer channels before clinical diagnosis. Online sleep assessment platforms and home sleep testing kits are bypassing traditional polysomnography referral pathways. This behavioral shift concentrates in US metropolitan markets where high-deductible health plans increase price sensitivity for initial device acquisition.
Positive Air Pressure Devices Market Segmentation
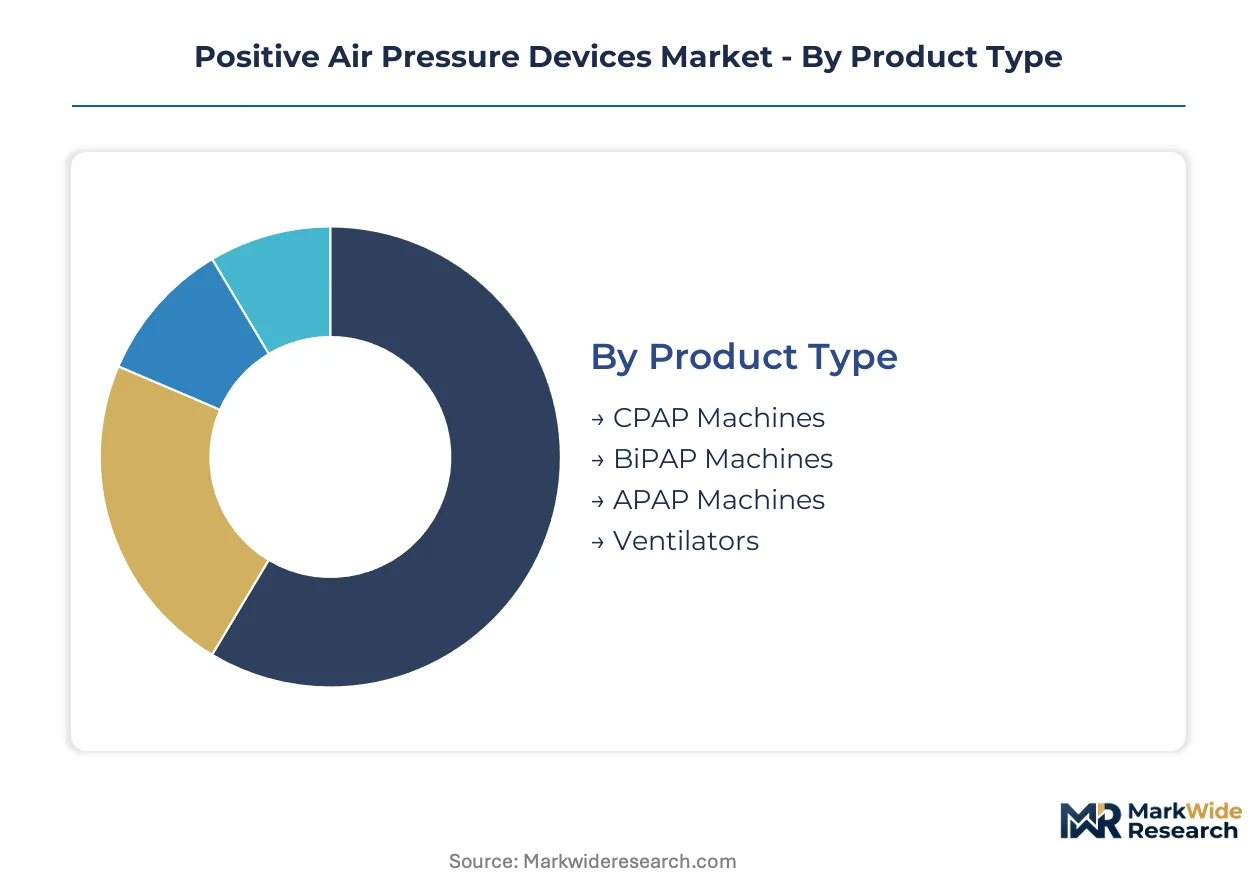
Channel configuration varies sharply across positive air pressure device categories. CPAP hardware flows predominantly through durable medical equipment suppliers under Medicare reimbursement, while auto-adjusting systems increasingly reach patients via direct-to-consumer platforms bypassing traditional sleep clinic referral pathways.
Product Type:
Channel-mix patterns diverge significantly: CPAP machines concentrate in homecare supplier networks, while BiPAP systems remain tethered to hospital procurement and pulmonologist-supervised dispensing.
- CPAP Machines:Fixed-pressure systems deliver continuous airflow between 4-20 cm H₂O through sealed mask interfaces. Germany's dense homecare respiratory services network sustains the highest per-capita penetration rates for these devices. Margin compression intensifies as basic hardware commoditizes.
- BiPAP Machines:Dual-pressure cycling systems alternate inspiratory and expiratory pressures for COPD and neuromuscular indications. Hospital procurement networks spanning North American acute care facilities anchor demand. Specialized clinical training requirements constrain deployment velocity outside supervised settings.
- APAP Machines:Real-time apnea-hypopnea index responsiveness commands premium positioning through algorithmic pressure modulation.
- Ventilators:Invasive and non-invasive critical care systems serve acute respiratory failure in intensive care unit environments.
By volume, CPAP machines lead. By growth pace, APAP systems are climbing the fastest.
End User:
Cost-tier stratification separates capital-intensive hospital purchases from recurring homecare rentals and cash-pay sleep clinic transactions.
- Hospitals:Acute care facilities procure ventilators and BiPAP systems through group purchasing organizations. North American health system consolidation is tightening vendor qualification requirements.
- Homecare:Long-term therapy device provisioning concentrates in Germany's reimbursement-integrated supplier networks. Patient compliance monitoring via cloud-connected platforms is reshaping service economics.
- Sleep Clinics:Diagnostic and titration centers are expanding device procurement programs for APAP-first prescribing protocols.
- Rehabilitation Centers:Post-acute respiratory therapy facilities manage weaning protocols for ventilator-dependent patients.
Homecare channels dominate unit volume. Sleep clinics are gaining share fastest in premium device categories.
Application:
Application-specific demand correlates with reimbursement policy density and diagnostic pathway maturity across regulated markets.
- Sleep Apnea:Obstructive sleep apnea represents the primary indication driving CPAP and APAP prescriptions. United States metropolitan markets show accelerating direct-to-consumer channel penetration as high-deductible health plans increase price sensitivity.
- COPD:Chronic obstructive pulmonary disease requires BiPAP therapy for hypercapnic respiratory failure. Pulmonologist-supervised titration limits patient onboarding capacity.
- Asthma:Acute exacerbation management occasionally employs non-invasive ventilation in emergency department settings.
- Acute Respiratory Distress:Critical care ventilation supports hypoxemic respiratory failure in intensive care unit environments.
Sleep apnea applications generate the highest unit volumes. COPD represents the steepest expansion trajectory as population aging accelerates.
Technology:
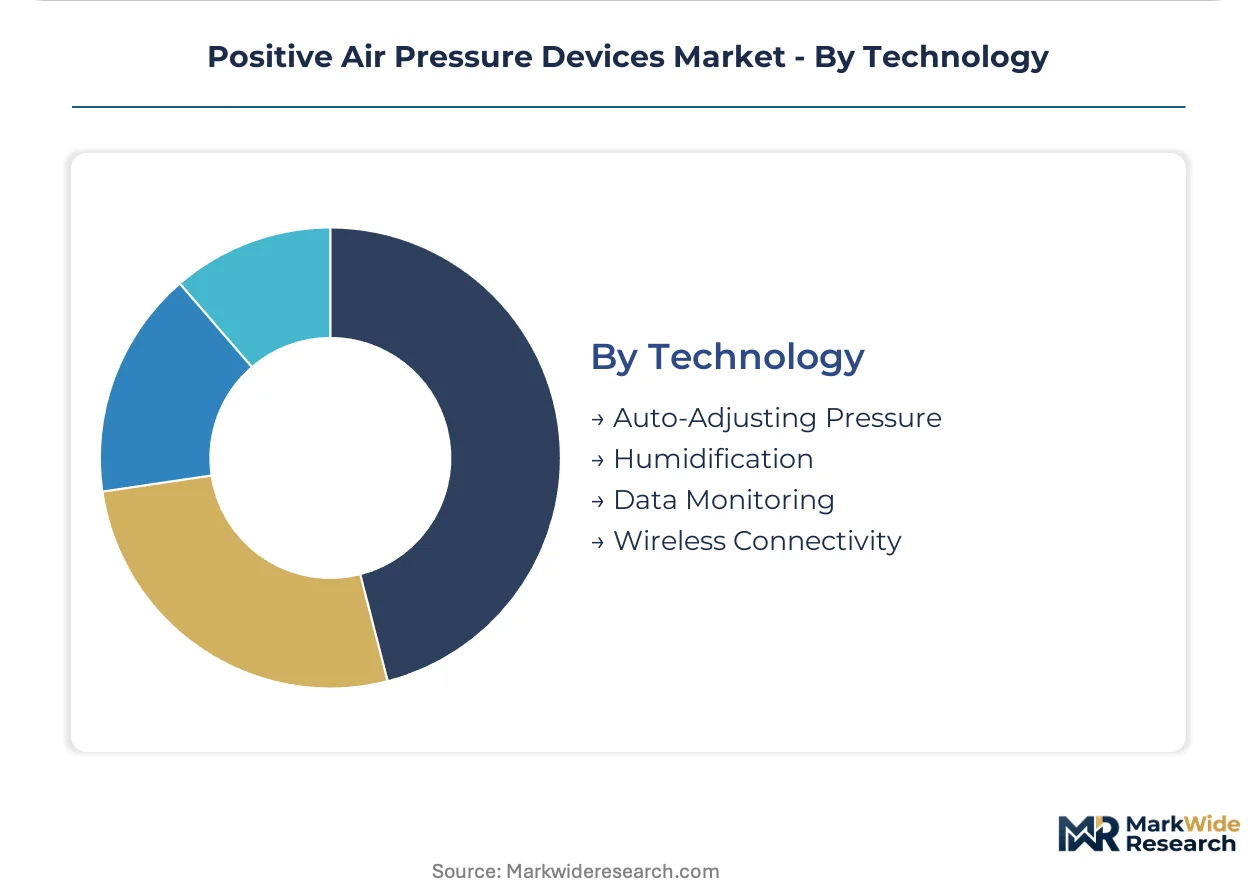
Technology tiers separate software-enabled premium offerings from mechanical baseline systems, with margin pools concentrating in algorithmic and connectivity features.
- Auto-Adjusting Pressure:Algorithmic pressure modulation responds to real-time respiratory event detection. FDA 510(k) clearance pathways for these systems extend product entry schedules by 12-18 months.
- Humidification:Heated humidification chambers integrated with mask interfaces reduce airway dryness complications. Fisher & Paykel Healthcare anchors positioning through this technology convergence.
- Data Monitoring:Cloud-connected remote compliance tracking enables therapy management subscriptions. HIPAA data transmission protocols impose ongoing software maintenance burdens.
- Wireless Connectivity:Cellular and Bluetooth-enabled device communication supports over-the-air algorithm updates and patient engagement platforms.
Auto-adjusting pressure systems command the highest average selling prices. Data monitoring capabilities are expanding most quickly as vendors pursue recurring revenue transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sleep clinics and homecare respiratory networks concentrate device procurement decisions across distinct national reimbursement environments. Germany's dense supplier infrastructure, the United States' direct-to-consumer channel expansion, and Japan's aging demographic profile each shape regional demand patterns differently.
United States
Sleep clinics in metropolitan markets are bypassing traditional durable medical equipment suppliers through direct-to-consumer platforms targeting cash-pay patients. The FDA's 510(k) premarket notification framework extends product entry timelines by 12-18 months for continuous positive airway pressure systems. The Southeast corridor from Florida through Georgia anchors expansion of diagnostic and titration center networks.
Germany
Homecare respiratory services networks sustain the highest per-capita penetration rates for long-term therapy devices through reimbursement-integrated supplier relationships. The EU Medical Device Regulation's Class IIa classification requirements govern software-enabled remote monitoring features entering the market. Bavaria's medical technology cluster around Munich concentrates manufacturing and quality system certification expertise.
Japan
Aging demographics accelerate demand for COPD and neuromuscular indication subsets requiring dual-pressure cycling systems. The PMDA's pharmaceutical and medical device agency oversees clinical evaluation obligations for algorithmic pressure modulation technologies. The Kanto region surrounding Tokyo hosts the densest concentration of sleep disorder diagnostic facilities.
China
Domestic contract manufacturers cluster precision pneumatic subassemblies for global device assembly operations. The NMPA's national medical products administration regulates Class II medical device registration for imported positive air pressure systems. The Yangtze River Delta around Shanghai anchors export-oriented production of blower motors and humidification chambers.
United Kingdom
National Health Service procurement frameworks constrain patient acquisition pipelines through payor reimbursement tightening. GDPR data transmission protocols impose encryption and audit-trail requirements on cloud-connected therapy management platforms. The Southeast corridor from London through Cambridge concentrates digital health venture activity targeting remote compliance monitoring.
Positive Air Pressure Devices Market Vendor Landscape
Player mix skews toward vertically integrated platform vendors with cloud-connected recurring revenue capabilities alongside specialized component suppliers. The market structure concentrates around three to four dominant platform operators controlling hospital procurement networks and homecare supplier relationships. Two strategic archetypes prevail: full-stack therapy management platforms integrating hardware, software, and data services; and focused component specialists supplying humidification chambers, mask interfaces, or pneumatic subassemblies. Competitive moves center on M&A activity targeting remote monitoring software capabilities and strategic partnerships with sleep clinic networks for patient acquisition.
Among North American platform operators, ResMed Inc exemplifies the vertically integrated archetype through its cloud-connected ecosystem spanning devices, masks, and therapy management software. Koninklijke Philips N.V. anchors European positioning through hospital procurement networks and acute care facility relationships. Fisher & Paykel Healthcare Limited represents the component-specialist vector with focused expertise in humidification technology integration. These three entities collectively illustrate the bifurcation between full-stack platform control and targeted subsystem excellence.
| Leading Market Players |
|---|
| ResMed Inc |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare Limited |
| Smiths Group Plc |
| React Health |
| Wellell Inc. |
| BMC Medical Co. Ltd. |
| Breas Medical AB |
| Drive DeVilbiss Healthcare |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with East Asian contract manufacturers lock in blower motor and pneumatic subassembly access while anchoring cost visibility for device assemblers navigating ISO 80601-2-70 certification timelines. These arrangements insulate procurement teams from spot-market volatility in precision-machined components while compressing margin flexibility for manufacturers lacking backward integration into humidification chamber production.
Pricing Analysis
Cost-plus contracts with steel and polymer indexation govern component sourcing agreements for blower housings and mask interface materials. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected APAP systems with algorithmic pressure modulation from fixed-pressure CPAP hardware and entry-level devices without humidification. Pricing pressure stems from Medicare reimbursement tightening and direct-to-consumer channel expansion. Homecare suppliers under Medicare Part B exhibit highest price sensitivity; sleep clinics prescribing APAP-first protocols show lowest sensitivity due to clinical outcome bundling.
Supply Chain Analysis
Port congestion along the Trans-Pacific trade lane elevates inbound logistics costs for containerized shipments of precision-machined aluminum blower housings and polymer mask components. Manufacturing concentration clusters in China, Malaysia, and Vietnam for pneumatic subassemblies, with Germany and the United States hosting final device assembly and quality system certification. Critical dependencies include rare-earth magnets for motor efficiency, medical-grade silicones for mask seals, and semiconductor components for pressure sensors. Single-source vulnerability concentrates in precision-machined blower impellers. Distribution runs through durable medical equipment supplier networks in Germany and direct-to-consumer platforms in US metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Positive air pressure devices are crossing into platform-economics territory as cloud-connected therapy management subscriptions displace hardware-centric revenue models, with interoperability between device data streams and electronic health record systems becoming the decisive ecosystem battleground.
For Market Incumbents: Consolidate control over sleep clinic procurement networks through exclusive data-sharing agreements that embed remote compliance monitoring into standard-of-care protocols. Deepen backward integration into humidification chamber manufacturing to defend margin pools against component specialists. Prioritize HIPAA-compliant cloud infrastructure investments as regulatory scrutiny intensifies on cross-border patient data flows.
For New Entrants and Emerging Players: Lead with direct-to-consumer channel positioning in US metropolitan markets where high-deductible health plans drive cash-pay acquisition for initial device trials. Target the APAP segment where algorithmic differentiation commands premium positioning outside Medicare reimbursement constraints. Pursue software companion development partnerships with telehealth platforms to bypass traditional polysomnography referral bottlenecks.
For Investors and Strategic Acquirers: Cloud-native remote monitoring specialists with FDA 510(k) quality systems and established HIPAA compliance infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on recurring revenue transformation and regulatory moat depth rather than hardware shipment volumes. Watch for inflection signals in hospital procurement network consolidation and GPO contract exclusivity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Transforms hardware vendors into recurring-revenue service platforms under HIPAA data protocols. |
| FDA 510(k) Pathway Investment | Accelerates product entry timelines for auto-adjusting pressure systems by 12-18 months. |
| Humidification Technology Licensing | Differentiates long-term home therapy offerings through airway dryness complication reduction. |
| Sleep Clinic Network Partnership | Captures patient acquisition pipelines outside Medicare reimbursement constraints. |
| EU MDR Class IIa Certification | Unlocks streamlined conformity assessment for software-enabled remote monitoring features. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR technical file registries, and hospital procurement contract disclosures. Primary interviews engaged respiratory therapists at sleep clinics, biomedical engineers at durable medical equipment suppliers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from CMS Medicare claims data, ISO certification body audit records, and customs trade statistics for pneumatic component flows. Bottom-up patient flow modeling and top-down reimbursement policy analysis were triangulated against manufacturer shipment disclosures.
Segmentation dimensions modeled include product type tier, end-user channel configuration, application indication, technology feature set, and geographic regulatory cluster across the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle dynamics, and pricing trajectory assumptions. Forecast inputs incorporated sleep apnea diagnosis prevalence trends, COPD population aging curves, and direct-to-consumer channel penetration patterns.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) clearance timelines, sustained Medicare reimbursement rates, and intact EU MDR transition schedules would require recalibration. Forecasts reflect documented assumptions regarding cloud platform adoption velocity and sleep clinic network consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Indonesia Devices Market
Medical Devices
Telehealth Device Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Thrombectomy System Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Liposuction Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Inversion Table Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Distal Embolic Filters Market