
 High Intensity Focused Ultrasound (HIFU) Market | 2026-2036
High Intensity Focused Ultrasound (HIFU) Market Size, Share, and Industry Trends Forecast 2026-2036
High Intensity Focused Ultrasound (HIFU) Market Foresight
China's therapeutic device manufacturers is pivoting toward integrated image-guided platforms for oncologic applications. Insightec Ltd. leverages magnetic resonance thermometry to sustain technology leadership in neurosurgical ablation. EDAP TMS anchors its competitive position through dedicated urology specialization, while Chongqing Haifu Medical Technology dominates domestic installation bases across tier-one hospitals.
High Intensity Focused Ultrasound directs acoustic energy to focal tissue volumes, achieving thermal coagulation at temperatures exceeding 56°C without intermediate tissue damage. Therapeutic devices command the largest revenue share as hospitals prioritize capital equipment for tumor ablation and symptomatic tissue reduction. Image-guided technology leads growth trajectories, with robotic-assisted systems gaining traction in precision-dependent gynecologic and urologic procedures where real-time monitoring reduces complication rates.
FDA premarket approval pathways and the EU MDR conformity assessment process shape product development cycles and geographic launch sequencing for manufacturers. China's NMPA innovation review channels and Japan's PMDA orphan medical device designation create parallel regulatory incentives for oncologic indications. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies, as coverage determinations increasingly determine commercial viability ahead of regulatory clearance alone.
Market Dynamics
Magnetic resonance thermometry integration is compressing procedure times and expanding treatable indications beyond established urology and oncology segments into neurosurgical and gynecologic applications.
Growth Catalysts
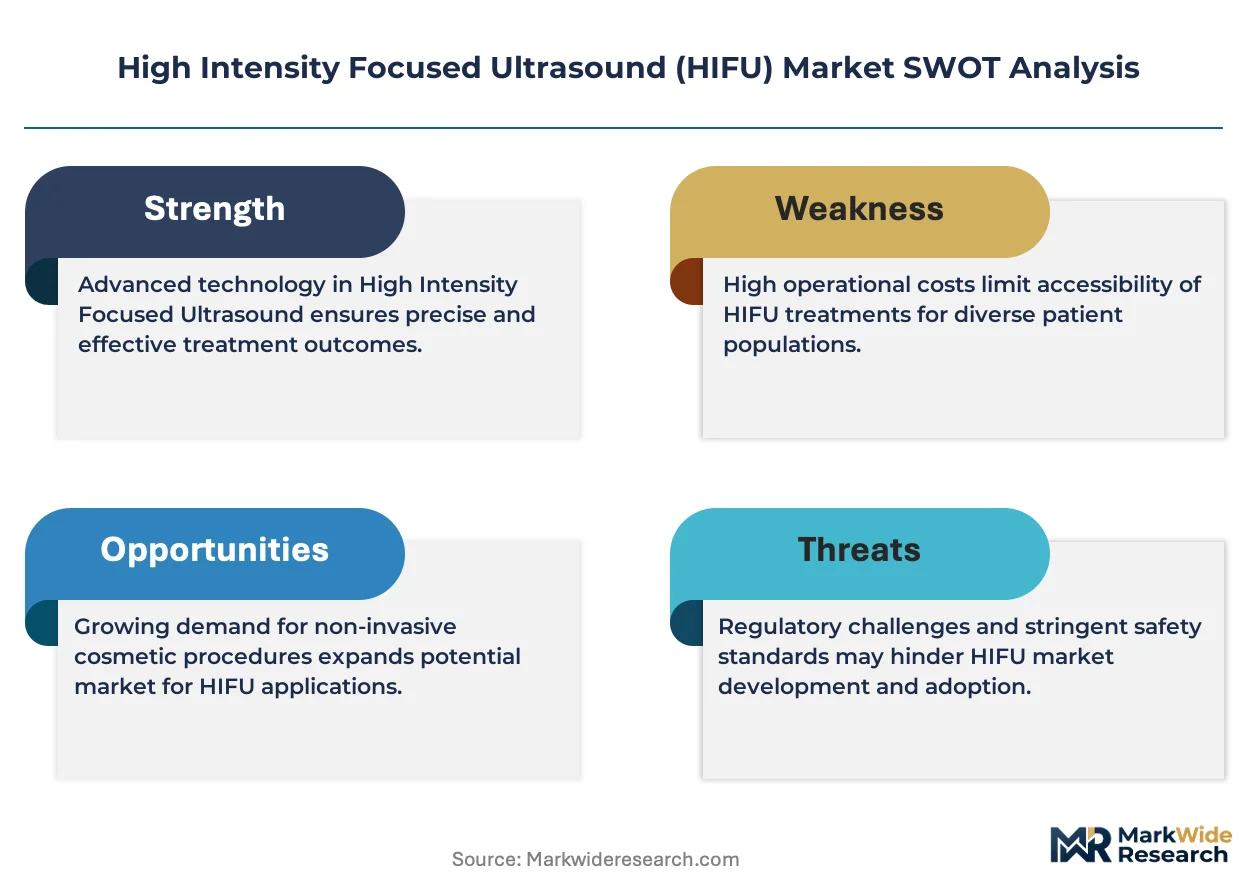
- FDA Breakthrough Device Pathway:Expedited review timelines for next-generation HIFU systems with enhanced imaging guidance are compressing commercialization cycles for manufacturers targeting prostate and liver tumor ablation.
- China's tier-one hospital expansion:Domestic installation bases across Beijing, Shanghai, and Guangzhou are multiplying as NMPA innovation review channels accelerate oncologic device approvals.
- Real-time monitoring protocols:Robotic-assisted surgical systems with integrated acoustic energy delivery are reducing complication rates in precision-dependent procedures.
Market Restraints
- Capital equipment intensity:Multi-million dollar system costs and dedicated facility requirements limit adoption to academic medical centers and large hospital networks with dedicated ablation programs.
- Reimbursement lag:CMS national coverage determinations and parallel health technology assessment processes in Germany and France create 18-36 month gaps between regulatory clearance and commercial viability.
- Technical limitation in bone-proximate targets:Acoustic shadowing from osseous structures restricts treatable anatomies, excluding spinal metastases and skull-base lesions from current protocols.
Strategic Opportunities
- India's underserved oncology infrastructure:CDSCO streamlined pathways for orphan oncologic devices and rising prostate cancer incidence create first-mover potential in Mumbai and Delhi hospital networks.
- EU MDR Article 54 clinical evidence incentives:Post-market surveillance data requirements for CE-marked ablation systems reward manufacturers with robust real-world evidence generation capabilities.
- Hybrid MRI-ultrasound convergence:Integration of magnetic resonance guidance with focused ultrasound delivery is opening movement disorder applications previously restricted to deep brain stimulation.
Industry Challenges
- Specialized sonographer training pipelines:Thermal dose planning and real-time thermometry interpretation require 12-18 month certification programs that hospital systems struggle to staff.
- Legacy PACS integration friction:Proprietary imaging formats from HIFU manufacturers create interoperability barriers with existing radiology infrastructure, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Intensity Focused Ultrasound (HIFU) Market |
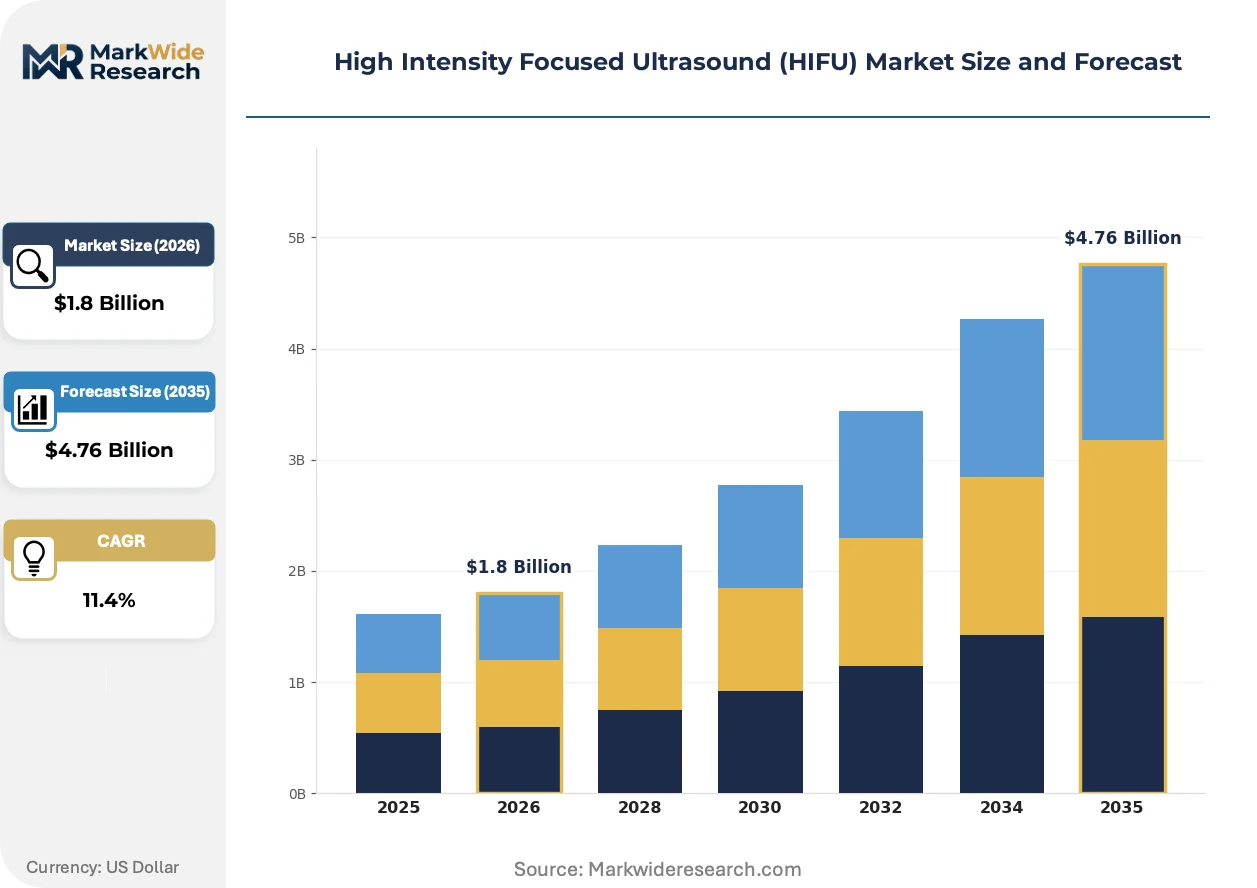
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Devices, Diagnostic Equipment, Research Instruments, Surgical Tools Application: Oncology, Urology, Gynecology, Aesthetic Treatments End User: Hospitals, Research Labs, Outpatient Clinics, Specialty Centers Technology: Image-Guided, Robotic-Assisted, Portable Systems, Conventional Systems |
| Companies Covered | Insightec Ltd., EDAP TMS, Chongqing Haifu Medical Technology, Koninklijke Philips N.V., Profound Medical, Theraclion, Alpinion Medical Systems, SonaCare Medical, Verasonics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Intensity Focused Ultrasound (HIFU) Market Shifts & Advancements
Image-guided ablation platforms are displacing conventional surgical resection in localized tumor management, with therapeutic ultrasound systems capturing procedural volume across multiple organ systems.
Phased-array transducer technology is rewriting the spatial precision of focal energy delivery. Academic medical centers in the United States and Germany are adopting these systems for uterine fibroid and prostate applications. The technology is compressing margins between treatable and adjacent tissue, enabling same-day discharge protocols that displace inpatient surgical stays.
EU MDR conformity assessment timelines are restructuring product launch sequencing for manufacturers. The notified body capacity crunch and enhanced clinical evidence requirements for Class III devices are forcing prioritization of European markets with established reimbursement. German hospital procurement consortia are responding with bundled purchasing agreements that favor systems with existing CE marking over pre-approval commitments.
Hospital capital acquisition committees are unbundling equipment procurement from service contracts. Large health systems in China and the United States are negotiating direct maintenance arrangements with third-party clinical engineers, displacing manufacturer-captive service models. This pattern is most visible in tier-one Chinese cities where domestic manufacturers compete aggressively on total cost of ownership.
High Intensity Focused Ultrasound (HIFU) Market Segmentation
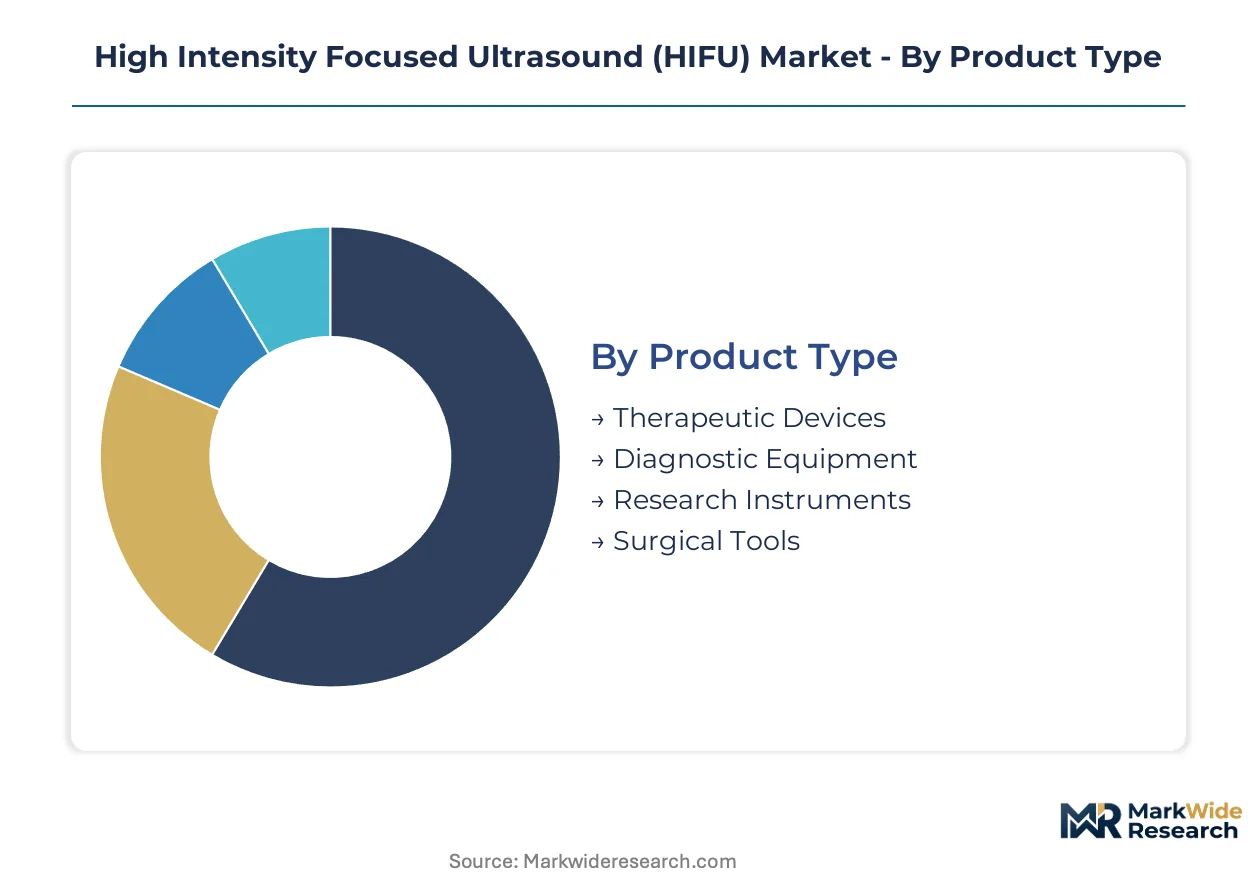
HIFU market segmentation reveals distinct procurement patterns across clinical settings. Technology integration levels and reimbursement pathways create divergent commercial trajectories for manufacturers targeting hospital networks versus outpatient operators.
Product Type:
Capital allocation priorities separate academic medical centers from community hospital purchasers in this category.
- Therapeutic Devices:These systems integrate high-power transducer arrays with real-time thermometry for tumor ablation and tissue reduction. Major hospital networks in the United States and Germany prioritize these platforms for prostate and liver oncology programs, though multi-million dollar price points restrict procurement to tier-one institutions with dedicated ablation centers.
- Diagnostic Equipment:Pre-treatment imaging and post-procedure monitoring systems enable treatment planning and efficacy assessment. Demand concentrates in China's tier-one cities where NMPA innovation review channels accelerate oncologic device approvals, with domestic manufacturers competing aggressively on total cost of ownership.
- Research Instruments:Laboratory-grade systems for preclinical studies and protocol development.
- Surgical Tools:Disposable and reusable accessories for energy delivery and tissue interaction.
Volume sits with Therapeutic Devices; growth tilts toward Diagnostic Equipment.
Application:
Reimbursement coding maturity determines addressable market size for each clinical indication.
- Oncology:Tumor ablation for prostate, liver, and pancreatic malignancies represents the most clinically validated application. FDA breakthrough device designations and CE marking pathways under EU MDR are accelerating commercial timelines for next-generation systems targeting solid tumors.
- Urology:Benign prostatic hyperplasia and prostate cancer applications command established procedural volumes. Academic medical centers in Germany and the United States deploy these systems for same-day discharge protocols that displace inpatient surgical stays.
- Gynecology:Uterine fibroid ablation and adenomyosis treatment.
- Aesthetic Treatments:Non-invasive skin tightening and body contouring applications.
Procedure volume concentrates in Urology; steepest expansion trajectory belongs to Oncology.
End User:
Facility infrastructure requirements and staffing capabilities segment the customer base.
- Hospitals:Integrated health systems with MRI suites and specialized sonographer training pipelines. China's tier-one hospital expansion multiplies domestic installation bases across Beijing, Shanghai, and Guangzhou as capital acquisition committees unbundle equipment procurement from service contracts.
- Specialty Centers:Dedicated urology and oncology clinics with focused procedural expertise. These operators in the United States negotiate direct maintenance arrangements with third-party clinical engineers, displacing manufacturer-captive service models.
- Research Labs:Academic and commercial research facilities.
- Outpatient Clinics:Ambulatory settings with limited imaging infrastructure.
Revenue concentrates with Hospitals; share gains flow fastest to Specialty Centers.
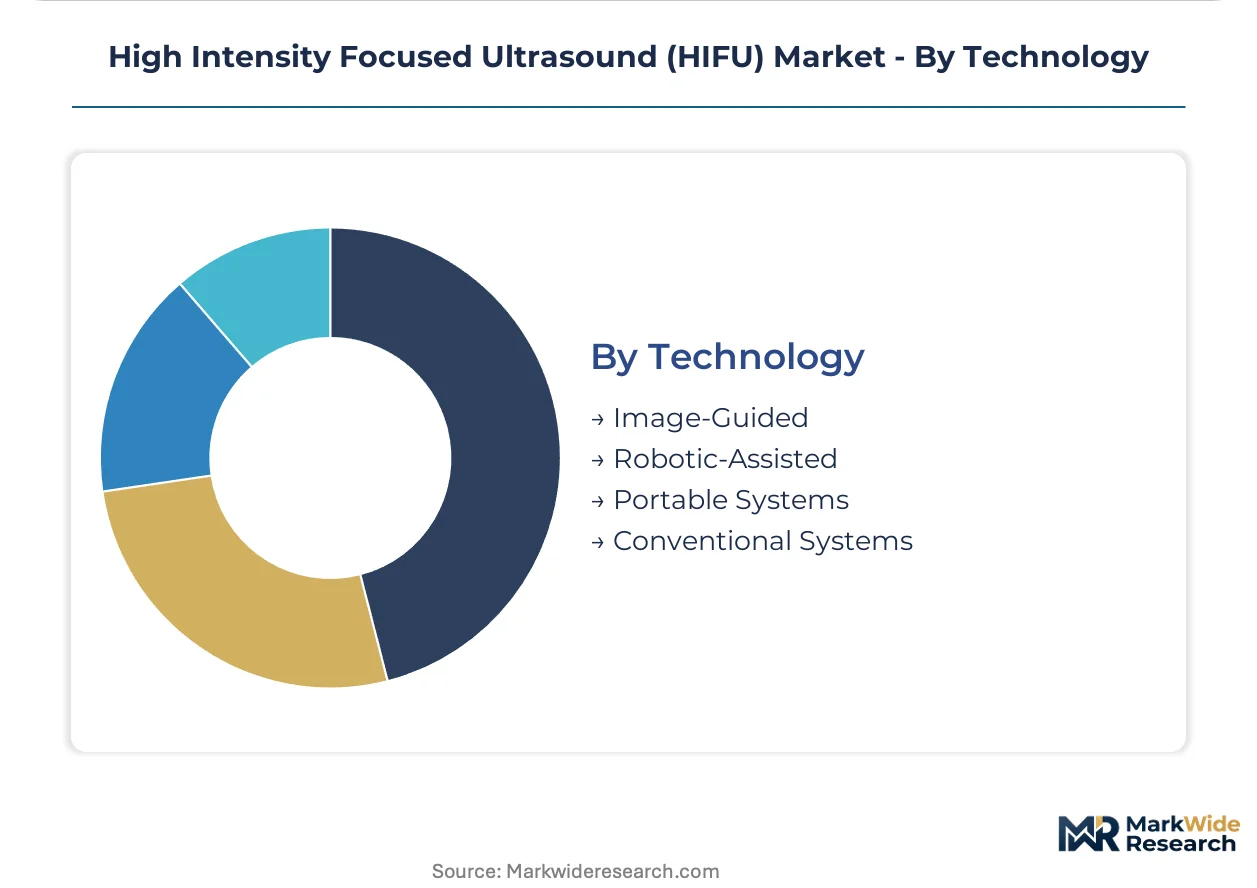
Technology:
Imaging integration depth separates premium platforms from commodity alternatives.
- Image-Guided:Magnetic resonance thermometry and ultrasound fusion enable real-time monitoring. Phased-array transducer technology is rewriting spatial precision of focal energy delivery, compressing margins between treatable and adjacent tissue in uterine fibroid and prostate applications.
- Robotic-Assisted:Automated positioning and energy delivery reduce operator variability. These systems gain traction in precision-dependent gynecologic and urologic procedures where real-time monitoring reduces complication rates.
- Portable Systems:Compact configurations for point-of-care deployment.
- Conventional Systems:Non-guided platforms with established cost structures.
Installed base tilts toward Conventional Systems; technology migration favors Image-Guided platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic transducer manufacturing clusters in Shenzhen and Dongguan supply precision components to HIFU system integrators worldwide, anchoring Asia-Pacific production networks while FDA-cleared platforms concentrate in Boston and Minneapolis medical technology corridors.
United States
Academic medical centers at Johns Hopkins, Mayo Clinic, and MD Anderson drive procedural volume for prostate and liver tumor ablation. FDA breakthrough device designations compress review timelines for next-generation image-guided systems. The Minneapolis-St. Paul corridor hosts concentrated device engineering talent pools serving major hospital networks.
Germany
University hospitals in Heidelberg, Munich, and Berlin anchor European clinical evidence generation for oncologic applications. CE marking pathways under EU MDR impose enhanced clinical evidence requirements that favor established manufacturers with robust post-market surveillance capabilities. The Baden-Württemberg medical technology cluster integrates precision manufacturing with radiology infrastructure.
China
Tier-one hospitals in Beijing, Shanghai, and Guangzhou multiply installation bases as NMPA innovation review channels accelerate oncologic device approvals. Domestic manufacturers compete aggressively on total cost of ownership while capital acquisition committees unbundle equipment procurement from service contracts. Chongqing anchors therapeutic ultrasound research programs.
Japan
Specialized cancer centers in Tokyo, Osaka, and Nagoya deploy HIFU systems for liver and pancreatic malignancies. PMDA orphan medical device designation creates regulatory incentives for movement disorder applications previously restricted to deep brain stimulation. The Kansai region concentrates biomedical engineering expertise for thermometry integration.
India
Rising prostate cancer incidence across Mumbai and Delhi hospital networks creates first-mover potential for CDSCO-streamlined orphan oncologic devices. Limited reimbursement infrastructure constrains commercial viability to cash-pay segments and corporate hospital chains. Apollo and Max Healthcare systems pilot ablation programs for uterine fibroid applications.
High Intensity Focused Ultrasound (HIFU) Market Competitive Landscape
Global majors compete with regional champions across imaging integration depth and regulatory clearance breadth. The vendor base stratifies between MRI-thermometry leaders, dedicated urology specialists, and domestic Chinese manufacturers with tier-one hospital installation density. Three archetypes dominate: integrated platform developers with multi-indication portfolios, single-specialty pure-plays with deep clinical evidence, and cost-optimized regional suppliers. Competitive moves concentrate on M&A for imaging technology assets and strategic partnerships for reimbursement pathway acceleration.
Within the integrated platform tier, Insightec Ltd. and Koninklijke Philips N.V. exemplify magnetic resonance guidance capabilities. EDAP TMS occupies a position as the dedicated urology specialist archetype. Chongqing Haifu Medical Technology anchors the domestic Chinese manufacturer segment with concentrated tier-one hospital presence.
| Leading Market Players |
|---|
| Insightec Ltd. |
| EDAP TMS |
| Chongqing Haifu Medical Technology |
| Koninklijke Philips N.V. |
| Profound Medical |
| Theraclion |
| Alpinion Medical Systems |
| SonaCare Medical |
| Verasonics, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up imaging specialists and sovereign-backed Chinese manufacturers anchor supply-side concentration, translating tier-one hospital procurement leverage into aggressive unbundling of service contracts from equipment sales. This ownership pattern compresses pricing discipline across therapeutic device tiers while feeding backward integration into acoustic transducer production.
Pricing Analysis
Warranty and multi-year service bundling separates premium MRI-thermometry platforms from unbundled domestic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, CE marking under EU MDR, and proprietary imaging format lock-in. Cost compression in mid-tier systems intensifies as Chinese manufacturers compete on total cost of ownership. Academic medical centers in Germany and the United States show least price sensitivity; outpatient clinics in India face acute budget constraints.
Supply Chain Analysis
Biomedical engineering talent scarcity in Shenzhen and Dongguan constrains phased-array transducer output despite precision manufacturing infrastructure. Component supply draws from China's NMPA-regulated facilities, Germany's Baden-Württemberg cluster, and Japan's Kansai thermometry specialists. Piezoelectric ceramics, MRI-compatible materials, and robotic positioning modules constitute critical inputs. Single-source vulnerability runs through acoustic transducer suppliers. Distribution runs through hospital procurement consortia and direct manufacturer relationships with tier-one health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timelines and NMPA innovation review channel bottlenecks are forcing capital-constrained manufacturers toward distressed exits, consolidating competitive position among imaging-integrated platform developers.
For Market Incumbents: Lock in proprietary MRI-thermometry protocols through exclusive hospital system partnerships before CE marking pathways mature for second-generation competitors. Acquire distressed sonographer training pipelines to control staffing bottlenecks. Prioritize reimbursement strategy investment over regulatory clearance alone, as CMS national coverage determinations increasingly gate commercial viability. For New Entrants and Emerging Players: Third-party clinical engineering service providers offer channel access without manufacturer-captive relationships. India's CDSCO-streamlined orphan oncologic device pathway presents the most penetrable geography, with rising prostate cancer incidence across Mumbai and Delhi hospital networks. Target hybrid MRI-ultrasound convergence for movement disorder applications as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor imaging-technology asset specialists in China's tier-one cities facing NMPA approval backlogs. Long-term viability centers on real-world evidence generation capabilities rewarded under EU MDR Article 54 post-market surveillance requirements. Watch FDA breakthrough device designation velocity as the inflection signal for platform-tier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body capacity crunch forces prioritization of established reimbursement markets. |
| Hospital System Partnership | Academic medical centers at Johns Hopkins and Mayo Clinic anchor clinical evidence generation for prostate ablation. |
| Reimbursement Strategy | CMS national coverage determinations create 18-36 month gaps between FDA clearance and commercial viability. |
| Software Companion Development | Real-time thermometry interpretation modules reduce 12-18 month sonographer certification burdens. |
| FDA Submission | Breakthrough device designation compresses review timelines for image-guided neurosurgical applications. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) and PMA filings, NMPA innovation review disclosures, EU MDR notified body assignment records, and hospital procurement database extracts. Bottom-up installation base modeling triangulates against top-down therapeutic device revenue estimates across the analysis window.
Rate-of-change decomposition separates volume drivers (tier-one hospital expansion in Beijing, Shanghai, and Guangzhou) from value drivers (image-guided technology migration). Segmentation dimensions span product type, application, end user, and technology integration depth. CAGRs derive from procedure volume trajectories in urology and oncology, cross-referenced against capital equipment replacement cycles and reimbursement pathway maturation timelines.
Caveats apply where FDA breakthrough designation velocity, EU MDR notified body capacity, or CMS coverage determination timelines could materially shift the outlook. Forecasts embed assumptions on NMPA approval channel efficiency and sonographer training pipeline expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market