
 Global Intraoral Cameras Market | 2026-2036
Global Intraoral Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intraoral Cameras Market Foresight
Aftermarket service revenue is narrowing as manufacturers bundle multi-year calibration and software-update contracts into initial hardware sales. Dentsply Sirona leverages its installed base of chairside imaging systems to lock in recurring revenue streams. Danaher anchors its position through KaVo Dental's dense service network across European clinical markets. Planmeca Oy differentiates via open-architecture compatibility that reduces switching costs for specialist practices.
Intraoral cameras are handheld optical devices typically employing CMOS or CCD sensors with LED or fiber-optic illumination, capturing magnified digital images of oral structures at resolutions exceeding 720p for real-time chairside visualization and patient education. Wireless intraoral cameras are capturing margin pools previously held by wired systems as lithium-ion power management and Bluetooth 5 protocols eliminate cable-replacement cycles. HD and autofocus variants command premium positioning in restorative dentistry and orthodontics where tissue-edge definition drives treatment-planning accuracy. CMOS sensor technology dominates unit economics while CCD persists in academic and forensic applications demanding minimal noise profiles.
FDA 510(k) premarket notification and EU MDR Class I classification govern electrical safety, electromagnetic compatibility, and biocompatibility of intraoral camera housings and sheathing materials. Japan's PMDA and METI coordinate standards alignment with JIS medical electrical equipment norms, creating parallel compliance burdens for multinational suppliers. Stakeholders must monitor evolving cybersecurity guidance from FDA and EMA as cloud-connected imaging workflows expose patient data to novel breach vectors.
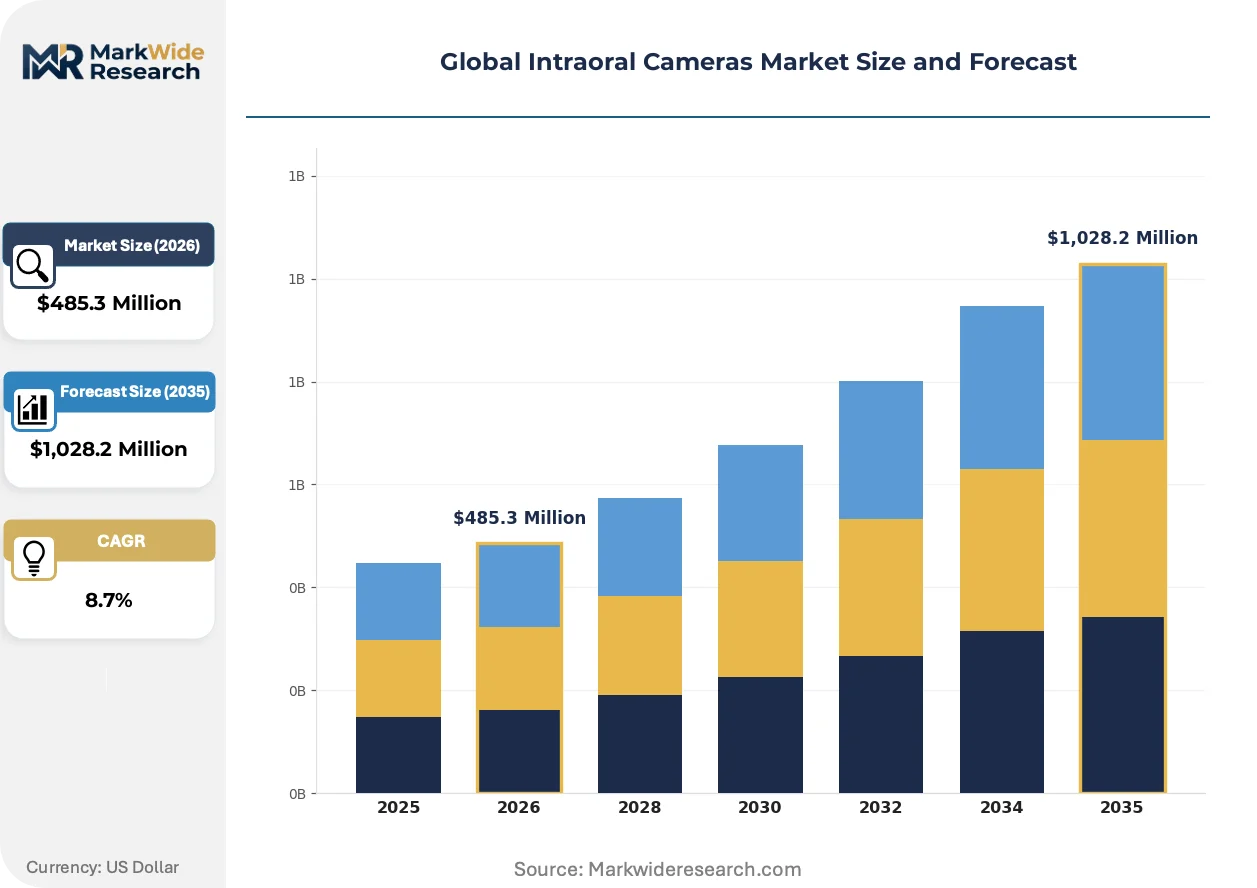
Market Dynamics
Wireless lithium-ion power management and Bluetooth 5 protocols are collapsing the installed base of wired intraoral cameras, forcing manufacturers to restructure hardware margins around bundled software subscriptions and multi-year calibration contracts.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for CMOS-based wireless variants are compressing product launch cycles for North American dental equipment distributors.
- Japan's preventive imaging reimbursement:METI-aligned dental insurance frameworks now cover chairside visualization for early caries detection, pulling HD camera procurement into general practices.
- CMOS sensor cost curves:Semiconductor foundry scale economies are driving unit cost reductions that enable 1080p resolution at price points accessible to mid-tier clinics.
Market Restraints
- EU MDR Class I biocompatibility testing:Extended validation timelines for housing and sheathing materials are delaying European market entry for Asian original equipment manufacturers.
- CCD sensor supply concentration:Specialty foundry capacity for low-noise CCD fabrication clusters in Japan, creating procurement bottlenecks for forensic and academic applications.
- Smartphone camera substitution:Clip-on dental adapters for iOS and Android devices are capturing patient education segments previously served by dedicated intraoral hardware.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Simplified registration for Class I medical devices is opening Latin America's largest dental market to wireless HD entrants.
- AI-assisted diagnostic convergence:Integration of real-time caries detection algorithms with autofocus optics is creating premium positioning in orthodontic and endodontic workflows.
- Cloud-connected imaging subscriptions:SaaS models bundling storage, AI analysis, and patient portal access are displacing perpetual-license software sales in German specialist practices.
Industry Challenges
- Cybersecurity compliance latency:FDA and EMA guidance on cloud-connected medical device data protection remains in draft form, freezing architectural decisions for WiFi-enabled camera platforms.
- Legacy chairside integration:Proprietary connector standards from incumbent imaging system vendors are forcing adapter development costs onto camera manufacturers seeking open-architecture positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intraoral Cameras Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intraoral Cameras, Wireless Intraoral Cameras, USB Intraoral Cameras, HD Intraoral Cameras, Autofocus Intraoral Cameras Application: Restorative Dentistry, Preventive Care, Orthodontics, Endodontics, Oral Surgery End User: Dental Clinics, Specialist Practices, Diagnostic Laboratories, Dental Schools, Mobile Dentistry Units Technology: CCD Sensor, CMOS Sensor, LED Illumination, Fiber Optic Lighting, Autofocus Mechanism |
| Companies Covered | Carestream Dental, Dentsply Sirona, Danaher, Planmeca Oy, Acteon Group, KaVo Dental, Digital Doc, Koninklijke Philips, DÜRR DENTAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intraoral Cameras Market Shifts & Advancements
Digital dentistry infrastructure investments are compressing replacement cycles for visualization hardware while elevating software interoperability and cybersecurity resilience as primary procurement criteria.
Autofocus liquid lens technology is collapsing the manual adjustment workflows that previously slowed chairside image capture in restorative procedures. Specialist practices in Germany and Japan are adopting these systems at replacement rates of eighteen to twenty-four months. The technology is collapsing the training burden for auxiliary staff while compressing appointment duration metrics that drive clinic throughput.
EU MDR technical documentation requirements for electrical safety and electromagnetic compatibility are forcing redesigns of battery compartment sealing and wireless antenna placement. Manufacturers serving European markets are absorbing twelve-to-eighteen month re-certification timelines. Wireless variants with integrated charging docks are experiencing the most significant engineering resource allocation shifts.
Subscription-based calibration and software update contracts are displacing transactional aftermarket service revenue in North American dental group practices. DSO procurement teams are negotiating enterprise-wide bundles that lock in three-to-five year service commitments. This shift is most visible in United States multi-location chains where standardization across fifty-plus offices overrides individual clinician hardware preferences.
Global Intraoral Cameras Market Segmentation
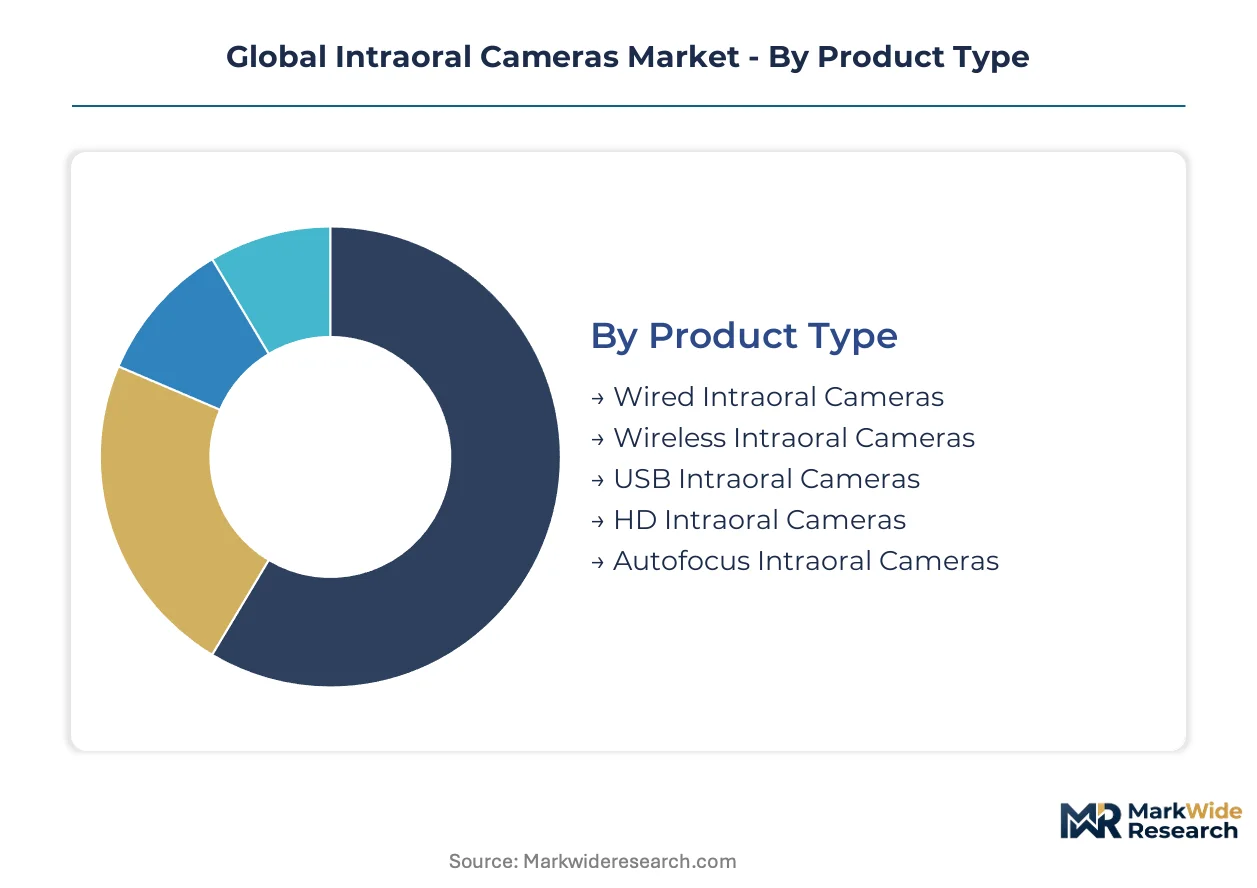
Segmentation in intraoral cameras reveals divergent replacement dynamics across hardware generations and clinical workflows. Procurement cycles stretch from eighteen months for high-throughput autofocus systems to seven years for wired installations in budget-constrained settings. Understanding these velocity differentials enables manufacturers to align service contract structures with actual utilization patterns.
Product Type:
Wireless variants turn over fastest as lithium-ion degradation and Bluetooth protocol obsolescence compress functional lifespans, while wired systems persist longest in secondary markets where cable replacement costs deter upgrades.
- Wireless Intraoral Cameras:Bluetooth 5-enabled handheld units with integrated power management eliminate tethering constraints during multi-quadrant examinations. German specialist practices and United States dental service organizations are standardizing procurement around these platforms to compress appointment duration metrics.
- Autofocus Intraoral Cameras:Liquid lens technology eliminates manual focal adjustment, collapsing image capture time from thirty seconds to under five seconds per view. Japan's preventive imaging reimbursement frameworks are accelerating adoption in general practices where auxiliary staff perform chairside visualization.
- Wired Intraoral Cameras:Legacy USB and proprietary connector systems retain installed base in price-sensitive Latin American and Southeast Asian clinics where infrastructure stability outweighs mobility benefits.
- HD Intraoral Cameras:1080p CMOS sensor configurations with enhanced dynamic range serve restorative and orthodontic applications demanding tissue-edge definition.
- USB Intraoral Cameras:Direct computer connectivity without dedicated docking stations appeals to solo practitioners minimizing capital outlay.
Wired intraoral cameras anchor the volume base while autofocus intraoral cameras gain share at the steepest rate.
Application:
Procedure complexity and reimbursement density determine hardware specification tiers, with restorative workflows commanding premium optics and preventive settings tolerating lower resolution thresholds.
- Restorative Dentistry:Crown margin visualization and shade matching demand 1080p resolution with color-calibrated LED illumination. United States prosthodontic practices and German dental laboratories are driving specification floors upward.
- Preventive Care:Early caries detection and patient education require adequate magnification without premium autofocus capabilities. Japan's METI-aligned insurance coverage is pulling HD procurement into general practice settings.
- Orthodontics:Arch documentation and treatment progression tracking benefit from rapid image capture sequences.
- Endodontics:Canal orifice identification demands high magnification with minimal motion blur.
- Oral Surgery:Soft tissue documentation and postoperative monitoring utilize standard-definition configurations in hospital outpatient departments.
Preventive care generates the highest unit volume while restorative dentistry commands the steepest price premiums per installation.
End User:
Scale economies and standardization mandates create procurement pattern divergence between consolidated dental service organizations and fragmented solo practices.
- Dental Clinics:Multi-chair facilities with centralized IT infrastructure prioritize wireless interoperability and cloud-connected imaging workflows. United States dental service organizations with fifty-plus locations are negotiating enterprise-wide standardization.
- Specialist Practices:Orthodontic and endodontic boutiques demand open-architecture compatibility to preserve workflow integration with existing imaging suites. German specialist markets show particular sensitivity to switching costs.
- Dental Schools:Training environments require durable hardware with standardized interfaces across student cohorts.
- Diagnostic Laboratories:Remote case review and digital impression validation drive demand for high-fidelity image transmission.
- Mobile Dentistry Units:Field-based preventive screening in rural United States markets and developing economies favors battery-operated wireless systems with ruggedized housing.
Dental clinics anchor the volume base while specialist practices expand most quickly as orthodontic and endodontic sub-specialization accelerates.
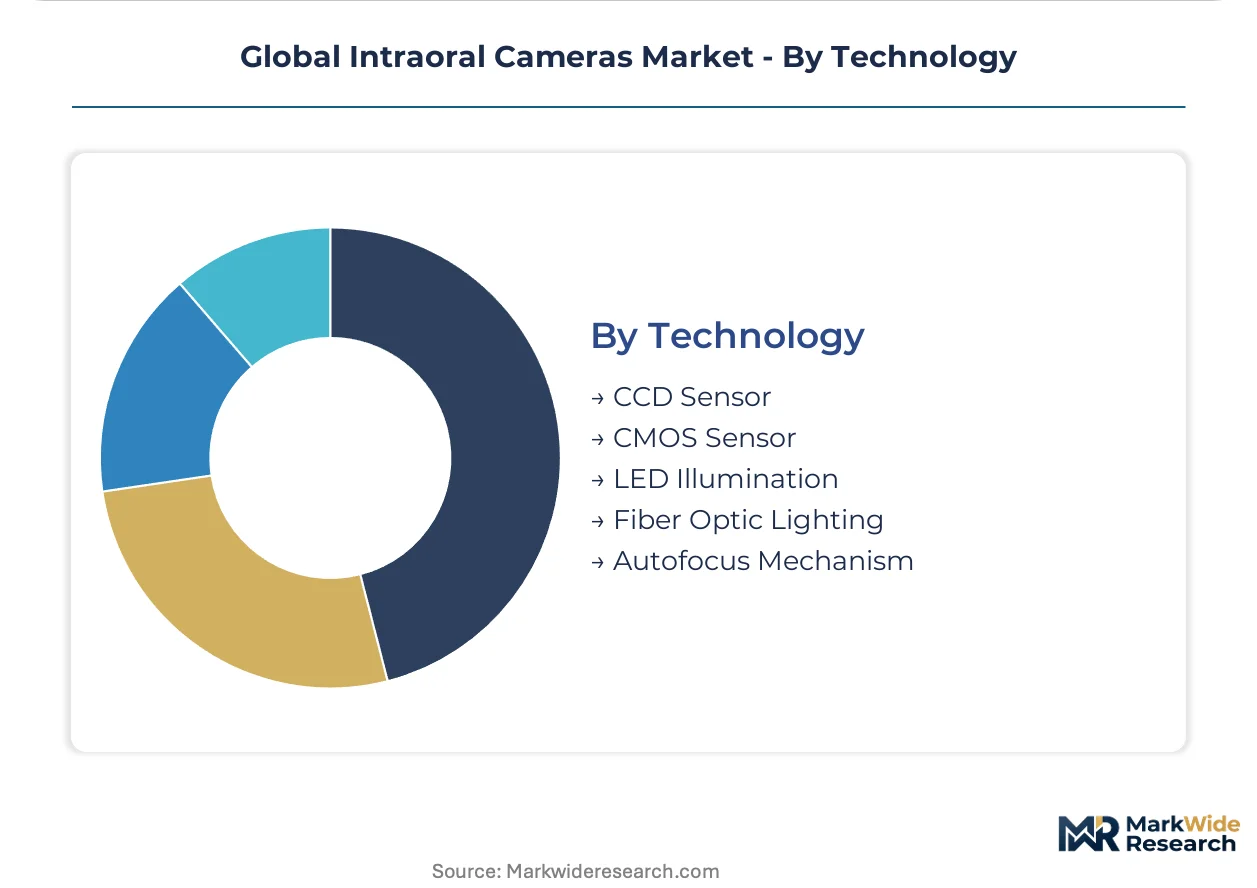
Technology:
Sensor economics and illumination efficiency are reshaping component sourcing strategies, with CMOS dominance eroding CCD's residual stronghold in forensic applications.
- CMOS Sensor:Complementary metal-oxide semiconductor technology delivers 1080p resolution at foundry scale economies that collapse unit costs. Taiwan and South Korean semiconductor fabrication capacity is enabling price accessibility for mid-tier clinics.
- LED Illumination:Solid-state lighting with tunable color temperature eliminates fiber optic cable fragility while reducing power consumption. Japanese component suppliers are consolidating market position through integrated sensor-illumination modules.
- CCD Sensor:Charge-coupled device technology persists in academic and forensic settings where noise minimization outweighs cost considerations. Japanese specialty foundry concentration creates procurement bottlenecks.
- Fiber Optic Lighting:Halogen-based illumination systems retain installed base in legacy wired configurations.
- Autofocus Mechanism:Liquid lens and voice coil motor technologies are collapsing training burdens for auxiliary clinical staff.
LED illumination anchors the volume base while autofocus mechanism integration climbs the fastest as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium autofocus systems at eighteen-month replacement cycles, while clinics in Brazil and India operate at higher sensitivity thresholds where wired configurations persist longest.
United States
Dental service organizations with fifty-plus locations are standardizing wireless procurement to compress appointment duration metrics across multi-state footprints. FDA 510(k) clearance timelines for CMOS-based variants have compressed from fourteen to nine months since 2023. Dallas-Fort Worth and Phoenix metropolitan clusters are witnessing concentrated DSO headquarters expansion driving enterprise-scale imaging contracts.
Germany
Specialist practices in restorative dentistry command specification floors of 1080p resolution with color-calibrated LED illumination. EU MDR Class I biocompatibility testing requirements are absorbing twelve-to-eighteen month re-certification timelines for housing material validation. The Baden-Württemberg industrial corridor around Stuttgart hosts dense concentrations of dental equipment engineering talent and precision manufacturing subcontractors.
Japan
METI-aligned dental insurance frameworks now reimburse chairside visualization for early caries detection, pulling HD camera procurement into general practice settings. PMDA coordinates standards alignment with JIS medical electrical equipment norms, creating parallel compliance burdens for multinational suppliers. The Nagoya-Chubu manufacturing belt supplies integrated sensor-illumination modules dominating component sourcing for Asia-Pacific assembly.
Brazil
ANVISA fast-track pathways for Class I medical devices are opening Latin America's largest dental market to wireless HD entrants at price points inaccessible under prior regulatory timelines. São Paulo state concentrates both private dental clinic density and federal university hospital procurement authority. Minas Gerais and Rio Grande do Sul secondary cities are absorbing wired system transfers from primary market upgrades.
China
Domestic CMOS foundry scale economies from Taiwan and South Korean semiconductor fabrication are enabling 1080p resolution accessibility for mid-tier clinic budgets. NMPA medical device registration requirements are tightening cybersecurity documentation for cloud-connected imaging workflows. The Yangtze River Delta around Shanghai hosts assembly operations serving both domestic consumption and Southeast Asian export markets.
Global Intraoral Cameras Market Competitive Landscape
Capability concentration sits with imaging system incumbents possessing dense service networks and chairside integration expertise; scale advantage sits with diversified dental conglomerates leveraging cross-product bundling. The vendor base structures around three tiers: integrated imaging suite providers, standalone camera specialists, and component module suppliers. Dominant competitive moves include multi-year calibration contract bundling and open-architecture compatibility positioning to reduce customer switching costs.
Among North American and European imaging conglomerates, Dentsply Sirona and Danaher exemplify the integrated-suite archetype through KaVo Dental's service infrastructure, while Planmeca Oy occupies a position emphasizing interoperability standards that lower integration friction for specialist practices. These three entities anchor the premium tier where software subscription attach rates determine lifetime customer value capture.
| Leading Market Players |
|---|
| Carestream Dental |
| Dentsply Sirona |
| Danaher |
| Planmeca Oy |
| Acteon Group |
| KaVo Dental |
| Digital Doc |
| Koninklijke Philips |
| DÜRR DENTAL |
| Others |
Supply & Pricing Matrix
The Nagoya-Chubu manufacturing belt around Nagoya anchors CMOS sensor and LED illumination module production, concentrating component sourcing leverage among Japanese integrated suppliers and compressing margin pools for downstream camera assemblers competing on hardware differentiation.
Pricing Analysis
Long-term calibration and software-update contracts dominate procurement structures as dental service organizations negotiate three-to-five year enterprise bundles. Pricing stratifies across premium autofocus systems with AI-assisted diagnostics, standard HD wireless configurations, and economy-tier wired USB variants. Cost compression in the economy segment intensifies as smartphone camera adapters capture patient education workflows. Solo practitioners in Southeast Asia exhibit the highest price sensitivity, while German specialist practices absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control regimes on advanced semiconductor manufacturing equipment constrain CMOS foundry capacity expansion outside Taiwan and South Korea, tethering sensor supply to East Asian fabrication clusters. Japanese specialty foundries retain CCD production for forensic applications. Lithium-ion power management ICs and Bluetooth 5 protocol chipsets complete the critical component triad. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, where earthquake or geopolitical disruption would cascade through camera assembly lines. Distribution runs through dental equipment distributors with regional service networks, bypassing direct-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
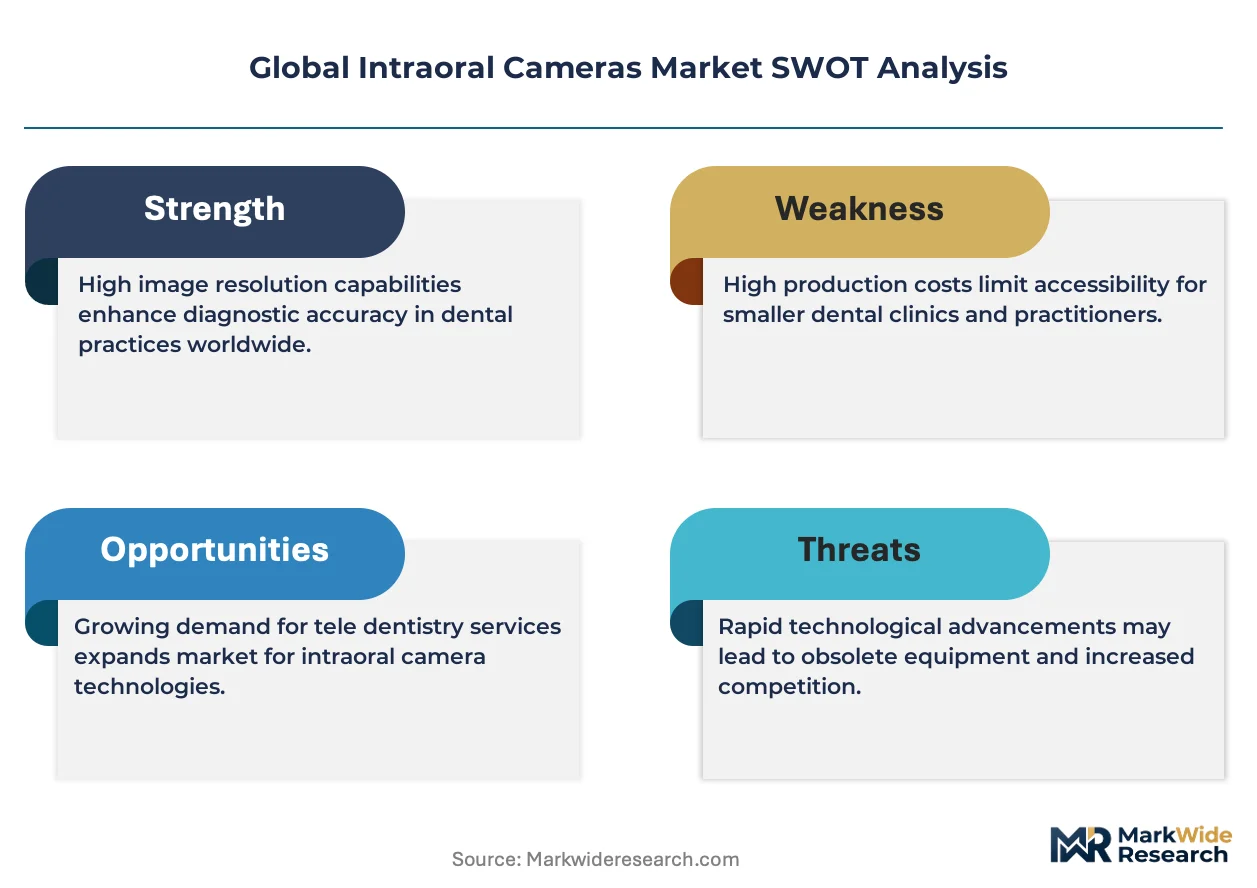
Incumbents face substitution defense imperatives as smartphone camera adapters with clip-on dental attachments erode the patient education segment previously served by dedicated hardware.
For Market Incumbents: Entrench installed base loyalty through multi-year calibration contract bundling and open-architecture compatibility investments that reduce specialist practice switching costs. Counter smartphone substitution threats by embedding AI-assisted diagnostic algorithms that clip-on adapters cannot replicate. Deepen backward integration into CMOS sensor-illumination module production to capture component margin pools concentrated in Japanese suppliers.
For New Entrants and Emerging Players: Brazil's ANVISA fast-track pathway for Class I medical devices offers the most penetrable geographic entry point, with São Paulo state concentrating private clinic density and federal procurement authority. Target mobile dentistry units in rural United States markets with ruggedized wireless systems optimized for field-based preventive screening. Pursue cloud-connected imaging SaaS bundling to bypass capital-intensive hardware margin competition.
For Investors and Strategic Acquirers: Long-term, this sits as a dental infrastructure consolidation play because digital dentistry workflow integration creates sticky installed bases with recurring software revenue attach rates. Acquisition targets should cluster around standalone camera specialists possessing FDA 510(k) clearance pipelines and dense European service networks. Monitor FDA draft cybersecurity guidance finalization as the signal indicating when WiFi-enabled platform investments will unlock enterprise procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Algorithm Integration | Real-time caries detection embedded in autofocus optics creates premium positioning in orthodontic workflows. |
| CE Marking Pathway Under EU MDR | Twelve-to-eighteen month biocompatibility validation timelines filter Asian OEM competitors from European market entry. |
| Dental Service Organization Partnership | Enterprise-wide standardization across fifty-plus location chains locks in three-to-five year recurring revenue streams. |
| Cloud-Connected Imaging SaaS Development | Subscription models bundling storage and patient portal access displace perpetual-license software in German practices. |
| ANVISA Fast-Track Registration | Simplified Class I device pathways open Latin America's largest dental market to wireless HD entrants at accessible price points. |
Research Methodology
The analysis maps wireless, autofocus, wired, HD, and USB product type segments, each validated through dental equipment procurement managers, biomedical engineers at dental schools, GPO contracts managers, and regulatory affairs specialists at imaging conglomerates. Primary interview findings triangulate against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract records, and semiconductor foundry capacity disclosures. Bottom-up unit shipment estimates and top-down dental clinic infrastructure investment patterns converge on market sizing.
Assumption sets held regulatory pathway timelines and CMOS sensor cost curves fixed while varying dental service organization consolidation rates and preventive imaging reimbursement expansion across geographies. The projection horizon spans product type, application, end user, and technology segmentation dimensions with CMOS versus CCD sensor mix and wireless versus wired connectivity as critical hardware transition variables. CAGRs derive from replacement cycle velocity differentials and software subscription attach rate trajectories.
Macroeconomic conditions sit as an overlay; deviation in dental clinic capital expenditure cycles or semiconductor fabrication capacity investment would shift the trajectory. Forecasts reflect assumptions on FDA cybersecurity guidance finalization and EU MDR enforcement consistency. Material shifts in smartphone camera adapter clinical validation or lithium-ion battery supply chain disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Transplant Monitoring Kits Market