
 Global Laminated Aluminium Foil Market | 2026-2036
Global Laminated Aluminium Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laminated Aluminium Foil Market Intelligence
Southeast Asia is reconfiguring laminated aluminium foil supply chains as Vietnam and Thailand add rolling and converting capacity. Hindalco Industries Ltd leverages captive alumina-to-foil integration across Indian operations. Novelis sustains automotive-grade metallurgy expertise that transfers into high-performance barrier laminates. Constantia Flexibles anchors European pharmaceutical packaging demand through dedicated healthcare film facilities.
Laminated aluminium foil consists of aluminium sheet bonded to polymer films or paper substrates through extrusion coating, adhesive lamination, or hot-melt processes, typically achieving oxygen transmission rates below 0.01 cc/m²/day for pharmaceutical blister applications. The primary purpose is to create hermetic, light-impermeable barriers that extend shelf life for moisture-sensitive and photo-degradable products. Multi-layer laminated structures command premium positioning in pharmaceutical packaging due to exacting barrier requirements, while single-side laminated formats dominate food and beverage wrapping volumes where cost efficiency outweighs extreme barrier performance. Blister pack packaging types concentrate margin pools because medical-grade validation and child-resistance certification create qualification barriers for new suppliers.
FDA enforces strict extractables and leachables testing for pharmaceutical contact layers, directly elevating compliance costs for laminate converters serving US-bound drug packaging. EMA's Medical Device Regulation and REACH substance restrictions in Europe simultaneously tighten biocompatibility documentation and restrict certain adhesive chemistries, forcing reformulation investments across the supply base. India's BIS certification mandates for food-contact materials add another compliance layer for exporters. Stakeholders must monitor regulatory divergence between jurisdictions, as misaligned approval timelines threaten synchronized product launches across major markets.
Market Dynamics
Pharmaceutical-grade barrier requirements are compressing qualification timelines for laminated aluminium foil converters, while rolling capacity expansion in India and Southeast Asia reshapes regional supply hierarchies. EU F-Gas Regulation phase-down schedules and REACH substance restrictions force simultaneous reformulation of adhesive layers and cooling systems across European converting facilities.
Growth Catalysts
- EMA Medical Device Regulation:Blister-pack validation requirements for pharmaceutical contact materials expand addressable market for medical-grade laminates as generic drug manufacturers upgrade packaging specifications.
- India PLI scheme:Domestic converting capacity subsidies attract capital deployment toward Southeast Asian export corridors, displacing Chinese-origin supply in regional pharmaceutical packaging.
- Hot-melt extrusion coating:Solvent-free bonding technology reduces volatile organic compound exposure in food-contact applications while accelerating line speeds for high-volume snack wrapping.
Market Restraints
- Primary aluminium ingot volatility:LME price swings transmit directly into foil rolling margins, compressing converter profitability during energy cost spikes.
- European rolling concentration:Three integrated producers control pharmaceutical-grade thin-gauge supply, creating qualification bottlenecks for new laminate entrants.
- Polymer film substitution:Metallized PET and EVOH coextrusions capture shelf-stable food segments where oxygen transmission rates above 0.1 cc/m²/day suffice.
Strategic Opportunities
- Indonesia domestic packaging:Halal pharmaceutical certification requirements and import substitution policies create captive demand for local laminate conversion.
- FDA extractables testing harmonization:Standardized leachable study protocols reduce redundant validation costs for converters serving multiple US drug manufacturers.
- Digital printing integration:Variable-data decoration on pre-laminated webs enables short-run pharmaceutical serialization without separate label application.
Industry Challenges
- Child-resistance certification timelines:ISO 8317 and US 16 CFR 1700.20 testing protocols extend product launch cycles by 8-14 months for novel blister formats.
- Multi-layer coextrusion expertise:Thin-gauge aluminium bonding to oriented nylon and cast polypropylene demands polymer rheology specialists scarce in emerging converting markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laminated Aluminium Foil Market |
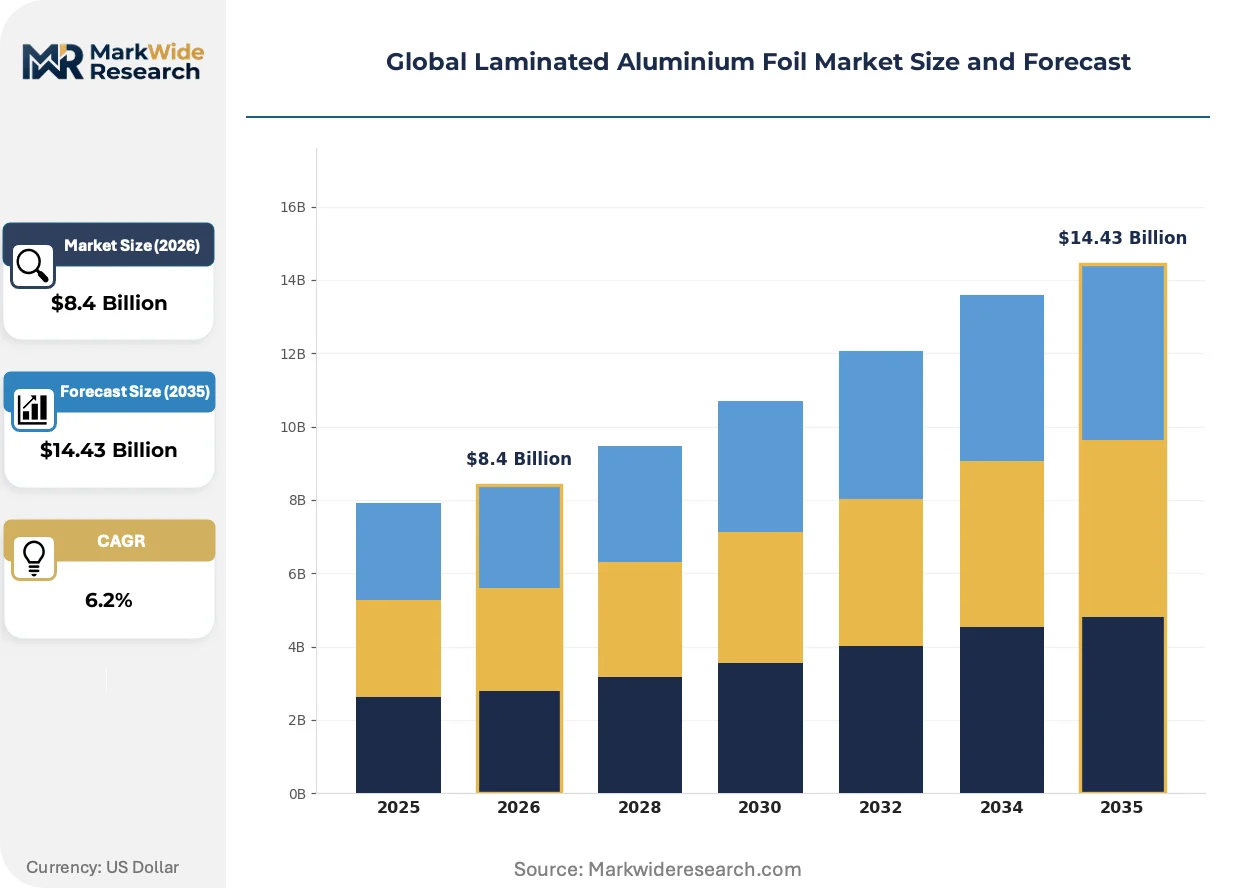
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Side Laminated, Double-Side Laminated, Multi-Layer Laminated, Barrier Laminated Application: Pharmaceutical Packaging, Food & Beverage Wrapping, Cosmetic Packaging, Industrial Wrapping End User: Packaging Manufacturers, Pharmaceutical Companies, Food Processing Entities, Cosmetic Firms Packaging Type: Roll, Sheet, Pouch, Blister Pack |
| Companies Covered | Safepack Industries Ltd, Zenith Alluminio Srl, Hindalco Industries Ltd, Novelis, All-Foils Inc, Constantia Flexibles, Amcor plc, Tropack Packmittel GMBH, Prithvi Foils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laminated Aluminium Foil Market Strategic Shifts & Innovations
Converting equipment and quality assurance systems are digitizing across laminated foil production lines, compressing defect detection response times and enabling real-time barrier property verification. Three interconnected developments are restructuring competitive capability requirements.
Machine vision inspection with sub-10-micron resolution is digitizing pinhole detection in rolled annealed foil, replacing offline sampling protocols. Pharmaceutical packaging converters in Germany and Switzerland deploy these systems to satisfy FDA process analytical technology guidelines. Real-time defect mapping enables selective lamination, reducing aluminium waste in high-value medical applications.
EU F-Gas Regulation phase-down mandates for hydrofluorocarbon refrigerants force cold-chain pharmaceutical distributors to validate laminate performance across expanded temperature excursions. EMA guidance on temperature-sensitive biologics storage tightens oxygen and moisture ingress specifications for secondary packaging. Converters serving European distribution networks invest in accelerated aging protocols that simulate +25°C to +40°C supply chain exposure.
Drug manufacturers consolidate primary packaging procurement under centralized category management functions, displacing fragmented site-level purchasing. This concentration demands laminate suppliers provide standardized global specifications with regional regulatory documentation. Indian and Thai converters establish dedicated pharmaceutical business units with US and EU regulatory affairs capabilities to serve consolidated buying desks.
Global Laminated Aluminium Foil Market Segmentation
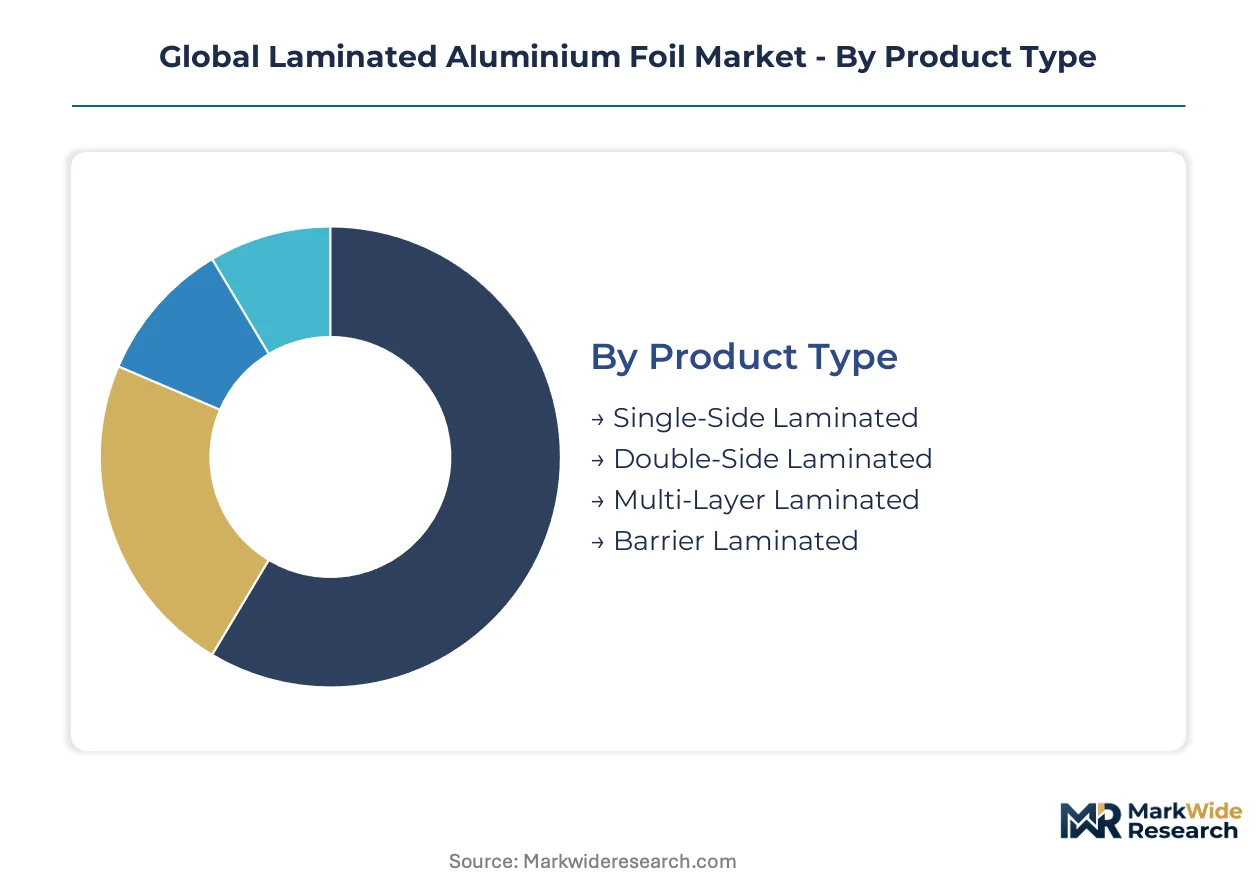
Segmentation in laminated aluminium foil reveals how technical specifications and regulatory requirements fragment purchasing behavior. Pharmaceutical-grade barrier laminates demand intensive qualification support and validation documentation, while food-contact formats prioritize volume scalability and line-speed compatibility.
Product Type:
After-sales service intensity varies sharply across product types, with multi-layer and barrier laminates requiring ongoing technical support for adhesive performance validation and shelf-life testing protocols.
- Multi-Layer Laminated:Structures bond aluminium with oriented nylon, cast polypropylene, and ethylene vinyl alcohol through coextrusion or adhesive lamination, achieving oxygen transmission rates below 0.01 cc/m²/day. Demand concentrates in German and Swiss pharmaceutical packaging corridors where EMA Medical Device Regulation mandates validated barrier documentation for temperature-sensitive biologics.
- Barrier Laminated:High-performance formats incorporate metallized or ceramic-coated layers alongside aluminium to extend moisture protection duration. Indian converters serving Southeast Asian export markets are scaling capacity here to capture halal pharmaceutical certification requirements in Indonesia and domestic substitution policies in Thailand.
- Single-Side Laminated:Aluminium bonded to single polymer substrates dominates high-volume snack wrapping where cost efficiency outweighs extreme barrier needs.
- Double-Side Laminated:Symmetrical structures with aluminium core between two polymer layers serve industrial moisture-barrier applications with moderate performance thresholds.
Multi-Layer Laminated holds the largest share; momentum sits with Barrier Laminated as biologics distribution networks expand temperature excursion validation requirements.
Application:
Application segmentation tracks how oxygen sensitivity and photo-stability requirements determine laminate specification tiers across end-use sectors.
- Pharmaceutical Packaging:Blister packs, strip packs, and cold-form laminates for drug products require FDA extractables and leachables testing plus EMA biocompatibility documentation. German packaging manufacturers are expanding orders for barrier-grade foil as generic drug makers upgrade specifications to meet centralized procurement standards.
- Food & Beverage Wrapping:Chocolate, dairy, and ready-to-eat segments use single-side laminated formats where metallized PET substitution threatens aluminium share in shelf-stable categories above 0.1 cc/m²/day oxygen transmission tolerance.
- Cosmetic Packaging:Sachets and sample pouches for skincare and fragrance products prioritize decorative surface quality and print adhesion over extreme barrier performance.
- Industrial Wrapping:VCI (volatile corrosion inhibitor) laminates and moisture-barrier bags for machinery and electronics export use double-side or multi-layer formats with desiccant compatibility.
Pharmaceutical Packaging commands premium positioning; Food & Beverage Wrapping delivers volume scale despite polymer substitution pressure.
End User:
End user categories reflect divergent procurement sophistication, with pharmaceutical companies demanding regulatory affairs partnership and food processors emphasizing line-speed optimization.
- Pharmaceutical Companies:Multinational drug manufacturers consolidate primary packaging procurement under centralized category management, requiring laminate suppliers to provide standardized global specifications with regional regulatory documentation for FDA, EMA, and CDSCO submissions.
- Packaging Manufacturers:Converters serving multiple end-use sectors maintain flexible production lines capable of switching between pharmaceutical validation batches and food-volume runs, with Indian and Thai operators adding dedicated pharmaceutical business units.
- Food Processing Entities:Snack and confectionery producers prioritize hot-melt extrusion coating compatibility for solvent-free bonding that accelerates line speeds and reduces VOC exposure.
- Cosmetic Firms:Beauty and personal care brands source laminated sachets through specialized converters with digital printing integration for short-run variable-data decoration.
Pharmaceutical Companies drive specification intensity; Packaging Manufacturers are expanding most quickly as converters add regulatory capabilities to serve consolidated buying desks.
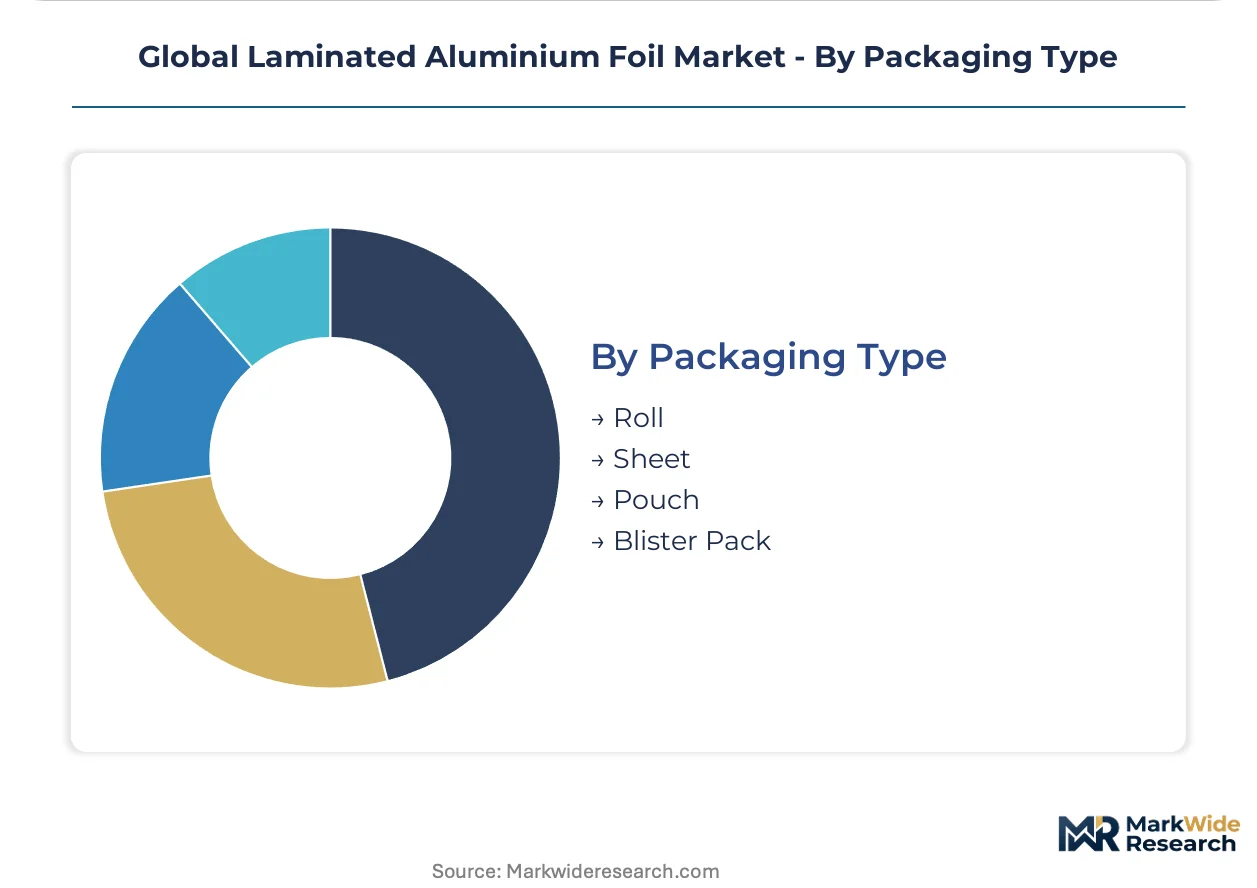
Packaging Type:
Packaging format determines converting equipment requirements and barrier validation protocols across the value chain.
- Blister Pack:Thermoformed cavities with lidding foil for unit-dose pharmaceuticals require child-resistance certification under ISO 8317 and US 16 CFR 1700.20, extending product launch cycles by 8-14 months for novel formats.
- Roll:Continuous web formats for automated form-fill-seal operations dominate food and industrial applications where line efficiency determines converter selection.
- Pouch:Pre-formed or form-fill-seal flexible packages serve single-serve food, cosmetic samples, and pharmaceutical unit doses with moderate barrier requirements.
- Sheet:Cut-to-size formats for manual packaging operations and small-batch pharmaceutical production carry higher per-unit costs but lower capital equipment barriers.
Blister Pack captures margin concentration; Roll formats scale fastest in Southeast Asian export corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA extractables testing requirements anchor United States demand for pharmaceutical-grade laminates, while EMA's Medical Device Regulation and India's PLI scheme reshape supply chain investments across three continents.
United States
Generic drug manufacturers consolidate procurement under centralized category management, expanding validation documentation requirements for barrier-grade foil. FDA enforces strict extractables and leachables protocols for pharmaceutical contact layers, elevating compliance costs for converters. New Jersey and Pennsylvania pharmaceutical packaging corridors concentrate demand for child-resistant blister formats.
Germany
Pharmaceutical packaging manufacturers expand orders for barrier-grade foil as generic drug makers upgrade specifications. EU F-Gas Regulation phase-down schedules force simultaneous reformulation of adhesive layers and cooling systems across converting facilities. Bavaria's healthcare film facilities anchor European pharmaceutical demand through dedicated barrier laminate production.
India
Domestic converters scale capacity to serve Southeast Asian export markets, displacing Chinese-origin supply in regional pharmaceutical packaging. The PLI scheme attracts capital deployment toward dedicated pharmaceutical business units with US and EU regulatory affairs capabilities. Gujarat and Maharashtra rolling corridors integrate captive alumina-to-foil production.
Vietnam
Converting capacity expansion reconfigures regional supply hierarchies for laminated aluminium foil serving ASEAN pharmaceutical markets. Halal pharmaceutical certification requirements and import substitution policies create captive demand for local laminate conversion. Ho Chi Minh City industrial zones attract rolling and converting investments from regional packaging groups.
Thailand
Domestic substitution policies strengthen local laminate conversion for food and pharmaceutical applications. BIS certification alignment for food-contact materials enables Thai converters to access Indian export corridors. Bangkok metropolitan packaging clusters add dedicated pharmaceutical lines with EMA documentation capabilities.
Global Laminated Aluminium Foil Market Key Industry Players
Integrated aluminium producers and specialized flexible packaging converters split the market between captive metallurgy control and regulatory affairs depth. Three integrated producers dominate pharmaceutical-grade thin-gauge supply in Europe, creating qualification bottlenecks for new laminate entrants. Strategic archetypes include backward-integrated primary aluminium rollers, dedicated healthcare packaging specialists, and diversified flexible packaging conglomerates. Capacity expansion in India and Southeast Asia and M&A consolidation among European converters represent the dominant competitive moves.
Within the integrated producer tier, Hindalco Industries Ltd exemplifies captive alumina-to-foil integration across Indian operations, while Novelis occupies a position transferring automotive-grade metallurgy expertise into high-performance barrier laminates. Among specialized converters, Constantia Flexibles anchors European pharmaceutical packaging demand through dedicated healthcare film facilities.
| Leading Market Players |
|---|
| Safepack Industries Ltd |
| Zenith Alluminio Srl |
| Hindalco Industries Ltd |
| Novelis |
| All-Foils Inc |
| Constantia Flexibles |
| Amcor plc |
| Tropack Packmittel GMBH |
| Prithvi Foils |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors transmit LME aluminium price volatility directly into European converter margins, compressing profitability for thin-gauge pharmaceutical foil while widening spreads between German barrier-grade supply and Indian export-tier pricing. This logistics-cost asymmetry rewards backward-integrated rollers with captive smelter access and penalizes merchant converters exposed to spot ingot markets.
Pricing Analysis
Geographic price spreads between European pharmaceutical-grade laminates and Southeast Asian export-tier supply now exceed raw material differentials, reflecting EMA validation documentation costs and child-resistance certification premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance tier and regulatory compliance depth, with FDA extractables-tested formats commanding sustained premiums. Pricing pressure stems from primary aluminium ingot volatility transmitting through rolling margins, particularly for merchant converters without captive alumina supply. Food-contact buyers exhibit highest price sensitivity, while multinational pharmaceutical companies prioritize specification consistency over unit cost negotiation.
Supply Chain Analysis
Contract manufacturing concentration among German, Swiss, and Austrian healthcare packaging specialists controls pharmaceutical-grade thin-gauge foil conversion, with dedicated barrier laminate facilities in Bavaria and Zurich anchoring European supply. Raw material flows draw from Indian alumina-to-foil integrated producers, Russian primary aluminium ingots, and Korean polymer film suppliers, creating multi-continent dependency chains. Single-source vulnerability concentrates in pharmaceutical-grade rolling capacity, where three integrated producers qualify for EMA biocompatibility documentation. Distribution runs through consolidated drug manufacturer procurement desks and regional converting hubs serving ASEAN pharmaceutical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Medical Device Regulation implementation and FDA extractables testing harmonization are disrupting qualification timelines, creating temporary margin pools for converters with pre-validated barrier documentation and regulatory affairs depth.
For Market Incumbents: Entrench pharmaceutical-grade positioning by acquiring dedicated healthcare film facilities with existing FDA master files and EMA technical documentation, while expanding hot-melt extrusion coating capacity to capture solvent-free food-contact demand. Novelis and Hindalco demonstrate how automotive-grade metallurgy expertise transfers into high-performance barrier laminates, defending against polymer film substitution in oxygen-sensitive applications. Prioritize child-resistance certification pipelines to compress 8-14 month ISO 8317 validation timelines.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian halal pharmaceutical packaging, where domestic certification requirements and import substitution policies create captive demand for local laminate conversion with limited incumbent penetration. Target Vietnamese and Thai converting capacity serving ASEAN export corridors, displacing Chinese-origin supply through BIS-aligned food-contact certification. Pursue digital printing integration partnerships to enable short-run pharmaceutical serialization without separate label application infrastructure.
For Investors and Strategic Acquirers: Mid-scale converters with dedicated pharmaceutical business units and US-EU dual regulatory capabilities represent the most defensible acquisition profile, given consolidated drug manufacturer procurement trends demanding standardized global specifications. Long-term viability hinges on temperature excursion validation expertise for biologics distribution networks expanding across +25°C to +40°C supply chain exposure. Monitor FDA extractables testing protocol harmonization progress as inflection signal for validation cost reduction and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Hindalco's captive supply chain demonstrates margin protection against LME volatility. |
| EMA Medical Device Regulation Certification | Validated barrier documentation expands addressable market for generic drug packaging upgrades. |
| Hot-Melt Extrusion Coating Capacity Addition | Solvent-free bonding technology reduces VOC exposure while accelerating snack wrapping line speeds. |
| Digital Printing Integration Partnership | Variable-data decoration on pre-laminated webs enables pharmaceutical serialization without label application. |
| Halal Pharmaceutical Certification Investment | Indonesian domestic requirements create captive demand for local laminate conversion capacity. |
Research Approach
A standing panel of pharmaceutical packaging procurement directors, flexible converting plant managers, regulatory affairs specialists, and polymer film supply planners provided ongoing calibration across the research window. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA medical device submissions, BIS food-contact certification records, and LME aluminium futures data. Bottom-up capacity assessments at rolling and converting facilities triangulated against top-down demand modeling from drug manufacturer packaging procurement disclosures.
Scenario-bracketing around EMA Medical Device Regulation implementation timelines, FDA extractables testing harmonization progress, and PLI scheme subsidy duration anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application barrier requirement, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from rolling capacity expansion announcements, converting equipment installation records, and pharmaceutical packaging demand forecasts incorporating biologics distribution growth.
Sensitivities concentrate around primary aluminium ingot price volatility, REACH substance restriction expansion, and child-resistance certification timeline compression. Forecasts reflect assumptions on regulatory convergence between FDA and EMA protocols, Indian PLI scheme renewal probability, and polymer film substitution thresholds in shelf-stable food segments. Quarterly review of LME aluminium futures curves, EMA guidance document releases, and ASEAN pharmaceutical import substitution policy announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Tin Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Metal Drums Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Brass Foils Market
Metal Packaging
Germany Metal Packaging Market