
 Tin Cans Market | 2026-2036
Tin Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Tin Cans Market Analytics
Aluminum is pivoting into beverage can lines as brands seek weight reduction and recycling economics, yet steel-tinplate retains cost advantages in processed food and aerosol applications. Ardagh Group leverages integrated metal supply chains across European steelworks to sustain margin control on three-piece food cans. Crown Holdings anchors North American beverage can capacity through continuous draw-and-iron press upgrades. Silgan Holdings competes in specialty and industrial segments where customized diameter-to-height ratios command technical premiums.
Tin cans are cylindrical metal containers fabricated from electrolytic tinplate or tin-free steel, formed through either draw-and-wall-ironing (two-piece) or bodymaking with seamed side-welds (three-piece), with interior lacquer coatings preventing corrosion and flavor contamination. Two-piece designs lead beverage applications due to material efficiency and seamless structural integrity, while three-piece construction dominates processed vegetables and fish where aggressive filling temperatures demand robust seam geometry. End-use specific formats capture pharmaceutical and industrial aerosol demand where pressure ratings and valve compatibility override standard capacity specifications.
FDA food-contact substance notifications govern interior coating chemistries in the United States, while EPA hazardous waste rules affect post-industrial scrap recovery economics for tinplate recyclers. EU REACH restrictions on bisphenol-A epoxy coatings and F-Gas Regulation phase-downs for aerosol propellants reshape material and formulation choices across export-oriented canmakers. Stakeholders must monitor evolving extended producer responsibility frameworks and coating substitution timelines to align capital allocation with compliance-driven specification changes.
Market Dynamics
Steel-tinplate supply concentration and REACH-driven coating substitution are compressing margins for canmakers while forcing rapid reformulation of interior lacquer systems across European export lines.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled-content quotas for metal packaging accelerate steel can adoption over single-use plastics in processed food retail across Germany and France.
- Draw-and-wall-ironing press upgrades:Beverage processors deploy two-piece aluminum lines to capture weight reduction and logistics savings in carbonated soft drink distribution.
- Southeast Asian canned seafood exports:Thai and Vietnamese processors expand procurement of three-piece tinplate containers to serve Japanese and South Korean retail chains.
Market Restraints
- Electrolytic tinplate input volatility:Tin price swings on the London Metal Exchange transmit directly to canmaking cost structures with limited hedging instruments available.
- REACH bisphenol-A epoxy restrictions:ECHA substance evaluation forces accelerated coating substitution timelines, straining R&D budgets and qualification cycles.
- Flexible pouch substitution:Retortable polyester laminates capture shelf-stable pet food and ready-meal volume previously held by steel cans.
Strategic Opportunities
- Indonesian urban retail expansion:Modern trade penetration in Jakarta and Surabaya creates first-mover advantage for branded food can distribution networks.
- Aerosol pharmaceutical applications:Metered-dose inhaler can demand rises on propellant reformulation requirements under EU F-Gas Regulation phase-down schedules.
- Digital print-to-can integration:Direct-to-metal inkjet decoration converges with short-run filling flexibility, enabling micro-batch craft beverage launches.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for BPA-NI (bisphenol-A non-intent) epoxy alternatives concentrates among a handful of European specialty chemical firms.
- Three-piece seam welding qualification:Side-strip welding parameter validation for new lacquer systems extends customer approval timelines by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tin Cans Market |
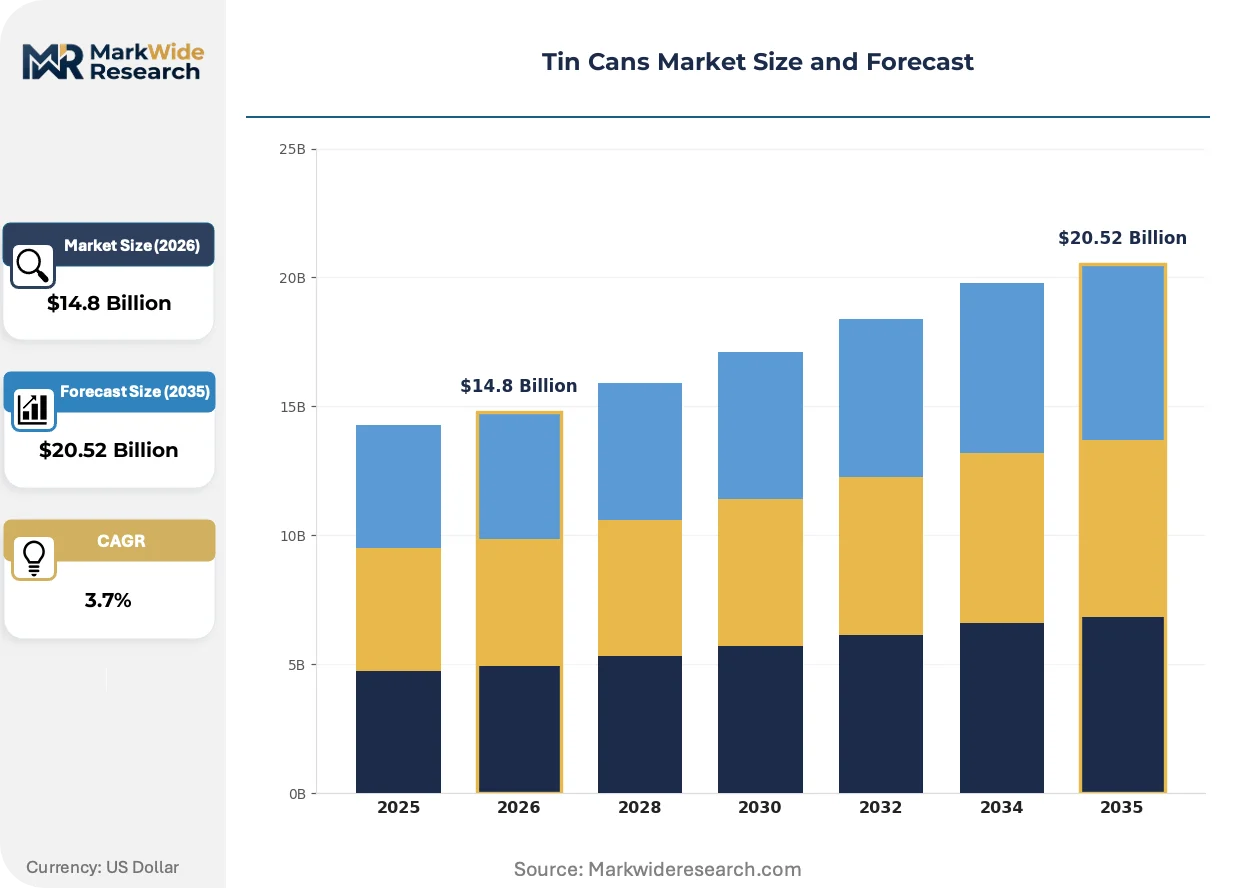
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.52 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Piece, Three-Piece, Specialty, End-Use Specific End User: Food & Beverage, Cosmetics, Pharmaceuticals, Industrial Capacity: 200ml, 400ml, 1L, 2L Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Ardagh Group, CAN-PACK Group, Crown Holdings, Inc, CPMC Holdings Limited, Kian Joo Group, Ball Corporation, Toyo Seikan Group Holdings, Ltd., Daiwa Can Company, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tin Cans Market Evolving Landscape
Active coating reformulation, press technology migration, and procurement model compression are restructuring competitive requirements for tinplate and aluminum can suppliers.
Water-based acrylic interior coatings are decentralizing the supplier base for food-contact barrier systems. Mid-tier canmakers in Poland and Spain adopt these chemistries to bypass incumbent epoxy resin supply constraints. The shift is decentralizing formulation expertise from dominant chemical multinationals toward regional coating compounders.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are forcing aerosol canmakers to validate compatibility with compressed gas and dimethyl ether alternatives. German pharmaceutical packagers face compressed timelines to requalify valve-seal interfaces. The segment is accelerating stainless steel and tinplate specification reviews to accommodate higher-pressure filling requirements.
Consolidated retail procurement in France and the United Kingdom compresses supplier negotiation cycles from annual to quarterly frameworks. Private-label canned vegetable buyers now demand real-time inventory visibility through vendor-managed stock programs. The shift is most visible in British supermarket supply chains, where direct-to-distribution-center fulfillment is displacing traditional wholesaler intermediation.
Tin Cans Market Segmentation
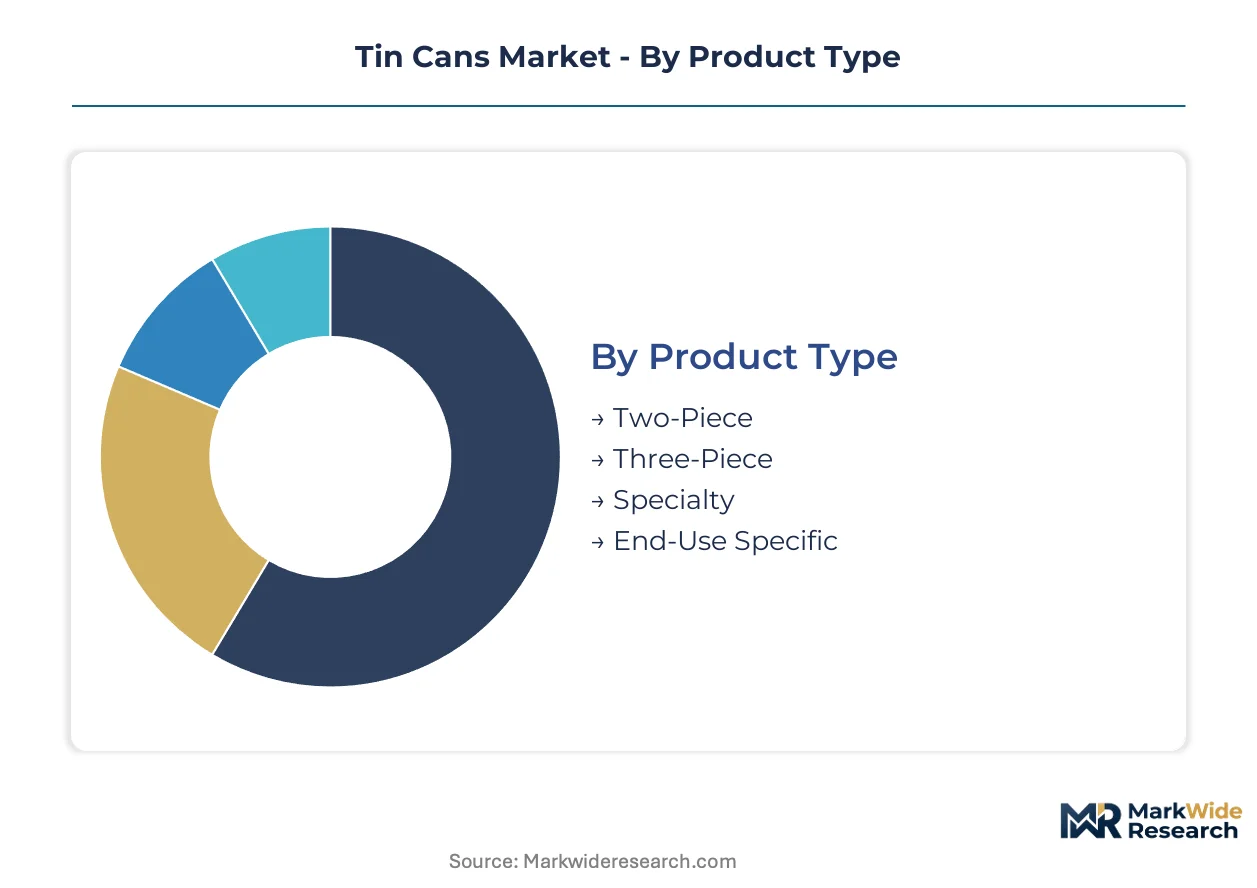
Segmentation in the Tin Cans Market reflects divergent technical requirements across filling processes, pressure ratings, and shelf-life specifications. Each category captures distinct procurement patterns that reshape supplier capabilities and capital allocation priorities.
Product Type:
Construction geometry determines material efficiency, seam integrity, and compatibility with interior coating systems.
- Two-Piece:Draw-and-wall-ironing forms seamless bodies from single metal blanks, eliminating side-seam welding and reducing material usage. Beverage processors in Germany and France deploy these lines for carbonated soft drinks where structural uniformity supports high-speed filling. Aluminum dominates this segment due to weight advantages in logistics networks.
- Three-Piece:Bodymaking with seamed side-welds accommodates aggressive thermal processing for vegetables, fish, and ready meals. Thai and Vietnamese seafood exporters specify three-piece tinplate containers for retort sterilization cycles that would compromise two-piece geometries. Steel-tinplate retains cost positioning here despite coating reformulation pressures under REACH.
- Specialty:Custom diameter-to-height ratios and decorative finishes serve premium gift markets and limited-edition releases.
- End-Use Specific:Pressure-rated designs for aerosol applications incorporate reinforced domes and valve-compatible neck profiles.
Mature deployment sits with Three-Piece construction in processed food. Newer deployment is concentrated in Two-Piece aluminum lines for beverage weight reduction.
End User:
Application-specific performance standards govern interior barrier specifications, sterilization protocols, and regulatory compliance pathways.
- Food & Beverage:Acidic contents and thermal processing demand epoxy or acrylic interior coatings with FDA food-contact substance notifications in the United States and EFSA compliance in Europe. Canned seafood, vegetables, and carbonated drinks represent volume concentration.
- Cosmetics:Aerosol and cream packaging requires compatibility with hydrocarbon propellants and fragrance stability. EU F-Gas Regulation phase-downs are forcing compressed gas and dimethyl ether alternatives that reshape valve-seal specifications.
- Pharmaceuticals:Metered-dose inhaler cans face stringent pressure ratings and propellant transition timelines under European regulatory schedules.
- Industrial:Lubricants, adhesives, and chemical products utilize heavy-gauge tinplate with corrosion-resistant exterior finishes for warehouse storage durability.
Volume concentration remains in Food & Beverage. Steepest expansion trajectory is appearing in Pharmaceuticals driven by inhaler demand and propellant reformulation requirements.
Capacity:
Volume specifications align with consumption occasions, retail format requirements, and logistics optimization across distribution networks.
- 200ml:Single-serve beverage and personal care formats dominate convenience store and travel retail channels. Japanese and South Korean vending machine networks specify this capacity for portion-controlled consumption.
- 400ml:Standard food service and household portions for vegetables, soups, and pet food products.
- 1L:Family-size beverage and cooking ingredient formats for supermarket retail in Indonesia and Malaysia.
- 2L:Industrial and institutional bulk packaging for food service distributors and manufacturing inputs.
Procurement scale concentrates in 400ml for mainstream retail. Gaining share fastest is 200ml through convenience channel expansion in Southeast Asian urban centers.
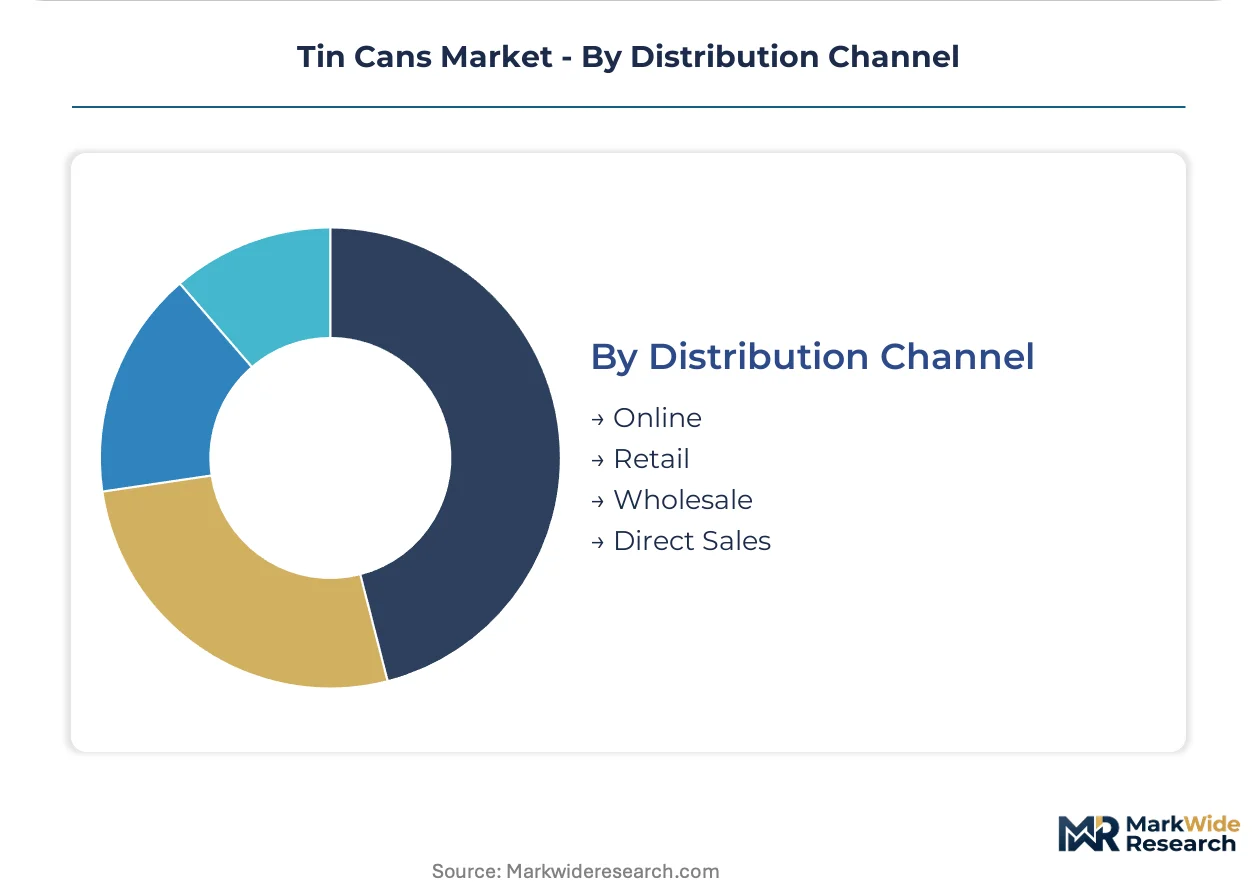
Distribution Channel:
Channel configuration determines order frequency, inventory visibility requirements, and margin structures for canmakers.
- Online:Direct-to-consumer and B2B platforms serve craft beverage startups and specialty food importers with short-run flexibility requirements. British supermarket chains now mandate real-time inventory visibility through vendor-managed stock programs.
- Retail:Supermarket and hypermarket procurement dominates volume, with consolidated buyers in France and the United Kingdom compressing negotiation cycles to quarterly frameworks.
- Wholesale:Traditional intermediation persists in emerging markets though direct-to-distribution-center fulfillment is displacing this layer in mature European supply chains.
- Direct Sales:Large food processors and beverage brands contract directly with Ardagh, Crown, and Silgan for captive supply arrangements with dedicated production lines.
Established volume flows through Retail and Wholesale. Channel shift is accelerating toward Online and Direct Sales as consolidation and digital integration reshape procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tin cans concentrates in Germany, Thailand, the United States, Japan, and Indonesia, where food processing clusters and beverage manufacturing anchor procurement volumes. Each market exhibits distinct regulatory pressures and supply chain configurations that reshape local competitive dynamics.
Germany
Carbonated soft drink bottlers in Bavaria and North Rhine-Westphalia drive two-piece aluminum can adoption for logistics weight reduction. The EU Green Deal packaging mandates enforce recycled-content quotas that favor steel over single-use plastics in processed food retail. Cologne and Hamburg host major canmaking facilities where coating reformulation under REACH bisphenol-A restrictions accelerates qualification timelines.
Thailand
Seafood processors in Samut Sakhon and Songkhla expand three-piece tinplate procurement for tuna and sardine exports to Japanese and South Korean retail chains. The country's national food safety regulator enforces thermal processing standards that favor robust seam geometries in retort applications. Bangkok-based distributors now mandate vendor-managed inventory systems for direct-to-port fulfillment.
United States
Craft beverage startups in Colorado and the Pacific Northwest demand short-run two-piece aluminum formats with direct-to-metal digital decoration. FDA food-contact substance notifications govern interior coating chemistries for acidic contents. Chicago and Milwaukee retain concentrated food can manufacturing for vegetables and pet food despite flexible pouch substitution pressures.
Japan
Vending machine networks in Tokyo and Osaka standardize 200ml single-serve beverage formats for portion-controlled consumption. METI industrial standards pressure canmakers toward lighter-gauge designs without compromising pressure ratings. Yokohama and Nagoya clusters specialize in pharmaceutical aerosol cans for metered-dose inhaler applications under propellant transition timelines.
Indonesia
Modern trade expansion in Jakarta and Surabaya creates procurement scale for 1L family-size cooking ingredient formats. The national standards body implements packaging material regulations that accelerate steel can adoption in formal retail channels. Surabaya's port infrastructure supports imported tinplate supply for domestic canmaking lines serving archipelago distribution.
Tin Cans Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated metal suppliers dominating three-piece food applications while aluminum beverage specialists capture two-piece volume. The structure tiers into scale-driven multinationals, regional fabricators with captive steel supply, and niche decorators serving craft beverage micro-batches. Dominant competitive moves include backward integration into electrolytic tinplate sourcing and technology licensing for water-based acrylic coating systems.
Within the integrated multinational tier, Ardagh Group and Crown Holdings occupy positions anchored by European steelworks relationships and North American press upgrade programs. Silgan Holdings exemplifies the specialty segment archetype where customized diameter-to-height ratios command technical premiums. Among Asia-Pacific fabricators, Toyo Seikan Group Holdings and Daiwa Can Company represent the regional specialist model with concentrated pharmaceutical and seafood packaging expertise.
| Leading Market Players |
|---|
| Ardagh Group |
| CAN-PACK Group |
| Crown Holdings, Inc |
| CPMC Holdings Limited |
| Kian Joo Group |
| Ball Corporation |
| Toyo Seikan Group Holdings, Ltd. |
| Daiwa Can Company |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal recycled-content mandates are compressing procurement cycles for steel-tinplate containers as processors abandon single-use plastics, forcing canmakers to absorb coating reformulation costs while defending contract positions against aluminum beverage alternatives.
Pricing Analysis
Volume concentration in three-piece food cans runs on thin margins anchored to London Metal Exchange tin volatility, while two-piece aluminum beverage lines capture premium positioning through weight-reduction logistics savings. Price differentiation hinges on gauge thickness and REACH-compliant interior coating certification tiers. Cost compression in European steel-tinplate supply is intensifying as electrolytic tinplate input volatility transmits directly to canmaking structures. Private-label vegetable processors in France and the United Kingdom exhibit highest price sensitivity; pharmaceutical aerosol buyers tolerate premium positioning for pressure-rated specifications.
Supply Chain Analysis
Regional distribution centers in Germany, Thailand, and Indonesia anchor hub-and-spoke patterns for tinplate procurement, with Surabaya and Jakarta serving archipelago fulfillment nodes. Raw material flows draw from Chinese electrolytic tinplate mills, Indonesian tin smelters, and European steelworks. Single-source vulnerability concentrates in coating chemical supply where BPA-NI epoxy alternatives hinge on a handful of European specialty compounders. Distribution runs through direct-to-distribution-center fulfillment displacing traditional wholesaler layers in British and French supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-driven coating substitution and tin price volatility are forcing subscale canmakers toward exit or acquisition as margin compression eliminates undifferentiated players.
For Market Incumbents: Anticipate accelerated qualification timelines for water-based acrylic interior coatings by securing regional compounder partnerships in Poland and Spain before incumbent epoxy suppliers consolidate BPA-NI expertise. Backward integration into electrolytic tinplate sourcing through European steelworks relationships defends margin control against London Metal Exchange volatility. Priority lever sits with coating chemist talent acquisition as formulation expertise concentrates among scarce European specialty firms. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Germany open a window for metered-dose inhaler can qualification as pharmaceutical packagers face compressed timelines to revalidate valve-seal interfaces. White-space targets concentrate in Indonesian urban retail expansion where modern trade penetration in Jakarta and Surabaya lacks established vendor-managed inventory systems. Go-to-market angle emphasizes direct-to-metal digital decoration capability for craft beverage micro-batches in Colorado and Pacific Northwest markets. For Investors and Strategic Acquirers: The window for entry favors mid-tier canmakers with captive steel supply and established REACH coating qualifications. Long-term viability rests on positioning for EU Green Deal packaging mandate enforcement across German and French processed food retail. Acquisition target archetype combines three-piece food can capacity with pharmaceutical aerosol certification. Signal to watch is side-strip welding parameter validation timelines for new lacquer systems as customer approval extensions indicate coating reformulation bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Tinplate | Ardagh Group's European steelworks relationships sustain margin control against LME tin volatility. |
| Water-Based Acrylic Coating Adoption | Mid-tier Polish and Spanish canmakers bypass incumbent epoxy resin supply constraints under REACH. |
| Draw-and-Wall-Ironing Press Upgrades | Crown Holdings anchors North American beverage capacity for carbonated soft drink weight reduction. |
| Vendor-Managed Inventory Systems | British supermarket chains now mandate real-time visibility displacing traditional wholesaler intermediation. |
| Digital Print-to-Can Integration | Direct-to-metal inkjet decoration enables micro-batch craft beverage launches in Colorado and Pacific Northwest. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with canmaking plant managers, coating R&D directors, food processor procurement leads, and pharmaceutical packaging engineers. ECHA substance evaluations, FDA food-contact substance notifications, and EU F-Gas Regulation schedules provided regulatory boundary conditions. Metal exchange price series and steelworks capacity disclosures furnished supply-side parameters. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Data-stream reconciliation across production volume disclosures, import-export customs records, and end-use procurement surveys shaped the analytical framework. Segmentation dimensions spanned construction geometry, end-use application, capacity specification, and distribution channel, with coating chemistry compliance tiered as an industry-specific overlay. CAGRs derived from regression against historical volume trajectories moderated by regulatory phase-in schedules and technology substitution elasticities. Tin price volatility assumptions and REACH substitution timelines fed directly into cost-structure projections.
The model assumes a particular technology adoption path; alternative pathways for water-based acrylic coating penetration would alter the outlook if epoxy resin supply constraints ease faster than anticipated. Forecasts reflect documented assumptions regarding EU Green Deal enforcement timing and Southeast Asian canned seafood export growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Brass Foils Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Aluminium Bottle Market