
 Tissue Paper Embosser Machine Market | 2026-2036
Tissue Paper Embosser Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Paper Embosser Machine Market Analytics
The EU Green Deal is hardening requirements for energy-efficient tissue converting equipment across European hygiene supply chains. Toscotec S.p.A. leverages its integrated approach to tissue line engineering to dominate premium embosser placements in Continental Europe. Fabio Perini S.p.A. anchors its competitive position through deep specialization in high-speed converting systems for consumer tissue rolls. A.Celli Group competes by extending its technology portfolio from winding through embossing to finished product handling.
A tissue paper embosser machine mechanically deforms tissue webs using patterned rollers to create bulk, softness, and absorbency in finished products, typically operating at speeds exceeding 600 meters per minute on multi-layer substrates. The primary commercial purpose centers on differentiating consumer tissue products through tactile quality while maintaining production throughput for bathroom tissue, paper towels, and facial tissue. Automatic configurations lead the product type dimension due to labor cost pressures in developed markets, while ultrasonic technology represents the fastest-growing segment as converters seek reduced energy consumption versus traditional heat transfer methods. Multi-head systems concentrate margin pools where tier-one manufacturers demand pattern complexity for premium private-label contracts.
The EU F-Gas Regulation and REACH compliance frameworks shape equipment specifications by restricting refrigerants in associated drying systems and governing chemical inputs in tissue softening agents that interact with embossed surfaces. FDA sanitary standards for tissue products sold into medical and food-service applications further constrain machine design through material contact surface requirements. Buyers must monitor how dual carbon goals in China and the EU Green Deal's evolving packaging rules redirect capital toward embossing lines with verified energy recovery systems and recyclable substrate compatibility.
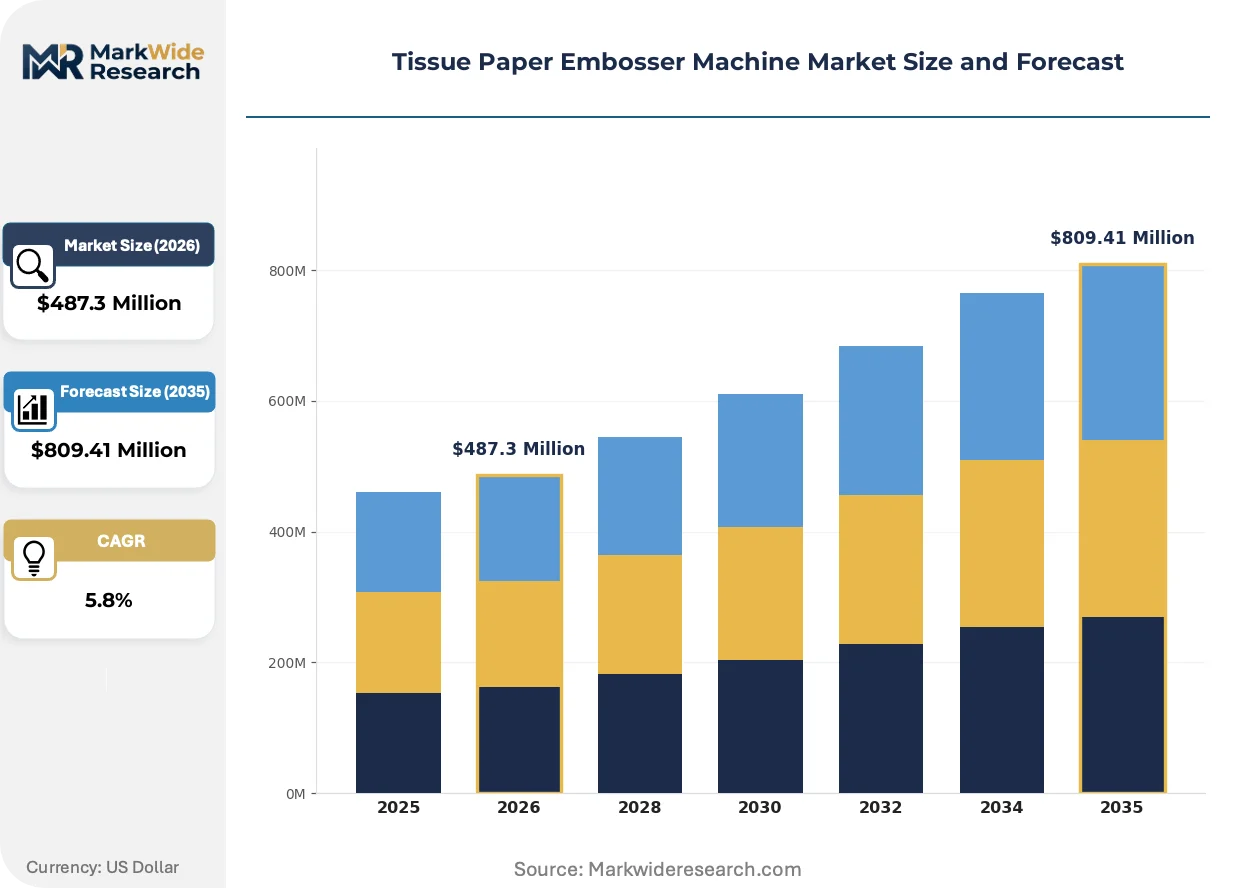
Market Dynamics
Ultrasonic embossing technology is compressing energy margins for traditional heat-transfer systems while the EU Green Deal accelerates capital rotation toward verified energy recovery architectures in tissue converting lines.
Growth Catalysts
- EU Green Deal packaging mandates:The regulation forces converters toward energy-efficient embossing systems with recyclable substrate compatibility, pulling replacement demand across Continental European mills.
- Consumer tissue capacity expansion:Household hygiene brands are scaling multi-layer substrate throughput to meet post-pandemic sustained demand for bathroom tissue and paper towels.
- Ultrasonic technology diffusion:This process reduces thermal energy consumption versus conventional heat transfer methods, attracting tier-one manufacturers seeking operational cost containment.
Market Restraints
- Specialized steel alloy volatility:Patterned roller manufacturing depends on precision-machined tool steel grades subject to raw material price swings and extended lead times from German and Japanese metallurgical suppliers.
- REACH chemical compliance friction:The framework restricts softening agent chemistries that interact with embossed tissue surfaces, complicating formulation R&D for converters serving EU markets.
- Technical speed-absorbency tradeoff:Multi-layer substrate processing above 800 meters per minute degrades pattern definition, limiting throughput gains for premium private-label contracts.
Strategic Opportunities
- India tissue mill modernization:The country's BIS standards adoption and PLI scheme incentives create openings for automatic embosser placements as domestic hygiene brands expand capacity.
- Medical-grade tissue certification:FDA sanitary standards for food-service and healthcare applications command price premiums, rewarding embosser configurations with validated contact surface materials.
- Digital pattern control convergence:Integration of real-time vision systems with servo-driven roller positioning enables rapid pattern changeover, reducing downtime for short-run private-label contracts.
Industry Challenges
- Mechatronics skill scarcity:Servo-driven multi-head systems require technicians fluent in both mechanical roller alignment and programmable logic controller diagnostics, a combination rare in traditional converting workforces.
- Legacy line integration complexity:Retrofitting ultrasonic embossing modules into existing tissue lines demands custom mechanical interfaces and control system harmonization, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Paper Embosser Machine Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Head, Multi-Head, Automatic, Semi-automatic Technology: Heat Transfer, Infrared, Ultrasonic, Flexographic End User: Manufacturers, Distributors, Retailers, Wholesalers Application: Household, Commercial, Industrial, Medical |
| Companies Covered | Toscotec S.p.A., A.Celli Group, Barry-Wehmiller Companies, Futura S.p.A., Gambini S.p.A., Fabio Perini S.p.A., Paper Converting Machine Company, Kawanoe Zoki Co. Ltd., Cavalleri S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Paper Embosser Machine Market Evolving Landscape
Active pattern complexity requirements from private-label retailers are forcing embosser architectures toward modular multi-head configurations with rapid changeover capability.
Ultrasonic embossing is consolidating its position in energy-sensitive converting operations by eliminating thermal transfer steps entirely. Mid-cap tissue mills in Germany and Northern Italy are adopting this technology at accelerated procurement cycles. The shift is consolidating margin pressure on traditional heated-roller suppliers while enabling converters to document carbon footprint reductions for EU Green Deal compliance submissions.
REACH chemical restrictions are tightening specifications for tissue softening agents that deposit on embossed surfaces. The regulation forces reformulation of quaternary ammonium compounds and silicone-based softeners used in premium bathroom tissue grades. Consumer tissue brands serving EU markets are responding by qualifying embosser systems with reduced chemical dependency through mechanical bulk generation alone.
Retailer consolidation is compressing equipment specification cycles as fewer buyers control larger private-label contract volumes. Mass-market distributors in Germany and France now mandate pattern complexity tiers that differentiate shelf positioning, replacing the previous standard-premium binary. This concentration is most visible in Central European tissue supply chains where Aldi, Lidl, and Carrefour procurement teams dictate embosser feature sets through technical scorecards.
Tissue Paper Embosser Machine Market Segmentation
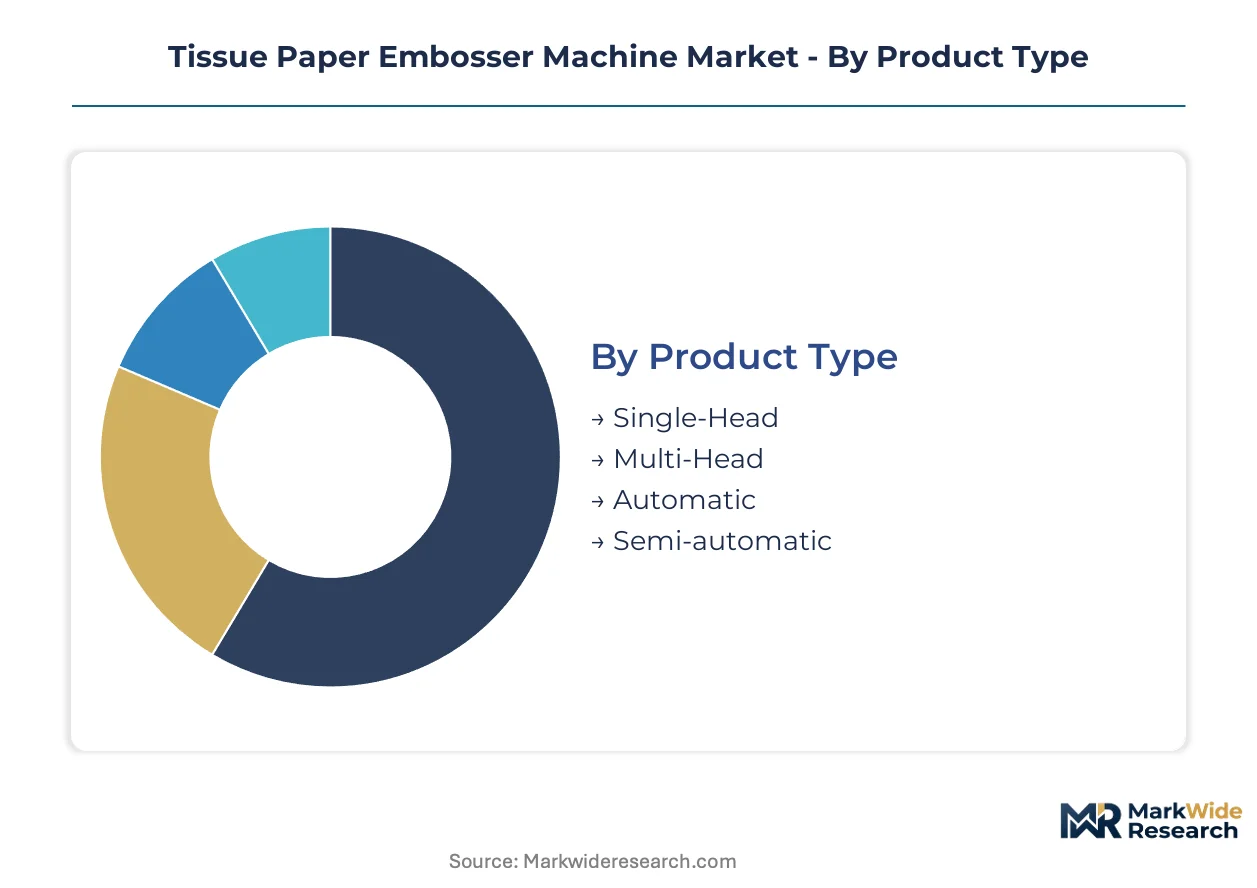
Tissue paper embosser machine segmentation reveals how capital deployment patterns align with substrate complexity and energy recovery requirements. Equipment buyers prioritize configurations that balance pattern definition fidelity against throughput economics in multi-layer converting lines.
Product Type:
Capital intensity varies sharply across head configurations, with servo-driven multi-head systems demanding the highest upfront investment for pattern complexity capabilities.
- Automatic:These systems integrate programmable logic controllers with vision-based quality monitoring to minimize operator intervention at speeds exceeding 600 meters per minute. Demand concentrates in German and Northern Italian mills where labor cost pressures and EU Green Deal energy documentation requirements drive procurement decisions.
- Multi-Head:Modular architectures enable rapid pattern changeover through servo-driven roller positioning, supporting short-run private-label contracts. Tier-one manufacturers serving Aldi, Lidl, and Carrefour technical scorecards in Central Europe concentrate demand here for shelf-positioning differentiation.
- Single-Head:Fixed-pattern configurations serve volume-focused producers with standardized product lines and longer production runs.
- Semi-automatic:Lower capital entry point suits emerging market mills modernizing from legacy mechanical systems.
Most installed capacity flows through Automatic configurations. Expansion is steepest in Multi-Head systems.
Technology:
Energy architecture determines operating cost trajectories, with thermal-based methods facing margin compression against electricity-efficient alternatives.
- Ultrasonic:Eliminates thermal transfer steps entirely through mechanical vibration energy, reducing carbon footprint documentation for EU Green Deal compliance. Mid-cap tissue mills in Germany and Northern Italy are adopting at accelerated procurement cycles to meet packaging sustainability requirements.
- Heat Transfer:Conventional heated-roller systems retain installed base dominance but face replacement pressure as energy recovery architectures gain specification preference.
- Infrared:Selective surface heating reduces thermal mass requirements compared to full-roller systems, occupying a mid-tier efficiency position.
- Flexographic:Pattern printing integration suits applications requiring visual differentiation alongside tactile embossing in premium tissue grades.
Heat Transfer retains the largest installed base. Ultrasonic technology is gaining share fastest.
End User:
Procurement authority concentrates with entities controlling capital allocation for integrated converting lines versus standalone equipment purchases.
- Manufacturers:Tissue mills with in-house converting operations specify embosser configurations as part of integrated line engineering, prioritizing pattern complexity and energy recovery verification.
- Distributors:Equipment trading intermediaries serve smaller mills without direct supplier relationships, typically handling semi-automatic and single-head configurations.
- Retailers:Private-label procurement teams increasingly dictate technical specifications through scorecards that mandate pattern complexity tiers for shelf positioning.
- Wholesalers:Bulk tissue converters with limited customization requirements prioritize throughput economics over pattern flexibility.
Manufacturers control the majority of new capacity investment. Retailer procurement influence is expanding most quickly.
Application:
Regulatory certification requirements fragment demand across use cases, with medical and food-service applications commanding validated contact surface materials.
- Household:Bathroom tissue and paper towel production dominates volume, with post-pandemic sustained demand driving capacity expansion across consumer tissue brands. EU Green Deal packaging mandates are redirecting capital toward recyclable substrate compatibility.
- Medical:FDA sanitary standards for healthcare applications command price premiums, rewarding embosser configurations with validated stainless steel contact surfaces and documented cleaning protocols.
- Commercial:Food-service and institutional tissue applications face intermediate regulatory requirements between household and medical grades.
- Industrial:Wiping and process tissue applications prioritize absorbency and bulk generation over pattern aesthetics.
Household applications absorb the majority of installed capacity. Medical-grade certification represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mechatronics talent clusters in Germany and Northern Italy anchor the European tissue converting equipment supply chain, with precision machining expertise concentrated around Bologna and Stuttgart industrial corridors.
Germany
Mid-cap tissue mills in the Baden-Württemberg and Bavaria regions drive automatic embosser procurement for EU Green Deal compliance documentation. The F-Gas Regulation restricts refrigerants in associated drying systems, forcing equipment retrofits. Stuttgart-based metallurgical suppliers deliver precision-machined tool steel grades for patterned roller manufacturing with extended lead times.
Italy
Integrated tissue line engineering capabilities concentrate in the Bologna-Modena corridor, serving Central European private-label contracts with rapid pattern changeover requirements. REACH compliance frameworks govern chemical softening agents interacting with embossed surfaces. Northern Italian converters are adopting ultrasonic technology at accelerated procurement cycles to meet packaging sustainability mandates.
United States
Consumer tissue brands in the Southeast and Midwest are expanding multi-layer substrate capacity for post-pandemic sustained bathroom tissue demand. FDA sanitary standards constrain machine design for medical-grade and food-service tissue applications. Wisconsin and Georgia industrial clusters host tissue mills specifying embosser configurations with validated stainless steel contact surfaces.
China
Domestic hygiene brands are modernizing converting lines under dual carbon goals redirecting capital toward energy recovery systems. The country's national packaging sustainability standards are tightening recyclable substrate compatibility requirements. Yangtze River Delta tissue mills are qualifying embossing equipment with verified carbon footprint documentation for export market access.
India
Domestic tissue mill modernization is accelerating under BIS standards adoption and PLI scheme incentives for automatic equipment placements. The central bank's industrial credit facilities support capital expenditure for hygiene product capacity expansion. Maharashtra and Gujarat industrial corridors are absorbing new embosser installations as regional hygiene brands scale production.
Tissue Paper Embosser Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor landscape where integrated line engineering specialists hold premium positioning against standalone equipment fabricators. The market structure concentrates margin pools among mid-cap European suppliers with captive metallurgical relationships, while Asian fabricators compete on throughput economics for emerging market mills. Two strategic archetypes dominate: integrated tissue line engineers bundling embossing with winding and converting, and precision roller specialists controlling patterned tool steel supply chains. Competitive moves center on technology licensing for ultrasonic modules and backward integration into servo-drive control systems.
Among Italian integrated line engineers, Toscotec S.p.A., A.Celli Group, and Fabio Perini S.p.A. occupy positions exemplifying the bundled equipment supply archetype. Toscotec S.p.A. represents the premium-tier vector where integrated tissue line engineering dominates Continental European placements. A.Celli Group sits within the technology portfolio extension archetype, spanning winding through embossing to finished product handling. Fabio Perini S.p.A. exemplifies deep specialization in high-speed converting systems, anchoring competitive positioning through focused expertise rather than horizontal expansion. These three S.p.A.-structured entities collectively illustrate how Italian industrial clustering around Bologna and Modena sustains competitive density in precision tissue converting equipment.
| Leading Market Players |
|---|
| Toscotec S.p.A. |
| A.Celli Group |
| Barry-Wehmiller Companies |
| Futura S.p.A. |
| Gambini S.p.A. |
| Fabio Perini S.p.A. |
| Paper Converting Machine Company |
| Kawanoe Zoki Co. Ltd. |
| Cavalleri S.r.l. |
| Others |
Value Network & Pricing Analysis
Ultrasonic embossing module adoption is compressing cost economics for traditional heat-transfer equipment while simultaneously concentrating supply relationships among German and Northern Italian metallurgical specialists capable of precision-machined tool steel delivery. This technology transition rewards converters with documented carbon footprint reductions for EU Green Deal compliance submissions while locking in premium pricing for servo-driven multi-head configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with differentiation driven by pattern complexity capabilities and energy recovery verification status. Premium multi-head systems with rapid changeover functionality command substantial uplifts over fixed-pattern single-head units serving volume-focused producers. Pricing pressure stems from Asian fabricators competing on throughput economics for emerging market mills, compressing margins in the semi-automatic tier. Tier-one manufacturers serving Aldi, Lidl, and Carrefour technical scorecards exhibit lowest price sensitivity due to private-label contract volume concentration, while smaller distributors trading standalone equipment show highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon documentation requirements are reshaping sourcing patterns for critical components across the equipment value chain. Precision-machined tool steel for patterned rollers draws from German and Japanese metallurgical suppliers with extended lead times, while servo-drive control systems and ultrasonic transducer modules rest on South Korean and Taiwanese electronics manufacturing clusters. Single-source vulnerability concentrates around Bologna-Modena corridor integrated line engineers controlling captive metallurgical relationships. Distribution runs through direct mill relationships for automatic configurations, with equipment trading intermediaries handling semi-automatic and single-head placements for smaller converters lacking direct supplier access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue paper embosser machine market functions as a stable compounder anchored by post-pandemic sustained hygiene product demand and regulatory-driven equipment replacement cycles across European and Asian converting operations.
For Market Incumbents: Anchor competitive position through backward integration into servo-drive control systems and ultrasonic module technology licensing, defending against Asian fabricators competing on throughput economics. Deepen captive metallurgical relationships with Stuttgart-based tool steel suppliers to secure pattern roller manufacturing capacity amid raw material volatility. Prioritize certification investment for FDA sanitary standards and EU Green Deal energy recovery verification to maintain premium positioning against emerging entrants. For New Entrants and Emerging Players: Mid-cap tissue mills in India's Maharashtra and Gujarat industrial corridors represent the most penetrable buyer archetype, with BIS standards adoption and PLI scheme incentives creating automatic equipment placement opportunities. Target medical-grade tissue certification as a white-space entry vector, where validated stainless steel contact surfaces command price premiums and incumbent concentration remains lower than household applications. Pursue technology licensing partnerships with established ultrasonic module suppliers rather than proprietary R&D development to compress time-to-market. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone equipment fabricators lacking integrated line engineering capabilities, as bundled supply archetypes capture premium multiples in Continental European placements. The market's long-term viability rests on regulatory compliance expenditure becoming embedded in converter capital allocation rather than discretionary investment. Monitor EU Green Deal packaging mandate enforcement intensity as the primary inflection signal, with accelerated procurement cycles for energy-efficient configurations indicating sustained replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Technology Licensing | Enables carbon footprint documentation for EU Green Deal compliance submissions without proprietary R&D investment. |
| Backward Integration into Servo-Drives | Captures margin pools in multi-head system positioning controls while reducing dependency on external electronics suppliers. |
| Medical-Grade Certification Investment | Unlocks FDA sanitary standard premiums for healthcare and food-service tissue applications with validated contact surfaces. |
| India Market Entry Partnership | Leverages PLI scheme incentives and BIS standards adoption to secure automatic embosser placements in modernizing mills. |
| Pattern Complexity Digitalization | Integrates real-time vision systems with servo-driven roller positioning for rapid changeover in short-run private-label contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with tissue mill engineering directors, OEM procurement teams, aftermarket service heads, and metallurgical supplier account managers alongside secondary validation. Primary intelligence drew from technical scorecard specifications issued by Aldi, Lidl, and Carrefour procurement teams, while secondary sources encompassed EU ECHA regulatory filings for REACH compliance frameworks, SEC 10-K disclosures from listed equipment fabricators, and customs trade data for precision-machined tool steel movements. Bottom-up capacity installation tracking across German, Italian, and Indian industrial corridors was triangulated against top-down market sizing derived from tissue converting line investment announcements.
Segment-weighting approaches distributed value estimates across automatic, multi-head, single-head, and semi-automatic product configurations, with technology segmentation spanning ultrasonic, heat transfer, infrared, and flexographic methods. End-user weighting reflected manufacturer versus distributor versus retailer procurement authority, while application segmentation differentiated household, medical, commercial, and industrial tissue grades. CAGRs were derived from regression analysis of historical capacity additions against regulatory compliance expenditure patterns, with forecast inputs incorporating EU F-Gas Regulation retrofit timelines and China's dual carbon goal enforcement intensity across the projection horizon.
Underlying measurement precision varies by segment; automatic and multi-head system data carry tighter precision than semi-automatic configurations due to concentrated supplier reporting, while ultrasonic technology adoption trajectories exhibit higher uncertainty than established heat transfer methods. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and raw material price stability, with revision risk concentrated in REACH chemical restriction scope expansion and specialized steel alloy supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Chocolate Wrapping Machine Market