
 North America Metal Cans Market | 2026-2036
North America Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Cans Market Analytics
The United States Gulf Coast is reconfiguring its beverage can supply base as new smelting and rolling investments come online. Ball Corporation leverages integrated aluminum sourcing to sustain cost advantages across North American beverage contracts. Crown Holdings Inc. anchors its position through high-speed two-piece can lines serving multinational brewers. Silgan Holdings Inc. competes on specialty-shaped and decorated cans for premium spirits brands.
North America metal cans are cylindrical containers fabricated from aluminum alloy or tinplate steel, typically ranging from 150 mL to 5 liters, formed through deep drawing or draw-and-iron processes and sealed with double-seamed lids to preserve contents against oxygen and light ingress. Their primary purpose is shelf-stable packaging for carbonated beverages, processed foods, aerosols, and industrial coatings. Aluminum soda and beer cans command the largest volume pools, while food cans in steel tinplate retain stable margins from institutional buyers requiring extended shelf life. Biodegradable coatings represent the fastest-evolving material segment as brands respond to consumer pressure on bisphenol-A migration concerns.
The US Food and Drug Administration governs food-contact substance compliance, while the EPA administers secondary aluminum smelter emissions standards that shape domestic metal sourcing economics. California's rigid packaging regulations and extended producer responsibility frameworks in Canadian provinces are forcing brand owners to document post-consumer recycled content thresholds. Stakeholders must monitor how state-by-state deposit legislation expansion and federal green procurement criteria will redistribute can sourcing obligations across the value chain.
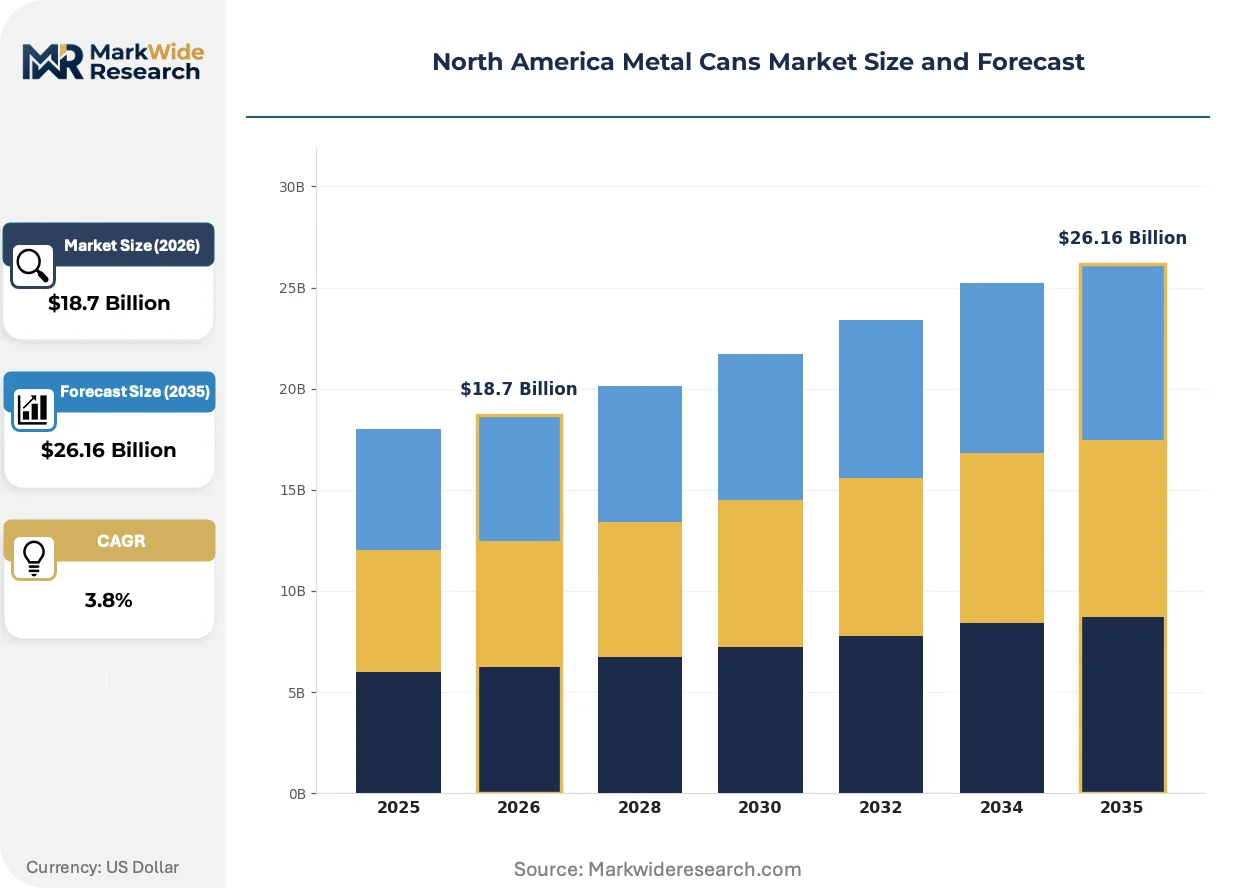
Market Dynamics
Aluminum can sheet capacity concentration along the US Gulf Coast is restructuring competitive economics as domestic smelting investments reduce import dependency and reshape regional supply contracts for beverage packaging.
Growth Catalysts
- Deposit legislation expansion:State-level container deposit frameworks in the US Northeast and Canadian provinces are mandating higher post-consumer recovery rates, forcing brand owners to source aluminum with documented recycled content thresholds.
- Craft beverage canning:Small-batch brewers and ready-to-drink cocktail producers are converting from glass to aluminum formats, driving demand for mid-volume canning lines and shorter production runs.
- Biodegradable coating chemistry:Non-BPA epoxy alternatives are achieving FDA food-contact approval, enabling brands to market bisphenol-free packaging claims without sacrificing shelf stability.
Market Restraints
- Primary aluminum input volatility:London Metal Exchange price swings for aluminum ingot compress rolling margins and complicate long-term contract pricing for can sheet suppliers.
- Smelter concentration risk:Domestic secondary aluminum supply clusters in Texas and Louisiana, exposing the value chain to hurricane disruption and regional power grid instability.
- Steel tinplate substitution ceiling:Food can applications requiring extended thermal processing cannot migrate to aluminum due to metallurgical limitations in high-temperature sterilization cycles.
Strategic Opportunities
- Mexico beverage manufacturing:Multinational brewers are expanding canning capacity in Baja California and central Mexico to serve export markets with lower labor and energy costs.
- Extended producer responsibility frameworks:Canadian provincial mandates for producer-funded recycling infrastructure create service revenue pools for can manufacturers offering closed-loop logistics.
- Digital printing convergence:UV-cured inkjet decoration technology is enabling mass-customization of can graphics, collapsing minimum order quantities for seasonal and promotional SKUs.
Industry Challenges
- Tooling engineer scarcity:Deep-drawing and die-maintenance expertise is aging out of the workforce faster than technical training programs in Ohio and Wisconsin can replenish qualified personnel.
- Legacy coating line conversion:Food can plants must retool solvent-based application systems to waterborne alternatives while maintaining FDA compliance and throughput rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Cans Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda Cans, Beer Cans, Food Cans, Paint Cans Material: Aluminum, Steel, Tinplate, Biodegradable Coatings End User: Food & Beverage, Household Products, Personal Care, Industrial Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Silgan Holdings Inc., DS Containers, Ball Corporation, Independent Can Company, CCL Container, Crown Holdings Inc., Mauser Packaging Solutions, Allstate Can Corporation, Ardagh Metal Packaging S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Cans Market Evolving Landscape
Active reshaping in metal can manufacturing centers on material substitution, regulatory compliance automation, and demand fragmentation across beverage subcategories.
Lightweighting through advanced aluminum alloy formulations is collapsing the gram-weight differential between standard and slim can formats. Premium spirits brands are adopting 250 mL and 200 mL slim profiles for single-serve cocktail positioning. This alloy innovation is collapsing the cost premium that previously constrained adoption outside carbonated soft drinks.
California's rigid packaging regulations and pending federal green procurement criteria are forcing documentation systems for post-consumer recycled content. The EPA's secondary smelter emissions standards are tightening metal sourcing compliance costs. Food can manufacturers serving institutional buyers are most affected, accelerating investment in automated chain-of-custody tracking.
Beverage brand procurement is fragmenting toward regional canning cooperatives and mobile canning services for seasonal production peaks. Craft brewers in the US Southeast are bypassing long-term supply contracts in favor of spot-market aluminum sourcing through independent brokers. This pattern is most visible in North Carolina and Virginia, where microbrewery density exceeds local canning capacity.
North America Metal Cans Market Segmentation
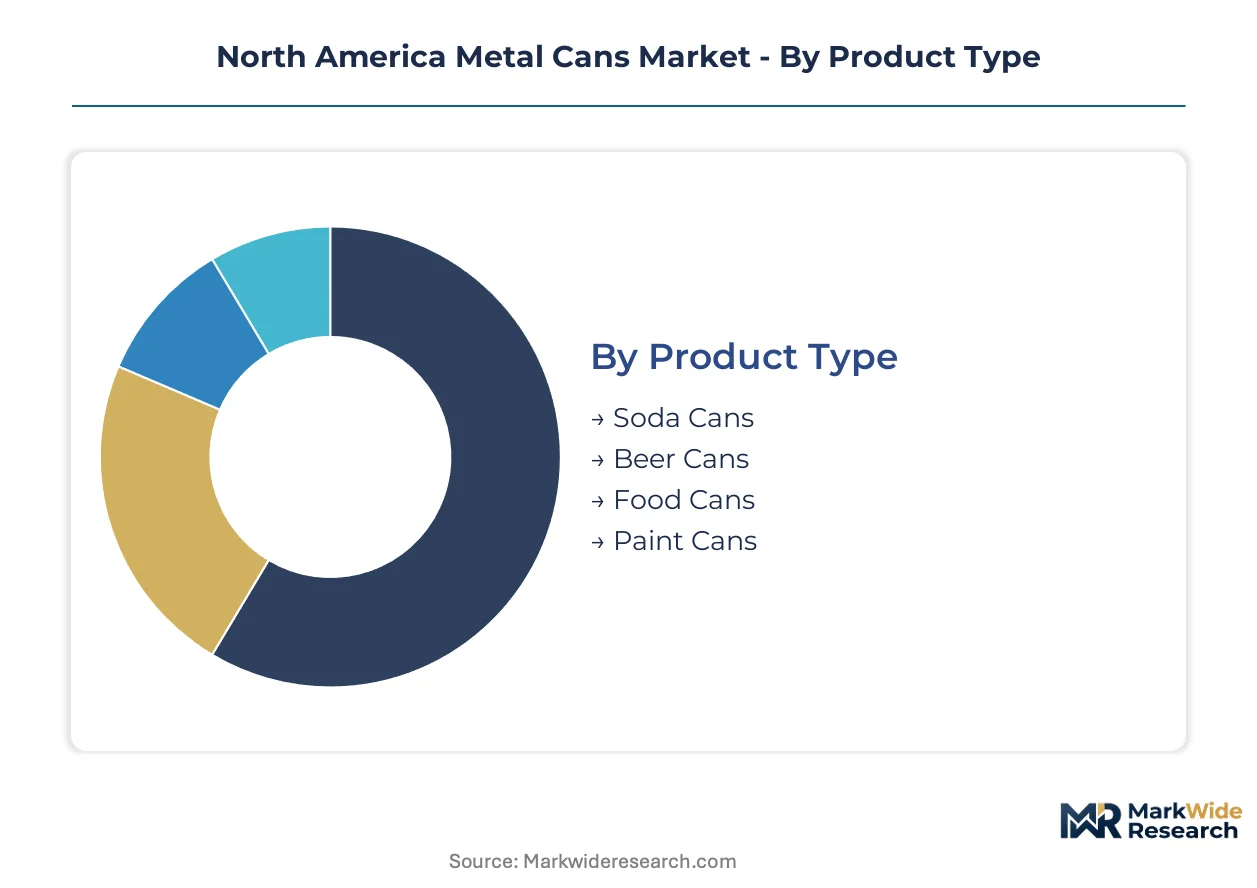
Segmentation in North American metal cans reveals distinct velocity profiles across product categories. Beverage formats turn inventory fastest while industrial applications anchor longer replacement cycles. Material choices and end-use specifications create divergent margin structures that reshape supplier priorities.
Product Type:
Beer cans rotate through supply chains fastest at seasonal peaks, while paint cans sit longest in distribution. Soda cans maintain the steadiest year-round velocity.
- Beer Cans:Two-piece aluminum construction with internal epoxy liners withstands carbonation pressure and pasteurization cycles. Craft brewers in North Carolina and Virginia drive spot-market sourcing for mid-volume runs, bypassing long-term contracts during peak summer demand.
- Soda Cans:Standard 12-ounce and 16-ounce formats dominate volume, with slim-profile variants gaining share in premium positioning. Major beverage contracts concentrate along the US Gulf Coast where integrated aluminum rolling reduces input cost volatility.
- Food Cans:Three-piece steel tinplate construction with double-seamed lids enables retort sterilization for shelf-stable proteins and vegetables. Institutional buyers in the US Southeast require extended shelf-life certification.
- Paint Cans:Lever-lid steel construction with solvent-resistant interior coatings serves architectural and industrial coatings manufacturers. Replacement cycles stretch 18-24 months versus beverage monthly turnover.
Soda cans dominate installed base. Beer cans are where expansion concentrates.
Material:
Cost tiers separate commodity aluminum from specialty substrates, with coating chemistry emerging as the premium differentiation layer.
- Aluminum:Alloy 3104-H19 sheet delivers the strength-to-weight ratio required for pressurized beverages. Domestic smelting investments in Texas and Louisiana are reducing import dependency for can sheet supply.
- Steel:Cold-rolled low-carbon substrate provides structural rigidity for food cans undergoing thermal processing. Tinplate integration protects against corrosion in acidic food matrices.
- Tinplate:Electrolytic tin coating on steel base metal enables soldered side seams in three-piece food can construction. California's rigid packaging regulations are forcing documentation of post-consumer recycled content thresholds.
- Biodegradable Coatings:Non-BPA epoxy alternatives using polyester or vinyl organosol chemistries achieve FDA food-contact compliance. Consumer pressure on bisphenol-A migration is accelerating conversion from legacy solvent-based systems.
Aluminum commands volume leadership. Biodegradable coatings are climbing the fastest.
End User:
Application maturity separates established beverage packaging from emerging personal care formats, with industrial demand showing highest price elasticity.
- Food & Beverage:Carbonated soft drinks, craft beer, ready-to-drink cocktails, and shelf-stable foods constitute the core demand pool. EPA secondary smelter emissions standards are tightening metal sourcing compliance costs for this segment.
- Household Products:Aerosol dispensers for cleaning agents and air fresheners utilize internal epoxy coatings to prevent chemical interaction. Canadian extended producer responsibility frameworks are creating service revenue pools for closed-loop logistics.
- Personal Care:Deodorant and hair spray aerosols require precision valve crimping and pressure-rated can bodies. Premium spirits brands are adopting 200-250 mL slim profiles for single-serve cocktail positioning.
- Industrial:Lubricants, adhesives, and coatings packaging prioritizes chemical resistance over shelf aesthetics. Spot-market aluminum sourcing through independent brokers serves seasonal production peaks.
Food & Beverage anchors revenue concentration. Personal Care is gaining share fastest.
Distribution Channel:
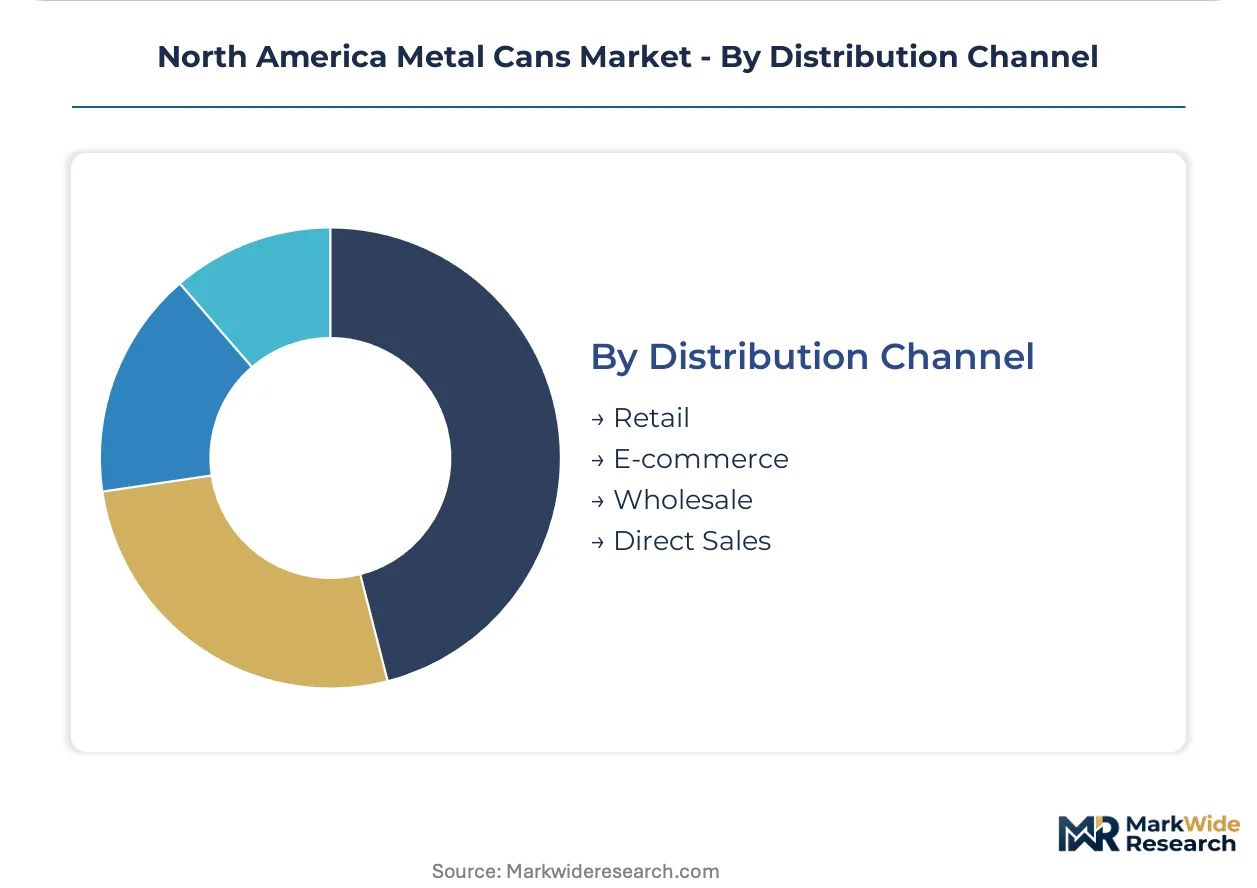
Customer type fragmentation is reshaping order economics, with direct sales capturing the largest accounts and e-commerce enabling smallest minimum quantities.
- Retail:Big-box and grocery chains procure through annual contracts with specified recycled content documentation. State-level container deposit frameworks in the US Northeast mandate recovery rate compliance.
- E-commerce:Digital-native brands source decorated cans through UV-cured inkjet platforms enabling mass-customization. Minimum order quantities are collapsing for seasonal and promotional SKUs.
- Wholesale:Distributors aggregate demand from regional canning cooperatives and mobile canning services. Spot-market sourcing peaks during craft beverage seasonal production cycles.
- Direct Sales:Multinational brewers and food processors negotiate integrated supply agreements with rolling mills and can manufacturers. Ball Corporation leverages captive aluminum sourcing to sustain cost advantages across North American contracts.
Direct Sales locks in volume concentration. E-commerce is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency anchors regulatory oversight across the dominant geography, with secondary smelter emissions standards tightening compliance costs for aluminum sourcing. State-level container deposit frameworks and provincial extended producer responsibility mandates are redistributing supply chain obligations.
United States
Craft brewers in North Carolina and Virginia drive spot-market aluminum sourcing for mid-volume canning runs. The EPA's secondary smelter emissions standards compress rolling margins for domestic sheet suppliers. Gulf Coast smelting investments in Texas and Louisiana reduce import dependency while exposing capacity to hurricane disruption.
Canada
Provincial extended producer responsibility frameworks mandate producer-funded recycling infrastructure. Health Canada and PMRA administer food-contact substance compliance parallel to FDA standards. Ontario and Quebec beverage canning cooperatives serve seasonal production peaks through mobile canning services.
Mexico
Multinational brewers expand canning capacity in Baja California and central Mexico for export market access. Lower labor and energy costs attract beverage manufacturing investment. The Bajío Region and Northern Border States concentrate new aluminum rolling capacity to serve cross-border supply contracts.
North America Metal Cans Market Competitive Landscape
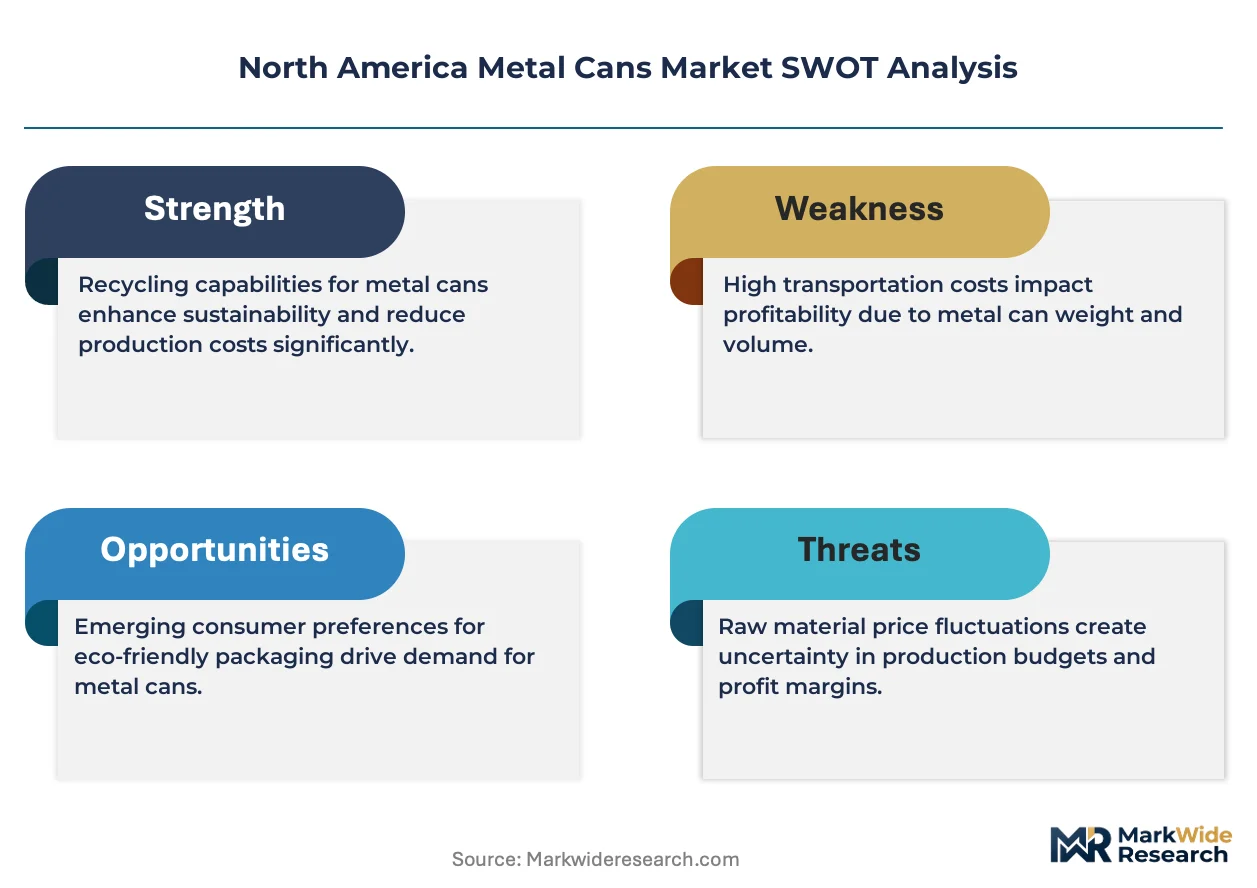
Vertically integrated multinationals and specialty fabricators split the market into distinct competitive tiers. Consolidation around captive aluminum supply and high-speed production lines favors scale players with Gulf Coast metal sourcing. Three archetypes dominate: integrated aluminum-to-can manufacturers, specialty decorated can specialists, and regional toll canning cooperatives. Capacity expansion and coating line conversion represent the dominant competitive moves as players respond to biodegradable chemistry mandates.
Within the integrated-manufacturer tier, Ball Corporation and Crown Holdings Inc. exemplify scale-driven positioning through captive metal supply chains. Silgan Holdings Inc. occupies the specialty-fabricator archetype, serving premium spirits brands with shaped and decorated formats. Ardagh Metal Packaging S.A. anchors the European-originated multinational segment with North American production assets.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| DS Containers |
| Ball Corporation |
| Independent Can Company |
| CCL Container |
| Crown Holdings Inc. |
| Mauser Packaging Solutions |
| Allstate Can Corporation |
| Ardagh Metal Packaging S.A. |
| Others |
Value Network & Pricing Analysis
Aluminum smelting investments in Texas and Louisiana concentrate upstream metal supply, redirecting margin pools toward Gulf Coast rolling mills and integrated can manufacturers with captive sheet sourcing. This geographic clustering compresses pricing power for independent converters while rewarding players with backward integration into primary metal production.
Pricing Analysis
Gulf Coast aluminum sheet commands a cost advantage over imported can stock from South Korea and Japan, though hurricane exposure introduces volatility premiums into long-term contracts. Pricing stratifies across premium, standard, and economy tiers based on recycled content certification and decoration complexity. Cost compression in standard beverage formats is intensifying because spot-market aluminum sourcing through independent brokers fragments volume leverage. Craft brewers in North Carolina and Virginia exhibit highest price sensitivity, while multinational brewers with direct mill relationships show lowest sensitivity due to hedged metal positions.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk as Section 232 aluminum tariffs reshape import economics for can sheet and tinplate steel. Domestic production draws from bauxite refineries in Texas and Louisiana, secondary smelters in the Ohio Valley, and rolling mills concentrated along the Gulf Coast. Single-source vulnerability clusters in electrolytic tin coating capacity for three-piece food cans, where domestic suppliers face limited qualified alternatives. Distribution runs through direct mill-to-plant contracts for multinational beverage accounts, with regional distributors serving craft canning cooperatives and mobile canning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aging workforce of deep-drawing tooling engineers and die-maintenance specialists constrains capacity expansion faster than technical training programs in Ohio and Wisconsin can replenish qualified personnel. This capability gap favors incumbents with institutional knowledge retention and structured apprenticeship pipelines.
For Market Incumbents: Entrench market position by securing captive aluminum supply through Gulf Coast smelting joint ventures or long-term offtake agreements with domestic rolling mills. Accelerate conversion of legacy solvent-based coating lines to waterborne biodegradable chemistries ahead of California's rigid packaging enforcement deadlines, using certification investment as a competitive moat against smaller converters lacking capital for compliance. For New Entrants and Emerging Players: Establish a beachhead in digital-printed decorated cans for seasonal craft beverage promotions, where UV-cured inkjet technology collapses minimum order quantities and spot-market aluminum sourcing through independent brokers neutralizes scale disadvantages. Target mobile canning services and regional canning cooperatives in the US Southeast, where microbrewery density exceeds local capacity and procurement patterns favor flexible short-run suppliers over integrated multinationals. For Investors and Strategic Acquirers: Capital is best deployed toward specialty-fabricator archetypes with proven biodegradable coating conversion capabilities and established relationships with premium spirits brands adopting slim-profile formats. Over the analysis window, acquisition targets should demonstrate defensible positions in personal care aerosols or food cans requiring thermal processing, segments where aluminum substitution faces metallurgical ceilings. The signal to watch is EPA enforcement intensity for secondary smelter emissions standards, which would accelerate consolidation among independent converters lacking compliance capital.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Gulf Coast captive metal supply secures cost advantages against import-dependent competitors during LME price volatility. |
| Biodegradable Coating Line Conversion | Non-BPA epoxy alternatives achieve FDA compliance while enabling bisphenol-free marketing claims for institutional food buyers. |
| Digital Printing Platform Deployment | UV-cured inkjet decoration collapses minimum order quantities for seasonal craft beverage SKUs and promotional campaigns. |
| Mobile Canning Service Partnerships | Regional cooperatives in North Carolina and Virginia aggregate fragmented craft brewer demand without fixed capacity investment. |
| Extended Producer Responsibility Logistics | Canadian provincial mandates create service revenue pools for closed-loop aluminum recovery infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with can manufacturing plant managers, beverage procurement directors, aluminum rolling mill executives, and EPA compliance officers; and secondary validation through SEC 10-K filings, American Can Association production surveys, LME aluminum price databases, and state-level container deposit legislation records. Bottom-up capacity modeling triangulated against top-down beverage consumption forecasts to reconcile volume estimates.
Forecast inputs included alloy formulation adoption curves, biodegradable coating conversion timelines, and regional canning capacity expansion announcements across the projection horizon. Segmentation dimensions spanned product type, material substrate, end-use application, and distribution channel, with CAGRs derived from regression analysis of historical production data against macroeconomic indicators. Industry-specific inputs incorporated EPA secondary smelter emissions compliance costs and California rigid packaging recycled content thresholds.
Stress conditions across aluminum price volatility, hurricane disruption frequency, and state-by-state deposit legislation expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about smelting investment completion rates and coating technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Aluminum Aerosol Cans Market