
 Chocolate Bar Packaging Market | 2026-2036
Chocolate Bar Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Bar Packaging Market Outlook
The premium and commodity tiers of chocolate bar packaging is rebalancing around material composition and shelf presence rather than unit cost alone. Amcor leverages its global film manufacturing network to supply high-barrier laminates for premium chocolate brands. Mondi Group anchors European demand with kraft-paper-based solutions that reduce plastic dependency. Smurfit Kappa Group competes through integrated cardboard supply chains serving private-label confectionery.
Chocolate bar packaging encompasses primary and secondary enclosures designed to protect cocoa-based products from moisture, oxygen, and light degradation while enabling brand communication at point of sale. Specifications typically include moisture vapor transmission rates below 1 g/m²/day and heat-seal strengths of 3–5 N/15mm for flow-wrapped formats. Wrappers and pouches lead volume consumption across retail channels, though boxes command higher per-unit margins in gift and seasonal segments. Paper and cardboard materials are gaining structural share as converters develop grease-resistant coatings that match plastic barrier performance.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material approvals and recycling claims across their respective jurisdictions. REACH compliance requirements in Europe restrict certain ink chemistries and adhesive systems used in direct food-contact layers. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in closed-loop recycling infrastructure or pivot toward certified compostable streams.
Market Dynamics
Material substitution pressure from the EU Packaging and Packaging Waste Regulation is compressing plastic dependency timelines across European chocolate supply chains. German confectionery exporters are accelerating specification upgrades for Asian retail channels, forcing converters to validate grease-resistant paper coatings at industrial scale.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are pulling molded pulp and compostable films into primary packaging specifications for premium artisan brands.
- Asian retail channel upgrading:Japanese and South Korean convenience store chains are demanding higher-barrier packaging for climate-controlled distribution, expanding addressable demand for European exporters.
- Barrier coating chemistry advances:Water-based grease-resistant treatments now achieve moisture vapor transmission rates below 1 g/m²/day, matching plastic performance in flow-wrapped formats.
Market Restraints
- Pulp fiber cost volatility:Molded pulp feedstock prices fluctuate with Nordic softwood harvest cycles and energy costs at Swedish and Finnish pulp mills.
- Compostable film supply concentration:Industrial-scale production of certified home-compostable barrier films clusters in Italy and the Netherlands, creating single-source risk for mid-tier converters.
- Heat-seal strength limitations:Bio-based sealant layers currently achieve 2–3 N/15mm versus 3–5 N/15mm for conventional laminates, restricting high-speed line compatibility.
Strategic Opportunities
- Indian organized retail expansion:Reliance Retail and D-Mart are scaling climate-controlled chocolate aisles, creating first-mover advantage for barrier-paper suppliers validating FSSAI food-contact compliance.
- Extended producer responsibility schemes:France's Citeo and Germany's Duales System Deutschland are funding closed-loop collection infrastructure that rewards mono-material packaging designs.
- Digital printing convergence with short-run flexibility:HP Indigo and Xeikon systems enable seasonal SKU proliferation without plate costs, serving gift-segment demand fragmentation.
Industry Challenges
- Migration testing timeline compression:REACH-compliant food-contact substance notifications require 12–18 month validation cycles, misaligning with retailer seasonal packaging refresh schedules.
- Legacy heat-seal equipment retrofit costs:Converters face six-figure capex per line to handle lower-temperature bio-sealant activation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Bar Packaging Market |
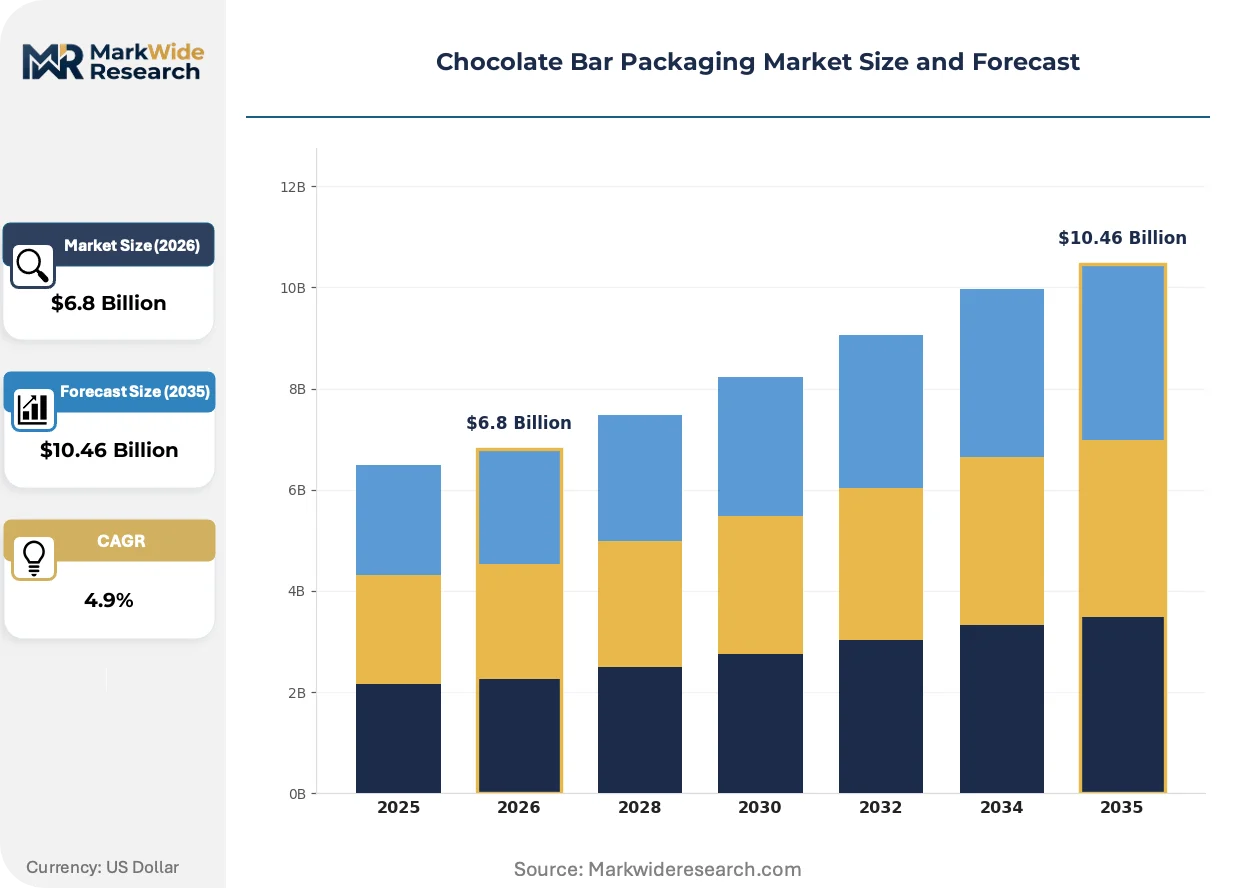
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Wrappers, Boxes, Pouches, Sleeves Material: Plastic, Paper, Aluminum, Cardboard Closure Type: Heat Seal, Resealable, Snap, Fold End User: Retail, Food Service, E-commerce, Exporters |
| Companies Covered | Constantia Flexibles, Sealed Air Corporation, Amcor, Smurfit Kappa Group, Huhtamaki, Mondi Group, Sonoco Products Company, WestRock, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Bar Packaging Market Strategic Shifts
Active reshaping in chocolate bar packaging centers on material science breakthroughs that enable plastic displacement without sacrificing shelf-life performance. Three interconnected developments are altering competitive positioning across the value chain.
Molded pulp thermoforming is modularizing primary packaging production for premium tablet formats. Swiss and Belgian artisan brands are piloting fiber-based trays with integrated grease barriers for direct food contact. This technology is compressing lead times for seasonal gift assortments while eliminating plastic window films through precision-formed pulp apertures.
REACH restrictions on specific ink chemistries and adhesive systems are forcing reformulation of direct food-contact layers across European converter operations. ECHA substance evaluations have flagged photoinitiator residues in UV-cured printing inks, triggering migration testing protocol updates. German packaging suppliers are responding by shifting to electron-beam curing systems that eliminate photoinitiator requirements entirely.
Retail buyer consolidation in German and French supermarket chains is compressing supplier qualification cycles and demanding just-in-time replenishment. Aldi and Lidl's private-label chocolate volume now flows through integrated cardboard supply chains with vendor-managed inventory clauses. This pattern is most visible in seasonal campaigns where packaging specification finalization occurs 8–10 weeks versus historical 16–20 week windows.
Chocolate Bar Packaging Market Segmentation
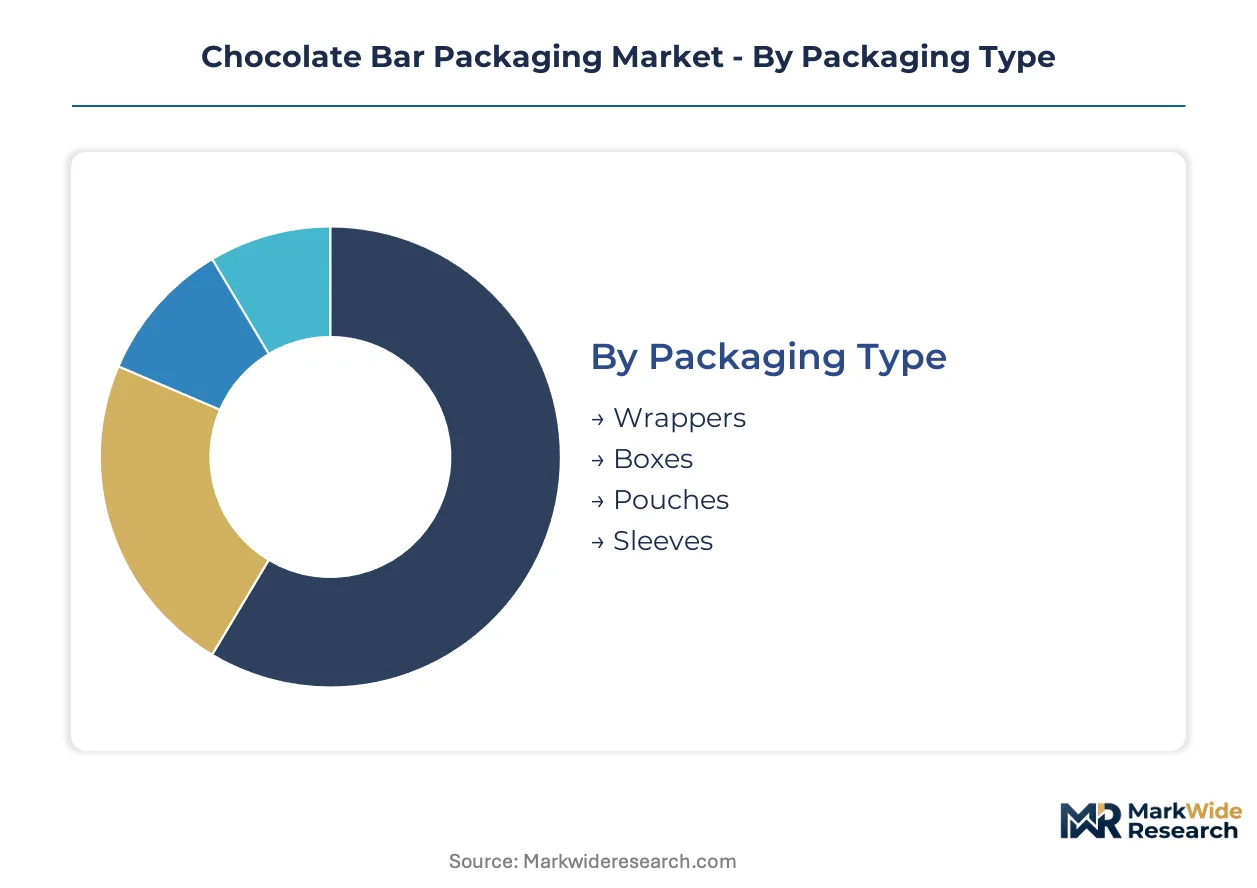
Chocolate bar packaging segmentation reveals divergent capital requirements across format types and material systems. Converters must align equipment investments with the specific barrier demands and line speeds of each segment.
Packaging Type:
Wrappers and boxes demand the heaviest upfront capital for high-speed rotary equipment and precision die-cutting systems.
- Wrappers:Flow-wrapped foil or laminate formats dominate volume throughput for single-serve tablets. German exporters are upgrading wrapper specifications for Japanese convenience store chains requiring moisture vapor transmission rates below 1 g/m²/day.
- Boxes:Rigid secondary packaging commands premium positioning in gift and seasonal assortments. Belgian artisan brands are piloting molded pulp trays with integrated grease barriers, compressing lead times for limited-edition releases.
- Pouches:Stand-up and flat formats serve multi-pack and sharing-size SKUs with lower equipment thresholds than wrappers.
- Sleeves:Band-style enclosures provide tamper evidence for premium tablets with minimal material input.
Wrappers absorb the bulk of installed capacity; boxes are expanding most quickly.
Material:
Material selection determines converter exposure to pulp fiber volatility and regulatory substitution timelines.
- Plastic:Multi-layer laminates with ethylene-based sealants retain dominance in high-barrier applications. REACH compliance requirements are accelerating reformulation of adhesive systems and UV-cured ink chemistries across European operations.
- Paper:Grease-resistant kraft and barrier-coated stocks are displacing plastic in flow-wrapped formats. Water-based treatments now achieve moisture vapor transmission rates matching conventional films, validating industrial-scale deployment.
- Aluminum:Foil laminates provide absolute light and oxygen barrier for ultra-premium dark chocolate with extended shelf-life targets.
- Cardboard:Integrated supply chains serve Aldi and Lidl private-label volume with vendor-managed inventory clauses and compressed seasonal qualification cycles.
Plastic retains the largest installed base; paper is climbing the fastest amid EU Packaging and Packaging Waste Regulation mandates.
Closure Type:
Seal technology selection constrains line speed compatibility and bio-based material adoption.
- Heat Seal:Thermal activation of laminate layers achieves 3–5 N/15mm bond strength for high-speed flow-wrapping. Bio-based sealants currently reach only 2–3 N/15mm, forcing six-figure capex per line for temperature profile retrofit.
- Resealable:Pressure-sensitive adhesive strips enable multi-serve consumption patterns in sharing-size pouches.
- Snap:Mechanical interlock closures serve rigid box formats without adhesive dependency.
- Fold:Tuck-style cartons minimize material input for low-cost private-label tablets.
Heat seal dominates throughput capacity; resealable formats are gaining share fastest in climate-controlled retail channels.
End User:
End-user concentration shapes specification complexity and replenishment cadence.
- Retail:Supermarket and convenience store channels drive standardization around shelf-ready display formats. Reliance Retail and D-Mart in India are scaling climate-controlled chocolate aisles, creating first-mover opportunity for FSSAI-compliant barrier-paper suppliers.
- E-commerce:Direct-to-consumer shipment demands enhanced crush resistance and temperature stability for last-mile integrity.
- Food Service:Hospitality and catering bulk formats prioritize portion control and dispensing efficiency over shelf presence.
- Exporters:Cross-border shipment requires validation against multiple food-contact regimes including FDA notifications and Japan's positive list system.
Retail commands the greatest specification volume; e-commerce is expanding most quickly with distinct protective packaging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne anchors European converter activity for chocolate bar packaging, with the Rhine-Ruhr corridor hosting specialized laminate production serving German confectionery exporters.
Germany
Duales System Deutschland funds closed-loop collection infrastructure that rewards mono-material packaging designs. The EU Packaging and Packaging Waste Regulation compresses plastic dependency timelines across domestic supply chains. Bavarian converters validate grease-resistant paper coatings at industrial scale for Asian retail channel exports.
United States
FDA food-contact substance notifications shape material approvals and recycling claims across domestic jurisdictions. Premium artisan brands in Brooklyn and San Francisco pilot molded pulp trays with integrated grease barriers. Midwestern converters supply high-barrier laminates for climate-controlled distribution networks.
India
FSSAI food-contact compliance requirements create first-mover advantage for barrier-paper suppliers entering organized retail. Reliance Retail and D-Mart scale climate-controlled chocolate aisles in Maharashtra and Gujarat. Mumbai-based converters develop water-based grease-resistant treatments matching plastic barrier performance.
Japan
METI standards and Japan's positive list system govern cross-border packaging validation for imported chocolate products. Convenience store chains in Tokyo and Osaka demand higher-barrier packaging specifications. Kanto-region converters adapt heat-seal equipment for lower-temperature bio-sealant activation profiles.
Netherlands
Industrial-scale production of certified home-compostable barrier films clusters in Rotterdam and Eindhoven, creating single-source risk for mid-tier converters. REACH compliance requirements restrict specific ink chemistries across converter operations. Dutch suppliers serve Belgian artisan brands piloting fiber-based tray formats.
Chocolate Bar Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier technology and sustainability certification tiers. The vendor base organizes around three strategic archetypes: integrated paperboard conglomerates with captive pulp supply, specialized flexible film manufacturers with global laminate networks, and molded pulp specialists serving artisan brand volumes. Dominant competitive moves include capacity expansion in compostable film production and strategic partnerships between converters and retail private-label programs.
Among European-based integrated packaging groups, Mondi Group, Smurfit Kappa Group, and Amcor occupy positions across the paperboard and flexible film segments. Mondi Group exemplifies the kraft-paper-based solutions archetype reducing plastic dependency. Smurfit Kappa Group represents integrated cardboard supply chain positioning for high-volume retail programs. Amcor anchors the high-barrier laminate specialist tier with global manufacturing network coverage.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Sealed Air Corporation |
| Amcor |
| Smurfit Kappa Group |
| Huhtamaki |
| Mondi Group |
| Sonoco Products Company |
| WestRock |
| Berry Global |
| Others |
Value Chain & Pricing Dynamics
Nordic softwood pulp indices cascade through converter cost structures, compressing margins at Swedish and Finnish mills before transmitting into tiered pricing for barrier-coated kraft and molded pulp feedstocks. Buyers face escalating premiums for grease-resistant paper specifications as energy costs at pulp facilities feed through laminate and tray pricing.
Pricing Analysis
Barrier performance throughput anchors value-based pricing tiers across chocolate packaging specifications. Three-tier pricing structure across premium, standard, and economy levels separates aluminum-foil laminates for ultra-premium dark chocolate from kraft-paper solutions for mid-market tablets and commodity plastic wraps for private-label volume. Cost compression in standard-tier barrier paper is intensifying because water-based coating chemistry advances are democratizing performance once reserved for premium laminates. Private-label retail buyers exhibit highest price sensitivity, while Belgian and Swiss artisan brands prioritize shelf-life extension over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle high-volume laminate demand from German and Belgian confectionery exporters, while distributor networks serve mid-tier converters across Southern Europe. Supply concentrates in Sweden, Finland, and Italy for pulp fiber and certified compostable film production. Raw material dependencies center on Nordic softwood pulp, bio-based sealant resins, and aluminum foil for oxygen-barrier applications. Single-source vulnerability clusters in Rotterdam and Eindhoven industrial-compostable film production, where mid-tier converters face concentration risk. Distribution runs through integrated cardboard supply chains with vendor-managed inventory clauses for Aldi and Lidl private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
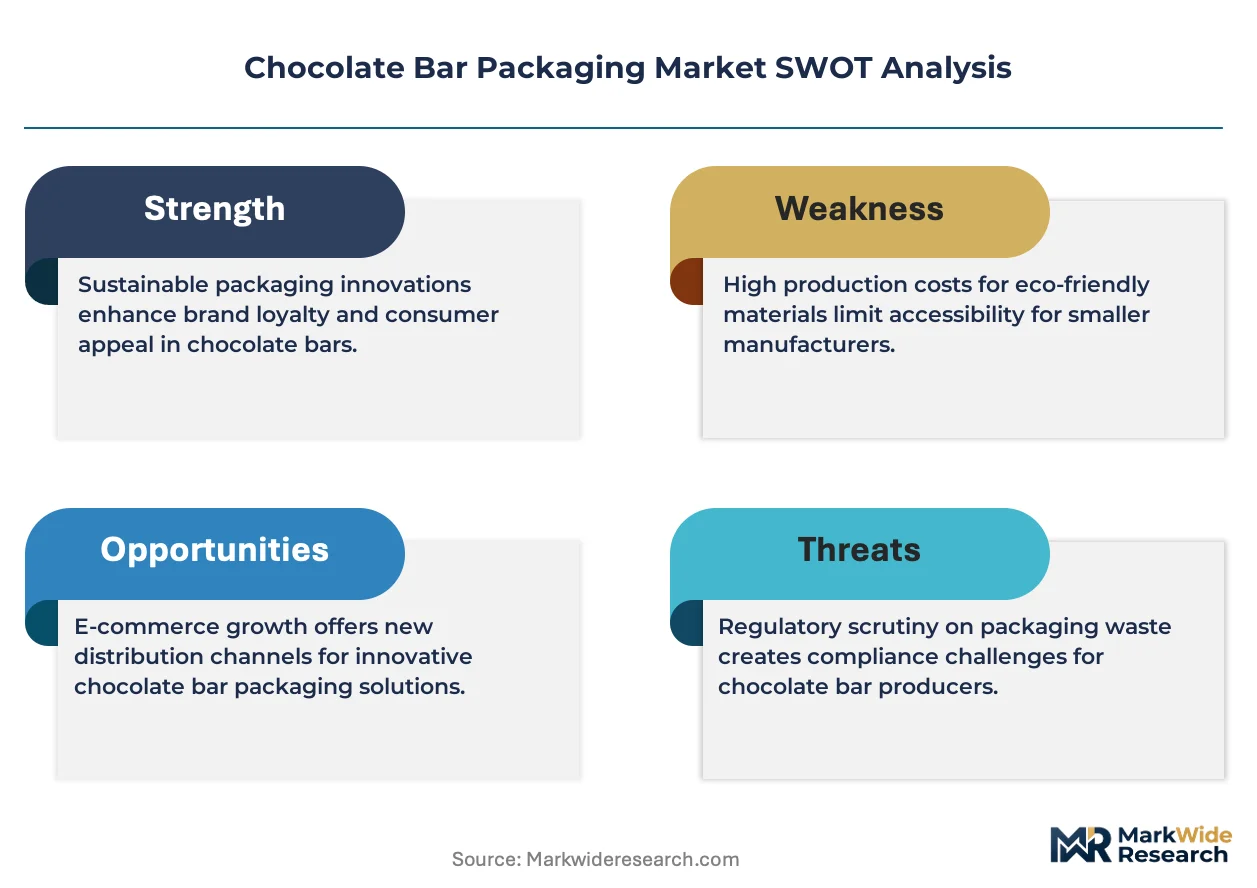
Industrial-scale compostable film capacity constraints are propping pricing premiums for REACH-compliant barrier solutions, creating supply-constrained conditions that favor incumbent converters with validated coating chemistries.
For Market Incumbents: Anchor market position through backward integration into Nordic pulp supply and captive grease-resistant coating production. Defend against Italian and Dutch compostable film specialists by accelerating FSSAI pre-validation for Indian organized retail entry. Prioritize electron-beam curing system deployment to eliminate photoinitiator migration risks flagged by ECHA substance evaluations. For New Entrants and Emerging Players: Indian artisan chocolate brands represent the most penetrable buyer archetype, with Reliance Retail and D-Mart scaling climate-controlled aisles ahead of barrier-paper supplier qualification. Target Maharashtra and Gujarat for first-mover FSSAI compliance positioning. Pursue digital printing convergence with HP Indigo or Xeikon systems to serve seasonal SKU fragmentation without plate cost barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor molded pulp specialists with validated grease-barrier technology in Belgium and Switzerland, where artisan brand volumes command premium positioning. Long-term viability hinges on mono-material packaging designs qualifying for France's Citeo and Germany's Duales System Deutschland closed-loop funding. Watch Japanese convenience store chain specification upgrades as inflection signal for European exporter demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic softwood access insulates converters from harvest-cycle price volatility. |
| Compostable Film Capacity Expansion | Industrial-scale production in Rotterdam and Eindhoven addresses single-source concentration risk. |
| FSSAI Pre-Validation Investment | Early compliance positioning captures Reliance Retail and D-Mart organized retail expansion. |
| Electron-Beam Curing Deployment | Elimination of photoinitiator residues satisfies ECHA migration testing protocol updates. |
| Digital Printing System Adoption | HP Indigo and Xeikon platforms enable seasonal SKU proliferation without plate cost penalties. |
Study Parameters
Document review covered EU Packaging and Packaging Waste Regulation filings, ECHA substance evaluation databases, and FSSAI food-contact compliance notifications, complemented by interviews with converter operations managers, confectionery brand packaging directors, and retail category buyers. Secondary validation drew from customs trade data, pulp mill production reports, and SEC filings of integrated packaging groups. Bottom-up demand modeling triangulated against top-down market sizing across material and format segments.
Installed capacity estimates and demand projections were generated across the analysis window by segmenting on packaging type, material system, closure technology, and end-user channel. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory substitution timelines and retail channel expansion patterns. Key inputs included Nordic softwood harvest cycle data, REACH compliance cost curves, and climate-controlled retail square footage buildout in India and Japan.
Revisions become necessary when EU Packaging and Packaging Waste Regulation implementation timelines accelerate, Nordic pulp fiber cost volatility exceeds historical bands, or Japanese convenience store specification upgrades stall. Forecasts reflect assumptions regarding barrier coating chemistry validation cycles and bio-sealant heat-seal strength improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Latin America Canned Food Packaging Market