
 Brass Foils Market | 2026-2036
Brass Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Brass Foils Market Analysis
Automotive electrification is rebalancing the end-use vertical mix away from traditional decorative applications and toward connector and terminal applications. Wieland-Werke AG leverages its integrated copper alloy portfolio to dominate European supply chains for EV conductive components. Aurubis AG anchors its position through captive copper refining and closed-loop recycling capabilities. Poongsan Corporation specializes in ultra-precise strip products for semiconductor lead frames across East Asian markets.
Brass foils are thin-gauge copper-zinc alloy strips, typically containing 60-70% copper with controlled lead content below specific thresholds, manufactured through cold rolling or hot rolling followed by annealing to achieve precise thickness tolerances and temper grades. Cold rolled foils command premium positioning in electronics interconnects where dimensional stability governs stamping yields, while annealed grades sustain volume demand from automotive terminal producers seeking optimized formability. Thin foils represent the fastest-growing thickness category as miniaturization trends in consumer electronics and medical device packaging compress component footprints.
Europe's REACH framework and RoHS directives constrain lead content in brass alloys, compelling reformulation investments across the supply base. China's SAMR enforces GB standards for copper alloy composition labeling, shaping import qualification protocols for foreign producers. Japan's METI promotes JIS-certified material traceability through its green supply chain initiatives. Stakeholders must monitor evolving alloy substitution patterns as regulatory thresholds tighten and end-users demand certified low-lead or lead-free formulations.
Market Dynamics
Automotive electrification is compressing gauge specifications across brass foil supply chains, forcing mills to retool rolling capacity toward sub-0.10mm thickness bands while maintaining conductivity thresholds for high-current EV connectors.
Growth Catalysts
- GB Standards Compliance:China's SAMR mandates enhanced copper alloy traceability, compelling domestic stampers to source certified foils and disqualifying uncertified imports.
- Semiconductor Packaging:Lead frame miniaturization in South Korea and Taiwan drives demand for ultra-thin annealed grades with sub-5 micron thickness tolerance.
- REACH RoHS Alignment:Europe's dual regulatory pressure on lead content accelerates reformulation investment toward certified low-lead alloys for automotive terminals.
Market Restraints
- Copper-Zinc Volatility:LME copper price swings and zinc concentrate shortages compress rolling margins, particularly for independent mills without captive smelting.
- German Supply Concentration:Precision stamping toolmakers cluster around Stuttgart and Nuremberg, creating single-source dependency risks for North American connector assemblers.
- Aluminum Substitution:Battery pack busbar applications increasingly specify aluminum alloys where conductivity-to-weight ratios favor mass reduction over copper performance.
Strategic Opportunities
- India PLI Scheme:Electronics manufacturing incentives under India's production-linked incentive program attract foil laminators to set up precision slitting operations near Chennai and Pune.
- Medical Device Miniaturization:Implantable electronics and diagnostic strip applications specify biocompatible low-lead formulations at premium price points.
- Closed-Loop Recycling:Japan's METI green supply chain certification rewards mills with verified scrap-to-foil traceability, opening preferential procurement channels.
Industry Challenges
- Precision Metallurgy Talent:Cold rolling expertise for sub-0.05mm foils concentrates among retiring Japanese and German engineer cohorts, constraining knowledge transfer.
- Multi-Standard Certification:Simultaneous JIS, ASTM, and EN compliance testing extends qualification timelines for new alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brass Foils Market |
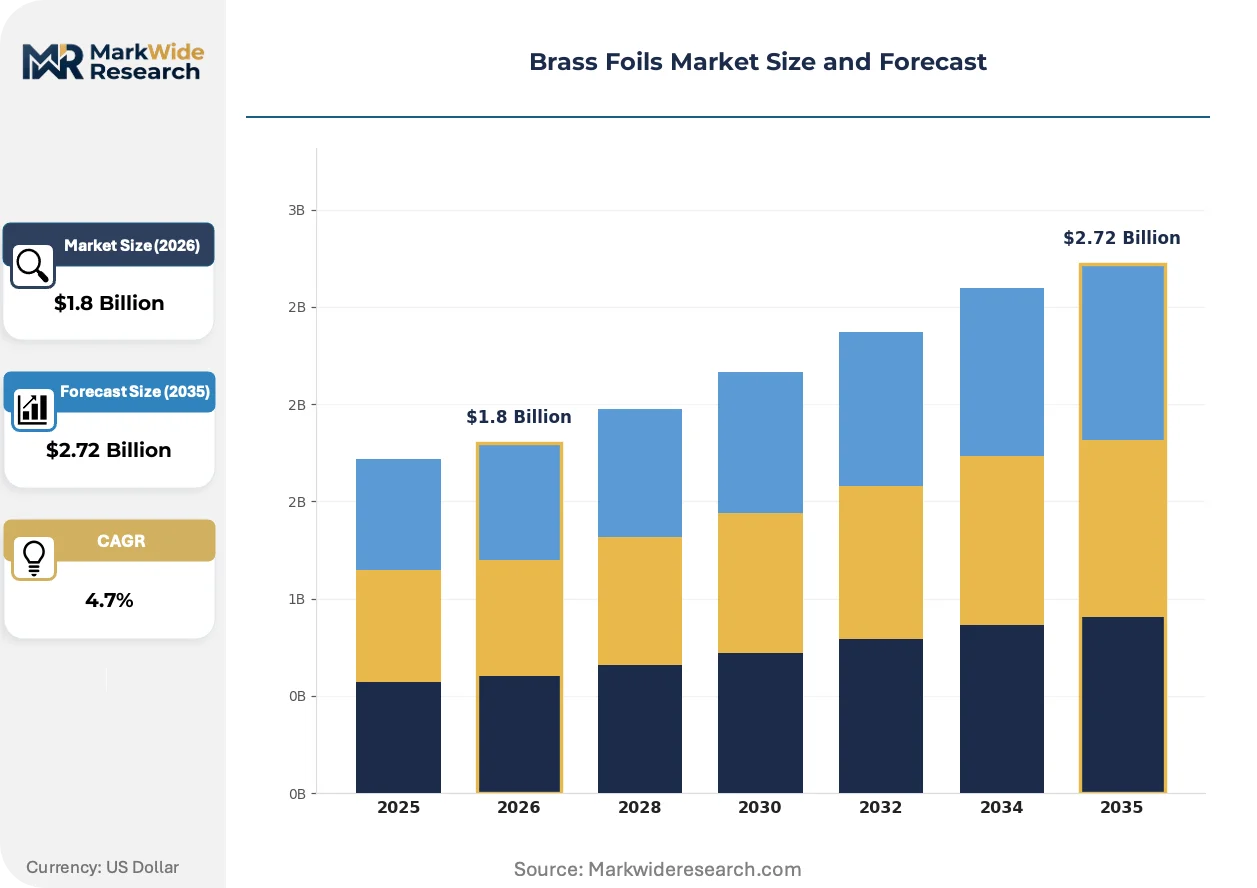
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Rolled, Hot Rolled, Annealed, Laminated Application: Electronics, Automotive Components, Decorative Items, Industrial Applications End User: Manufacturers, Electronics Companies, Automotive Firms, Craft Artists Thickness: Thin Foils, Medium Foils, Thick Foils, Ultra-Thin Foils |
| Companies Covered | Ningbo Jintian Copper, Wieland-Werke AG, Aurubis AG, CHALCO, Poongsan Corporation, KME Group, Mitsubishi Materials Corporation, Olin Brass, Mueller Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brass Foils Market Emerging Trajectories
Material science breakthroughs and regulatory stringency are converging to redefine brass foil specifications, with alloy reformulation and process automation emerging as decisive competitive differentiators.
Twin-roll casting is expanding into precision brass foil production, eliminating intermediate hot rolling steps and achieving direct gauge reduction from molten metal to cold-rollable strip. Japanese mills are adopting this continuous process for connector-grade foils, cutting energy intensity and enabling tighter thickness control. The technology is expanding into European supply chains as energy costs pressure traditional semi-continuous casting economics.
REACH Annex XVII restrictions on lead content in electrical equipment are compelling alloy redesigns across European automotive supply chains. ECHA's 0.1% weight threshold for homogeneous materials forces terminal producers to qualify bismuth-silicon modified alloys with equivalent machinability. German OEMs are accelerating supplier audits to verify compliance documentation ahead of 2027 enforcement milestones.
Consolidated procurement through mill-direct contracts is displacing distributor-mediated spot purchasing among tier-one automotive connector manufacturers. Buyers in South Korea and Japan are negotiating multi-year offtake agreements with attached technical service provisions, compressing working capital cycles for qualified suppliers. This concentration is most visible in semiconductor lead frame supply chains where traceability requirements exceed distributor capabilities.
Brass Foils Market Segmentation
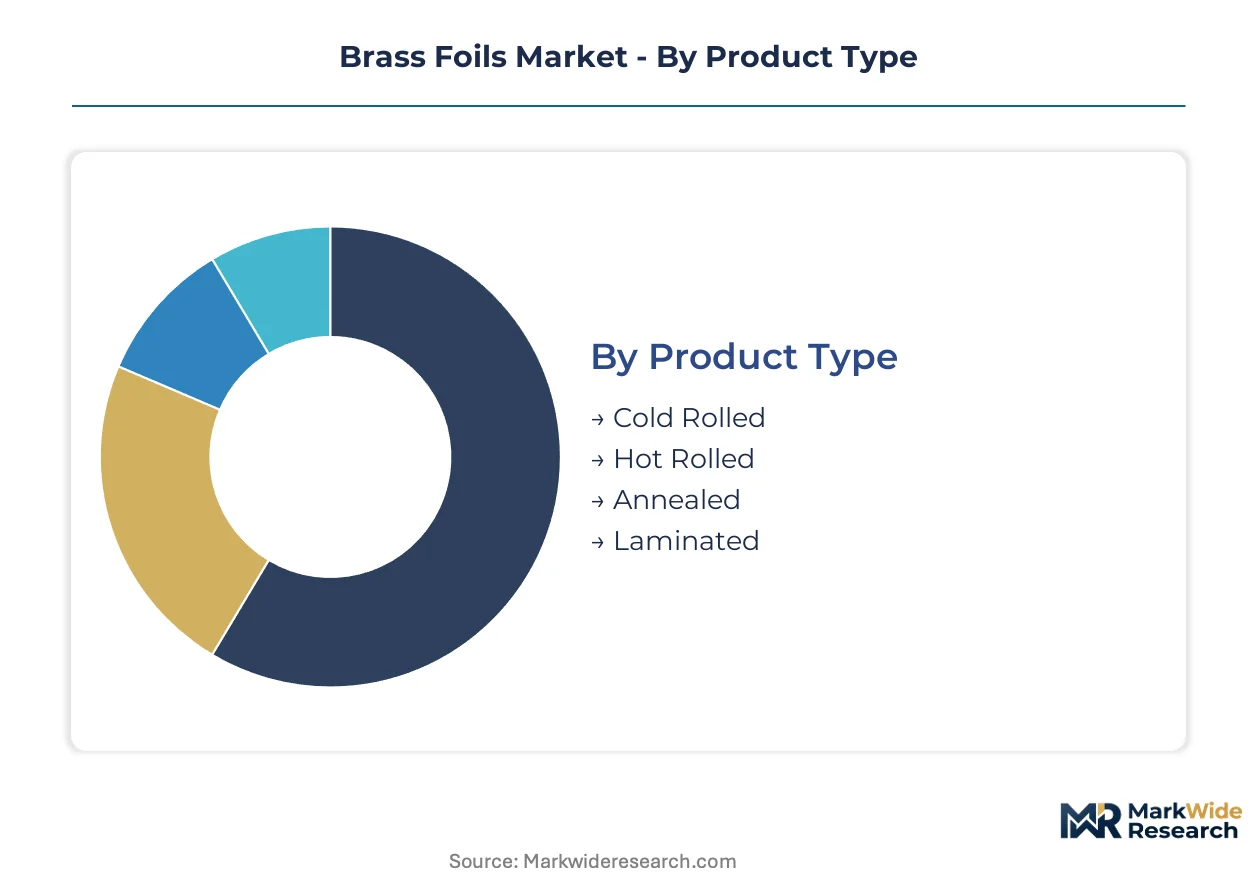
Brass foil procurement patterns diverge sharply across manufacturing processes and end-use specifications. Cold rolling precision governs electronics interconnect yields while automotive stampers prioritize annealed formability. Thickness bands below 0.10mm now command disproportionate investment attention from mills retooling for electrification demand.
Product Type:
Cold rolling and hot rolling processes create distinct metallurgical structures that determine downstream stamping performance and conductivity thresholds.
- Cold Rolled:Work-hardened microstructures deliver dimensional stability for precision stamping of semiconductor lead frames and high-density connectors. South Korean electronics assemblers specify sub-5 micron thickness tolerance for this grade, paying premium spreads over standard temper bands.
- Annealed:Recrystallized grain structures optimize ductility for complex terminal forming in automotive harness applications. German OEMs source this grade exclusively for EV connector programs requiring 180-degree bend performance without cracking.
- Hot Rolled:Coarser grain structures suit decorative and architectural applications where surface finish requirements are less stringent than electrical performance.
- Laminated:Polymer-bonded constructions insulate conductive layers in flexible circuit boards and medical diagnostic strips, commanding specialty pricing in biocompatible formulations.
Cold rolled leads on scale; annealed leads on momentum as automotive electrification accelerates gauge compression.
Application:
End-use specifications fragment procurement requirements across conductivity, corrosion resistance, and aesthetic demands.
- Electronics:Interconnect miniaturization drives sub-0.05mm specifications with JIS-certified traceability for semiconductor packaging in Japan and Taiwan.
- Automotive Components:Terminal and busbar applications specify lead-free alloys under REACH Annex XVII, forcing reformulation investments across European supply chains.
- Decorative Items:Architectural trim and luxury packaging sustain volume demand for polished surface finishes with traditional 60-70% copper content.
- Industrial Applications:Heat exchangers and corrosion-resistant gaskets specify medium-gauge bands with standardized temper grades for predictable forming behavior.
Electronics commands premium positioning; automotive components climbs fastest on electrification procurement shifts.
End User:
Customer scale and technical capability determine contract structures and qualification timelines.
- Manufacturers:Precision stamping houses in Stuttgart and Nuremberg dominate European connector supply with captive toolmaking and mill-direct procurement.
- Electronics Companies:Tier-one semiconductor assemblers negotiate multi-year offtake agreements with attached metallurgical support, compressing distributor margins.
- Automotive Firms:OEM connector divisions audit alloy certification documentation ahead of regulatory enforcement milestones.
- Craft Artists:Small-batch decorative applications source through distributor channels with limited traceability requirements.
Electronics companies lead on scale; automotive firms lead on momentum.
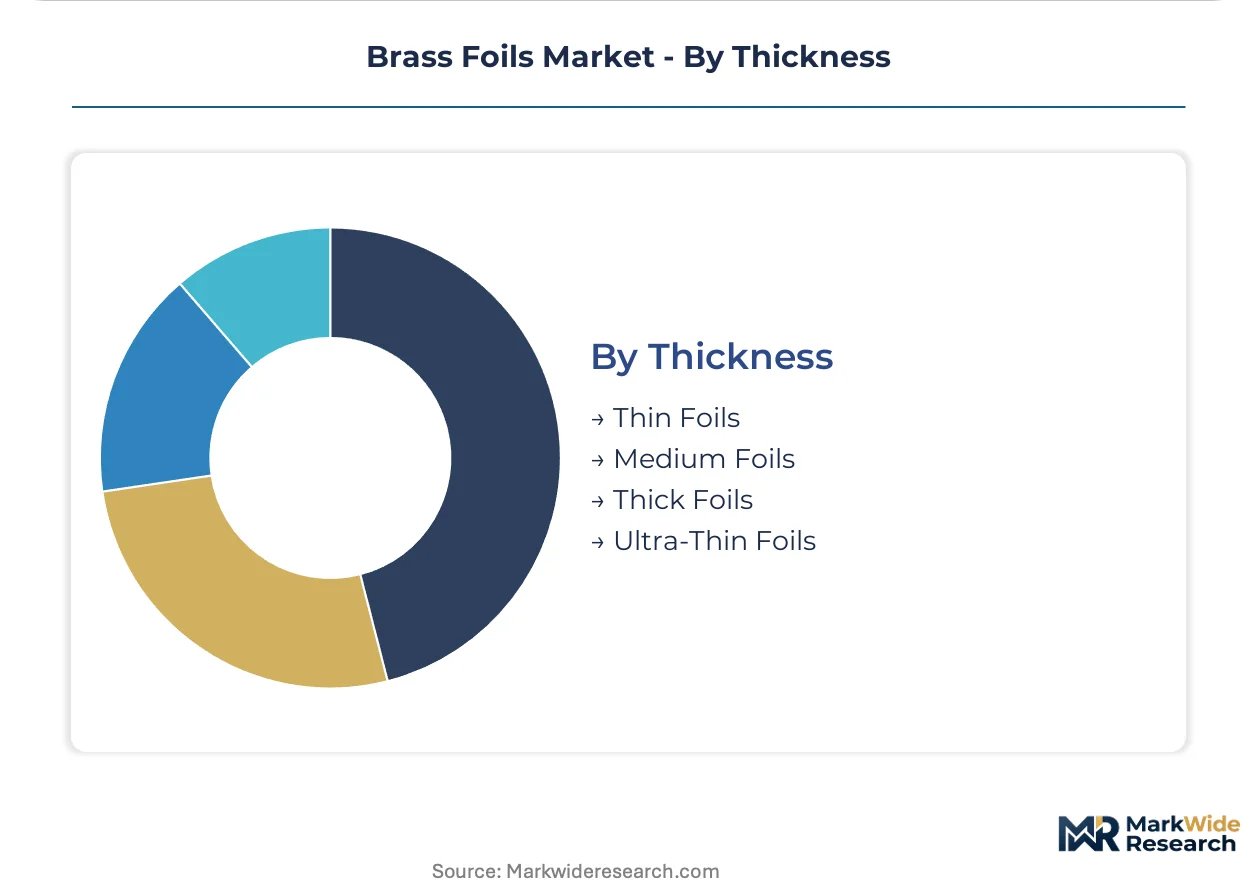
Thickness:
Gauge specification directly determines rolling mill configuration and energy intensity per output ton.
- Ultra-Thin Foils:Sub-0.025mm specifications for implantable medical electronics and advanced semiconductor packaging require specialized Sendzimir mills with limited global installed capacity.
- Thin Foils:The 0.025-0.10mm band captures connector and terminal demand from EV battery management systems and consumer electronics miniaturization.
- Medium Foils:Standard industrial gauges sustain volume production for heat exchangers and general stamping applications.
- Thick Foils:Above 0.20mm specifications serve decorative and architectural markets with lower technical barriers to entry.
Thin foils lead on scale; ultra-thin foils lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting brass foil production toward jurisdictions with integrated copper refining and lower compliance-cost structures. China and South Korea capture investment flows from European mills facing REACH-mandated alloy reformulation expenses. India's PLI scheme for electronics manufacturing is accelerating precision slitting capacity near Chennai and Pune.
Germany
Stuttgart and Nuremberg host precision stamping toolmakers supplying EV connector programs for BMW and Mercedes-Benz. ECHA's REACH Annex XVII enforcement drives terminal producers toward bismuth-silicon modified alloys with verified 0.1% lead thresholds. German OEMs audit supplier documentation ahead of 2027 milestones, compressing qualification timelines for domestic mills.
China
SAMR's GB standards for copper alloy traceability disqualify uncertified imports while channeling domestic demand toward qualified producers. Yangtze River Delta rolling mills retool for sub-0.10mm gauge bands serving battery management system connectors. Ningbo-based producers leverage integrated copper smelting to undercut European reformulation costs.
Japan
METI's green supply chain certification rewards mills with scrap-to-foil traceability, opening preferential procurement channels for semiconductor lead frame suppliers. Kansai region rolling houses specialize in sub-5 micron tolerance foils for advanced packaging applications. JIS-certified material documentation governs qualification protocols for Tokyo-based electronics assemblers.
South Korea
Busan-Ulsan corridor producers supply ultra-thin annealed grades to Samsung and SK Hynix semiconductor packaging lines. Domestic stampers negotiate multi-year offtake agreements with attached metallurgical support, displacing distributor-mediated spot purchasing. MFDS-aligned biocompatibility standards govern medical diagnostic strip applications at premium price points.
India
Chennai and Pune precision slitting operations serve electronics manufacturing incentives under the PLI scheme. BIS certification requirements for copper alloy inputs shape import substitution patterns among domestic connector assemblers. Maharashtra-based laminators expand capacity for flexible circuit board applications in consumer electronics supply chains.
Brass Foils Market Vendor Landscape
Capacity expansion dominates the current landscape as mills retool rolling lines for electrification-driven gauge compression. The vendor base stratifies between integrated copper majors with captive smelting and independent precision rollers serving niche electronics specifications. Three archetypes define positioning: alloy-integrated refiners, precision rolling specialists, and regional stamping houses with backward foil fabrication. M&A activity concentrates on acquiring Sendzimir mill capacity for ultra-thin foil production, while strategic partnerships between mills and automotive terminal producers lock in multi-year offtake volumes.
Among German-integrated copper majors, Wieland-Werke AG and Aurubis AG exemplify the alloy-integrated refiner archetype with captive smelting and closed-loop recycling capabilities. Poongsan Corporation occupies a specialist position within East Asian precision rolling, serving semiconductor lead frame demand with ultra-thin strip expertise. These three entities anchor distinct competitive vectors: European regulatory compliance, East Asian miniaturization specifications, and automotive electrification procurement.
| Leading Market Players |
|---|
| Ningbo Jintian Copper |
| Wieland-Werke AG |
| Aurubis AG |
| CHALCO |
| Poongsan Corporation |
| KME Group |
| Mitsubishi Materials Corporation |
| Olin Brass |
| Mueller Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
LME copper futures and zinc concentrate benchmarks cascade through brass foil supply chains into three-tier pricing structure across premium, standard, and economy levels. Cold-rolled grades for semiconductor lead frames command spreads over annealed automotive grades, while hot-rolled decorative bands absorb commodity volatility through volume scale.
Pricing Analysis
Distributor margins compress as mill-direct contracts displace spot purchasing among tier-one automotive connector manufacturers. Price differentiation rests on certification grade—JIS-certified traceability for electronics versus standard temper bands for industrial applications—and volume scale with multi-year offtake agreements. Cost compression in standard grades intensifies because Ningbo-based producers leverage integrated smelting, while premium tiers maintain pricing power through Sendzimir mill scarcity. Electronics assemblers in South Korea show least price sensitivity for sub-5 micron tolerance foils; decorative craft artists sourcing through distributors exhibit highest sensitivity.
Supply Chain Analysis
China's SAMR-mandated GB standards for copper alloy traceability reshape sourcing patterns, channeling domestic demand toward qualified Yangtze River Delta producers. Raw material dependencies draw from Chilean copper concentrate, Australian zinc ore, and domestic scrap recovery networks. Single-source vulnerability concentrates in German precision stamping toolmakers clustered around Stuttgart and Nuremberg. Distribution runs through mill-direct contracts for automotive and electronics tiers, with distributor channels serving decorative and small-batch industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brass foils function as a stable compounder anchored by automotive electrification's irreversible gauge compression toward sub-0.10mm specifications. Connector miniaturization sustains replacement demand across vehicle generations and electronics refresh cycles.
For Market Incumbents: Anchor market position through captive Sendzimir mill capacity acquisition and backward integration into scrap-to-foil closed-loop recycling. Aluminum substitution in battery pack busbars threatens copper-zinc terminal applications; defend through bismuth-silicon alloy reformulation investments ahead of REACH Annex XVII enforcement milestones. Prioritize JIS, ASTM, and EN multi-standard certification to extend qualification timelines into competitive moats. For New Entrants and Emerging Players: The premium-economy price-point gap in annealed automotive grades opens white-space opportunity in India's PLI-subsidized electronics corridors near Chennai and Pune. Target medical device miniaturization applications specifying biocompatible low-lead formulations at specialty pricing. Establish precision slitting operations with BIS-certified traceability to serve import-substitution demand among domestic connector assemblers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision rolling specialists possessing Sendzimir mill capacity for ultra-thin foil production. Five-to-ten-year viability favors mills with verified scrap-to-foil traceability qualifying for Japan's METI green supply chain certification. Watch twin-roll casting adoption rates as inflection indicator for energy-cost-competitive capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sendzimir Mill Capacity Acquisition | Ultra-thin foil capability locks in semiconductor lead frame supply chains with sub-5 micron tolerance. |
| Closed-Loop Recycling Certification | METI green supply chain verification opens preferential procurement channels from Tokyo-based electronics assemblers. |
| Bismuth-Silicon Alloy Reformulation | REACH Annex XVII compliance maintains European automotive terminal qualification ahead of 2027 enforcement. |
| PLI-Aligned Precision Slitting Expansion | India's electronics manufacturing incentives attract foil laminators to Chennai and Pune corridors. |
| Twin-Roll Casting Process Adoption | Japanese mills cut energy intensity while achieving direct gauge reduction from molten metal to cold-rollable strip. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured rolling mill operators, precision stamping procurement leads at German automotive Tier 1 suppliers, semiconductor packaging engineers in South Korea and Taiwan, and copper alloy metallurgists at integrated refiners. Secondary validation drew from LME price data, SAMR GB standard filings, ECHA REACH documentation, JIS certification registries, and customs trade flows. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included manufacturing process type, thickness band, application vertical, and regional production hub. CAGRs derived from rolling average substitution rates for aluminum in busbar applications and electrification-driven gauge compression trajectories. Forecast inputs incorporated copper-zinc price correlation coefficients and regulatory enforcement timeline assumptions.
Caveats apply where LME copper volatility, zinc concentrate supply disruptions, or accelerated aluminum substitution in battery applications could materially shift the outlook. Forecasts reflect assumptions about REACH Annex XVII compliance timelines and SAMR certification enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Europe Metal Cans Market