
 Latin America Food Cans Market | 2026-2036
Latin America Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Food Cans Market Insights
Capital-intensity divergence between integrated steel suppliers and downstream can fabricators is reorganizing competitive tiers across Latin America. Crown Holdings Inc. leverages its captive aluminum rolling capacity to secure raw material access in Brazilian and Mexican plants. Can-Pack S.A. anchors its position through dense manufacturing footprints in Poland and Latin America that sustain export flexibility. Trivium Packaging differentiates via decorated two-piece can technology for premium shelf appeal in Chilean and Argentine retail channels.
Latin America food cans are cylindrical metal containers fabricated from aluminum, steel, or tinplate substrates, typically formed through draw-and-wall-ironing or three-piece soldering processes, designed to provide hermetic sealing and shelf-stable preservation of processed foods for 24 to 60 months. Tinplate material type dominates volume across the region due to established steelmaking infrastructure in Brazil and lower unit costs for traditional three-piece vegetable and fruit cans. Aluminum product category lines, particularly for seafood cans and premium meat preparations, represent the fastest-growing structural segment as brands migrate toward lighter-weight, corrosion-resistant formats. Small and medium packaging sizes concentrate margin pools in urban Mexican and Colombian retail, where single-serve and household formats align with shrinking household sizes and convenience purchasing patterns.
ANVISA in Brazil enforces food-contact material migration standards that shape can lining formulations and supplier qualification protocols across the value chain. Mexico's Federal Commission for the Protection against Sanitary Risk (COFEPRIS) aligns with Codex Alimentarius guidelines while adding national heavy metal thresholds that filter import sourcing for tinplate substrates. Stakeholders must monitor pending harmonization between Mercosur technical regulations and Mexican NOM standards, as divergence in testing protocols would fragment compliance costs for multi-country suppliers.
Market Dynamics
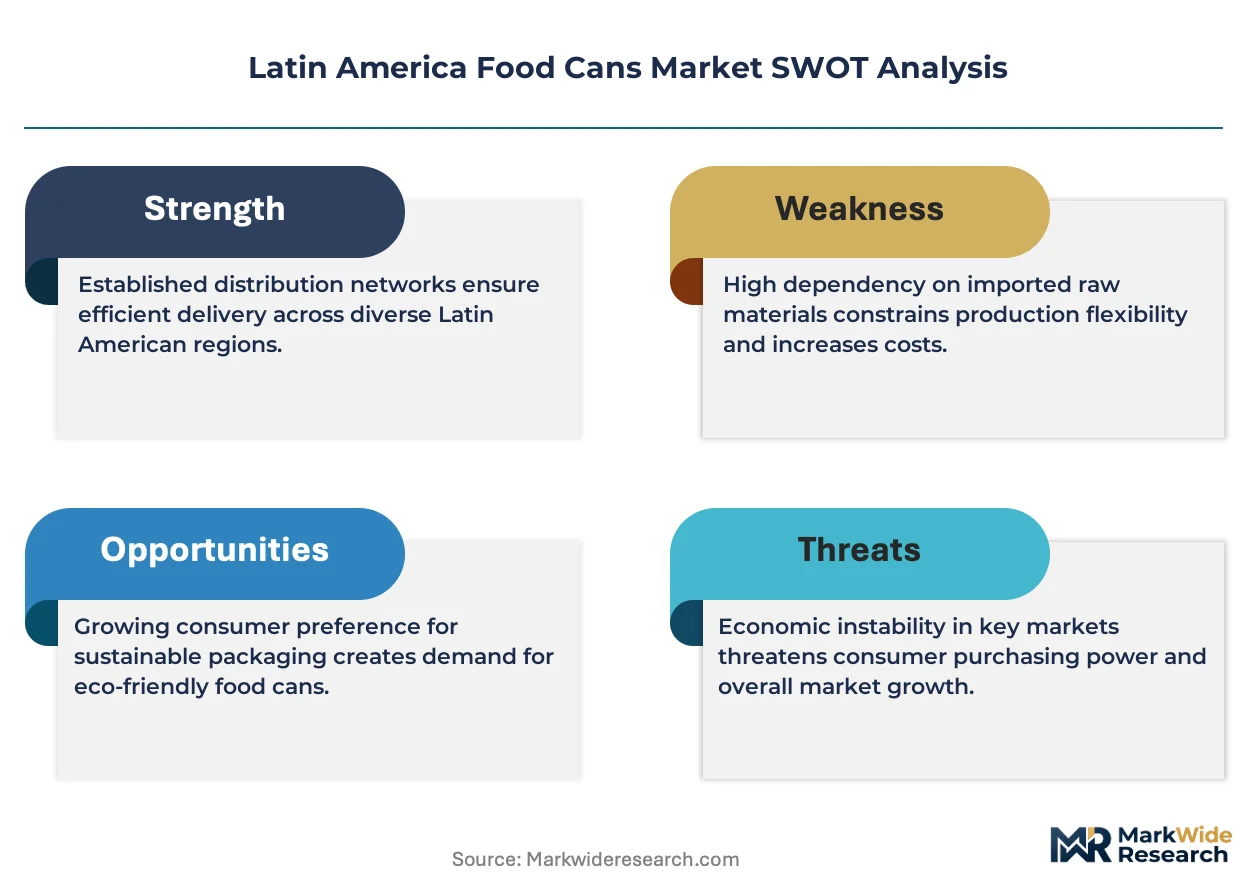
ANVISA migration limits for food-contact metal packaging are forcing can fabricators to reformulate interior coatings and requalify substrate suppliers across Brazilian and Mexican production networks.
Growth Catalysts
- COFEPRIS heavy metal thresholds:Mexico's national standards filter import sourcing for tinplate substrates, creating qualified supplier relationships that lock in domestic fabricator volumes.
- Draw-and-wall-ironing technology:Two-piece aluminum can production lines expand capacity for seafood and premium meat applications, displacing heavier three-piece formats in coastal processing zones.
- São Paulo state concentration:Brazil's industrial corridor clusters canning infrastructure within 200 kilometers of vegetable and fruit supply basins, compressing logistics costs for regional brands.
Market Restraints
- Steel input cost volatility:Tinplate substrate pricing fluctuates with Brazilian flat-rolled steel output, squeezing margin predictability for three-piece vegetable can specialists.
- Mercosur-Mexican NOM divergence:Pending harmonization gaps in migration testing protocols fragment compliance costs for multi-country suppliers serving both trade blocs.
- Flexible pouch substitution:Retortable plastic formats capture single-serve prepared meals in Colombian and Peruvian retail, eroding aluminum can penetration in convenience segments.
Strategic Opportunities
- Chilean and Argentine premium retail:Decorated two-piece can technology for shelf-stable seafood and specialty meats remains underpenetrated relative to Brazilian market development.
- Central Mexican industrial corridor expansion:Canning infrastructure capacity lags processed fruit output growth in Querétaro and Guanajuato states.
- Urban single-serve formats:Shrinking household sizes in Mexico City and Bogotá drive demand for 200-300 milliliter can sizes that command margin premiums over standard volumes.
Industry Challenges
- Coating chemist skill scarcity:BPA-NI and polyester lining formulation expertise concentrates with legacy European and North American additive suppliers, constraining local technical staffing.
- Line reconfiguration capex:Migration from three-piece soldering to two-piece DWI aluminum processes demands furnace and press investments that mid-scale fabricators cannot self-finance.
- ANVISA qualification timelines:New substrate supplier approval cycles extend 18-24 months, freezing sourcing flexibility during raw material disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Food Cans Market |
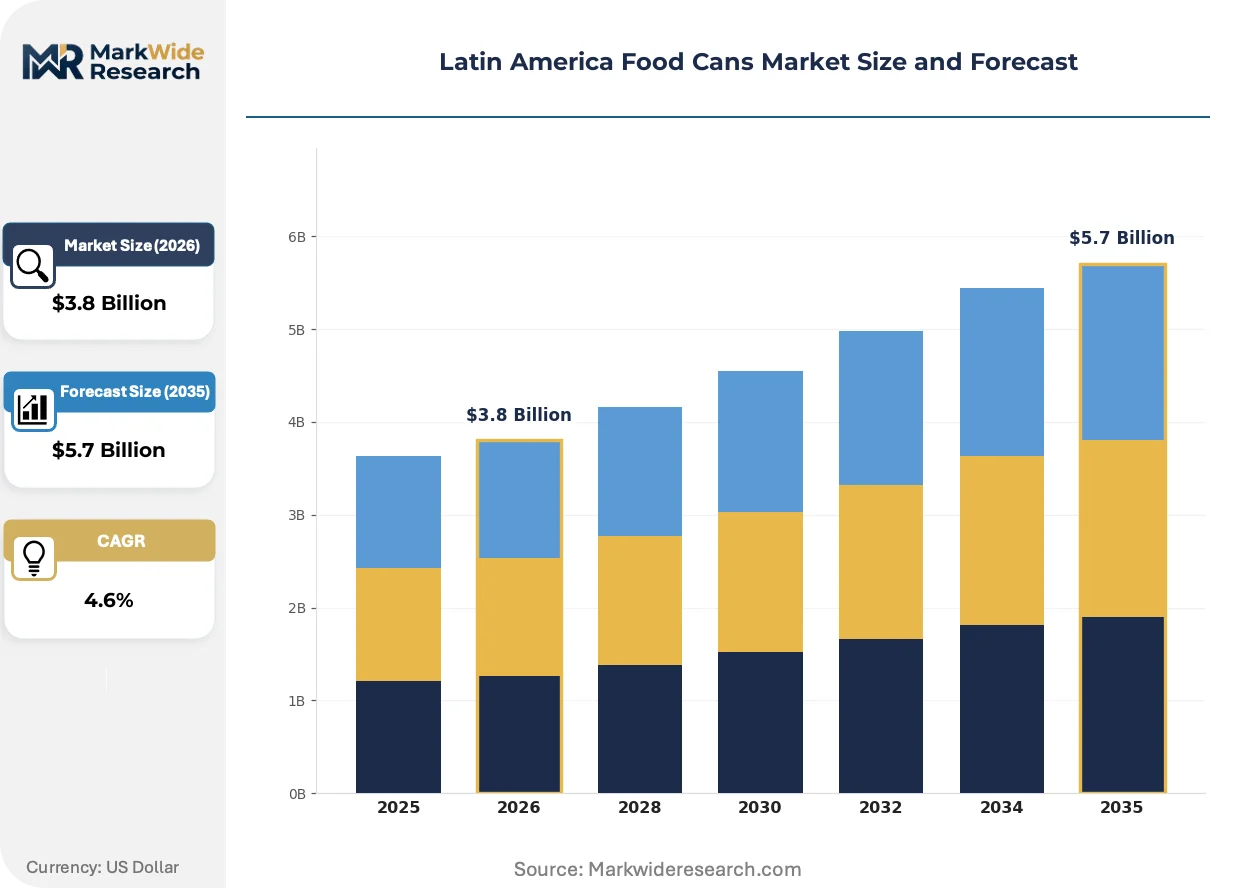
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Tinplate, Composite Product Category: Vegetable Cans, Fruit Cans, Meat Cans, Seafood Cans End User: Households, Food Service, Retail, Manufacturers Packaging Size: Small, Medium, Large, Jumbo |
| Companies Covered | Crown Holdings Inc., Ball Corporation, Can-Pack S.A., Silgan Holdings Inc., Ardagh Group, Trivium Packaging, Wells Can Company Ltd., Allstate Can Corp., Ball Metalpack, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Food Cans Market Trends and Innovations
Material substitution and regulatory stringency are compressing traditional format dominance while opening premium positioning pathways for aluminum and decorated substrates across Latin American retail channels.
Water-based interior coating systems are fragmenting the incumbent epoxy-phenolic lining standard in Brazilian can plants. ANVISA-compliant BPA-NI formulations from European additive suppliers now qualify at three major São Paulo-area fabricators. The technology is fragmenting supplier relationships as coaters decouple from legacy solvent-based chemistries and establish parallel qualification tracks with Asian resin alternatives.
COFEPRIS alignment with Codex Alimentarius guidelines, layered with supplemental Mexican heavy metal thresholds, is tightening substrate purity documentation requirements. Import tinplate lots now require batch-level spectrographic certification that domestic Brazilian steel mills already provide. Smaller Mexican can importers lacking laboratory partnerships face sourcing exclusion from retail grocery chain approved vendor lists.
Shrinkage in household sizes across Mexico City, São Paulo, and Bogotá is rotating demand toward smaller can formats. Single-serve 200-gram vegetable and fruit cans displace 400-gram family sizes in convenience store and online grocery channels. Colombian retail chains now stock three SKU tiers where two previously sufficed, compressing production run lengths and favoring fabricators with quick-change DWI press capabilities.
Latin America Food Cans Market Segmentation
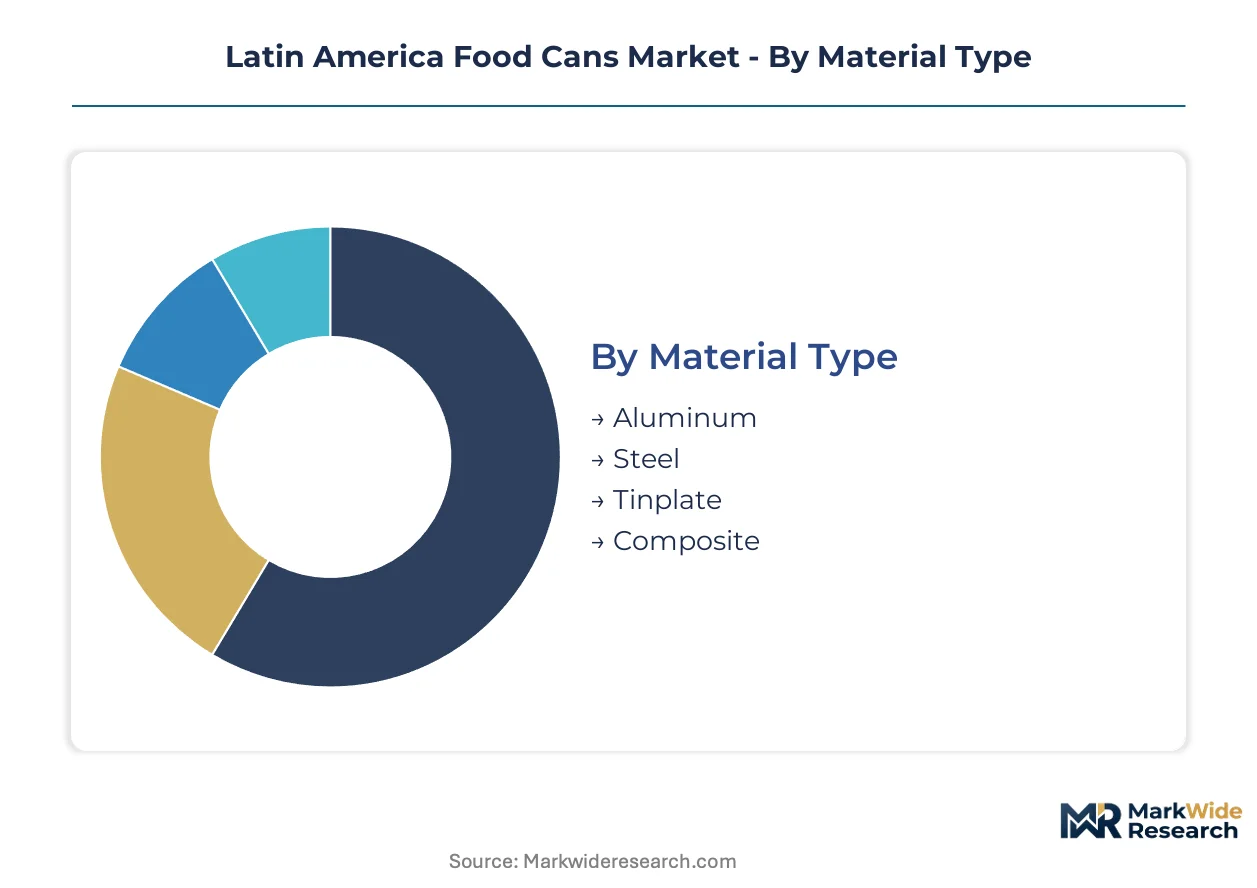
Food can segmentation across Latin America tracks divergent cost structures and regulatory pathways. Material chemistry and sizing specifications channel products toward distinct retail tiers and export qualifications.
Material Type:
Channel mix splits between mass-market grocery supply and export-certified premium lines, with substrate selection determining which retail doors open.
- Aluminum:Drawn-and-wall-ironed two-piece construction delivers corrosion resistance for seafood and premium meat applications. Coastal Brazilian and Chilean processors favor this format for export-grade shelf-stable products requiring extended maritime transit.
- Tinplate:Traditional three-piece soldered construction dominates São Paulo-state vegetable canning operations. Brazilian steel mills supply substrate at lower unit cost than imported alternatives, locking in regional brand relationships.
- Steel:Flat-rolled carbon steel substrates serve industrial-scale fruit canning in Mexico's central corridor. COFEPRIS heavy metal documentation requirements filter sourcing to certified domestic mills.
- Composite:Multi-layer paper-metal laminates address niche organic and specialty food positioning in Argentine natural product channels.
Tinplate dominates installed base. Aluminum is where expansion concentrates.
Product Category:
Cost tier stratification separates commodity vegetable processing from premium protein positioning, with margin capture varying threefold across the spectrum.
- Vegetable Cans:Tomato, corn, and bean formulations in 400-gram three-piece formats anchor volume across Mexican and Brazilian retail grocery. São Paulo-state infrastructure clusters compress per-unit logistics to national distribution networks.
- Seafood Cans:Tuna and sardine two-piece aluminum lines command premium shelf positioning in Chilean and Colombian supermarkets. ANVISA migration-compliant interior coatings qualify these products for cross-border Mercosur circulation.
- Fruit Cans:Peach and pineapple preservation in syrup drives medium-format demand through Mexico's central industrial corridor. Querétaro and Guanajuato processing expansion outpaces regional can fabrication capacity.
- Meat Cans:Luncheon meat and prepared protein formats concentrate in Brazilian urban convenience retail, with single-serve sizing gaining share in shrinking-household demographics.
Vegetable formats anchor volume throughput. Seafood applications deliver the steepest expansion trajectory.
End User:
Volume concentration tracks procurement scale, with manufacturer and retail channels consolidating specification power while food service fragments across regional operators.
- Retail:Supermarket and hypermarket chains in Mexico City, São Paulo, and Bogotá consolidate demand for standardized 300-400 gram household formats. Private-label expansion at Grupo Bimbo-affiliated and Carrefour Brazil networks concentrates sourcing among qualified fabricators.
- Manufacturers:Co-packing and ingredient supply relationships with processed food multinationals demand batch-level traceability documentation. COFEPRIS and ANVISA dual qualification requirements raise supplier switching costs.
- Households:Direct procurement through traditional markets persists in Peruvian and Colombian secondary cities, though modern retail conversion compresses this channel's share.
- Food Service:Institutional catering and restaurant prep kitchens in Brazilian mining and agricultural corridor towns drive jumbo-format demand with lower per-unit margin capture.
Retail channels dominate specification setting. Manufacturer direct sourcing is where contract consolidation concentrates.
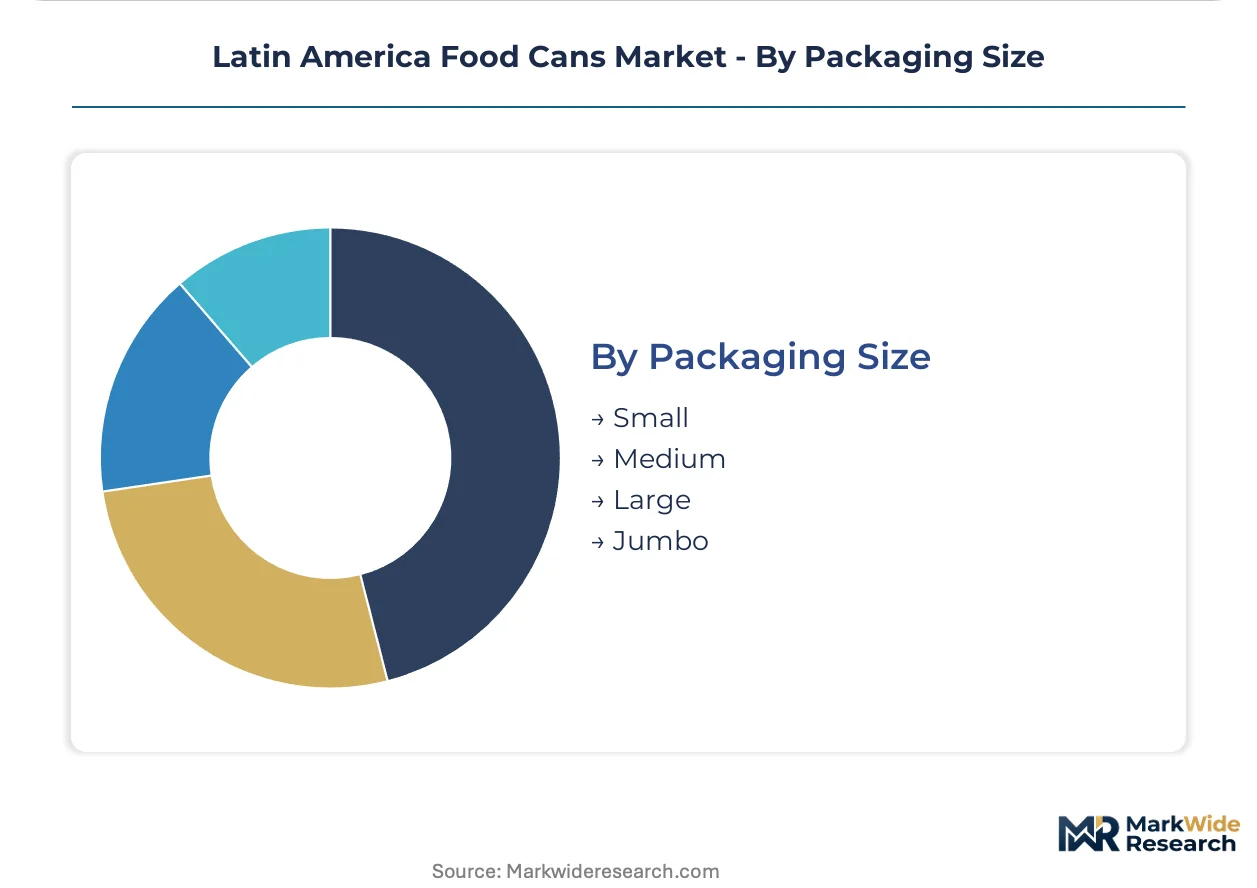
Packaging Size:
Customer type and household structure rotate demand toward smaller formats, with urban single-person and two-person households displacing traditional family-size procurement.
- Small:200-300 milliliter single-serve cans command margin premiums in Mexico City and Bogotá convenience networks. Quick-change DWI press capabilities at fabricators with Colombian and Mexican plants match shortened production runs.
- Medium:400-gram standard household formats retain volume leadership across Brazilian and Mexican mass retail. São Paulo-state canning infrastructure optimizes line efficiency at this specification tier.
- Large:800-gram family and small institutional formats concentrate in Brazilian interior states and Colombian Andean corridor towns with larger household sizes.
- Jumbo:1.5-3 kilogram industrial and food service formats serve mining camp catering and remote agricultural processing facilities across Chilean and Peruvian extractive zones.
Medium formats dominate current throughput. Small sizing is where capacity expansion and margin improvement jointly concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Colombia and Peru exhibit acute price sensitivity to tinplate substrate fluctuations, while Chilean and Argentine purchasers of premium seafood cans absorb aluminum cost premiums with limited volume elasticity. This demand-elasticity contrast shapes where fabricators anchor capacity versus where they test premium formats.
Brazil
São Paulo state hosts the continent's densest canning infrastructure cluster, with vegetable processors operating within 200 kilometers of steel mill supply. ANVISA migration limits for food-contact metal packaging force reformulation of interior coatings at fabricators serving retail grocery chains. Campinas and Sorocaba industrial zones concentrate draw-and-wall-ironing capacity expansion for aluminum seafood cans.
Mexico
Central industrial corridor states of Querétaro and Guanajuato drive fruit canning output growth that outpaces regional fabrication capacity. COFEPRIS heavy metal thresholds filter tinplate import sourcing to batch-certified suppliers, locking qualified fabricator relationships. Mexico City Metro convenience networks command margin premiums for 200-300 milliliter single-serve formats.
Chile
Coastal processing zones favor two-piece aluminum construction for export-grade shelf-stable seafood requiring extended maritime transit. Decorated can technology for premium retail positioning remains underpenetrated relative to Brazilian market development. Valparaíso and Concepción anchorage points concentrate canning infrastructure near Pacific fishing fleet operations.
Colombia
Bogotá urban retail rotates demand toward smaller can formats as household sizes shrink, with convenience store channels expanding SKU tiers from two to three per brand. Retortable plastic pouch substitution erodes aluminum can penetration in single-serve prepared meals. Medellín and Cali secondary cities sustain traditional market procurement patterns with slower modern retail conversion.
Argentina
Natural product channels in Buenos Aires and Córdoba generate niche demand for composite paper-metal laminates in organic food positioning. Macro-economic volatility compresses capital investment timelines for line reconfiguration toward two-piece aluminum processes. Rosario agricultural processing corridor sustains jumbo-format institutional demand for remote agricultural facility catering.
Latin America Food Cans Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Latin American food can fabrication. Integrated metal suppliers with captive rolling capacity anchor the cost-competitive tier for high-volume vegetable and fruit applications, while specialized decorators and coating innovators occupy premium positioning for seafood and meat preparations. Three strategic archetypes dominate: steel-integrated volume players, aluminum-specialist coastal fabricators, and quick-change flexible producers serving fragmented SKU demands. Competitive moves concentrate on furnace and press capacity expansion in central Mexican corridors, and strategic partnerships with European additive suppliers for BPA-NI coating qualification.
Among North American-based multinationals, Crown Holdings Inc. and Ball Corporation exemplify scale-driven archetypes with integrated aluminum supply chains. Can-Pack S.A. occupies a position within the European-anchored tier with dense manufacturing footprints sustaining export flexibility across Poland and Latin American markets. These three names anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Ball Corporation |
| Can-Pack S.A. |
| Silgan Holdings Inc. |
| Ardagh Group |
| Trivium Packaging |
| Wells Can Company Ltd. |
| Allstate Can Corp. |
| Ball Metalpack |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between São Paulo-state can fabricators and Brazilian steel mills lock in tinplate supply access while anchoring price visibility for three-piece vegetable can production. These arrangements insulate regional brands from spot market volatility in flat-rolled steel inputs, though aluminum substrate for two-piece seafood cans trades on shorter procurement cycles exposed to LME pricing swings.
Pricing Analysis
After-sales coating requalification services now drive lifetime value as ANVISA migration compliance extends customer relationships across 18-24 month approval cycles. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-compliant BPA-NI coated cans from legacy epoxy-phenolic formats and uncoated industrial grades. Price differentiation hinges on certification tier and volume scale, with COFEPRIS batch-certified tinplate commanding premiums over uncertified import alternatives. Cost compression in standard-grade three-piece cans is intensifying because Brazilian steel mill capacity expansions outpace demand growth. Small Mexican can importers exhibit acute price sensitivity, while Chilean seafood exporters absorb aluminum premiums with limited volume elasticity.
Supply Chain Analysis
Inventory lead times for European BPA-NI coating additives stretch 12-16 weeks, forcing Brazilian fabricators to hold larger safety stocks of qualified interior lining materials. Raw material supply concentrates in Brazil, Mexico, and Chile, with tinplate substrate drawn from Brazilian flat-rolled steel mills, aluminum coil from Mexican rolling operations, and seafood-grade two-piece cans from Chilean coastal fabricators. The value chain rests on tinplate steel, aluminum coil, and epoxy-phenolic resin inputs. Single-source vulnerability concentrates in European additive suppliers for BPA-NI formulations, where qualification switching costs freeze sourcing flexibility. Distribution runs through retail grocery chain approved vendor lists that filter smaller Mexican importers lacking laboratory partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where ANVISA-COFEPRIS regulatory interoperability creates ecosystem lock-in effects for qualified fabricators. Coating chemistry standardization across Mercosur and Mexican NOM frameworks would amplify network effects for early movers in dual-qualification capacity.
For Market Incumbents: Compound defensive positioning through captive aluminum rolling capacity expansion in Brazilian coastal zones and backward integration into BPA-NI coating formulation partnerships with European additive suppliers. Crown Holdings Inc. and Can-Pack S.A. anchor this consolidation logic. Flexible pouch substitution in Colombian prepared meals threatens aluminum can penetration in convenience segments, making quick-change DWI press capabilities the priority capability investment for SKU proliferation defense.
For New Entrants and Emerging Players: Lead with decorated two-piece can technology for premium seafood positioning in Chilean and Argentine retail channels, where shelf-appeal differentiation remains underpenetrated relative to Brazilian market development. Central Mexican industrial corridor expansion in Querétaro and Guanajuato states offers white-space capacity for fruit canning output growth outpacing regional fabrication supply. A co-packing partnership model with processed food multinationals bypasses retail grocery chain vendor list barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with quick-change DWI press capabilities and existing ANVISA qualification tracks, as these assets capture margin premiums from urban single-serve format proliferation across shrinking-household demographics in Mexico City and Bogotá. Long-term viability over a 5-10 year window hinges on regulatory harmonization execution between Mercosur technical regulations and Mexican NOM standards. The signal to watch is COFEPRIS adoption of batch-level spectrographic certification requirements for import tinplate, which would accelerate domestic mill preference and reshape import sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Crown Holdings Inc. secures raw material access in Brazilian and Mexican plants against LME volatility. |
| BPA-NI Coating Qualification Partnership | European additive supplier relationships lock in ANVISA-compliant formulation supply for São Paulo fabricators. |
| Quick-Change DWI Press Capacity Expansion | Colombian and Mexican plants match shortened production runs for 200-300 milliliter single-serve format proliferation. |
| Dual COFEPRIS-ANVISA Certification Investment | Multi-country suppliers reduce compliance fragmentation costs pending Mercosur-Mexican NOM harmonization. |
| Decorated Two-Piece Can Technology Deployment | Chilean and Argentine premium retail channels gain shelf-appeal differentiation for export-grade seafood positioning. |
Research Methodology
Cross-validation between primary interviews with coating chemists, can fabricator procurement directors, and retail grocery chain category buyers anchors the qualitative findings against secondary validation from ANVISA regulatory filings, COFEPRIS heavy metal threshold documentation, and Brazilian steel mill production disclosures. Plant managers at São Paulo-state vegetable processors, technical R&D directors at European additive suppliers, and channel sales heads at Mexican tinplate distributors contributed operational perspective. Customs records, SEC 10-K filings of North American packaging multinationals, and trade flow databases provided volume and value benchmarks. Bottom-up capacity assessments triangulate against top-down demand aggregation from retail SKU proliferation patterns.
Sensitivity analysis around steel input cost volatility and regulatory harmonization timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, product category, packaging size tier, and end-user channel structure. CAGRs derive from installed capacity utilization trajectories and line reconfiguration investment pipelines. Migration rates from three-piece soldering to two-piece DWI aluminum processes and urban household size shrinkage indices inform demand-side elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside ANVISA-COFEPRIS regulatory convergence or sustained steel mill capacity expansion would require recalibration. Forecasts reflect assumptions about coating chemist skill scarcity concentration and European additive supplier qualification timelines. Revision becomes warranted when flexible pouch substitution rates in Colombian and Peruvian retail cross thresholds that erode aluminum can penetration in convenience segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Brass Foils Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Metal Pails Market