
 Metal Packaging Market | 2026-2036
Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Packaging Market Intelligence
REACH compliance is decoupling European market access from legacy tinplate supply chains. Ball Corporation leverages integrated aluminum recycling to sustain cost advantages across beverage can volumes. Crown Holdings anchors North American food can production through specialized steel-coating capabilities. Ardagh Group SA competes in premium aerosol and specialty segments with differentiated shaping technologies.
Metal packaging comprises rigid and semi-rigid enclosures fabricated from aluminum, steel, tinplate, or stainless steel through deep drawing, three-piece welding, or two-piece drawing-and-ironing processes, engineered to provide barrier protection against oxygen, light, and moisture for shelf-stable goods. Aluminum leads beverage applications due to lightweighting and infinite recyclability, while steel dominates food containers where puncture resistance and retort compatibility matter; tinplate retains niche pharmaceutical and high-acid food roles despite slower growth. Material selection increasingly tracks regional recycling infrastructure maturity and energy-intensity thresholds rather than commodity cost alone.
EPA rules on industrial emissions shape US can manufacturing investment cycles, while EU F-Gas Regulation and CE marking constrain coating and sealing technologies. China's SAMR enforces GB standards for food-contact metals that dictate import specifications. Stakeholders must monitor how carbon-border mechanisms and extended producer responsibility frameworks redistribute competitive advantage between virgin and recycled feedstock positions.
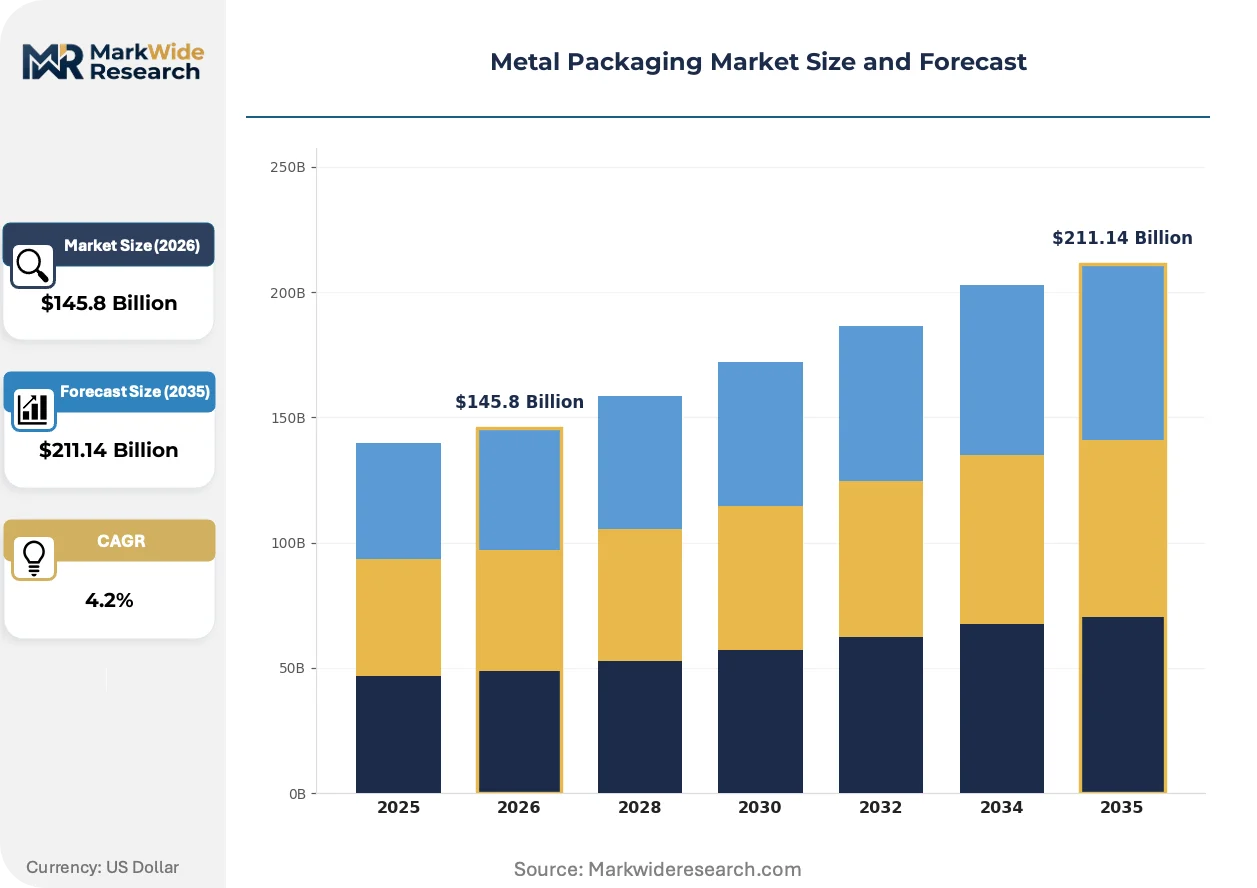
Market Dynamics
Aluminum can lightweighting programs are compressing material intensity per unit while EU carbon-border adjustments force feedstock provenance verification across import supply chains. This dual pressure is restructuring competitive advantage toward integrated recyclers with certified low-carbon metal streams.
Growth Catalysts
- Beverage brand format conversion:Soft-drink and craft-beer producers are abandoning glass and PET for aluminum cans to meet retailer sustainability scorecards and reduce logistics damage rates.
- REACH compliance restructuring:ECHA substance restrictions on legacy tinplate coatings are accelerating migration to polymer-laminated steel and aluminum alternatives across European food-contact applications.
- Southeast Asian manufacturing clustering:Vietnam, Thailand, and Indonesia are attracting can-making investments to serve regional beverage consumption expansion with localized supply.
Market Restraints
- Primary aluminum energy intensity:Smelter electricity costs and carbon-accounting exposure concentrate supply risk with Chinese and Gulf producers facing EU border-tax liability.
- Tinplate coating substitution limits:High-acid food and pharmaceutical applications retain tinplate dependency where polymer alternatives fail thermal-stability testing.
- Steel scrap quality fragmentation:Food-can steel requires low-copper shredded scrap grades that compete with construction rebar demand, tightening input availability.
Strategic Opportunities
- India beverage can penetration:Per-capita aluminum can consumption remains below Southeast Asian levels, creating headroom as Coca-Cola and PepsiCo expand bottler partnerships.
- Aerosol propellant transition:Compressed-gas and bag-on-valve systems are displacing hydrocarbon propellants, requiring new can-body engineering for pressure-rated aluminum extrusions.
- Extended producer responsibility frameworks:Deposit-return schemes in Germany, Sweden, and the Netherlands are generating closed-loop aluminum flows that reduce virgin metal procurement costs.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for BPA-non-intent epoxy alternatives and polyester laminates is concentrated with retiring European specialists.
- Two-piece can line conversion capex:Bodymaker and trimmer equipment for drawn-and-ironed aluminum requires multi-year investment cycles with limited secondary market liquidity.
- F-Gas Regulation compliance timeline:EU restrictions on hydrofluorocarbon propellants force aerosol manufacturers to reformulate and requalify can-lining compatibility within compressed schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Packaging Market |
| Market Size in 2026 | $145.8 Billion |
| Market Size in 2035 | $211.14 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Foil, Containers, Tubes Material: Aluminum, Steel, Tinplate, Stainless Steel Application: Food, Beverage, Personal Care, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Group SA, Silgan Holdings, CANPACK, Greif, CCL Containers, Sonoco Products Company, Toyn Seikan Group Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Packaging Market Strategic Shifts & Innovations
Digital printing and smart-packaging integration are transforming metal containers from passive barriers into interactive consumer touchpoints and supply-chain data nodes. These capabilities are compressing batch-size economics and enabling regional customization.
Polymer-ceramic hybrid coatings are overtaking conventional epoxy phenolics for high-acid food contact. These multilayer systems withstand retort temperatures above 130°C while eliminating bisphenol-A regulatory exposure. Major tomato and citrus processors in Italy and Spain are qualifying these linings for 2025 production campaigns, forcing coating suppliers to expand technical-service teams.
EU F-Gas Regulation phase-down schedules are constraining aerosol propellant choices and accelerating compressed-nitrogen system adoption. This shift demands thicker aluminum can walls and modified dome geometries to maintain pressure integrity. German personal-care brands are leading qualification programs, with Swissmedic reviewing pharmaceutical aerosol alternatives under parallel timelines.
Beverage brands are consolidating procurement around aluminum suppliers with certified renewable-energy smelting. This preference compression is marginalizing traders without chain-of-custody documentation. North American craft brewers and seltzer producers are the most aggressive adopters, inserting carbon-intensity clauses directly into mill-direct contracts.
Metal Packaging Market Segmentation
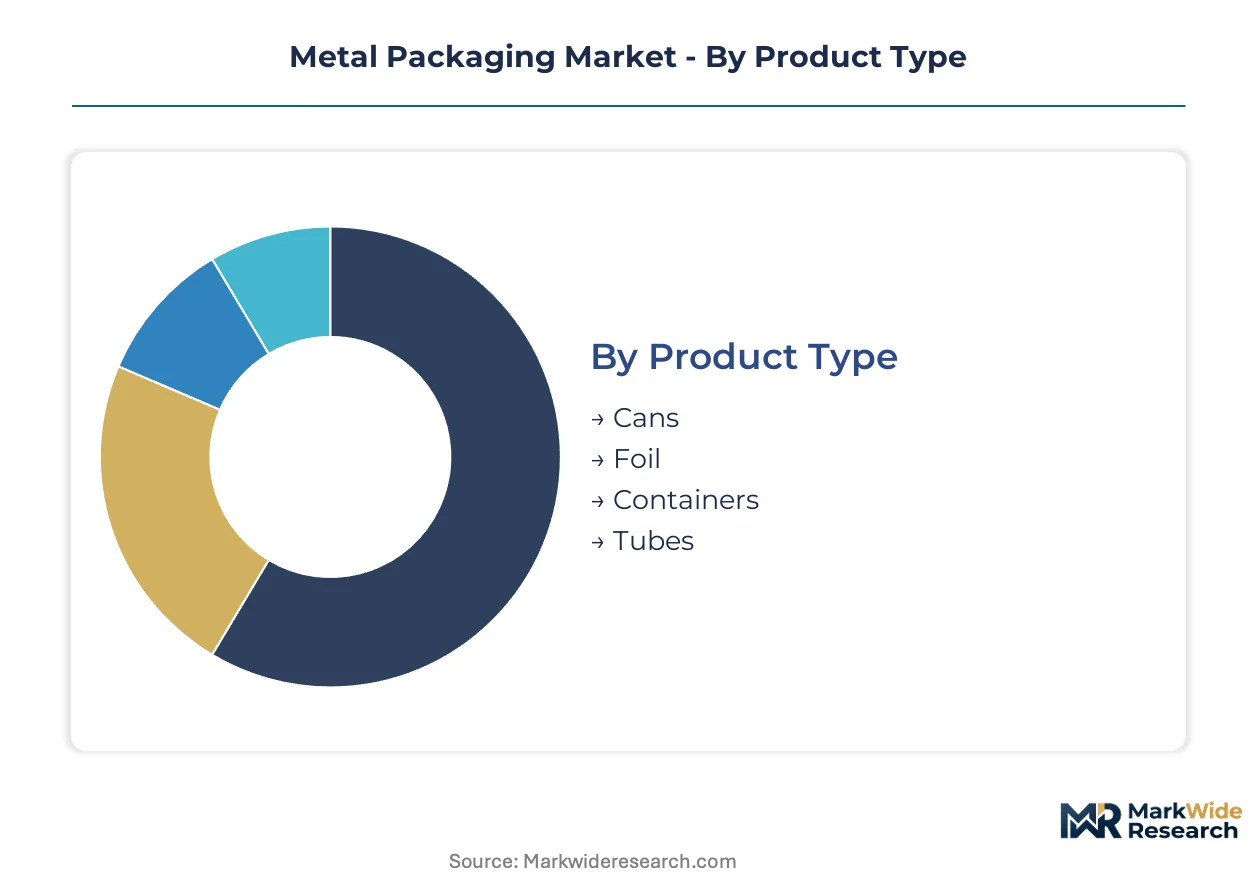
Metal packaging segmentation reveals how material selection, product geometry, and end-use requirements create distinct competitive arenas. Each dimension carries different margin profiles, regulatory burdens, and capital intensity thresholds that reshape supplier positioning.
Product Type:
Customization intensity spans from commodity-standardized formats to engineered specialty shapes, with tooling amortization and volume predictability driving supplier economics.
- Cans:Two-piece drawn-and-ironed aluminum dominates beverage volumes with sub-12-gram body weights, while three-piece welded steel retains food-retort applications. Demand concentrates with Coca-Cola and PepsiCo bottler networks in Vietnam and Thailand as regional consumption climbs.
- Foil:Rolled aluminum below 50 microns serves pharmaceutical blister packs and flexible lidding with precise gauge control. European pharmaceutical contract manufacturers are qualifying domestic foil sources to satisfy EU Green Deal carbon-border documentation requirements.
- Containers:Rigid steel enclosures with double-seamed lids handle processed meats and ready meals. Retailer private-label programs in Germany and the Netherlands specify polymer-ceramic hybrid linings to eliminate BPA liability.
- Tubes:Collapsible aluminum extrusions with internal lacquer barriers serve pharmaceutical ointments and high-viscosity personal care. Swissmedic qualification timelines constrain supplier switching for European pharmaceutical brands.
Leading the category by volume: Cans. Growing fastest: Foil.
Material:
Cost tiers separate virgin-primary metal from recycled-content grades, with carbon-accounting transparency becoming a price-discriminating attribute.
- Aluminum:Beverage can sheet with 70%+ post-consumer scrap content commands mill-direct premiums from craft brewers and seltzer brands. Hydropower-smelted primary ingot from Norway and Iceland avoids EU carbon-border liability.
- Steel:Tin-free chromium-coated steel dominates food cans with retort stability and puncture resistance. Low-copper shredded scrap grades compete with construction rebar demand, tightening input availability for food-grade specifications.
- Tinplate:Electrolytic tin coating above 2.8g/m² retains pharmaceutical and high-acid food roles where polymer alternatives fail thermal-stability testing. REACH compliance on legacy coating chemistries is accelerating substitution.
- Stainless Steel:Type 304 and 316 grades serve aggressive chemical and pharmaceutical applications with autoclave compatibility. Premium pricing reflects nickel content volatility and specialized forming equipment requirements.
Highest volume share: Aluminum. Steepest expansion trajectory: Recycled-content aluminum grades.
Application:
Margin structures diverge between high-volume beverage contracts and specification-intensive pharmaceutical supply, with regulatory burden as the primary differentiator.
- Food:Steel containers with polyester-laminated interiors handle tomato and citrus retort processing. Italian and Spanish processors are qualifying polymer-ceramic hybrid linings for production campaigns.
- Beverage:Aluminum cans with digital-printed sleeves enable regional customization and batch-size compression. North American craft brewers insert carbon-intensity clauses directly into mill-direct contracts.
- Personal Care:Aerosol cans with compressed-nitrogen propellant systems require thicker aluminum walls and modified dome geometries. German personal-care brands lead qualification programs under EU F-Gas Regulation timelines.
- Pharmaceuticals:Tinplate tubes and stainless-steel containers with extractables-testing documentation serve FDA and EMA submission requirements. Swissmedic reviews pharmaceutical aerosol alternatives under parallel regulatory schedules.
Dominant revenue share: Beverage. Fastest-climbing segment: Pharmaceuticals.
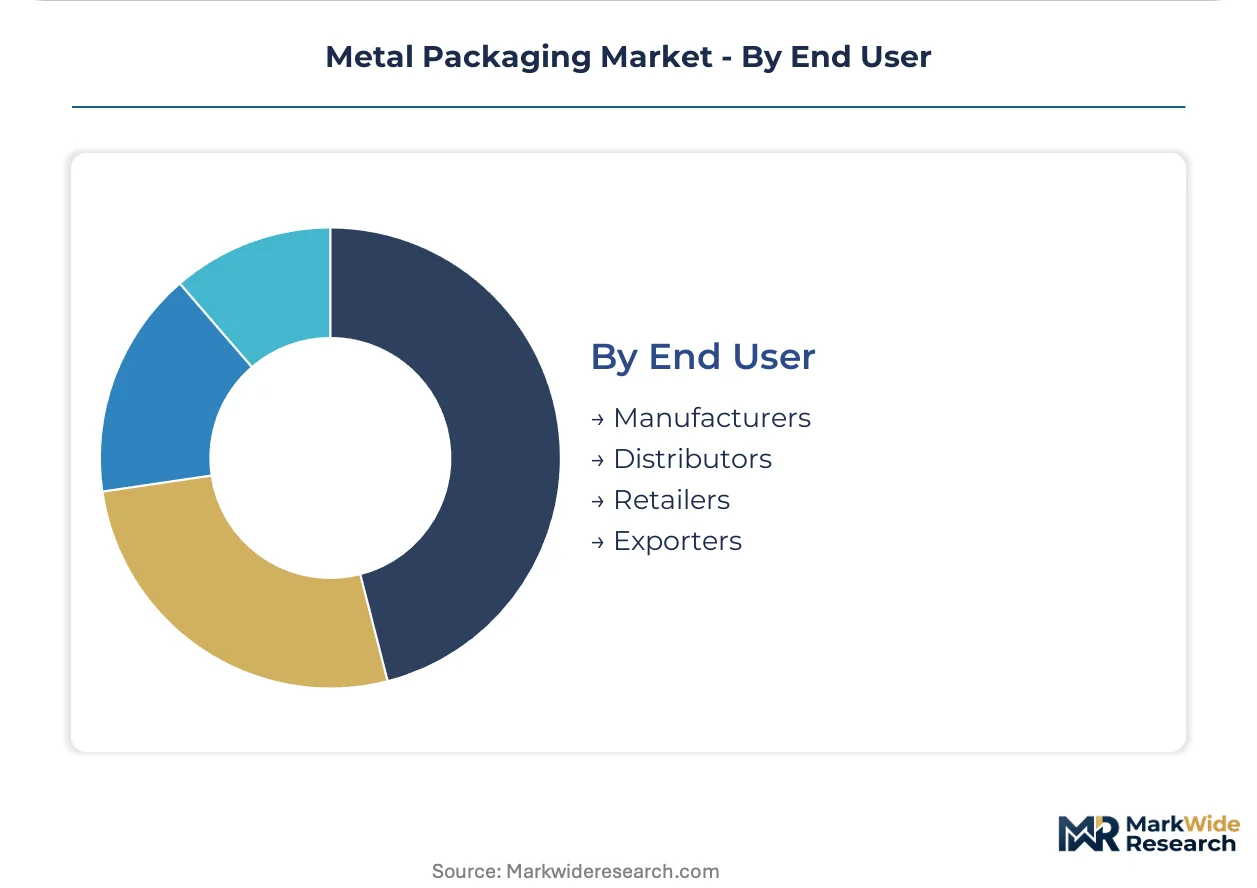
End User:
Supply-chain position determines specification authority, with brand owners driving material substitution faster than intermediaries.
- Manufacturers:Food and beverage processors with captive can-making lines control coating chemistry and metal gauge specifications. Extended producer responsibility frameworks in Germany and Sweden generate closed-loop aluminum flows.
- Distributors:Industrial packaging intermediaries aggregate fragmented demand from regional processors. Inventory carrying costs concentrate purchasing power with national-scale distributors.
- Retailers:Private-label programs at German and Dutch chains specify sustainability scorecard compliance including carbon-intensity documentation. Retailer consolidation is compressing supplier margins.
- Exporters:Cross-border traders face EU carbon-border adjustment documentation requirements for Chinese and Gulf-origin primary aluminum. Chain-of-custody certification is marginalizing traders without mill-direct relationships.
Largest procurement volume: Manufacturers. Fastest-growing channel: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Thang Long Industrial Park II hosts expanding beverage can fabrication lines serving Coca-Cola and PepsiCo bottler networks as regional consumption climbs.
United States
Craft brewers and hard seltzer producers insert carbon-intensity clauses directly into mill-direct aluminum contracts. EPA industrial emissions rules shape can manufacturing investment cycles across Ohio and Colorado production corridors. Chicago anchors North American food can steel-coating capabilities through specialized chromium-coated steel operations.
Germany
Deposit-return schemes generate closed-loop aluminum flows that reduce virgin metal procurement costs for beverage processors. EU F-Gas Regulation constrains aerosol propellant choices and accelerates compressed-nitrogen system adoption. Hamburg and Berlin-Brandenburg concentrate personal-care can qualification programs under Swissmedic-aligned pharmaceutical timelines.
China
SAMR enforces GB standards for food-contact metals that dictate import specifications for regional processors. Dual carbon goals tighten energy-intensity thresholds for primary aluminum smelters in Shandong and Xinjiang. Yangtze River Delta clusters serve Southeast Asian export demand with localized coating and forming operations.
India
Per-capita aluminum can consumption remains below Southeast Asian levels, creating headroom as beverage majors expand bottler partnerships. BIS certification requirements shape domestic sourcing preferences for pharmaceutical and food-contact applications. Maharashtra and Gujarat host emerging two-piece can line investments targeting regional beverage growth.
Italy
Tomato and citrus processors qualify polymer-ceramic hybrid linings for production campaigns, forcing coating suppliers to expand technical-service teams. REACH substance restrictions accelerate migration from legacy tinplate coatings across Emilia-Romagna food operations. Milan anchors premium aerosol and specialty segment competition with differentiated shaping technologies.
Metal Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material grades and end-use applications. The supplier base organizes around three strategic archetypes: integrated aluminum recyclers with certified low-carbon streams, steel-coating specialists with retort-compatible capabilities, and premium aerosol engineers with pressure-rated extrusion expertise. Capacity expansion and backward integration into scrap sorting represent the dominant competitive moves as carbon-border documentation requirements tighten.
Within the integrated recycler tier, Ball Corporation and Crown Holdings occupy positions defined by scale and geographic coverage breadth. Ardagh Group SA exemplifies the specialty-engineering archetype through its concentration in shaped aerosol and premium beverage formats. These three anchors sit within a competitive structure where mill-direct relationships and chain-of-custody certification increasingly determine procurement access.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Group SA |
| Silgan Holdings |
| CANPACK |
| Greif |
| CCL Containers |
| Sonoco Products Company |
| Toyn Seikan Group Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
London Metal Exchange aluminum cash prices cascade through mill-direct contracts into three-tier pricing structure across premium, standard, and economy levels, with hydropower-smelted Norwegian ingot commanding carbon-border premiums against Chinese primary metal facing EU liability.
Pricing Analysis
Short lead-time premiums of certified low-carbon aluminum sheet compress margins for traders without mill-direct relationships. Pricing stratifies across premium, standard, and economy tiers based on carbon-intensity certification and volume scale commitments. Cost compression in standard-grade beverage can sheet is intensifying because Chinese smelter electricity costs face EU border-tax exposure. Craft brewers and seltzer brands exhibit lowest price sensitivity, prioritizing renewable-energy smelting documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Coca-Cola and PepsiCo bottler networks mandate multi-supplier qualification across Vietnam, Thailand, and Indonesia fabrication clusters. Raw material flows draw from Australian bauxite, Chinese alumina refining, and Gulf smelter output. Single-source vulnerability concentrates around Chinese primary aluminum facing EU carbon-border documentation requirements. Distribution runs through regional can-making plants serving localized beverage consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
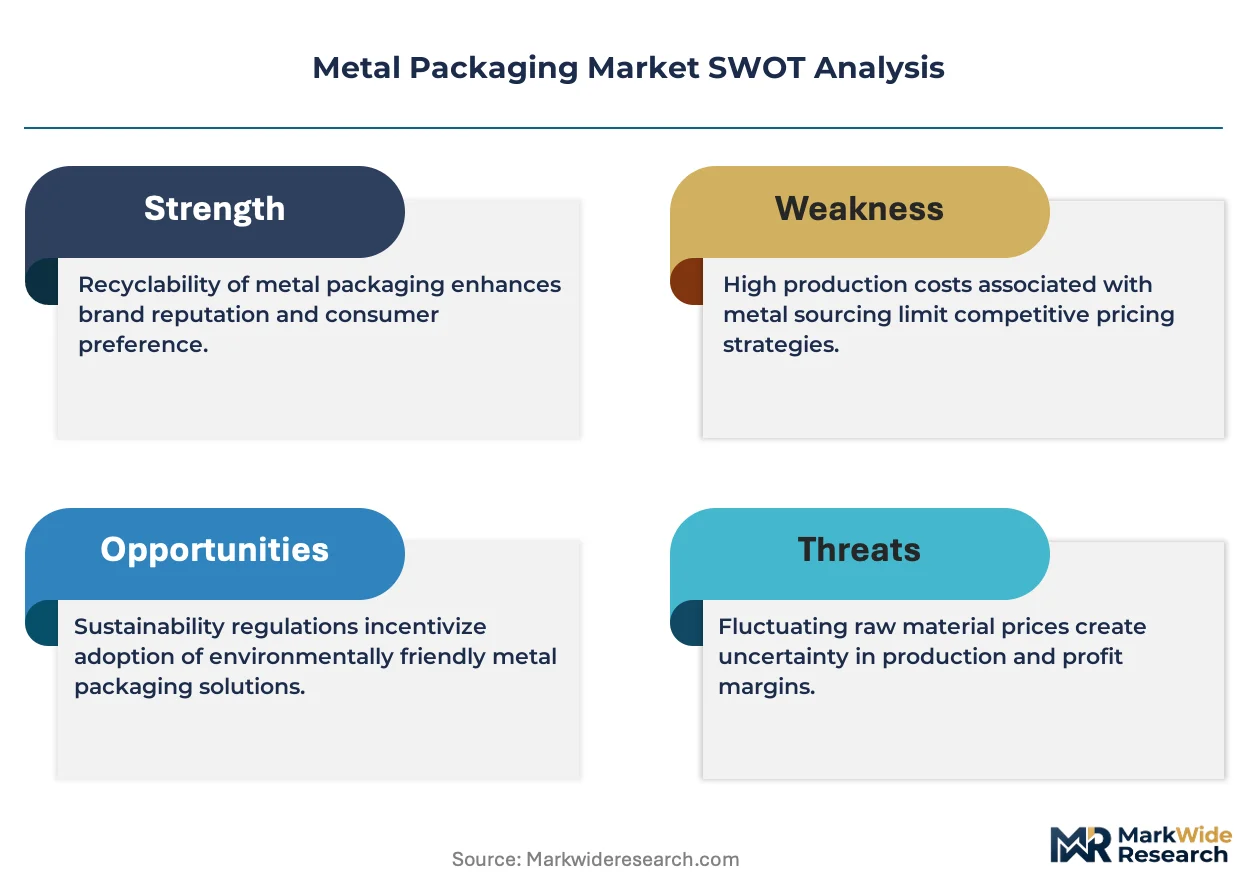
EU carbon-border adjustments and REACH compliance restructuring are forcing consolidation among coating-dependent tinplate suppliers without certified low-carbon aluminum transitions.
For Market Incumbents: Deploy backward integration into scrap sorting and hydropower-smelter partnerships to secure certified low-carbon metal streams. Ball Corporation and Crown Holdings anchor positions through mill-direct relationships; smaller European tinplate specialists face substitution risk from polymer-laminated steel migration. Capacity addition in Vietnam and Thailand defends regional share against emerging local fabricators. For New Entrants and Emerging Players: Begin with India beverage can penetration, where per-capita consumption trails Southeast Asian benchmarks. White-space targets include pharmaceutical aerosol alternatives under EU F-Gas Regulation timelines and polymer-ceramic hybrid lining qualification for Italian tomato processors. Direct mill partnerships with Norwegian or Icelandic smelters provide carbon-intensity differentiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor European tinplate coating specialists with REACH-compliant polymer-laminated steel conversion capabilities. Five-to-ten-year viability hinges on EU Green Deal carbon-border mechanism enforcement breadth. Watch German deposit-return scheme expansion as inflection indicator for closed-loop aluminum flow economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Sorting | Secures low-copper shredded grades for food-can steel specifications against construction rebar competition. |
| Hydropower Smelter Partnership | Locks Norwegian and Icelandic primary aluminum exempt from EU carbon-border liability. |
| Polymer-Ceramic Hybrid Lining Qualification | Captures Italian and Spanish tomato processor volumes abandoning legacy tinplate coatings. |
| Compressed-Nitrogen Aerosol Engineering | Meets EU F-Gas Regulation timelines for German personal-care brand procurement. |
| Digital Printing Capability Expansion | Enables North American craft brewer batch-size compression and regional customization. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this metal packaging analysis. Primary interviews with can plant managers, beverage procurement leads, coating formulation specialists, and aluminum mill sales directors combined with secondary validation from ECHA substance restriction databases, EPA industrial emissions filings, and SAMR GB standard updates. Bottom-up volume modeling across material grades and top-down value reconciliation triangulated market sizing.
Granularity-level modeling distinguished two-piece versus three-piece can geometries, virgin versus recycled-content aluminum grades, and retort-compatible versus ambient food applications across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating beverage format conversion rates and carbon-border mechanism phase-in assumptions. Industry-specific inputs included LME price trajectories, EU ETS carbon cost pass-through coefficients, and regional recycling infrastructure maturity indices.
Underlying measurement precision varies by segment; beverage can volumes carry tighter precision than pharmaceutical aerosol specialty formats. Forecasts reflect assumptions on EU carbon-border enforcement timing and REACH coating substitution timelines. Deviation in Chinese smelter electricity cost trajectories or German deposit-return scheme adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Tin Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Metal Pails Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Metal Cans Market
Metal Packaging
Global Laminated Steel for Cans Market