
 United Arab Emirates Metal Packaging Market | 2026-2036
United Arab Emirates Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Metal Packaging Market Analytics
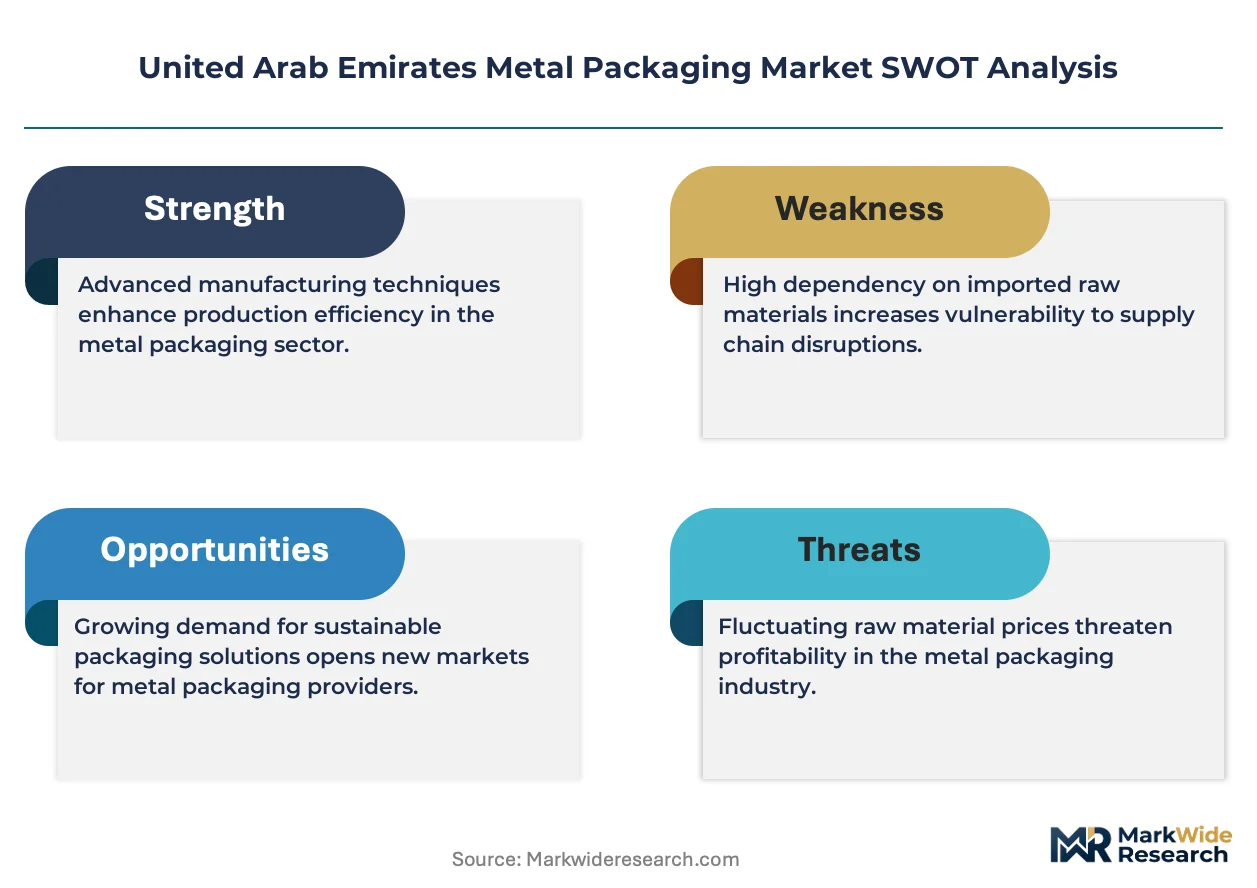
Asset-light leasing arrangements for coating and printing lines is fragmenting competitive entry barriers across the Emirates. Gulf Cans Industries LLC leverages in-house tinplate slitting to sustain margin control on two-piece beverage cans. Emirates Metallic Industries Company Limited anchors regional supply through its galvanized steel drum operations serving petrochemical clients. Crown Holdings Inc. differentiates via advanced necking technology that reduces aluminum gauge without sacrificing pressure performance.
Metal packaging encompasses rigid and semi-rigid containers fabricated from aluminum, steel, or tinplate substrates, typically formed through deep drawing, draw-redraw, or three-piece welding processes with internal protective lacquering to prevent corrosion and ensure food safety compliance. These structures serve to preserve shelf stability, enable thermal processing, and withstand distribution stresses across ambient and chilled supply chains. Cans command the largest volume share within product type segments, driven by single-serve beverage formats and aerosol propellant applications where aluminum's lightweight properties offset raw material premiums. Food & Beverage end users generate the fastest expansion trajectory, particularly for ready-to-drink coffee and functional beverages requiring oxygen barrier performance that metal substrates deliver more reliably than multilayer plastics.
MOHAP enforces food-contact compliance frameworks that mandate migration testing for bisphenol-A alternatives in internal can coatings, while the UAE's adoption of GCC Standardization Organization guidelines harmonizes shelf-life labeling with Saudi and Kuwaiti requirements. Emirates Authority for Standardization and Metrology (ESMA) certification for steel drums used in chemical export creates non-tariff barriers that favor domestic converters with existing test-house relationships. Stakeholders must monitor MOHAP's anticipated alignment with EU Packaging and Packaging Waste Regulation principles, as this would reshape recycled content verification obligations across the supply base.
Market Dynamics
MOHAP's tightening migration limits for epoxy-based can coatings are forcing converters across Dubai and Abu Dhabi to requalify lacquer formulations, compressing product development timelines and raising compliance costs for beverage can suppliers serving carbonated soft drink bottlers.
Growth Catalysts
- Beverage Can Demand:Carbonated soft drink bottlers and craft brewers across Dubai and Abu Dhabi are expanding single-serve aluminum can procurement, driving volume through Jebel Ali's industrial corridor.
- MOHAP Food-Contact Standards:Updated migration testing requirements for bisphenol-A alternatives are accelerating adoption of polyester-phenolic hybrid coatings among domestic converters seeking regulatory pre-approval.
- Port-Proximate Conversion:Tinplate slitting and two-piece can manufacturing capacity clusters near Jebel Ali's container terminals, reducing inland freight costs for export-bound petrochemical drum producers.
Market Restraints
- Aluminum Ingot Volatility:Raw material premiums for primary aluminum ingot fluctuate with London Metal Exchange pricing, squeezing margin predictability for lightweight beverage can producers.
- Coating Chemical Concentration:Specialty epoxy and polyester resin supply concentrates among European and Asian chemical producers, exposing UAE converters to currency and shipping cost volatility.
- Steel Drum Substitution:Intermediate bulk containers and multilayer plastic totes are displacing galvanized steel drums in certain petrochemical logistics applications, capping volume growth in industrial packaging.
Strategic Opportunities
- Ready-to-Drink Coffee:Functional beverage brands in Dubai are specifying oxygen-barrier metal cans over multilayer plastics, creating premium positioning for converters with advanced lacquering capabilities.
- ESMA Certification Relationships:Steel drum exporters serving Saudi and Kuwaiti markets can leverage existing test-house partnerships to accelerate GCC Standardization Organization compliance timelines.
- Necking Technology Convergence:Advanced mechanical necking combined with thinner aluminum gauge specification enables material cost reduction without pressure performance compromise for carbonated formats.
Industry Challenges
- Coating Formulation Talent:Qualified polymer chemists familiar with food-contact lacquer migration testing are scarce in the Emirates, extending R&D hiring cycles for domestic converters.
- Legacy Equipment Retrofit:Existing three-piece welding lines require substantial capital expenditure to accommodate MOHAP-compliant coating application systems, straining mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Metal Packaging Market |
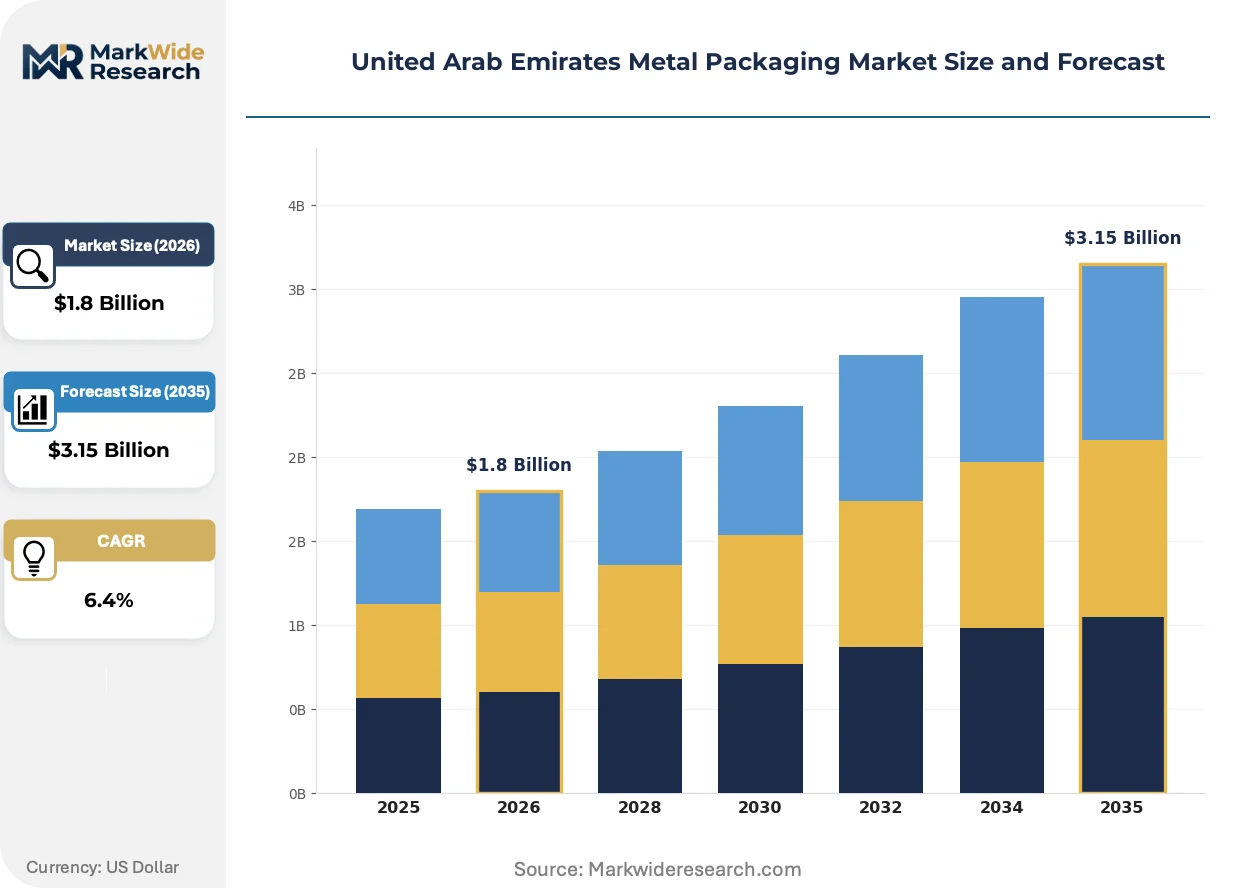
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Containers, Foils, Drums End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Material: Aluminum, Steel, Tinplate, Biodegradable Options Application: Storage, Transportation, Packaging, Preservation |
| Companies Covered | Gulf Cans Industries LLC, Emirates Metallic Industries Company Limited, Crown Holdings Inc., Arabian Can Industry, SAPIN U.A.E., Ball Corporation, Middle East Cans Industry LTD, Dayal Metal Containers Factory LLC, Can-Pack SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Metal Packaging Market Evolving Landscape
Lightweighting technologies and regulatory chemistry shifts are compressing traditional manufacturing economics across the Emirates metal packaging base, while procurement behaviors among beverage brand owners favor technical partnership over transactional supply.
Polyester-phenolic hybrid internal lacquers are replacing conventional epoxy-based can coatings to satisfy MOHAP migration limits for bisphenol-A alternatives. Beverage can converters in Dubai's Jebel Ali corridor are adopting these formulations at accelerated qualification pace. This chemistry transition is collapsing the historical cost advantage of standard epoxy systems, forcing margin compression across mid-tier suppliers lacking formulation partnerships.
MOHAP's alignment with GCC Standardization Organization guidelines harmonizes shelf-life labeling requirements across Saudi, Kuwaiti, and Emirati markets. Steel drum manufacturers serving cross-border petrochemical logistics must now maintain unified certification documentation. Chemical export packaging segments are responding by consolidating test-house relationships to streamline multi-jurisdiction compliance.
Brand owners in the ready-to-drink coffee and functional beverage categories are contracting directly with coating technology licensors rather than relying solely on converter specification. This disintermediation of technical decision-making shifts formulation control upstream. Dubai-based beverage marketing headquarters are most visibly adopting this procurement model, prioritizing oxygen barrier performance guarantees over unit cost minimization.
United Arab Emirates Metal Packaging Market Segmentation
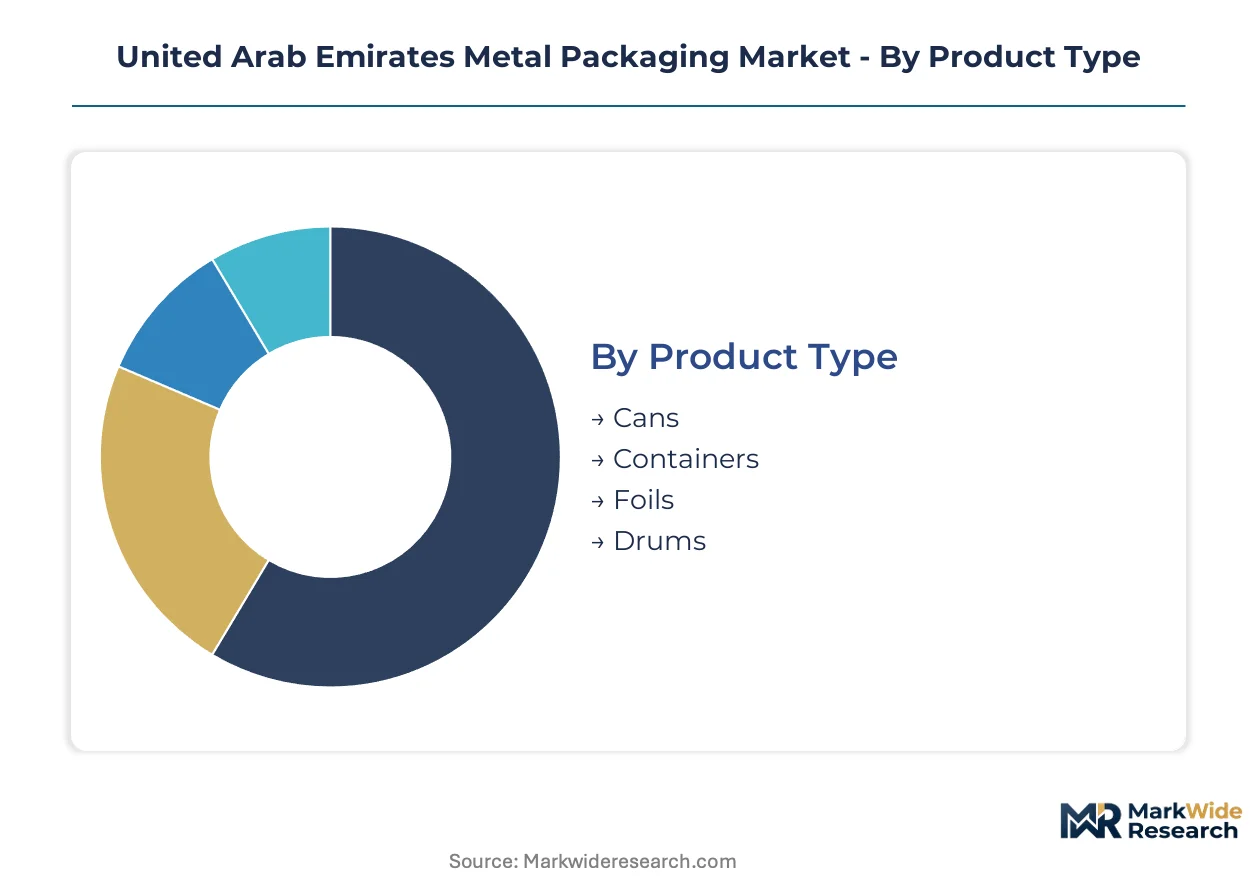
Segmentation in the Emirates metal packaging market reflects divergent technical requirements across beverage carbonation pressures, chemical compatibility thresholds, and MOHAP food-contact compliance tiers. Understanding these divisions clarifies why converter capabilities cluster in Jebel Ali and why certain substrate-coating combinations command procurement premiums.
Product Type:
Mature two-piece beverage formats coexist with emerging sustainable alternatives across Dubai and Abu Dhabi conversion facilities.
- Cans:Two-piece aluminum beverage cans dominate procurement volumes through deep-drawn single-serve formats with internal polyester-phenolic lacquering. Dubai's carbonated soft drink bottlers and craft brewers concentrate demand in Jebel Ali's industrial corridor, where Crown Holdings' advanced necking technology enables gauge reduction without pressure performance loss.
- Drums:Galvanized steel drums with ESMA certification serve petrochemical export logistics through welded three-piece construction and chemical-resistant internal coatings. Emirates Metallic Industries anchors regional supply from port-proximate facilities, though intermediate bulk containers are displacing volume in certain chemical handling applications.
- Containers:Rigid metal containers span food preservation and aerosol propellant formats with draw-redraw or welded manufacturing processes.
- Foils:Aluminum foil laminates provide barrier layers for pharmaceutical blister packs and flexible food packaging substrates.
Cans retain volume leadership; Drums hold the steepest expansion curve in petrochemical export segments.
End User:
Customer procurement patterns split between high-frequency beverage replenishment cycles and specification-heavy industrial compliance documentation.
- Food & Beverage:Ready-to-drink coffee and functional beverage brands in Dubai specify oxygen-barrier metal cans over multilayer plastics, prioritizing barrier performance guarantees. MOHAP's tightened migration limits for epoxy-based coatings are accelerating polyester-phenolic hybrid adoption among domestic converters seeking regulatory pre-approval.
- Chemicals:Petrochemical logistics operators require ESMA-certified steel drums with unified GCC Standardization Organization shelf-life labeling for cross-border Saudi and Kuwaiti shipments. Test-house relationship consolidation is streamlining multi-jurisdiction compliance documentation.
- Pharmaceuticals:Blister pack and primary container demand emphasizes particulate cleanliness and barrier integrity for moisture-sensitive formulations.
- Cosmetics:Aerosol and rigid container applications leverage aluminum's lightweight properties for premium positioning and propellant compatibility.
Food & Beverage commands the largest procurement volumes; Chemicals is gaining share fastest through export logistics expansion.
Material:
Substrate selection balances London Metal Exchange pricing volatility against functional performance requirements in carbonated and corrosive applications.
- Aluminum:Lightweight beverage can substrates offset raw material premiums through downgauging enabled by advanced mechanical necking technology. Primary ingot price fluctuations squeeze margin predictability for Jebel Ali converters serving carbonated format bottlers.
- Tinplate:Steel sheet with electrolytic tin coating provides corrosion resistance for food containers and three-piece can fabrication. Gulf Cans Industries leverages in-house slitting capabilities to sustain margin control on two-piece beverage production.
- Steel:Galvanized and uncoated grades serve industrial drum and general-line container applications with ESMA certification requirements.
- Biodegradable Options:Experimental metal-polymer hybrid substrates and coating innovations address emerging sustainability procurement criteria.
Aluminum maintains volume leadership; Tinplate demonstrates the most rapid technology-driven cost optimization.
Application:
Functional use cases span ambient distribution stability through thermal processing compatibility and chemical containment integrity.
- Packaging:Primary containment functions for consumer-facing beverage and food products with shelf-life extension requirements. Brand owners in Dubai's marketing headquarters are contracting directly with coating technology licensors, disintermediating converter specification control.
- Transportation:Industrial logistics applications for petrochemical and hazardous material movement across GCC borders. Jebel Ali's container terminal proximity reduces inland freight costs for export-bound drum producers.
- Storage:Intermediate and long-term containment for bulk chemicals and processed food ingredients.
- Preservation:Oxygen and light barrier protection for sensitive formulations requiring extended ambient stability.
Packaging retains the dominant value share; Transportation is climbing the fastest on petrochemical export volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbonated soft drink bottlers and craft brewers concentrate procurement decisions in Dubai and Abu Dhabi, where port-proximate conversion capacity reduces logistics friction for beverage can suppliers serving domestic and re-export markets.
Dubai
Jebel Ali's industrial corridor hosts the densest clustering of tinplate slitting and two-piece can manufacturing capacity in the Emirates. MOHAP's updated food-contact material standards are accelerating polyester-phenolic hybrid coating adoption among converters seeking regulatory pre-approval. Crown Holdings' advanced necking technology operations in this zone enable aluminum gauge reduction without pressure performance compromise.
Abu Dhabi
Petrochemical logistics operators in the capital command ESMA-certified steel drum production for cross-border chemical shipments to Saudi Arabia and Kuwait. The Kizad industrial zone anchors galvanized drum fabrication with GCC Standardization Organization shelf-life labeling compliance. Emirates Metallic Industries maintains regional supply relationships from port-adjacent facilities serving export-bound clients.
Sharjah
Mid-tier converters in the Northern Emirates specialize in three-piece welded containers and general-line metal packaging for regional food processors. MOHAP migration testing requirements for bisphenol-A alternatives are extending product development timelines for these smaller fabricators. Industrial zones near Sharjah's container terminals support cost-competitive drum refurbishment and reconditioning services.
Northern Emirates
Ras Al Khaimah and Fujairah host emerging conversion capacity targeting re-export markets across the Gulf and East Africa. Craft brewing clusters in these emirates are driving niche demand for small-batch aluminum can formats. Limited local coating formulation expertise is forcing reliance on Dubai-based technical partnerships for MOHAP-compliant lacquer specification.
United Arab Emirates Metal Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across beverage can, industrial drum, and general-line packaging segments. The vendor base fragments between multinational technology licensors with regional licensing arrangements and domestic converters with captive port-proximate capacity. Two strategic archetypes dominate: integrated substrate-to-container operators with in-house slitting capabilities, and coating-technology-dependent fabricators relying on external formulation partnerships. Competitive moves concentrate on advanced necking technology licensing and GCC Standardization Organization certification relationship consolidation.
Within the integrated operator tier, Gulf Cans Industries LLC and Emirates Metallic Industries Company Limited represent archetypal positions—one leveraging in-house tinplate slitting for beverage can margin control, the other anchoring petrochemical drum supply through ESMA-certified galvanized steel operations. Crown Holdings Inc. occupies the multinational technology licensor position, differentiated by mechanical necking capabilities that enable material cost reduction. These three entities exemplify how substrate control, regulatory certification relationships, and process technology licensing define competitive positioning in the Emirates metal packaging base.
| Leading Market Players |
|---|
| Gulf Cans Industries LLC |
| Emirates Metallic Industries Company Limited |
| Crown Holdings Inc. |
| Arabian Can Industry |
| SAPIN U.A.E. |
| Ball Corporation |
| Middle East Cans Industry LTD |
| Dayal Metal Containers Factory LLC |
| Can-Pack SA |
| Others |
Value Network & Pricing Analysis
Undercapacity in Jebel Ali's polyester-phenolic coating lines is driving premium pricing for MOHAP-compliant lacquer application slots, while pressuring mid-tier converters toward asset-light leasing arrangements that sacrifice margin control for compliance speed.
Pricing Analysis
Certification level (MOHAP pre-approved versus standard epoxy) creates the primary spread between domestic converter tiers. Contract-based long-term offtake agreements dominate procurement from carbonated soft drink bottlers, with price differentiation resting on migration testing documentation and GCC Standardization Organization shelf-life labeling. Pricing pressure stems from aluminum ingot volatility on London Metal Exchange benchmarks. Craft brewers exhibit highest price sensitivity; petrochemical drum exporters show lowest due to ESMA certification non-negotiability.
Supply Chain Analysis
Contract manufacturing concentration among European and Asian specialty resin producers holds decisive lacquer formulation capacity. Raw material dependencies draw from Chinese tinplate rolling, Indian electrolytic tin coating, and German polyester-phenolic resin synthesis. Single-source vulnerability concentrates in bisphenol-A alternative chemistry licensing. Distribution runs through Jebel Ali container terminals for export-bound drum producers, with inland freight costs determining regional competitiveness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating formulation services and migration testing partnerships expand faster than base container fabrication, creating recurring-revenue layers that outpace hardware margins across Dubai and Abu Dhabi conversion facilities.
For Market Incumbents: Entrench MOHAP pre-approval relationships by consolidating test-house partnerships before alignment with EU Packaging and Packaging Waste Regulation principles raises recycled content verification barriers. Defend against asset-light leasing entrants through backward integration into tinplate slitting. Prioritize certification investment over capacity addition in Northern Emirates where coating talent scarcity extends R&D cycles. For New Entrants and Emerging Players: Pursue ready-to-drink coffee brand direct contracting opportunities in Dubai's marketing headquarters, where oxygen barrier specification control is disintermediating traditional converter relationships. Target Sharjah mid-tier fabricators for acquisition or technical partnership to access three-piece welding infrastructure. Lead with coating technology licensing rather than capital-intensive manufacturing scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with captive MOHAP test-house relationships and GCC Standardization Organization documentation capabilities. Five-to-ten year viability favors integrated substrate-to-container operators over coating-dependent fabricators exposed to European resin supply volatility. Monitor MOHAP's anticipated EU regulatory alignment as inflection indicator for recycled content verification investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Pre-Approval Certification | Accelerates market access for polyester-phenolic hybrid coating adopters before regulatory tightening. |
| Test-House Relationship Consolidation | Streamlines multi-jurisdiction compliance for steel drum exporters serving Saudi and Kuwaiti logistics operators. |
| Advanced Necking Technology Licensing | Enables Crown Holdings-style aluminum gauge reduction without pressure performance compromise for carbonated formats. |
| Asset-Light Coating Line Leasing | Fragments competitive entry barriers for mid-tier Sharjah converters facing legacy equipment retrofit capital constraints. |
| Direct Brand Owner Contracting | Disintermediates converter specification control as Dubai beverage marketing headquarters prioritize barrier guarantees. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulation chemists, beverage procurement managers at Dubai marketing headquarters, petrochemical logistics operators, and ESMA certification specialists, then refined through secondary validation against MOHAP regulatory filings, GCC Standardization Organization guideline documentation, London Metal Exchange aluminum pricing data, and Emirates Authority for Standardization and Metrology certification records. Bottom-up volume modeling across converter facilities triangulated with top-down petrochemical export value chain analysis.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type (cans, drums, containers, foils), material substrate (aluminum, tinplate, steel), end-use vertical (food and beverage, chemicals, pharmaceuticals, cosmetics), and application function (packaging, transportation, storage, preservation). CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost step-changes and coating chemistry transition timelines. Industry-specific inputs incorporated MOHAP migration limit revision schedules and Jebel Ali port capacity utilization trends.
Sensitivities concentrate around MOHAP's EU regulatory alignment timing, London Metal Exchange aluminum volatility bands, and European resin producer capacity allocation decisions. Forecasts reflect documented assumptions on coating qualification pace and brand owner procurement model evolution. Quarterly review of MOHAP pre-approval queue lengths and GCC cross-border drum shipment documentation changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Metal Pails Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Converter Aluminum Foil Market