
 Medical Tapes Market | 2026-2036
Medical Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tapes Market Intelligence
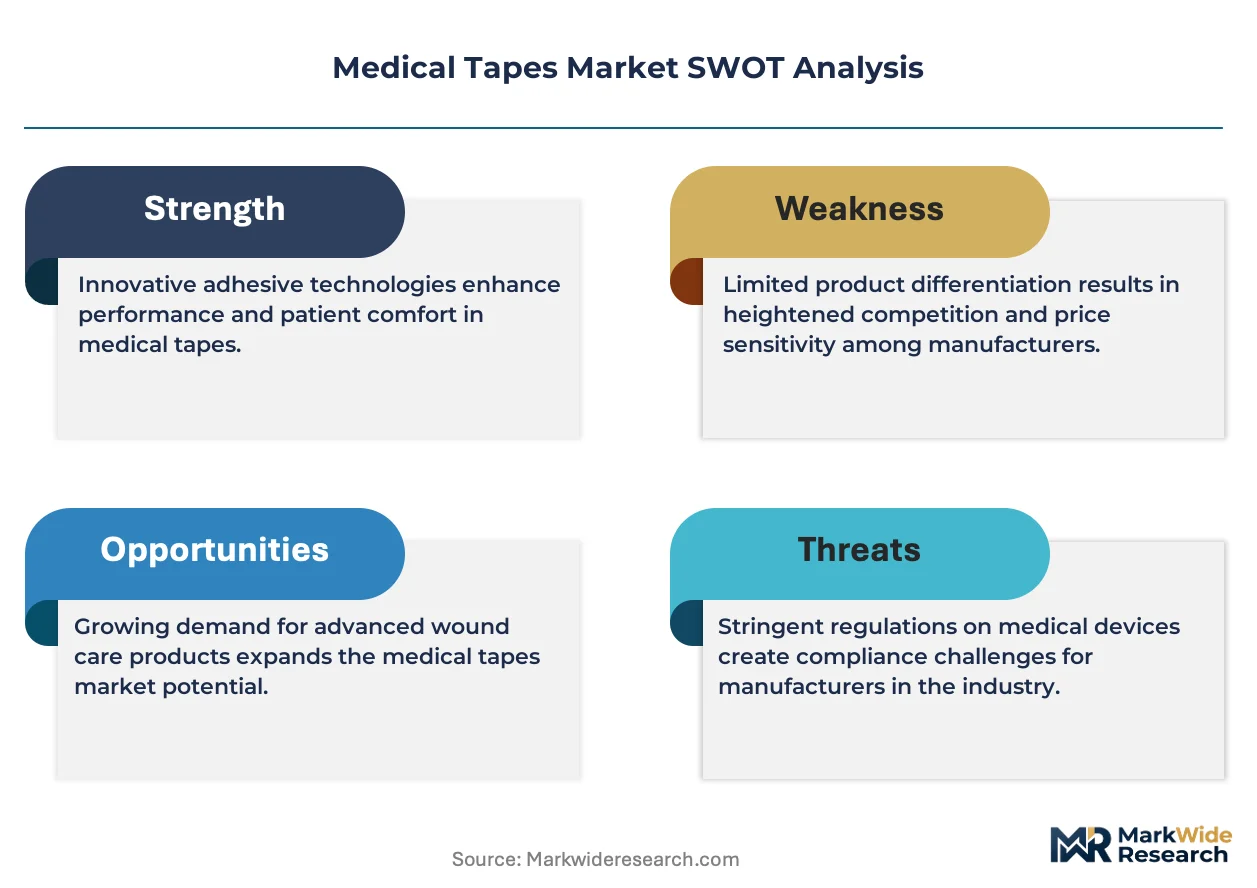
Demand from general hospital wound care is decoupling from high-margin applications in sports medicine and cosmetic procedures. 3M Company leverages its material science expertise to dominate the high-performance adhesive tape segment. Johnson & Johnson sustains its market position through extensive distribution networks reaching hospitals and homecare settings. Smith & Nephew specializes in advanced wound care, competing on clinical outcomes.
Medical tapes are flexible adhesive materials designed for direct skin contact to secure dressings or devices. These products must exhibit specific adhesion-to-peel strength ratios and use biocompatible substrates like cloth or foam. Silicone tape and foam tape products are gaining share over traditional cloth tapes due to superior gentleness on sensitive skin. In terms of technology, acrylic adhesives maintain a dominant position for general use, while silicone adhesives represent the fastest-growing segment for specialized applications.
Market access is governed by stringent regulatory frameworks, including the U.S. FDA's 510(k) clearance process and the EU's Medical Device Regulation (MDR). In China, the NMPA imposes specific GB standards for material safety and biocompatibility, influencing manufacturing for that market. Future competitive advantage will depend on navigating these disparate regional compliance pathways while innovating in material science for sensitive skin applications.
Market Dynamics
The market's central dynamic is the tension between clinical performance and material biocompatibility, driven by stricter global regulatory standards. This pressure is forcing a portfolio shift away from traditional tapes toward advanced adhesives designed for sensitive, at-risk skin, particularly in homecare and post-operative settings.
Growth Catalysts
- Expanding Homecare Sector:The increasing prevalence of chronic conditions and an aging population are shifting post-operative and long-term wound management to homecare settings, boosting demand for user-friendly and gentle-to-skin medical tapes.
- Material Science Advancements:The development of silicone and foam-based adhesives provides superior performance on fragile skin compared to traditional acrylics, catalyzing adoption in high-value segments like neonatal care and geriatrics.
- Rising Clinical Standards:Healthcare systems in developed nations like Germany and the United States are adopting protocols that prioritize the prevention of medical adhesive-related skin injuries (MARSI), creating sustained demand for premium, clinically-proven tape products.
Market Restraints
- Higher Cost of Advanced Materials:The significant price premium for silicone-based and other advanced adhesive tapes limits their widespread adoption in cost-sensitive healthcare systems and for general-purpose applications, slowing substitution of traditional products.
- Regulatory Fragmentation:Navigating disparate compliance requirements, such as the FDA's 510(k) process in the U.S., the EU's MDR, and China's GB standards, increases development costs and time-to-market for new products.
- Threat from Alternative Technologies:In certain surgical and acute wound closure scenarios, medical tapes face competition from substitutes like liquid skin adhesives, sutures, and staples, which can offer faster application or higher tensile strength.
Strategic Opportunities
- Wearable Medical Devices:The proliferation of wearable sensors and drug delivery patches creates an opportunity for specialized, long-wear medical tapes designed for secure, multi-day adhesion without causing skin irritation.
- Emerging Market Penetration:As healthcare infrastructure and spending improve in regions across Latin America and Southeast Asia, there is a significant opportunity to introduce both basic and advanced wound care tapes to underserved populations.
- Medicated Adhesive Tapes:Integrating active pharmaceutical ingredients (APIs) into adhesive formulations presents an opportunity to develop tapes that offer antimicrobial, anti-inflammatory, or analgesic properties, enhancing therapeutic value.
Industry Challenges
- Complex Compliance Pathways:Manufacturers face operational hurdles in generating the extensive clinical and biocompatibility data required to achieve and maintain certification under stringent frameworks like the EU's Medical Device Regulation.
- Raw Material Supply Constraints:The supply of specialized, medical-grade polymers and silicone for advanced tapes is concentrated among a few chemical companies, creating potential for price volatility and supply chain disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tapes Market |
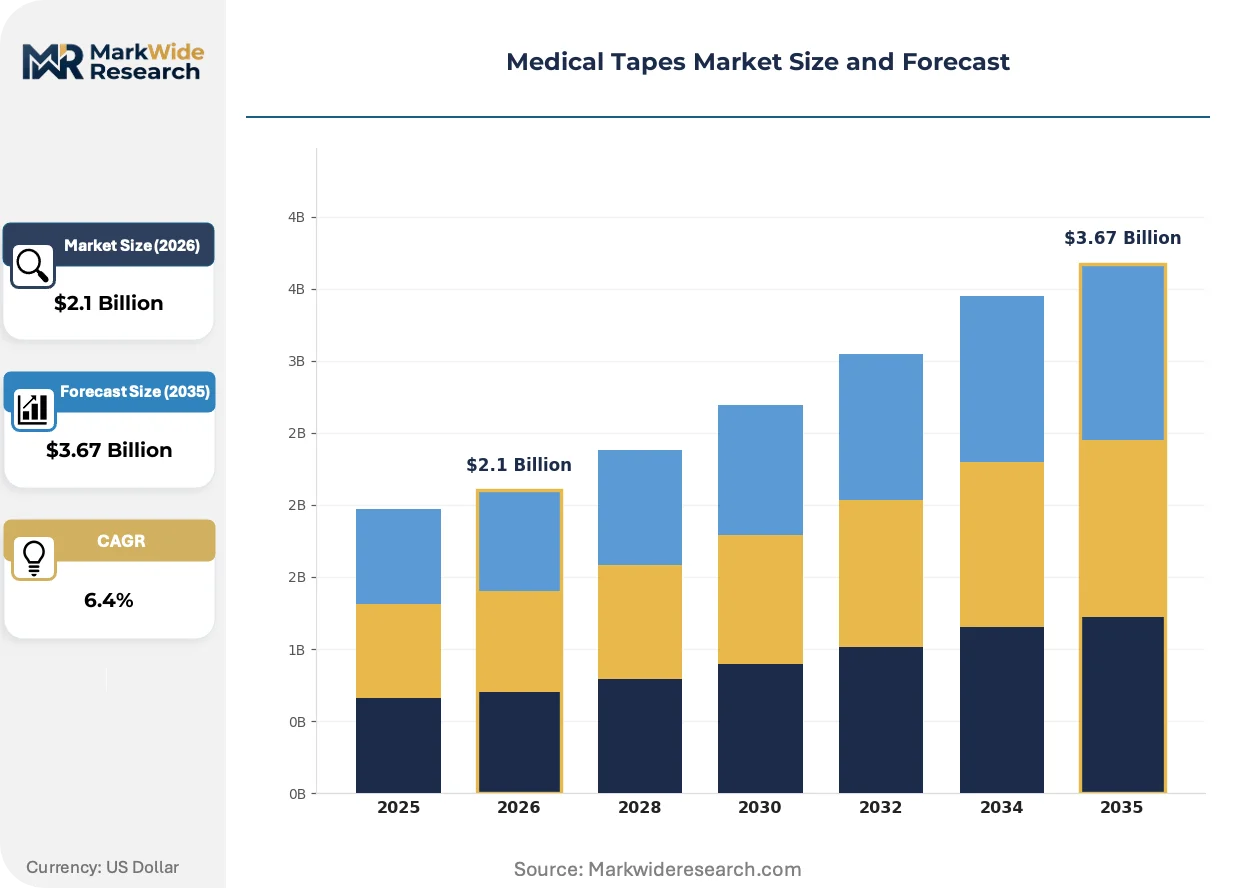
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Tape, Silicone Tape, Foam Tape, Cloth Tape, Plastic Tape Application: Wound Care, Surgical Dressing, Orthopedics, Sports Medicine, Cosmetic Procedures End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Homecare Settings Technology: Acrylic Adhesive, Rubber Adhesive, Silicone Adhesive, Hydrocolloid Adhesive |
| Companies Covered | 3M Company, Johnson & Johnson, Cardinal Health, Medline Industries, Smith & Nephew, Medtronic, Nitto Denko Corporation, Paul Hartmann AG, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tapes Market Strategic Shifts & Innovations
Material science innovation is focused on enhancing the patient experience by improving the balance between secure adhesion and atraumatic removal. This pursuit is creating a new generation of tapes designed to minimize skin stripping and irritation, particularly for patients with compromised skin integrity.
Smart adhesive technology provides real-time wound status monitoring. These advanced tapes are being adopted by specialized wound care clinics and hospitals managing chronic conditions like diabetic ulcers. This technology is integrating diagnostic feedback directly into the tape itself, transforming it from a passive fixation device into an active element of patient care protocols.
The European Union's Medical Device Regulation (MDR) is elevating compliance burdens across the industry. This regulation mandates more rigorous clinical evidence and post-market surveillance for all devices, including tapes. Manufacturers of even lower-risk tapes now face increased scrutiny and documentation requirements to secure or maintain CE marking for European market access.
Institutional purchasing criteria are evolving beyond simple unit cost. Major hospital networks are increasingly evaluating medical tapes based on a total cost of ownership, which includes the expense associated with treating adhesive-related skin injuries. This shift is most visible in North American and European healthcare systems, where it favors premium tapes that can demonstrate a reduction in complication rates.
Medical Tapes Market Segmentation
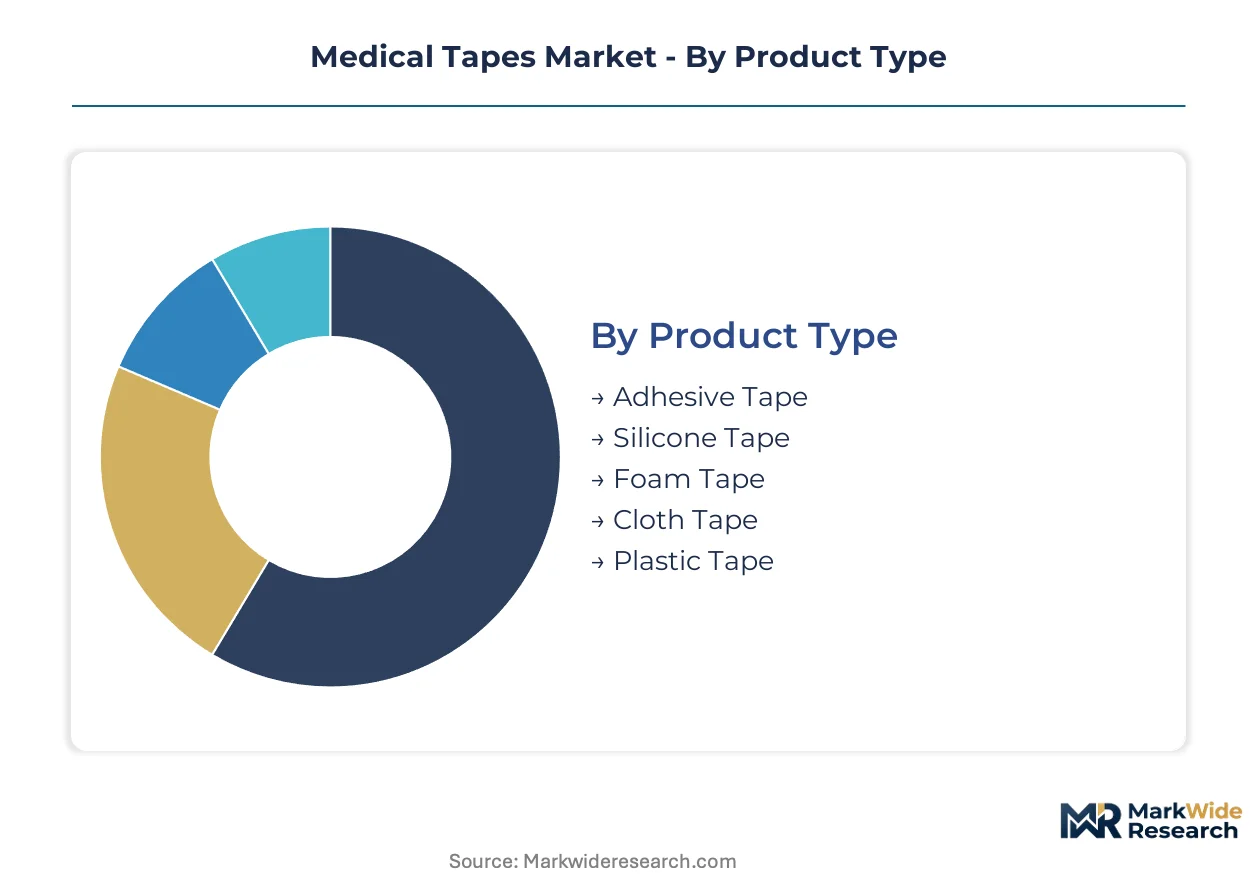
The medical tapes market is diverse, reflecting varied clinical needs from basic wound dressing to specialized surgical applications. Understanding these segments reveals how material science and application-specific demands drive product innovation and procurement decisions across healthcare settings. This segmentation highlights areas of high growth and established market presence.
Product Type:
Product types delineate the material composition and primary functional characteristics of medical tapes, distinguishing between general-purpose fixation and specialized skin-friendly solutions.
- Silicone Tape:This product features a soft, conformable silicone adhesive layer, offering gentle adhesion and atraumatic removal, minimizing skin stripping. Demand concentrates in developed healthcare systems like Germany and the United States for fragile skin applications, driven by protocols preventing medical adhesive-related skin injuries.
- Foam Tape:Foam tapes incorporate a conformable foam substrate with an adhesive backing, providing cushioning, absorption, and secure fixation, particularly on contoured body areas. Homecare settings and post-operative recovery drive demand for foam tapes due to their ease of application and comfort for long-term wear.
- Adhesive Tape:This broad category encompasses various backing materials with acrylic or rubber-based adhesives for general securement.
- Cloth Tape:Traditional cloth tapes offer strong adhesion and conformability, widely used for securing dressings and medical devices in general hospital settings.
- Plastic Tape:Plastic tapes, often transparent or translucent, provide a waterproof barrier and secure fixation for light dressings and IV lines.
Volume placements concentrate in Adhesive Tape; the faster expansion belongs to Silicone Tape.
Application:
Application segments classify medical tapes based on their intended clinical use, ranging from routine post-operative management to highly specialized procedures requiring specific performance attributes.
- Wound Care:Tapes for wound care secure primary and secondary dressings, providing protection and promoting a healing environment, often requiring gentleness for sensitive or compromised skin. Demand for these tapes is high in homecare settings, driven by an aging population and the increasing prevalence of chronic conditions.
- Surgical Dressing:These tapes are specifically designed to secure surgical incisions and dressings, requiring strong, reliable adhesion that can withstand bodily fluids and movement. Hospitals and ambulatory surgical centers represent primary users, prioritizing products that ensure patient safety and minimize post-operative complications.
- Orthopedics:Orthopedic applications utilize tapes for securing splints, casts, and other support devices, demanding robust adhesion and conformability.
- Sports Medicine:Tapes in sports medicine provide support, compression, and injury prevention for athletes, requiring high tensile strength and flexibility.
- Cosmetic Procedures:Tapes for cosmetic procedures offer gentle fixation for delicate skin post-surgery, emphasizing minimal scarring and atraumatic removal.
The largest segment by volume remains Wound Care, while Cosmetic Procedures demonstrates significant growth due to specialized product requirements.
End User:
End user segments define the primary healthcare environments where medical tapes are procured and utilized, influencing product specifications and distribution channel requirements.
- Hospitals:Hospitals represent a foundational end-user segment, utilizing a wide range of medical tapes for general wound care, surgical applications, and securing medical devices across various departments. Procurement in these institutions often emphasizes total cost of ownership, including the cost of treating adhesive-related skin injuries.
- Homecare Settings:This segment includes patients and caregivers managing medical needs outside clinical facilities, driving demand for user-friendly, gentle-to-skin tapes suitable for self-application and extended wear. The aging population and shift towards chronic disease management at home significantly impact product development for this sector.
- Ambulatory Surgical Centers:These centers require efficient, reliable tapes for outpatient surgical procedures, focusing on rapid application and secure, short-term fixation.
- Diagnostic Laboratories:Diagnostic laboratories use medical tapes for securing samples, labeling, and minor patient care, prioritizing ease of use and material compatibility.
Demand from Hospitals forms a stable base, with Homecare Settings showing the most dynamic expansion due to demographic shifts.
Technology:
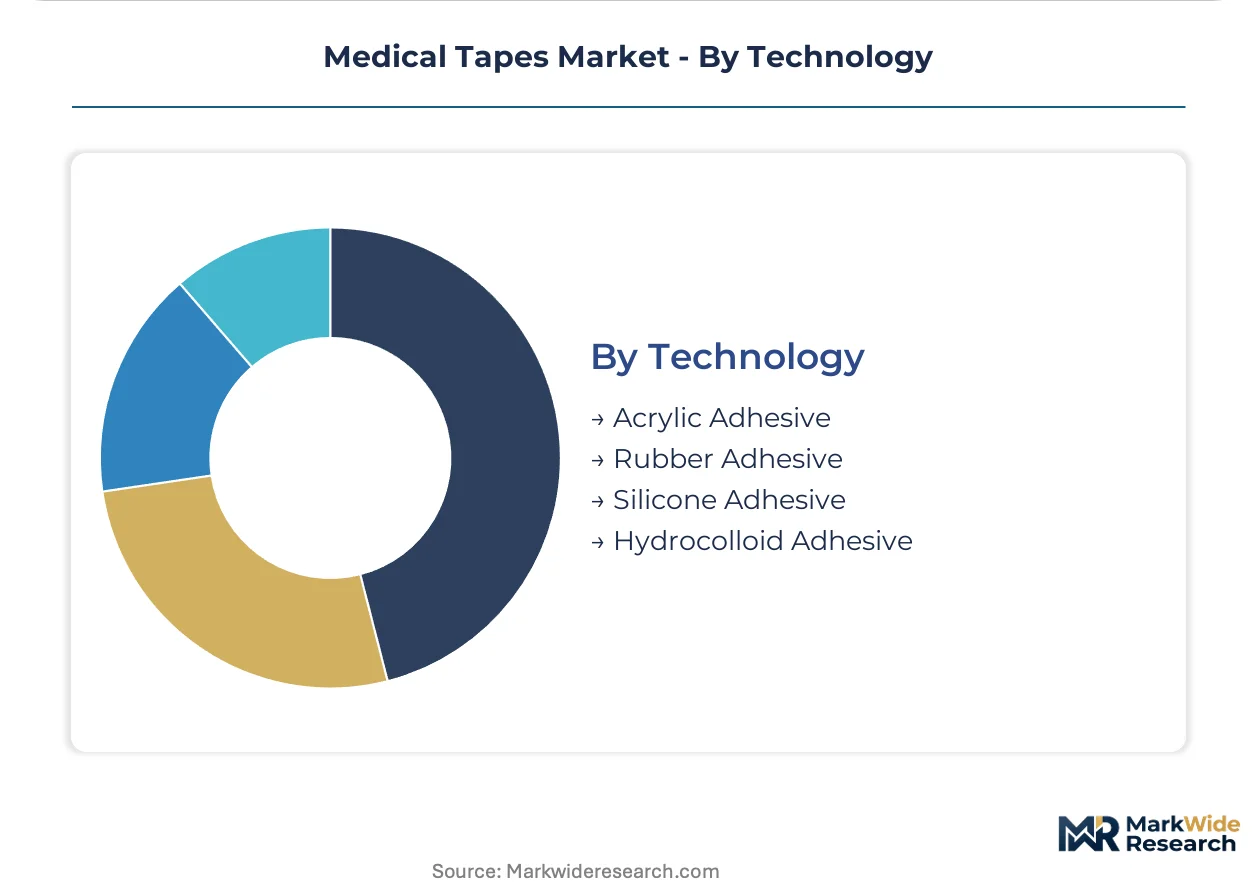
Technology segmentation differentiates medical tapes based on the chemical composition of their adhesive layer, directly impacting adhesion strength, skin compatibility, and application suitability.
- Acrylic Adhesive:Acrylic adhesives are widely used for their strong, durable bond and versatility across many medical tape applications, representing a mature and cost-effective technology. These adhesives maintain a dominant position for general-purpose tapes, particularly in cost-sensitive healthcare systems and high-volume segments.
- Silicone Adhesive:Silicone adhesives offer superior gentleness on sensitive skin and atraumatic removal, making them ideal for fragile skin and repeated applications without causing injury. This technology represents the fastest-growing segment for specialized applications, driven by improved patient outcomes and regulatory emphasis on skin integrity.
- Rubber Adhesive:Rubber-based adhesives provide strong initial tack and good adhesion, often used in more traditional and heavy-duty medical tape formulations.
- Hydrocolloid Adhesive:Hydrocolloid adhesives are known for their moisture-absorbing properties and ability to create a moist wound environment, often used in advanced wound care dressings.
While Acrylic Adhesive technology holds the largest market share, Silicone Adhesive is gaining share fastest due to its clinical advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its robust FDA regulatory framework, effectively functions as a specialized zone for medical device innovation and manufacturing concentration. This environment drives significant demand for advanced medical tapes, particularly in high-value clinical applications.
United States
Demand for medical tapes in the United States stems from an aging population and the increasing focus on preventing medical adhesive-related skin injuries (MARSI). The FDA's 510(k) clearance process dictates market access and product development for new medical devices. Major medical device clusters, such as those in Boston and Minneapolis, drive innovation in high-performance adhesive tapes.
Germany
Germany's developed healthcare system prioritizes premium, clinically-proven medical tapes to reduce complication rates. The EU's Medical Device Regulation (MDR) sets stringent biocompatibility and performance standards for all products. Bavaria, a prominent MedTech region, demonstrates strong adoption of advanced wound care tapes for sensitive skin applications.
China
China's medical tape market sees demand from expanding hospital infrastructure and a growing focus on domestic manufacturing. The NMPA imposes specific GB standards for material safety and biocompatibility, influencing product formulations. The Yangtze River Delta region, including cities like Shanghai, serves as a significant hub for medical device production and distribution.
Japan
Japan exhibits strong demand for gentle, high-performance medical tapes, driven by an aging population requiring sensitive skin solutions. The PMDA regulates medical device approvals, emphasizing product safety and efficacy for clinical use. Tokyo's advanced medical research centers contribute to the development and adoption of innovative adhesive technologies.
India
India's expanding healthcare infrastructure and underserved populations fuel demand for both basic and advanced wound care tapes. The CDSCO's medical device rules guide product registration and quality control for manufacturers. Bengaluru, with its growing medical technology cluster, sees increasing investment in local production capabilities for various medical consumables.
Medical Tapes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the medical tapes market. The market structure exhibits a tiered consolidation, with established players dominating high-value segments. Strategic archetypes include material science innovators, broad-portfolio distributors, and advanced wound care specialists. Companies prioritize material science advancements and extensive distribution network expansion as key competitive moves.
Among the established branded specialists, 3M Company exemplifies material science innovation, leveraging its expertise in high-performance adhesive tapes. Johnson & Johnson sustains its market position through extensive distribution networks, reaching diverse healthcare settings globally. Smith & Nephew represents a focus on advanced wound care, competing on superior clinical outcomes for specialized applications.
| Leading Market Players |
|---|
| 3M Company |
| Johnson & Johnson |
| Cardinal Health |
| Medline Industries |
| Smith & Nephew |
| Medtronic |
| Nitto Denko Corporation |
| Paul Hartmann AG |
| Baxter International |
| Others |
Cost & Logistics Intelligence
Silicone adhesive technology adoption simultaneously reshapes cost economics and supply concentration in the medical tapes market. Its specialized raw materials and manufacturing processes drive higher production costs and limit supplier diversification.
Pricing Analysis
Lead-time-driven pricing structures often command a premium for rapid delivery of specialized medical tapes. The dominant pricing model involves contract-based long-term offtake agreements for institutional buyers. Price differentiation stems from quality grade, specific biocompatibility certifications like EU MDR, and brand reputation. Pricing softness impacts traditional cloth and plastic tapes as procurement shifts to total cost of ownership, making homecare settings and general wound care highly price-sensitive compared to high-value cosmetic procedures.
Supply Chain Analysis
Reverse-logistics flows for medical tapes are minimal, primarily limited to product recalls or quality control returns, rather than refurbishment. Supply concentration for specialized medical-grade polymers and silicone centers in key chemical manufacturing hubs, drawing from suppliers in the United States and Germany. This creates a single-source vulnerability, particularly for advanced materials. Distribution runs through established channels, including large medical distributors for hospitals and direct-to-consumer models for homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical tapes market functions as a cost-of-compliance story, where stringent regulatory frameworks like the EU Medical Device Regulation create a significant barrier-to-entry moat for compliant manufacturers. This regulatory environment favors established players with robust quality systems.
For Market Incumbents: Anticipate evolving clinical standards by continuously investing in material science R&D for advanced silicone and foam tapes. Deepen vertical integration into specialized adhesive production to mitigate raw material supply constraints. Incumbents should also expand distribution networks in homecare settings to counter the threat from alternative wound closure technologies. Prioritizing certification investment under stringent frameworks like the EU MDR reinforces market position.
For New Entrants and Emerging Players: Begin with a focus on underserved niche segments requiring specialized performance, such as medicated adhesive tapes or advanced tapes for wearable medical devices. Target emerging markets across Latin America and Southeast Asia where healthcare infrastructure is expanding. A go-to-market strategy emphasizing superior clinical outcomes for sensitive skin applications, particularly in neonatal care or cosmetic procedures, offers a viable entry point.
For Investors and Strategic Acquirers: Exit pathways concentrate in material science innovators specializing in advanced adhesive technologies and companies with robust regulatory compliance platforms. The market demonstrates long-term viability over the next 5-10 years, driven by an aging population and increasing focus on sensitive skin solutions. Strategic acquirers should seek firms with strong intellectual property in silicone or foam adhesives. A key signal to watch is the accelerating adoption rate of smart adhesive technologies in specialized clinics.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Science R&D Expansion | Develops next-generation adhesives for sensitive skin, aligning with evolving clinical standards. |
| EU MDR Compliance Acceleration | Secures and maintains market access in Europe, creating a regulatory competitive advantage. |
| Homecare Distribution Network Enhancement | Captures demand from an expanding patient population managing chronic conditions at home. |
| Medicated Tape Product Development | Integrates active pharmaceutical ingredients, enhancing therapeutic value and patient outcomes. |
| Strategic Partnerships for Wearable Devices | Creates specialized tapes for secure, long-wear adhesion in the rapidly growing wearables sector. |
Research Approach
Independent corroboration across FDA filings, EU MDR documentation, and NMPA GB standards underwrites the qualitative findings of this study. Primary interviews with clinicians, hospital purchasing committees, and R&D directors at medical tape manufacturers informed market dynamics. Secondary data from medical journal articles and GPO contracts provided quantitative validation. This analysis utilized both bottom-up and top-down triangulation to ensure data accuracy.
Rate-of-change decomposition analyzes growth across the analysis window by segmenting the market across product type, application, end user, and technology. The analytical framework incorporates regional regulatory clusters as a key dimension. Compound annual growth rates were derived from a blend of historical trends and projected future drivers. Key forecast inputs include global aging population demographics and the increasing prevalence of chronic conditions.
Underlying measurement precision varies by segment; established product types like Adhesive Tape carry tighter precision than emerging segments like Medicated Adhesive Tapes. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Practitioners should monitor significant shifts in global regulatory frameworks and supply chain resilience for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Metal Foil Tapes Market
Tapes
Gummed Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Acoustic Tape Market
Tapes
Security Tape Market
Tapes
Thread Seal Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Carbon Tapes Market
Tapes
Tape Dispenser Market
Tapes
Flatback Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Kraft Paper Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Painting Masking Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Raffia Tapes Market