
 Metal Packaging Coatings Market | 2026-2036
Metal Packaging Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Packaging Coatings Market Outlook
Modular coating systems that separate base-layer adhesion from top-layer functional performance is expanding choice architecture for metal packaging procurement teams. Akzo Nobel N.V. leverages its marine and protective coatings heritage to transfer corrosion-science IP into beverage can interiors. PPG Industries sustains North American supply relationships through captive resin production and toll-manufacturing agreements with regional metal decorators. Kansai Paint anchors Asian volume through long-term supply contracts with integrated steel-and-aluminum rolling mills.
Metal packaging coatings comprise chemically engineered film-forming systems applied to tinplate, tin-free steel, or aluminum substrates to prevent corrosion, ensure food safety, and enable decorative lithography; typical formulations achieve dry-film thicknesses of 4–12 micrometers and must pass extraction testing under simulated thermal processing conditions. Epoxy coatings still dominate food-contact applications due to their barrier performance against acidic contents, though polyester alternatives are gaining fastest in cosmetic aerosol segments where ECHA scrutiny of bisphenol derivatives intensifies. Waterborne formulations command premium positioning in European supply chains as REACH registration costs and VOC emission thresholds restructure feasible product portfolios for mid-size applicators.
FDA food-contact notification requirements and EFSA scientific opinions on epoxy-based can coatings create divergent compliance burdens that fragment formulation standardization across Atlantic supply chains. China's GB standards for food-contact coatings and Japan's Food Sanitation Law impose additional migration-testing protocols that exclude non-certified suppliers from branded-goods supply chains. Stakeholders must monitor regulatory divergence between FDA, EFSA, and national Asian frameworks when situating regional production capacity or qualifying second-source coating suppliers.
Market Dynamics
REACH registration costs and EFSA migration-test protocols are fragmenting formulation standardization across Atlantic supply chains, forcing applicators to maintain parallel product portfolios or exit select geographies entirely.
Growth Catalysts
- BPA-Free Mandates:FDA food-contact notifications and EFSA scientific opinions on epoxy derivatives accelerate waterborne polyester adoption in beverage can interiors across Germany and France.
- Aluminum Substrate Expansion:Lightweighting demands from craft beverage producers in the United States drive coating orders for two-piece aluminum cans with enhanced sidewall adhesion chemistry.
- Dual-Carbon Alignment:China's GB standards for low-VOC food-contact coatings create certified-supplier preference in branded-goods supply chains serving domestic dairy and infant formula markets.
Market Restraints
- Epoxy Resin Input Volatility:Bisphenol A and epichlorohydrin price swings compress margin predictability for mid-size toll coaters serving regional metal decorators.
- Applicator Supply Concentration:Western European filling equipment operators face qualified-coater scarcity as REACH compliance costs eliminate smaller regional players in Italy and Spain.
- Migration-Test Technical Limits:Current extraction protocols under simulated thermal processing cannot reliably predict long-term performance for novel polyester alternatives in high-acid food matrices.
Strategic Opportunities
- India Food-Processing Expansion:FSSAI notification requirements for food-contact coatings remain underpenetrated by certified international suppliers, creating first-mover positioning in Mumbai and Delhi-NCR canning corridors.
- Aerosol Cosmetic Convergence:Fragrance and personal care brands in Japan are specifying polyester interior linings free from bisphenol derivatives, opening premium formulation demand.
- Modular System Architecture:Separating base-layer adhesion from top-layer functional performance enables applicators to customize without full reformulation, reducing SKU complexity for multi-brand coaters.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in waterborne epoxy-polyester hybrid systems resides with aging specialists in Germany and the Netherlands, constraining R&D throughput for next-generation compliant coatings.
- Certification Timeline Compression:FDA food-contact notification review periods and EFSA re-evaluation cycles for existing epoxy approvals create planning uncertainty for coating development pipelines.
- Legacy Equipment Retrofit Costs:Converting solvent-borne coating lines to waterborne-capable curing systems requires capital outlays that strain mid-size metal decorators in Eastern European markets.
Report Scope
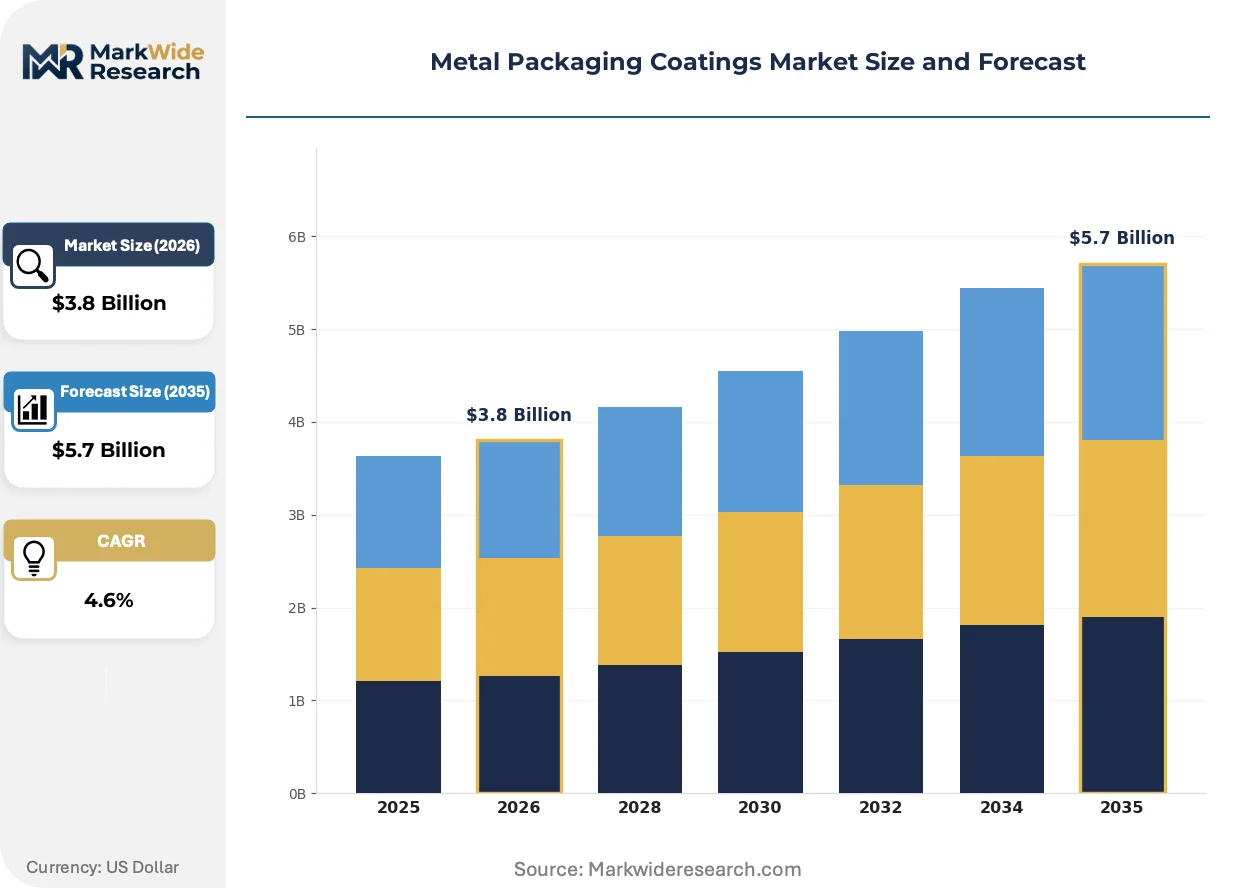
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Packaging Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyester, Acrylic, Vinyl Application: Food & Beverage, Cosmetics, Pharmaceuticals, Automotive End User: Consumer Goods, Industrial, Electronics, Building Formulation: Waterborne, Solventborne, High Solids, Powder |
| Companies Covered | The Sherwin-Williams Company, Nippon Paint Holdings, Axalta Coating Systems, Henkel AG & Co. KGaA, Kansai Paint, Akzo Nobel N.V., BASF SE, Arkema Group, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Packaging Coatings Market Strategic Shifts
Active chemistry migration, regulatory test-protocol evolution, and procurement specification tightening are compressing product development cycles and reshaping supplier qualification pathways in parallel.
Photoinitiated UV-curable coatings for three-piece food cans are electrifying the exterior decoration segment by eliminating thermal oven curing and reducing energy input requirements by half. Japanese beverage can manufacturers are piloting these systems for seasonal limited-edition runs requiring rapid color changeovers. The technology is electrifying competitive positioning among regional decorators who can advertise carbon footprint reductions to sustainability-focused brand owners.
EFSA's 2023 re-evaluation of bisphenol A migration limits and ongoing ECHA scrutiny under REACH restriction proposals are forcing reformulation roadmaps across European supply chains. Coating manufacturers must now maintain dual-track development for epoxy-based and epoxy-free interior systems pending final regulatory determinations. Food-contact coating applicators in France and Germany are responding by accelerating polyester and acrylic alternative validation programs ahead of potential mandate timelines.
Specification authority is consolidating from metal decorators toward filling equipment operators and ultimately to brand-owner technical teams who now dictate coating chemistry by SKU. This procurement centralization is displacing regional applicator autonomy in favor of approved-supplier lists managed by multinational beverage and food conglomerates. The pattern is most visible in North American craft brewing supply chains where canning line operators now require pre-qualified coating certifications before accepting decorated shell stock.
Metal Packaging Coatings Market Segmentation
Procurement specifications for metal packaging coatings diverge sharply across end-use verticals, with food-contact compliance requirements fragmenting formulation choices while automotive and industrial buyers prioritize corrosion resistance over migration-test certification. Understanding segment-level technical demands enables suppliers to align R&D investment with qualified-buyer concentration.
Coating Type:
Technical performance against acidic contents and regulatory migration limits differentiate buyer selection criteria across chemistry families.
- Epoxy:Thermosetting polymers derived from bisphenol A and epichlorohydrin deliver superior barrier performance against high-acid food matrices. Demand concentrates among two-piece aluminum beverage can manufacturers in the United States facing FDA food-contact notification requirements for interior linings.
- Polyester:Saturated polyester resins formulated without bisphenol derivatives are gaining specification share in European cosmetic aerosol segments where ECHA scrutiny under REACH intensifies. German filling equipment operators now require polyester validation for fragrance and personal care brands.
- Acrylic:Thermoplastic formulations offer UV stability and exterior durability for decorative lithography on three-piece food cans.
- Vinyl:PVC-based systems persist in industrial pail and drum applications where cost positioning outweighs food-contact compliance burdens.
Volume sits with epoxy systems; growth tilts toward polyester alternatives.
Application:
End-use migration-test protocols and thermal processing requirements create divergent specification tiers that reshape supplier qualification pathways.
- Food & Beverage:Interior linings must pass extraction testing under simulated thermal processing conditions, with dry-film thickness specifications of 4–12 micrometers. Japanese beverage can manufacturers are piloting photoinitiated UV-curable exterior coatings for seasonal limited-edition production runs requiring rapid color changeovers.
- Cosmetics:Fragrance and personal care brands in Japan specify polyester interior linings free from bisphenol derivatives, opening premium formulation demand for validated alternative chemistries.
- Pharmaceuticals:Barrier coatings for aerosol drug delivery systems require compliance with national pharmaceutical regulator standards in Germany and the Netherlands.
- Automotive:Corrosion-resistant coatings for brake fluid reservoirs and oil filter housings prioritize adhesion chemistry over food-contact migration protocols.
Procurement authority concentrates in food and beverage; cosmetics applications are climbing the fastest.
End User:
Scale economies and specification centralization patterns fragment addressable market structure across buyer categories.
- Consumer Goods:Multinational beverage and food conglomerates now dictate coating chemistry by SKU through approved-supplier lists, displacing regional metal decorator autonomy. North American craft brewing supply chains exemplify this shift, with canning line operators requiring pre-qualified coating certifications.
- Industrial:Mid-size toll coaters serving regional metal decorators in Eastern European markets face capital strain converting solvent-borne lines to waterborne-capable curing systems.
- Electronics:Precision coating requirements for EMI shielding cans in telecommunications equipment demand thickness uniformity beyond food-packaging tolerances.
- Building:Architectural metal trim and flashing applications prioritize exterior weatherability over interior migration compliance.
Revenue concentrates with consumer goods buyers; industrial segment expansion faces equipment retrofit constraints.
Formulation:
Regulatory emission thresholds and registration cost burdens restructure feasible product portfolios by geography and applicator scale.
- Waterborne:Epoxy and polyester dispersions command premium positioning in European supply chains as REACH registration costs and VOC emission thresholds eliminate smaller regional players in Italy and Spain. German applicators lead adoption due to environmental regulator enforcement patterns.
- Solventborne:Conventional systems retain cost advantage in industrial pail and drum segments where thermal oven curing infrastructure is already installed.
- High Solids:Reduced-solvent formulations bridge compliance and performance for mid-size decorators seeking incremental emission reduction without full waterborne conversion.
- Powder:Thermosetting powder coatings for exterior metal furniture and building components operate outside food-contact regulatory scope.
Installed base favors solventborne systems; waterborne formulations are gaining share fastest in Germany and France.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, Japan, and the United States, while consumption growth concentrates in India and Southeast Asian packaging corridors. This geographic split reshapes logistics costs and regional formulation strategies for coating suppliers.
Germany
REACH registration costs and EFSA migration-test protocols are eliminating smaller regional applicators in Bavaria and Baden-Württemberg. German filling equipment operators now mandate waterborne epoxy-polyester hybrid validation for beverage can interiors. The Rhine-Main industrial corridor hosts the highest concentration of qualified coaters serving branded-goods supply chains.
United States
FDA food-contact notification requirements for BPA-free interior linings are accelerating orders from craft beverage producers in Colorado and Oregon. Lightweighting demands drive coating specifications for two-piece aluminum cans with enhanced sidewall adhesion. Pacific Northwest canning clusters now require pre-qualified coating certifications before accepting decorated shell stock.
Japan
METI guidance on low-VOC industrial coatings aligns with Food Sanitation Law migration-testing protocols for food-contact applications. Photoinitiated UV-curable exterior coatings are piloting in Kansai-region beverage can plants for seasonal limited-edition production. Osaka-based decorators are electrifying competitive positioning through carbon footprint reduction claims.
India
FSSAI notification requirements for food-contact coatings remain underpenetrated by certified international suppliers in Maharashtra and Gujarat. Mumbai and Delhi-NCR canning corridors present first-mover positioning for compliant waterborne formulations. Domestic dairy and infant formula markets are tightening procurement specifications toward GB-standard-aligned low-VOC systems.
China
GB standards for food-contact coatings and dual carbon goals are restructuring feasible product portfolios for mid-size applicators in Guangdong and Zhejiang. Yangtze River Delta steel-and-aluminum rolling mills anchor Asian volume through long-term supply contracts. NMPA-aligned migration-testing protocols now exclude non-certified suppliers from branded-goods supply chains.
Metal Packaging Coatings Market Competitive Environment
The competitive structure tilts toward diversified chemical conglomerates with captive resin production and marine coatings heritage. Mid-size toll coaters face margin compression from epoxy resin input volatility and REACH compliance cost escalation. Three archetypes dominate: integrated coatings-resin producers, regional metal decorator partners, and specialty aerosol cosmetic formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek geographic coverage without full regulatory replication.
Among diversified chemical conglomerates, Akzo Nobel N.V., PPG Industries, and Kansai Paint occupy positions reflecting distinct geographic anchoring strategies. Akzo Nobel N.V. exemplifies the marine-to-packaging IP transfer archetype through corrosion-science application. PPG Industries represents North American supply relationship sustainment through captive production structures. Kansai Paint anchors Asian volume concentration through mill-integrated supply arrangements. These three entities illustrate how heritage specializations and regional production footprints shape competitive positioning without requiring identical capability replication across all markets.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Nippon Paint Holdings |
| Axalta Coating Systems |
| Henkel AG & Co. KGaA |
| Kansai Paint |
| Akzo Nobel N.V. |
| BASF SE |
| Arkema Group |
| PPG Industries |
| Others |
Value Chain & Pricing Dynamics
Bisphenol A and epichlorohydrin price volatility cascades through three-tier pricing structures across premium, standard, and economy levels, with REACH-registered European suppliers commanding premiums over toll coaters in Eastern European markets facing conversion capital constraints.
Pricing Analysis
Margin tightening in mid-size toll coating tiers reflects epoxy resin input volatility and REACH compliance cost escalation. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FDA food-contact notification holders capturing premiums. Cost-down pressure on waterborne formulations accelerates as German filling equipment operators consolidate approved-supplier lists. Industrial pail and drum buyers exhibit highest price sensitivity; cosmetic aerosol brands show lowest.
Supply Chain Analysis
Epoxy resin supply rests on petrochemical producers in Germany, the Netherlands, and the United States. Specialty bisphenol derivatives and photoinitiator chemicals draw from Japanese and South Korean specialty chemical manufacturers. Single-source vulnerability concentrates around epichlorohydrin purification capacity. Distribution runs through integrated steel-and-aluminum rolling mills in the Yangtze River Delta and captive resin production networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive resin production and marine coatings heritage represent the upstream levers incumbents are racing to control, while new entrants target certification gaps in underpenetrated geographies.
For Market Incumbents: To counter formulation chemist scarcity in waterborne epoxy-polyester hybrid systems, deepen backward integration into specialty resin production and accelerate EFSA-compliant alternative validation programs ahead of potential mandate timelines. Capacity addition in India and Southeast Asia addresses procurement centralization by multinational beverage conglomerates. For New Entrants and Emerging Players: Begin with FSSAI notification pathways in Maharashtra and Gujarat canning corridors, where certified international suppliers remain sparse. Target polyester interior lining validation for Japanese fragrance and personal care brands as the most penetrable premium segment. Pursue toll-manufacturing partnerships with regional metal decorators lacking waterborne conversion capital. For Investors and Strategic Acquirers: EFSA re-evaluation cycles for existing epoxy approvals accelerating is the leading indicator that dual-track R&D capabilities will separate viable targets from stranded assets. Five-to-ten year viability favors integrated coatings-resin producers with marine heritage IP transfer potential. Watch for REACH registration cost-driven consolidation among Italian and Spanish regional applicators as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive bisphenol derivative supply secures margin control against epichlorohydrin volatility. |
| Waterborne Line Conversion Partnerships | Toll-manufacturing agreements with Eastern European decorators expand geographic coverage without full regulatory replication. |
| EFSA-Compliant Alternative Validation | Polyester and acrylic interior lining certification opens specification share as epoxy scrutiny intensifies. |
| India FSSAI Certification First-Mover Positioning | Mumbai and Delhi-NCR dairy canning corridors offer uncaptured branded-goods supply chain access. |
| Photoinitiated UV-Curable System Deployment | Seasonal limited-edition beverage can production in Kansai region reduces energy input and carbon footprint claims. |
Study Parameters
Multi-period observation of REACH registration cost trajectories, EFSA scientific opinion timelines, and coating formulation patent filings anchored the trend analysis, supplemented by interviews with plant managers at German filling equipment operators, procurement leads at aluminum rolling mills, technical R&D directors at coating manufacturers, and channel partners in industrial distribution. Secondary validation drew from ECHA restriction proposal documentation, FDA food-contact notification databases, customs and trade data for epoxy resin imports, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across coating chemistry families.
Input-output matrices mapped bisphenol derivative supply through formulation tiers to end-use applications across the projection horizon. Segmentation dimensions modeled included coating chemistry family, substrate material, formulation type, end-use vertical, and regional regulatory cluster. CAGRs derived from regression analysis against macro industrial production indices and packaging material consumption trends. Forecast inputs incorporated EFSA re-evaluation cycle assumptions and waterborne adoption rate differentials by geography.
Underlying measurement precision varies by segment; waterborne epoxy and polyester alternatives carry tighter precision than emerging acrylic systems given regulatory validation maturity. Forecasts reflect documented assumptions around migration-test protocol evolution and dual-carbon policy implementation pace. Raw material price volatility, REACH restriction proposal outcomes, and certification timeline compression represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Metal Pails Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Saudi Arabia Metal Packaging Market