
 United States Aluminium Cans Market | 2026-2036
United States Aluminium Cans Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aluminium Cans Market Intelligence
Premium lightweight specification tiers is redrawing competitive boundaries across the United States aluminium cans landscape. Ball Corporation leverages its integrated aluminium supply chain to sustain cost leadership in 12 oz and 16 oz formats. Crown Holdings Inc. anchors its position through deep specialization in slim and specialty can geometries for craft beverage clients. Silgan Holdings Inc. differentiates via manufacturing scale across multiple diameter specifications serving both national and regional brands.
United States aluminium cans are cylindrical containers fabricated from aluminium alloy substrates typically containing magnesium and manganese additions, formed through deep drawing and wall ironing processes to achieve thin-walled structures with internal pressure resistance for carbonated and non-carbonated contents. Their primary commercial purpose centers on hermetic food and beverage preservation combined with lightweight logistics efficiency and infinite recyclability. The beverage end user segment dominates volume throughput given carbonated soft drink and beer packaging scale, while specialty can formats command margin premiums through differentiated branding surfaces and unique geometries. Slim can configurations within the product type dimension are gaining share among energy drink and ready-to-drink cocktail producers seeking shelf differentiation.
The EPA oversees recycling rate benchmarks and scrap content verification protocols that directly influence converter sourcing decisions and closed-loop collection infrastructure investment. FDA regulations governing food contact substances and migration limits shape internal coating specifications and alloy purity requirements for direct beverage contact applications. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and aluminium scrap price volatility as these forces will determine regional manufacturing economics and collection system profitability.
Market Dynamics
EPA recycled content mandates under the Resource Conservation and Recovery Act are forcing converters to restructure scrap sourcing relationships and invest in closed-loop collection infrastructure across Texas and the Southeast manufacturing corridors.
Growth Catalysts
- Recycled Content Mandates:EPA regulations under the Resource Conservation and Recovery Act compel converters to increase post-consumer scrap utilization, driving investment in domestic sorting and re-melt capacity.
- Craft Beverage Canning Expansion:Pacific Northwest craft beer producers are installing dedicated aluminium canning lines, displacing glass bottle dependency and creating regional demand clusters.
- Lightweight Specification Premiums:Advanced magnesium-manganese alloy formulations enable thinner wall structures that reduce material input costs while maintaining pressure resistance for carbonated contents.
Market Restraints
- Aluminium Scrap Price Volatility:London Metal Exchange pricing fluctuations for primary and secondary aluminium create margin compression for converters locked into fixed-price beverage contracts.
- Rolling Mill Concentration:Domestic flat-rolled aluminium supply concentrates in Texas and the Southeast, exposing can manufacturers to regional logistics bottlenecks and force majeure risks.
- Internal Coating Migration Limits:FDA food contact substance regulations impose strict epoxy-phenolic and polyester coating specifications that limit formulation flexibility and extend qualification timelines.
Strategic Opportunities
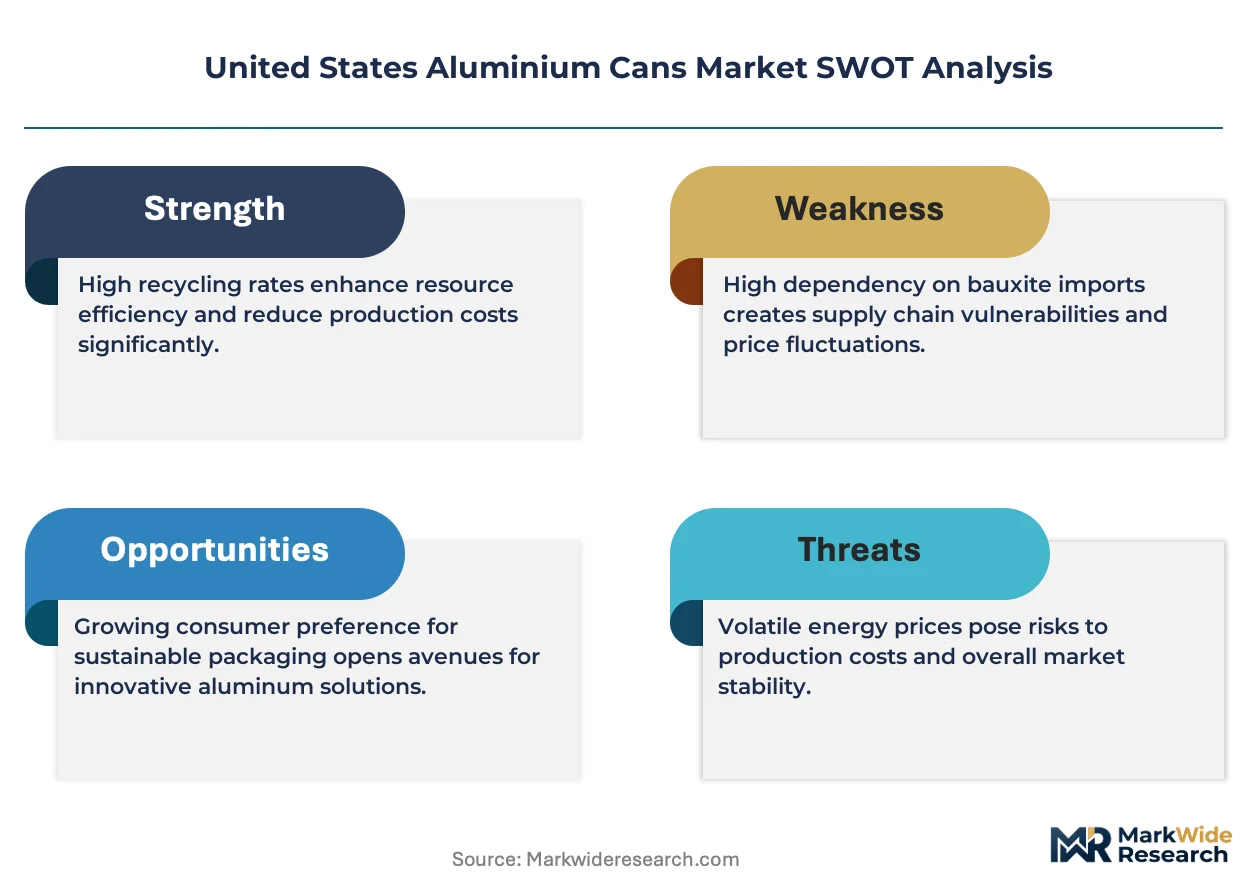
- State Extended Producer Responsibility Frameworks:Emerging deposit-return legislation in California and Northeastern states creates profitable closed-loop collection infrastructure investments with guaranteed scrap offtake.
- Ready-to-Drink Cocktail Formats:Slim can geometries for premium spirits mixers command shelf price premiums and attract brand owners seeking differentiation in convenience retail channels.
- Digital Printing Convergence:High-definition direct-to-can decoration technology enables short-run customization for regional craft brands, compressing minimum order quantities and expanding addressable customer bases.
Industry Challenges
- Deep Drawing Die Engineering Talent:Specialized tool-and-die expertise for thin-wall ironing processes remains concentrated among retiring workforce cohorts, constraining new line commissioning speed.
- Coating Qualification Timelines:FDA migration testing protocols for new internal lining chemistries extend certification cycles to 18-24 months, delaying product launches for reformulated specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aluminium Cans Market |
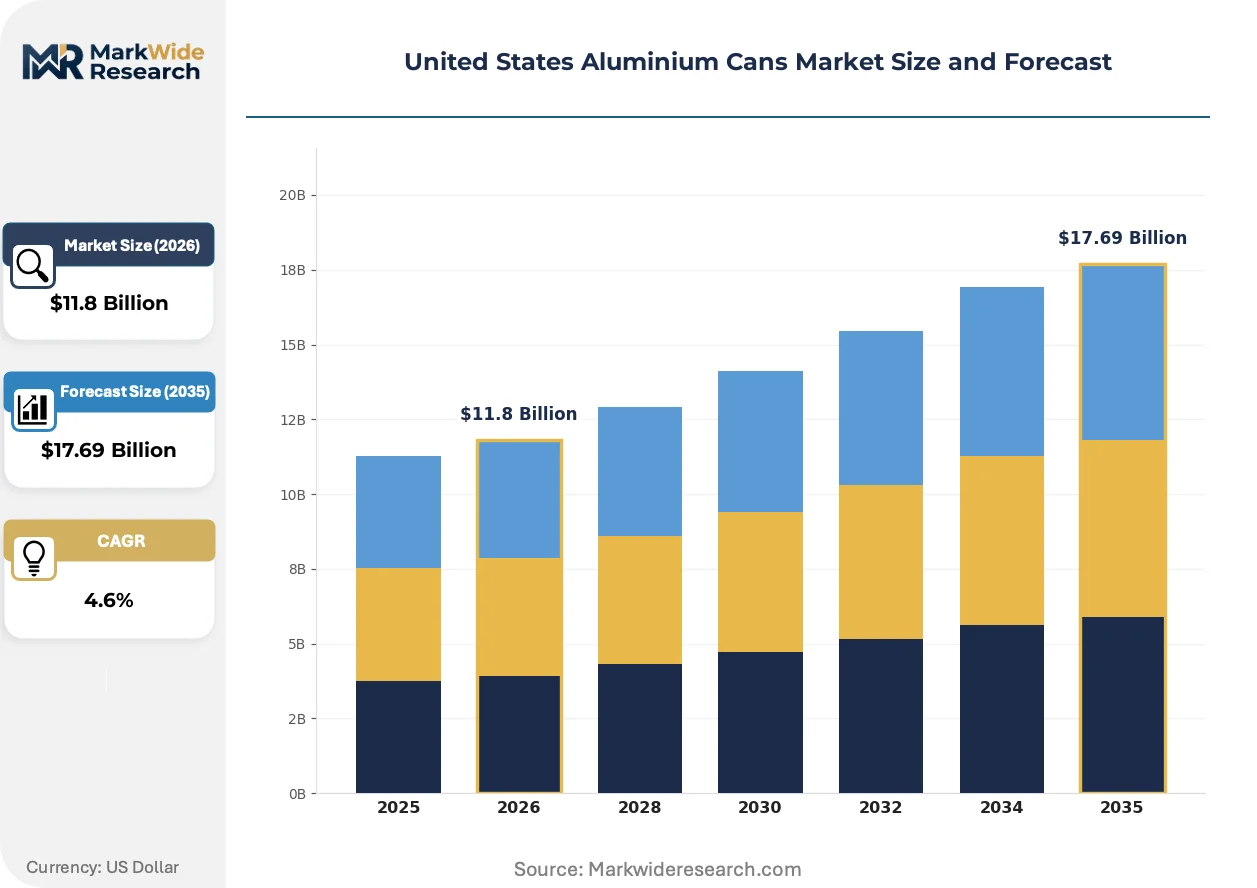
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Slim Cans, Specialty Cans, Bulk Cans End User: Beverage Industry, Food Industry, Personal Care, Household Products Size: 12 oz, 16 oz, 24 oz, 32 oz Manufacturing Stage: Recycling, Pre-production, Production, Post-production |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Silgan Holdings Inc., Ardagh Group S.A., CCL Industries Inc., CANPACK S.A., Envases Universales de México S.A. de C.V., Mauser Packaging Solutions, Novelis Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aluminium Cans Market Strategic Shifts & Innovations
Aluminium can manufacturing is experiencing material science and regulatory pressures that are compressing specification tolerances and expanding decoration capabilities simultaneously across domestic production networks.
Advanced magnesium-manganese alloy substrates with optimized grain structure are supplanting legacy 3004-series formulations in premium lightweight tiers. Energy drink and ready-to-drink cocktail producers are adopting these specifications fastest, typically within 12-18 month qualification windows. The shift is compressing material cost structures for early adopters while creating specification fragmentation that disadvantages smaller converters lacking metallurgical R&D capacity.
FDA migration limit updates for bisphenol-A alternatives in internal coatings are accelerating epoxy-phenolic replacement programs across domestic can lines. Converters must validate polyester and acrylic-based lining systems against revised food contact substance thresholds before 2026 compliance deadlines. Beverage segments with acidic contents, including craft seltzers and citrus-forward cocktails, face the most stringent retesting burdens and are prioritizing coating supplier partnerships with established FDA master file submissions.
Direct-to-can digital printing is displacing traditional offset lithography for short-run craft beverage contracts. Regional breweries in the Pacific Northwest and Colorado are consolidating decoration procurement with converters offering sub-50,000 unit minimums and 72-hour artwork changeover capabilities. This channel fragmentation is most visible in specialty retail and taproom direct distribution, where seasonal and limited-release SKUs outnumber core brand volumes.
United States Aluminium Cans Market Segmentation
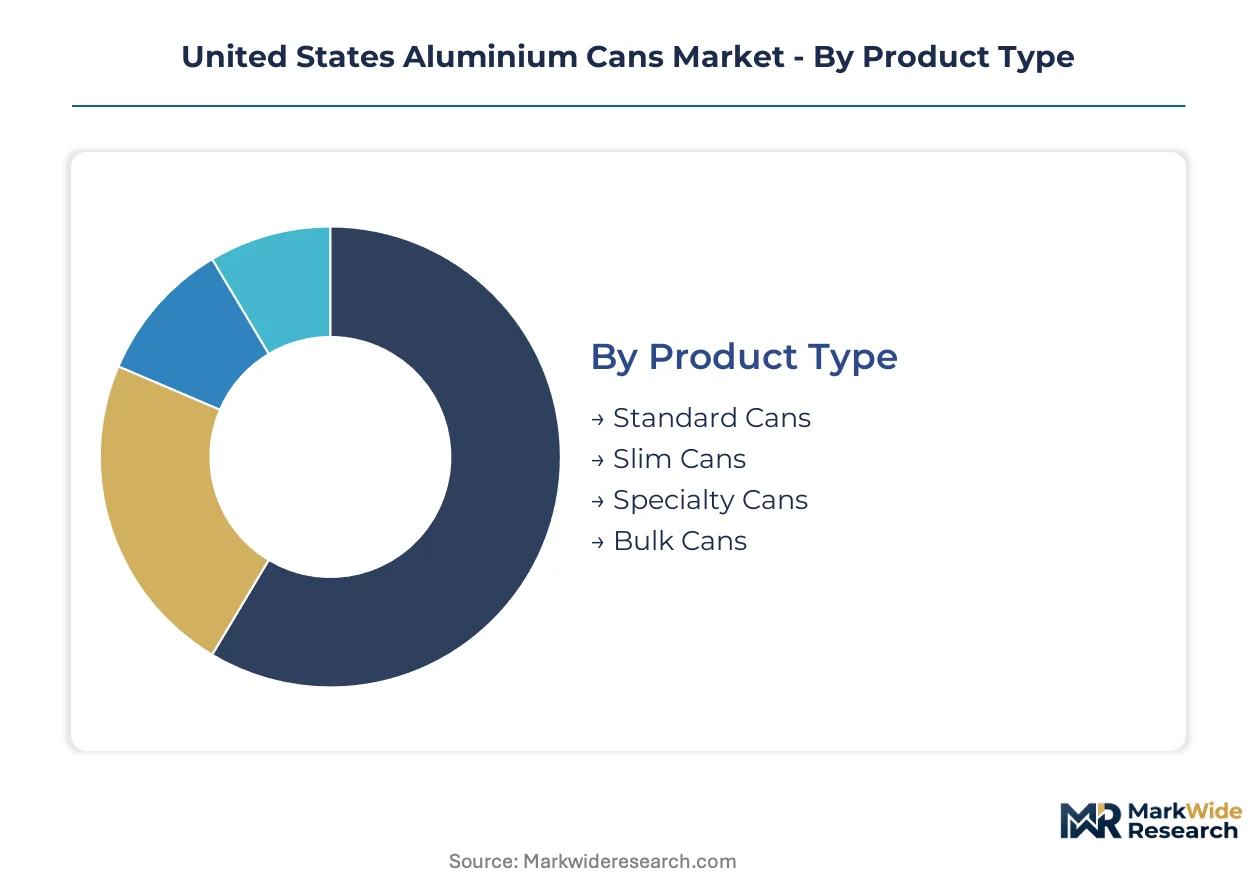
Aluminium can demand fragments across four distinct dimensions, each governing different margin structures and procurement patterns. Product geometry and end-use application determine specification complexity, while size and manufacturing stage segmentation control supply chain economics and regulatory exposure.
Product Type:
Channel mix varies sharply by geometry, with mass retail and convenience stores favoring high-velocity standard formats while on-premise and specialty retail concentrate demand for differentiated profiles.
- Standard Cans:Cylindrical 12 oz and 16 oz configurations with uniform diameter specifications serve carbonated soft drinks and mainstream beer brands. Demand concentrates in Texas and Southeast beverage manufacturing corridors where rolling mill proximity minimizes logistics costs for national brand owners.
- Slim Cans:Reduced-diameter geometries with elongated profiles accommodate energy drinks and ready-to-drink cocktails seeking shelf differentiation. Pacific Northwest craft producers and premium spirits mixers are expanding canning lines fastest, displacing glass dependency in convenience retail channels.
- Specialty Cans:Unique geometries including contoured bodies and shaped openings command decoration premiums for limited-release craft brands.
- Bulk Cans:Industrial-scale formats serve food service and institutional beverage dispensing with simplified coating specifications.
Standard Cans dominate installed base. Slim Cans is where expansion concentrates.
End User:
Cost tier stratification separates high-volume beverage contracts from specification-intensive food and personal care applications with stringent migration limits.
- Beverage Industry:Carbonated soft drinks, beer, energy drinks, and ready-to-drink cocktails constitute the volume anchor. EPA recycled content mandates under the Resource Conservation and Recovery Act are restructuring scrap sourcing relationships for major converters serving this segment.
- Food Industry:Acidic contents including tomatoes and citrus products impose the most demanding internal coating specifications. FDA food contact substance regulations drive 18-24 month qualification timelines for reformulated lining systems.
- Personal Care:Aerosol and dispensing applications require specialized valve integration and pressure resistance engineering.
- Household Products:Cleaning and automotive formulations utilize thicker gauge substrates with simplified decoration requirements.
Beverage Industry commands volume throughput. Food Industry carries the steepest compliance burden.
Size:
Volume scale concentrates in mainstream formats while premium positioning drives experimentation at capacity extremes.
- 12 oz:The foundational single-serve specification anchors carbonated soft drink and beer portfolios. National brand owners in Texas and Southeast manufacturing clusters negotiate long-term supply agreements locking in rolling mill offtake.
- 16 oz:Expanded capacity serves craft beer and energy drink positioning in convenience and gas station channels. Pacific Northwest producers are installing dedicated canning lines to capture this format's margin premium over glass alternatives.
- 24 oz:Multi-serve and value-tier applications target price-sensitive demographics in club retail.
- 32 oz:Crowler and large-format specialty applications serve taproom direct distribution with short-run digital decoration.
12 oz maintains production dominance. 16 oz is climbing the fastest among expanding formats.
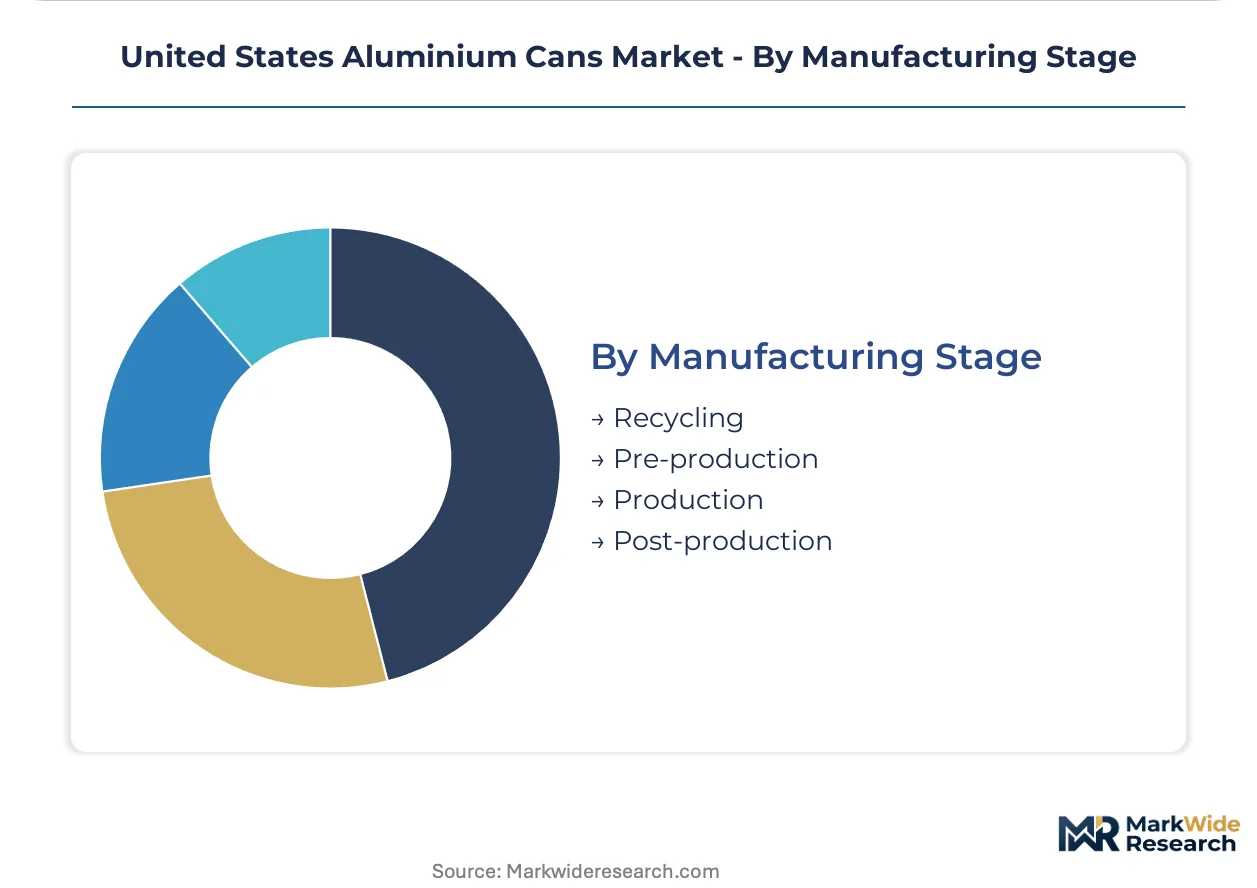
Manufacturing Stage:
Supply concentration and margin distribution vary across the value chain, with upstream recycling and downstream decoration commanding distinct competitive dynamics.
- Recycling:Closed-loop collection infrastructure investment is accelerating under EPA mandates, with guaranteed scrap offtake emerging in California and Northeastern deposit-return jurisdictions.
- Pre-production:Deep drawing die engineering and alloy formulation R&D concentrate among integrated converters with captive metallurgical expertise.
- Production:Wall ironing and coating application lines in Texas and Southeast corridors face force majeure exposure from regional rolling mill concentration.
- Post-production:Direct-to-can digital printing enables sub-50,000 unit minimums for regional craft brands, compressing artwork changeover timelines to 72 hours.
Production captures value-add concentration. Post-production is gaining share fastest through digital convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Texas and the Southeast exhibit the highest price elasticity, locking in long-term supply agreements with rolling mill proximity. Pacific Northwest craft producers show lower elasticity, prioritizing specification flexibility over unit cost. Northeastern states demonstrate intermediate elasticity, balancing deposit-return incentives against logistics premiums.
Texas
Carbonated soft drink and mainstream beer canning lines anchor demand volumes in the Dallas-Fort Worth and Houston corridors. EPA recycled content mandates under the Resource Conservation and Recovery Act are restructuring scrap sourcing relationships for converters operating here. Rolling mill concentration in East Texas exposes manufacturers to regional force majeure risks during extreme weather events.
Southeast
Beverage manufacturing clusters in Georgia and Florida are expanding aluminium canning capacity to serve convenience retail and gas station channels. State-level extended producer responsibility frameworks remain under legislative development, creating uncertainty for closed-loop collection investment timelines. The Atlanta metro area hosts multiple converter finishing lines that source coil from nearby rolling operations.
Pacific Northwest
Craft beer producers across Oregon and Washington are installing dedicated aluminium canning lines, displacing glass bottle dependency for taproom distribution. FDA food contact substance regulations govern internal coating specifications for acidic craft seltzers popular in this region. Seattle and Portland metros concentrate digital printing adoption for short-run seasonal SKUs with 72-hour artwork changeover requirements.
California
Deposit-return legislation creates profitable closed-loop collection infrastructure with guaranteed scrap offtake for converters serving energy drink and ready-to-drink cocktail producers. The state's beverage container recycling program mandates minimum recycled content thresholds that exceed federal EPA benchmarks. Los Angeles and Central Valley distribution hubs face inbound logistics premiums due to distance from domestic rolling mill supply.
Northeast
Extended producer responsibility frameworks in New York and Massachusetts are accelerating investment in sorting and re-melt capacity for post-consumer aluminium scrap. FDA migration limit updates for bisphenol-A alternatives impose 18-24 month coating qualification timelines on converters here. Boston and Philadelphia metros concentrate specialty can demand from premium spirits mixers seeking shelf differentiation in urban retail channels.
United States Aluminium Cans Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States aluminium cans landscape. Integrated converters with captive metallurgical expertise command specification innovation, while scale-focused operators compete on unit economics for high-volume beverage contracts. Three archetypes dominate: alloy formulation specialists, decoration technology leaders, and logistics-optimized mass producers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing rolling mill offtake agreements and digital printing capabilities respectively.
Among North American packaging specialists, Ball Corporation and Crown Holdings Inc. exemplify divergent strategic positions within the competitive structure. Ball Corporation represents the integrated supply chain archetype with backward integration into aluminium substrate production. Crown Holdings Inc. occupies a position emphasizing geometric specialization for differentiated beverage formats. Silgan Holdings Inc. anchors the multi-diameter scale tier, serving both national brand owners and regional craft producers across specification ranges. These three entities collectively illustrate how competitive positioning fragments across technology, cost, and customer-type vectors.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Silgan Holdings Inc. |
| Ardagh Group S.A. |
| CCL Industries Inc. |
| CANPACK S.A. |
| Envases Universales de México S.A. de C.V. |
| Mauser Packaging Solutions |
| Novelis Inc. |
| Others |
Cost & Logistics Intelligence
Long-term rolling mill offtake agreements lock in both aluminium coil supply access and price visibility for converters serving Texas and Southeast beverage manufacturing clusters, insulating participants from London Metal Exchange volatility while exposing them to force majeure risks from regional concentration.
Pricing Analysis
EPA recycled content mandates under the Resource Conservation and Recovery Act dictate the pricing tier structure across the United States aluminium cans landscape. Three-tier pricing structure across premium lightweight, standard specification, and economy gauge levels separates converters by metallurgical R&D capability. Pricing pressure stems from aluminium scrap price volatility compressing margins for participants locked into fixed-price beverage contracts. National brand owners in Texas demonstrate highest price sensitivity, while Pacific Northwest craft producers prioritize specification flexibility over unit cost.
Supply Chain Analysis
Texas and the Southeast anchor domestic flat-rolled aluminium supply for can manufacturing, with Georgia and Florida hosting multiple converter finishing lines. Deep drawing die engineering and magnesium-manganese alloy substrates feed from captive metallurgical expertise concentrated among integrated players. Single-source vulnerability runs through East Texas rolling mill concentration during extreme weather events. Distribution runs through beverage manufacturing corridors with proximity to coil supply determining logistics economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States aluminium cans fragmentation creates opportunity niches as craft beverage producers displace glass dependency and demand sub-50,000 unit digital decoration runs.
For Market Incumbents: Shield market position by securing captive aluminium substrate supply through backward integration into rolling mill offtake, and accelerate FDA-compliant coating qualification programs to outpace 18-24 month certification timelines. Emerging state extended producer responsibility frameworks threaten collection infrastructure control, making regional scrap sourcing partnerships the priority lever. For New Entrants and Emerging Players: Lead with direct-to-can digital printing capabilities targeting Pacific Northwest craft breweries and Colorado taproom distribution, where seasonal SKU proliferation outpaces core brand volumes. The most penetrable segment sits in slim can geometries for ready-to-drink cocktails, with 72-hour artwork changeover serving as the specific go-to-market angle. For Investors and Strategic Acquirers: Alloy formulation specialists with established FDA master file submissions represent the most attractive acquisition target archetype, given coating migration limit updates accelerating epoxy-phenolic replacement programs. Long-term viability over the mid-term projection horizon hinges on metallurgical R&D capacity and regulatory qualification speed. The signal to watch is state-level deposit-return legislation expansion creating guaranteed scrap offtake jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Rolling Mill Offtake Agreement | Secures aluminium coil supply for Texas and Southeast manufacturing corridors against force majeure exposure. |
| Digital Printing Capability Acquisition | Enables sub-50,000 unit minimums for Pacific Northwest craft beverage seasonal SKU proliferation. |
| FDA Coating Qualification Investment | Accelerates epoxy-phenolic replacement programs ahead of bisphenol-A alternative migration deadlines. |
| Closed-Loop Collection Infrastructure | Captures guaranteed scrap offtake in California and Northeastern deposit-return jurisdictions. |
| Slim Can Geometry Expansion | Targets ready-to-drink cocktail shelf differentiation in convenience retail channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage procurement managers, converter plant engineers, rolling mill sales directors, and EPA compliance officers. Secondary validation drew from FDA food contact substance filings, EPA Resource Conservation and Recovery Act guidance documents, London Metal Exchange pricing data, and state-level extended producer responsibility legislative records. Bottom-up volume triangulation across product type, end user, size, and manufacturing stage dimensions was cross-checked against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework models aluminium can demand by product geometry, beverage application, specification tier, and regional manufacturing cluster. CAGRs were derived from segment-level growth trajectory analysis. Industry-specific inputs include craft beverage canning line installation rates, recycled content mandate compliance timelines, and digital printing adoption curves among regional brands.
The analysis sits within stated boundaries; outcomes outside sustained EPA mandate enforcement, rolling mill capacity stability, or aluminium scrap price regime continuity would require recalibration. Forecasts reflect documented assumptions regarding coating qualification timeline compression and state-level deposit-return expansion. Recalibration cycles align with material shifts in regulatory compliance deadlines and metallurgical specification migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
PTP Aluminum Foil Market