
 Metal Drums Market | 2026-2036
Metal Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Drums Market Foresight
Single-source to multi-source drum procurement is recalibrating how chemical and petroleum buyers manage supply risk. Greif, Inc. leverages its North American reconditioning network to offer closed-loop drum programs. Mauser Packaging Solutions anchors European demand through its industrial packaging footprint across Germany and the Netherlands. Schütz GmbH & Co. KGaA differentiates via integrated IBC and steel drum systems for chemical logistics.
Metal drums are cylindrical steel or aluminum containers, typically 55 gallons in nominal capacity, fabricated through seam welding or rolling with chime reinforcement for stacking strength. They serve as primary shipping and storage vessels for liquids, powders, and hazardous materials under UN certification standards. Tight head drums dominate hazardous chemical applications due to their sealed top-and-bottom construction and pressure-relief options. Stainless steel variants command premium positioning in pharmaceutical and food processing end uses where corrosion resistance and cleanability requirements apply. Open head drums retain volume leadership in solid waste and general manufacturing segments where access and reusability outweigh sealing demands.
EPA hazardous waste regulations and DOT 49 CFR packaging standards govern drum specifications for chemical and petroleum transport in the United States. OSHA mandates secondary containment and drum integrity testing protocols that extend replacement cycles and quality requirements. The EU REACH framework and F-Gas Regulation indirectly shape drum demand through chemical phase-outs and substitution patterns. Stakeholders must monitor evolving UN performance-oriented packaging standards and regional carbon-border adjustments that could alter steel sourcing economics for drum fabrication.
Market Dynamics
REACH and OSHA mandates for thicker-gauge steel and improved seam welding are forcing chemical manufacturers in Germany and the US to replace entire drum fleets, creating simultaneous supply compression and demand surge across the hazardous materials packaging sector.
Growth Catalysts
- REACH Phase-Out Mandates:Chemical substitution requirements under EU REACH are generating drum replacement cycles as reformulated products demand upgraded containment specifications.
- US Gulf Coast Petrochemical Expansion:New ethylene and propylene capacity along the Texas-Louisiana corridor is scaling drum procurement volumes for intermediate chemical storage.
- Stainless Steel Pharmaceutical Adoption:Cleanability requirements in sterile manufacturing are displacing carbon steel drums in vaccine and biologics production facilities.
Market Restraints
- Steel Price Volatility:Hot-rolled coil input costs fluctuate with energy pricing and scrap availability, compressing fabricator margins and destabilizing contract pricing.
- Chinese Supply Concentration:Over half of global steel drum manufacturing capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for European and North American buyers.
- Composite IBC Substitution:Intermediate bulk containers from Schütz and Mauser are capturing liquid chemical volumes above 300 liters through reduced tare weight and collapsible return logistics.
Strategic Opportunities
- India Chemical Manufacturing:PLI scheme incentives for specialty chemicals and agrochemicals are building drum demand in Gujarat and Maharashtra industrial corridors.
- Closed-Loop Reconditioning:Drum leasing and reconditioning networks offer service revenue streams that decouple growth from virgin steel consumption.
- UN Performance Testing Harmonization:Converging certification standards across DOT 49 CFR, ADR, and IMDG Code are reducing multi-jurisdiction compliance costs for drum exporters.
Industry Challenges
- Welding Certification Scarcity:UN-certified seam welders require specialized training and audit trails that lag demand expansion in Eastern European and Southeast Asian fabrication hubs.
- Legacy Fleet Compatibility:Existing drum handling equipment and filling lines constrain rapid adoption of modified chime geometries or alternative closure systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Drums Market |
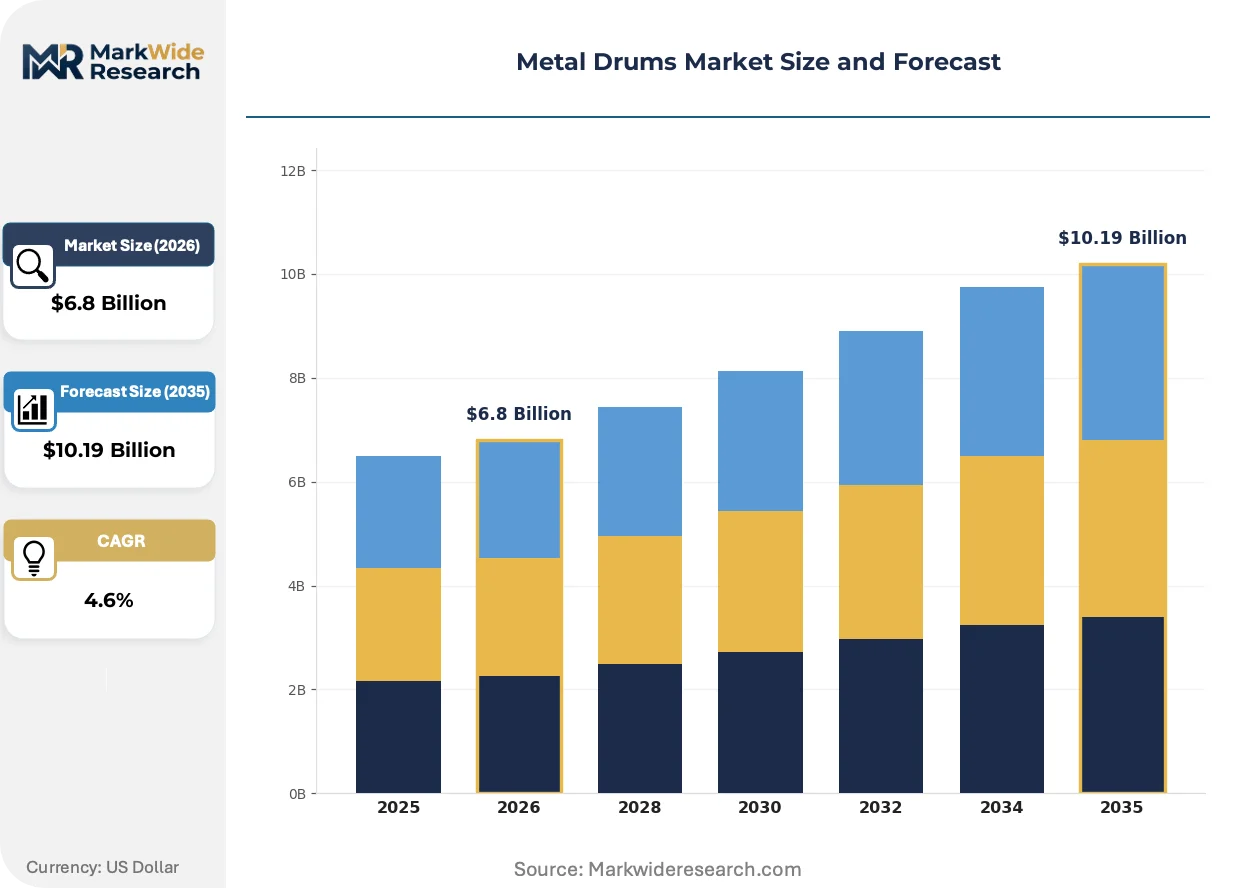
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head, Tight Head, Tapered, Specialty Drums Material: Steel, Aluminum, Stainless Steel, Coated Steel Application: Liquid Storage, Solid Waste, Chemical Transport, Food Processing End User: Manufacturing, Construction, Oil & Gas, Pharmaceuticals |
| Companies Covered | North Coast Container Corp., General Steel Drum LLC, Greif, Inc., Time Technoplast Ltd., Balmer Lawrie & Co. Ltd., Mauser Packaging Solutions, Rahway Steel Drum Company, Skolnik Industries, Inc., Schütz GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Drums Market Shifts & Advancements
Digital tracking technologies and predictive integrity monitoring are embedding intelligence into drum assets, transforming passive containers into data nodes within chemical supply chain networks.
Laser seam welding with real-time penetration monitoring is integrating quality assurance directly into production lines. Pharmaceutical and food-grade drum buyers in Switzerland and the Netherlands are specifying this technology for lot-traceable weld documentation. The process is integrating automated defect detection that eliminates post-fabrication radiographic testing bottlenecks.
EPA hazardous waste manifest digitization under the e-Manifest system is forcing drum serialization and blockchain-anchored chain-of-custody records. Chemical waste generators in Ohio and Texas must now tag containers with unique identifiers readable across treatment, storage, and disposal facilities. Small hazardous waste handlers are consolidating vendor relationships to reduce compliance fragmentation.
Chemical buyers are compressing drum supplier panels from six-plus vendors to two or three strategic partners with integrated reconditioning capabilities. This concentration is visible across BASF and Dow procurement functions in Ludwigshafen and Lake Jackson, where total cost of ownership models now weight logistics coordination above unit pricing. German chemical clusters are piloting vendor-managed inventory programs with drum fleet optimization software.
Metal Drums Market Segmentation
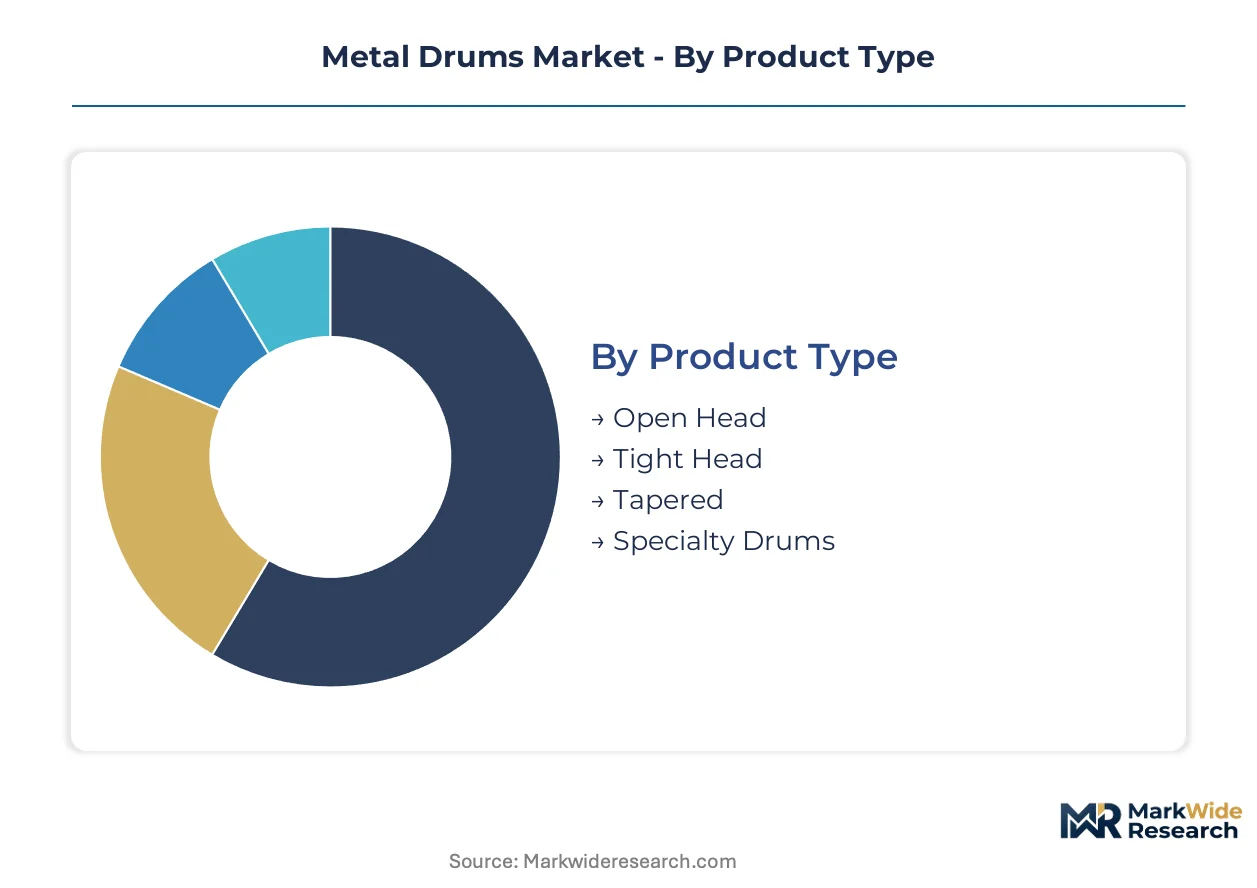
Metal drum buyers select specifications based on containment requirements, regulatory certification, and handling infrastructure compatibility. Each segment tier carries distinct cost structures and replacement cycles that shape procurement strategy across chemical and industrial end uses.
Product Type:
Drum head configuration determines sealing integrity and access protocols, driving upgrade cycles as REACH and OSHA mandates force fleet replacements.
- Tight Head:Factory-sealed top and bottom construction with rolled seams provides maximum containment for hazardous liquids. Chemical manufacturers in Germany and along the US Gulf Coast are replacing carbon steel tight head fleets with thicker-gauge variants to meet new seam welding standards.
- Open Head:Removable lid design with bolt ring or lever lock closure enables repeated access for solids and viscous materials. General manufacturing facilities in Ohio and Texas favor open head drums for waste collection where UN certification requirements are less stringent than chemical transport.
- Tapered:Nesting geometry reduces return shipping volume for reusable drum programs. Reconditioning networks leverage tapered designs to optimize backhaul logistics across North American closed-loop systems.
- Specialty Drums:Custom diameters, linings, or pressure ratings serve pharmaceutical and nuclear applications with non-standard containment protocols.
Tight Head sits at the top of the volume ranking, with Specialty Drums climbing the fastest.
Material:
Material selection balances corrosion resistance against unit economics, with premium grades displacing standard carbon steel in regulated applications.
- Steel:Hot-rolled carbon steel dominates bulk chemical and petroleum storage through cost efficiency and structural durability. Fabricators in Shandong province supply the majority of global steel drum capacity, creating procurement concentration risk for European and North American buyers.
- Stainless Steel:304 and 316 grades deliver pharmaceutical-grade cleanability and acid resistance. Vaccine production facilities in Switzerland and the Netherlands specify stainless steel for sterile manufacturing environments where carbon steel corrosion is unacceptable.
- Aluminum:Lightweight properties suit aviation fuel and specialty chemical transport where tare weight reduction offsets higher material cost.
- Coated Steel:Epoxy or phenolic linings extend carbon steel compatibility to mildly corrosive chemicals without full stainless steel investment.
Steel commands the largest volume position, while Stainless Steel expands most quickly.
Application:
Application segments align with regulatory complexity tiers, from standard industrial handling to hazardous material protocols.
- Chemical Transport:UN-certified packaging for dangerous goods mandates specific seam welding, pressure relief, and labeling standards. DOT 49 CFR and ADR compliance drives drum replacement cycles as certification standards tighten.
- Liquid Storage:Intermediate chemical holding and bulk inventory management requires drum fleets with extended outdoor weathering resistance.
- Solid Waste:RCRA hazardous waste containment under EPA e-Manifest digitization rules now requires serialized drum tracking from generator to disposal facility.
- Food Processing:FDA-compliant drum specifications govern edible oil and ingredient storage with strict cleanability and material migration limits.
Chemical Transport leads volume, with Food Processing gaining share fastest.
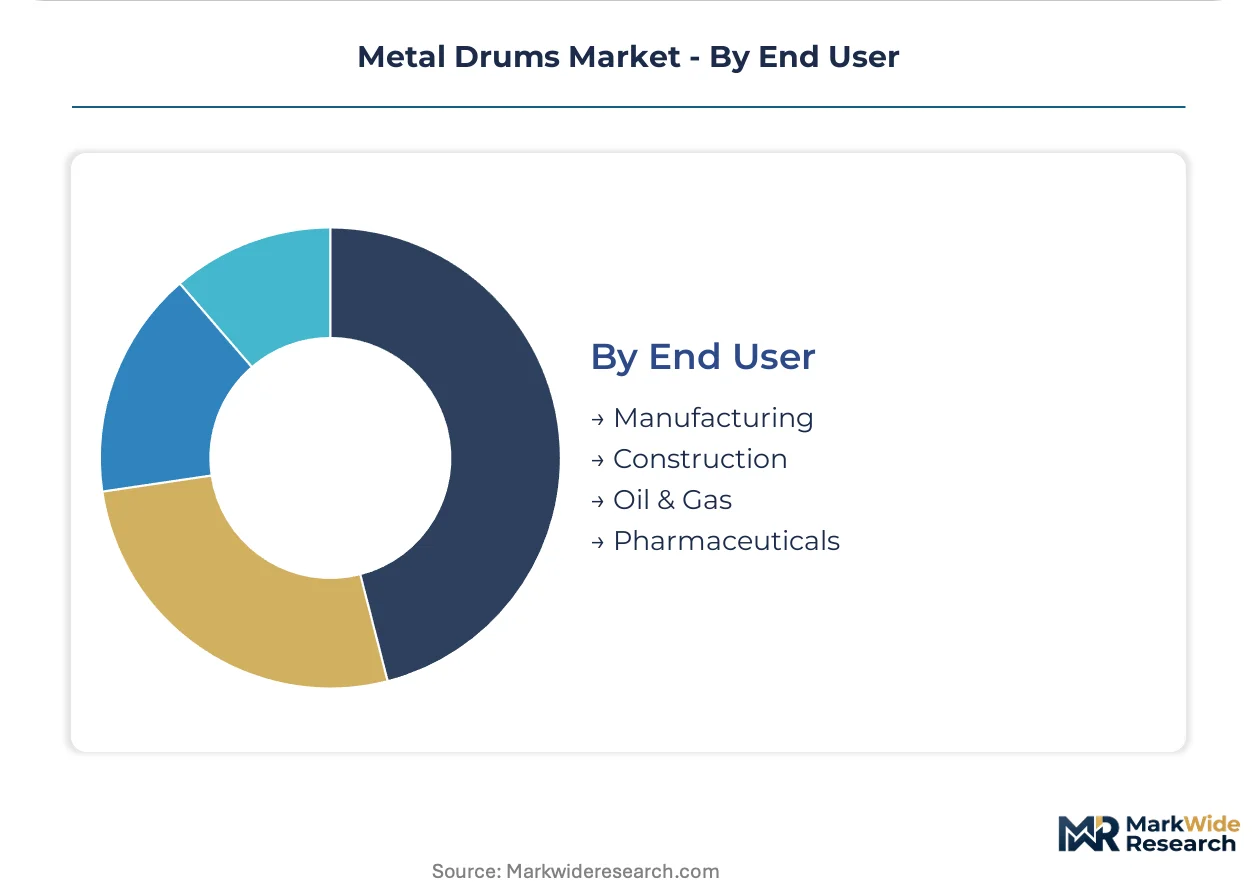
End User:
End user segments reflect vertical-specific drum specifications and procurement consolidation patterns.
- Oil & Gas:Upstream drilling fluids, downstream lubricants, and midstream transport all require UN-certified steel drums with pressure relief. Petrochemical expansion along the Texas-Louisiana corridor is scaling procurement volumes for intermediate storage.
- Pharmaceuticals:Sterile manufacturing and active pharmaceutical ingredient handling specify stainless steel with lot-traceable weld documentation. Swissmedic and FDA cGMP requirements drive premium material selection.
- Manufacturing:General industrial chemicals, coatings, and adhesives represent the broadest drum consumption base with the most price-sensitive procurement.
- Construction:Solvent-based coatings, sealants, and adhesives require standard steel drums with limited specialty specification.
Manufacturing holds the top volume position, with Pharmaceuticals climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting drum fabrication toward jurisdictions where REACH-equivalent compliance costs less, while end-use demand concentrates in petrochemical corridors with stringent local standards.
United States
OSHA mandates for thicker-gauge steel and improved seam welding are forcing chemical manufacturers along the Texas-Louisiana Gulf Coast to replace entire drum fleets. The EPA's e-Manifest digitization rules now require serialized tracking from generator to disposal facility. Houston and Lake Jackson anchor procurement scaling for ethylene and propylene intermediate storage.
Germany
REACH phase-out mandates for chemical substitution are generating drum replacement cycles as reformulated products demand upgraded containment specifications. ECHA enforcement of UN performance-oriented packaging standards tightens certification requirements for cross-border chemical transport. The Ludwigshafen chemical cluster is piloting vendor-managed inventory programs with drum fleet optimization software.
China
Over half of global steel drum manufacturing capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for European and North American buyers. MEE environmental inspections and dual carbon goals are pressuring fabricators to upgrade welding emissions controls. Zhejiang and Guangdong provinces are seeing capacity consolidation as smaller shops fail compliance audits.
India
PLI scheme incentives for specialty chemicals and agrochemicals are building drum demand in Gujarat and Maharashtra industrial corridors. BIS certification requirements for hazardous goods packaging are tightening import substitution pressures on domestic fabrication. The Mundra-Dahej belt is scaling drum procurement for export-oriented chemical manufacturing.
Switzerland
Swissmedic and FDA cGMP requirements for sterile manufacturing are driving premium stainless steel drum specification in vaccine and biologics production. Lot-traceable weld documentation mandates favor laser seam welding with real-time penetration monitoring. Basel and Zurich pharmaceutical clusters specify 316-grade drums for active pharmaceutical ingredient handling.
Metal Drums Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue reconditioning and closed-loop service models to escape commodity steel pricing. The vendor base stratifies across integrated multinationals with reconditioning networks, regional fabricators serving single-country demand, and specialty shops focused on pharmaceutical-grade certification. Three archetypes dominate: scale-driven volume players, reconditioning-integrated service providers, and premium-tier stainless steel specialists. Competitive moves concentrate on M&A for reconditioning network density and backward integration into steel coil sourcing.
Among North American fabricators, Greif, Inc. and General Steel Drum LLC exemplify the reconditioning-integrated archetype, while Schütz GmbH & Co. KGaA anchors European positioning through its industrial packaging footprint. Mauser Packaging Solutions occupies a position spanning both continents with IBC and steel drum system integration.
| Leading Market Players |
|---|
| North Coast Container Corp. |
| General Steel Drum LLC |
| Greif, Inc. |
| Time Technoplast Ltd. |
| Balmer Lawrie & Co. Ltd. |
| Mauser Packaging Solutions |
| Rahway Steel Drum Company |
| Skolnik Industries, Inc. |
| Schütz GmbH & Co. KGaA |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up reconditioning specialists have consolidated North American drum networks, tightening supply discipline while extracting service-margin premiums from chemical buyers seeking closed-loop fleet management. This ownership concentration feeds directly into pricing power, as Greif and Mauser leverage network density to bundle reconditioning with virgin drum supply and resist spot-market commoditization.
Pricing Analysis
Distributor margin compression in standard carbon steel drums is forcing fabricators to shift volume through direct-to-OEM contracts with BASF and Dow procurement functions. Three-tier pricing structure across premium, standard, and economy levels separates UN-certified laser-welded pharmaceutical drums from commodity tight-head chemical transport units. Cost compression in standard steel tiers is intensifying because hot-rolled coil input volatility prevents long-term contract stabilization. General manufacturing buyers in Ohio and Texas exhibit highest price sensitivity, while Swiss pharmaceutical facilities accept 40-60% premiums for lot-traceable stainless steel documentation.
Supply Chain Analysis
UN-certified seam welder qualification gates capacity expansion, as Eastern European and Southeast Asian fabrication hubs lack audit-trail infrastructure for hazardous goods certification. Manufacturing concentrates in China, Germany, and the United States, with Shandong province alone hosting over half of global steel drum fabrication. Raw material flows draw from hot-rolled coil mills, scrap steel recyclers, and specialty 316-grade stainless suppliers. Single-source vulnerability in Chinese capacity creates structural risk for European and North American buyers facing MEE environmental compliance crackdowns. Distribution runs through chemical distributor networks, direct mill-to-plant contracts, and reconditioning service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in metal drums rests on reconditioning service revenue capture and stainless steel tier mix shift toward pharmaceutical certification, not virgin steel volume growth.
For Market Incumbents: Deploy reconditioning network density as the primary defensive lever. Expand captive reconditioning capacity in the US Gulf Coast corridor to lock in ethylene and propylene intermediate storage contracts before composite IBC substitution accelerates. Deepen backward integration into steel coil sourcing through mill partnerships that stabilize input cost exposure against scrap volatility. For New Entrants and Emerging Players: REACH phase-out mandates in Germany open a window for specialty drum fabrication serving reformulated chemical containment specifications. Target stainless steel pharmaceutical drum production in Switzerland and the Netherlands where Swissmedic lot-traceability requirements deter commodity competition. Pursue vendor-managed inventory partnerships with Ludwigshafen and Basel chemical clusters as the go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking reconditioning integration but holding UN certification infrastructure. Five-to-ten-year viability favors assets with laser seam welding capability and pharmaceutical-grade cleanroom access. Watch EPA e-Manifest enforcement intensity as the inflection signal—accelerated serialization mandates will consolidate vendor relationships toward integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Sourcing | Captive hot-rolled coil supply locks in margin stability against scrap price volatility. |
| Laser Seam Welding Certification Investment | Real-time penetration monitoring meets Swissmedic lot-traceability mandates for pharmaceutical drums. |
| Closed-Loop Reconditioning Network Expansion | Service revenue decouples growth from virgin steel consumption in Greif's North American model. |
| Vendor-Managed Inventory Programs | BASF and Dow pilot fleet optimization software with Ludwigshafen chemical cluster partners. |
| Stainless Steel Pharmaceutical Tier Capacity Buildout | 316-grade drum production captures vaccine and biologics cleanability premiums in Basel. |
Research Methodology
Direct dialogue with drum fabrication plant managers, chemical procurement leads at downstream OEMs, reconditioning network operators, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed packaging companies, and UN performance-oriented packaging certification databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated against shipment data and replacement cycle assumptions.
Bottom-up volume builds aggregated individual country-level fabrication capacity, utilization rates, and replacement cycle timing across the projection horizon. Segmentation dimensions modeled include head configuration, material grade tier, end-use industry application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical shipment patterns against petrochemical capacity expansion timelines and REACH-driven fleet replacement schedules. Forecast inputs incorporated steel coil price elasticity coefficients and UN certification audit backlog durations.
Revisions become necessary when EPA e-Manifest enforcement intensity, REACH chemical substitution pace, or Chinese MEE environmental compliance actions materialize outside baseline assumptions. Forecasts reflect documented assumptions regarding welding certification training pipeline expansion and stainless steel pharmaceutical adoption curves. A model refresh is warranted upon material change in hot-rolled coil input cost volatility or composite IBC substitution rates in liquid chemical transport above 300 liters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Household Aluminum Foils Market