
 Aluminium Bottle Market | 2026-2036
Aluminium Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Bottle Market Outlook
Lightweight alloy formulation and inline digital printing is reshaping aluminium bottle production economics across packaging tiers. Ball Corporation leverages captive aluminium supply and aerospace-grade metalworking heritage to dominate North American beverage can and bottle conversion. Trivium Packaging sustains European leadership through integrated aerosol and beverage aluminium forming operations across multiple plants. Crown Holdings anchors Asia-Pacific expansion with high-speed necking and shaping lines purpose-built for local beverage brands.
An aluminium bottle is a rigid metal container formed from aluminium alloy sheet through deep drawing, ironing, and necking processes, typically achieving wall thickness below 0.3 millimetres while maintaining internal pressure resistance to 90 psi or higher. Its primary commercial purpose is to store carbonated beverages, cosmetics, and pharmaceutical formulations with complete light and oxygen barrier protection. Screw cap configurations command the largest volume share due to universal compatibility with beverage filling lines and consumer reseal expectations. Food and Beverage end-use absorbs the majority of output, though Cosmetics applications generate disproportionate margin pools through premium finishing and custom shaping. Spray and push-pull closure systems represent the fastest-growing product type segment, driven by personal care and household chemical dispensing requirements.
The US FDA governs direct food contact aluminium surfaces through 21 CFR 177.1390 laminate specifications, while EU REACH and F-Gas Regulation constrain coating chemistries and aerosol propellant choices across European production. EPA emissions guidelines and state-level bottle deposit laws in California, Oregon, and New York shape regional manufacturing location decisions and recycling infrastructure investment. Stakeholders must monitor evolving extended producer responsibility frameworks and alloy sourcing certification standards as determinants of market access and brand positioning.
Market Dynamics
Substitution pressure from EU Single-Use Plastics Directive enforcement is collapsing virgin PET demand curves across beverage packaging, redirecting brand capex toward aluminium forming capacity and inline coating infrastructure.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for single-use plastic containers are forcing beverage brand reformulation toward aluminium alternatives across Germany, France, and Italy.
- Lightweighting alloy innovations:Next-generation 3104-H19 and 5182-H48 sheet formulations enable sub-0.25mm wall thickness without pressure rating degradation, unlocking cost parity with PET at scale.
- Cosmetics end-use premiumization:Skincare and fragrance houses in Switzerland and France are specifying anodized aluminium bottles with digital print personalization, commanding 3-4x unit economics versus glass.
Market Restraints
- Primary aluminium ingot volatility:London Metal Exchange price swings above 15% annually compress converter margin structures and deter long-term supply contracts.
- Coating chemistry constraints:EU REACH Annex XVII restrictions on bisphenol-A epoxy liners force costly migration to polyester-phenolic hybrid systems with unproven shelf-life performance.
- Glass bottle residual preference:Premium mineral water brands in Italy and France maintain consumer loyalty to traditional packaging, slowing aluminium penetration in highest-margin segments.
Strategic Opportunities
- Refillable bottle system expansion:Germany's Pfand deposit-return infrastructure supports 50+ reuse cycles per aluminium vessel, creating closed-loop revenue models absent in single-use markets.
- Personal care spray applications:Aerosol-compatible aluminium bottles with bag-on-valve technology are capturing share from tinplate in deodorant and dry shampoo segments.
- Digital print convergence:Single-pass inkjet decoration enables lot-size-one production economics, collapsing minimum order quantities and unlocking micro-brand access.
Industry Challenges
- Deep-draw tooling expertise scarcity:Qualified die designers and ironing process engineers command premium compensation, constraining brownfield capacity expansion timelines.
- Multi-layer liner qualification delays:FDA 21 CFR 177.1390 compliance testing for new coating chemistries extends 18-24 months, freezing product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Bottle Market |
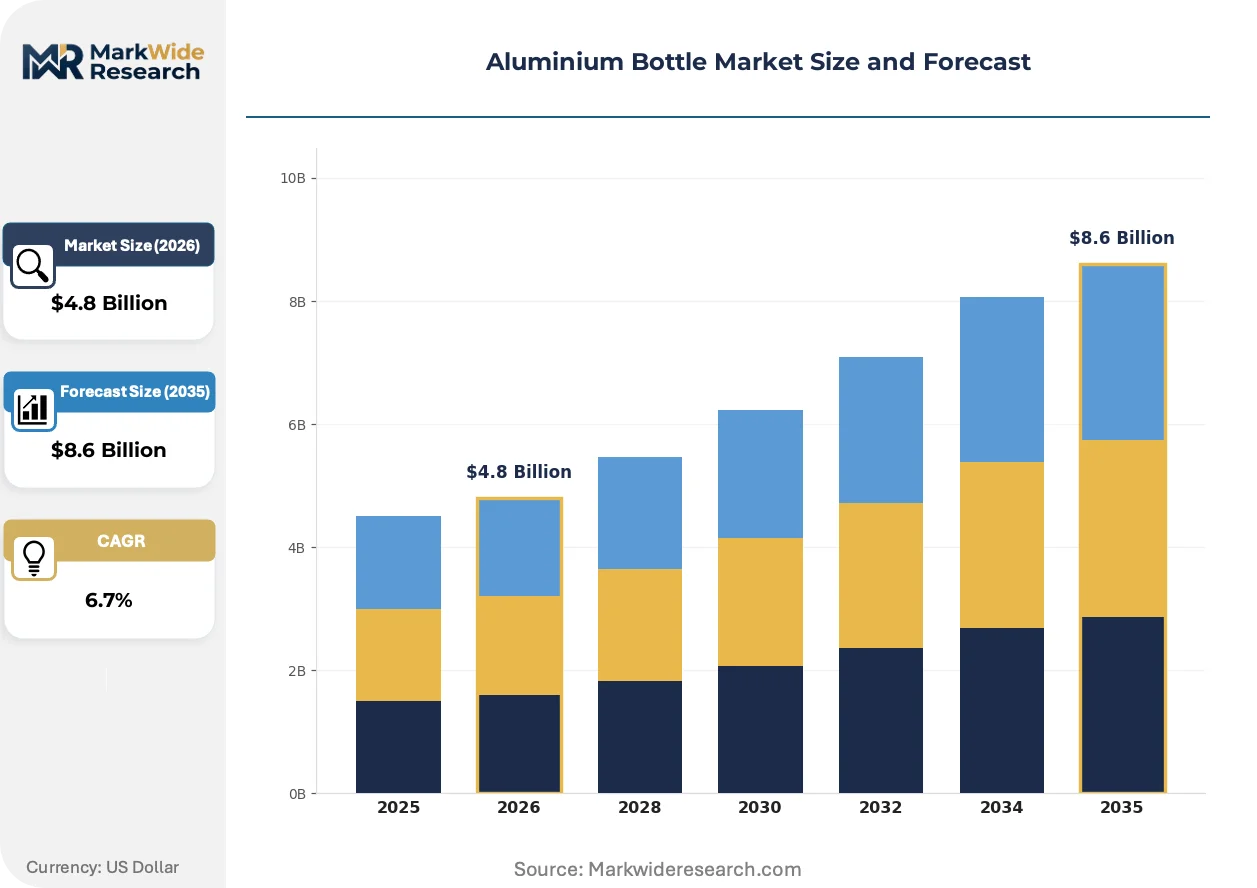
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Cap, Flip Top, Spray, Push-Pull End User: Food and Beverage, Cosmetics, Pharmaceuticals, Household Shape: Round, Square, Customized, Ergonomic Cap Material: Plastic, Metal, Wood, Composite |
| Companies Covered | Ball Corporation, Ardagh Group, Trivium Packaging, Crown Holdings, EXAL Corporation, CCL Container, Envases Group, Tournaire Group, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Bottle Market Strategic Shifts
Inline digital decoration and alloy lightweighting are compressing the capital-intensity gap between aluminium and plastic packaging, while regulatory mandates accelerate substitution timelines beyond pure economic rationality.
High-speed single-pass inkjet printing is collapsing conventional gravure cylinder economics by eliminating plate costs and enabling real-time design changes. Beverage brands in California and Bavaria are piloting variable-data campaigns with 48-hour turnaround from concept to filled bottle. This capability is compressing marketing campaign minimum viable scales from millions to tens of thousands of units.
REACH F-Gas Regulation constraints on hydrofluorocarbon propellants are forcing aerosol manufacturers toward compressed gas and mechanical pump alternatives. Aluminium bottle producers with integrated nitrogen dosing lines capture this transition, while converters dependent on legacy propellant chemistries face stranded asset risk. Personal care brands in the Netherlands and Belgium are fastest to reformulate.
Direct-to-retail procurement models are fragmenting traditional distributor networks as beverage startups bypass wholesale tiers. E-commerce-native brands in urban Germany and the UK are specifying aluminium bottles for unboxing aesthetics and shipping durability. This channel pivot favors converters with sub-10,000 unit flexibility and 72-hour fulfillment windows over legacy high-volume specialists.
Aluminium Bottle Market Segmentation
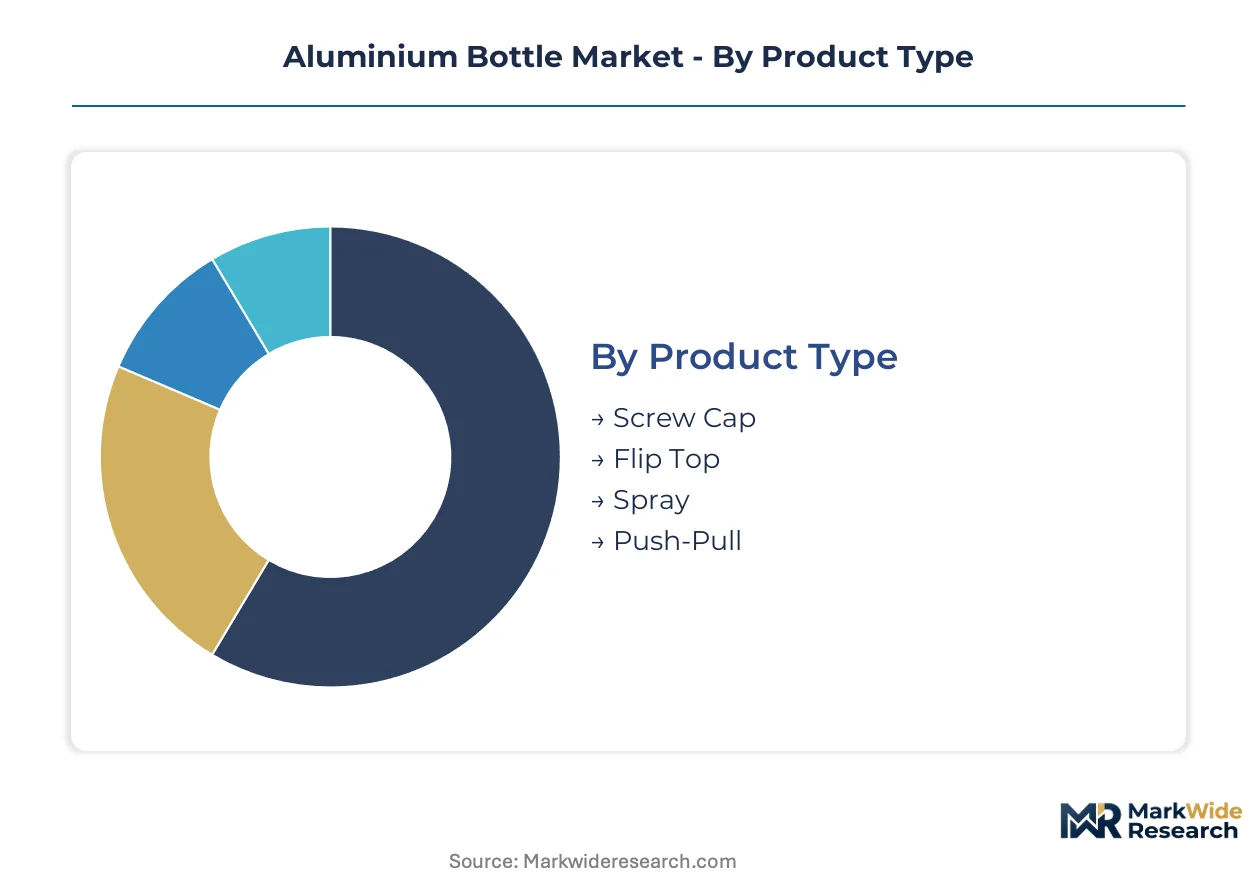
Aluminium bottle segmentation reveals how closure mechanics, end-use chemistry, and consumer ergonomics drive divergent specification requirements across supply chains. Each dimension creates distinct tooling investments and regulatory compliance pathways that shape converter specialization.
Product Type:
Screw Cap configurations dominate beverage filling line compatibility and consumer reseal expectations across retail channels.
- Screw Cap:Threaded aluminium or composite closures mate with standardized neck finishes, enabling high-speed capping at 2,000+ bottles per minute on rotary filling lines. German mineral water brands and North American craft breweries specify this format for deposit-return system compatibility.
- Spray:Aerosol-compatible bottles with bag-on-valve or traditional dip-tube configurations capture share from tinplate in personal care applications. Netherlands-based deodorant and dry shampoo brands are fastest to adopt this transition under REACH F-Gas Regulation constraints.
- Flip Top:Hinged polypropylene closures enable single-handed dispensing for sports nutrition and on-the-go beverage consumption.
- Push-Pull:Silicone valve mechanisms support controlled flow rates for viscous products and child-resistant requirements.
The dominant share belongs to Screw Cap, while Spray is closing the gap fastest on regulatory tailwinds.
End User:
Application chemistry dictates liner specification, pressure rating, and surface treatment protocols across converter facilities.
- Food and Beverage:Carbonated soft drinks, craft beers, and premium waters absorb the majority of aluminium bottle volume. FDA 21 CFR 177.1390 laminate specifications and EU REACH coating constraints govern internal epoxy-phenolic liner qualification timelines.
- Cosmetics:Anodized finishes and digital print personalization command premium unit economics in Swiss skincare and French fragrance markets. Three-to-four times margin multiples versus glass justify dedicated production cells.
- Pharmaceuticals:Child-resistant closures and tamper-evident bands meet FDA packaging requirements for over-the-counter formulations.
- Household:Industrial chemical resistance and trigger-spray compatibility serve cleaning product and automotive fluid applications.
Food and Beverage holds the volume base, though Cosmetics generates the steepest margin expansion trajectory.
Shape:
Form factor selection balances pallet density, shelf presence, and ergonomic handling requirements.
- Round:Cylindrical bodies maximize internal pressure resistance and minimize material stress concentrations. Standard diameters optimize retail shelf facings and secondary packaging cube efficiency.
- Square:Rectangular cross-sections improve pallet utilization and shipping density for e-commerce fulfillment.
- Customized:Brand-specific silhouettes enable trademark protection and unboxing differentiation for direct-to-consumer channels.
- Ergonomic:Contoured waist profiles and textured grip zones target single-handed consumption scenarios.
Round configurations retain manufacturing efficiency leadership, yet Customized shapes are expanding most quickly among digital-native brands.
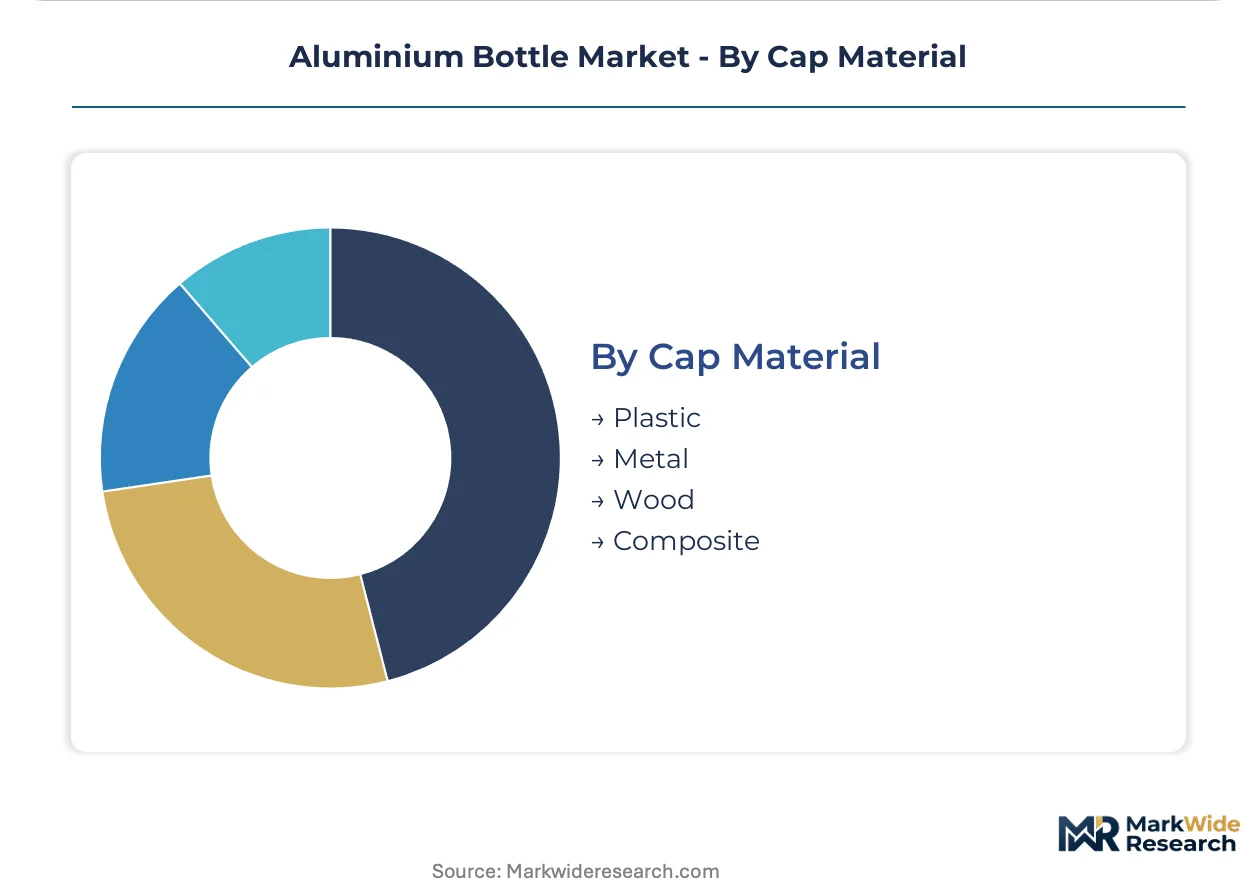
Cap Material:
Closure substrate selection interfaces with recycling stream compatibility and premium positioning strategies.
- Plastic:Polypropylene and polyethylene closures dominate cost-optimized beverage applications with established recycling codes.
- Metal:Aluminium screw caps enable mono-material packaging claims and streamlined sortation in European recycling infrastructure.
- Wood:Cork-composite and hardwood stoppers serve premium spirits and cosmetic oil positioning in French and Italian markets.
- Composite:Multi-layer structures combine torque retention with tactile surface finishes for luxury fragrance applications.
Plastic maintains cost-driven volume leadership, while Metal closures are gaining share fastest on circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across aluminium bottle markets, with European converters supplying premium cosmetic vessels to North American brands while Asian fabricators dominate standard beverage formats. Trade flows concentrate where regulatory pressure on plastics intersects with established metalworking infrastructure.
Germany
Pfand deposit-return systems and refillable mineral water networks sustain the highest reuse-cycle economics for aluminium bottles in Europe. The country's national packaging regulator enforces strict extended producer responsibility quotas that privilege metal over polymer alternatives. Bavarian bottling clusters around Munich and Nuremberg host integrated forming and coating facilities serving premium water brands.
United States
Craft beverage startups and direct-to-consumer cosmetics brands drive import demand for decorated aluminium vessels from European suppliers. FDA 21 CFR 177.1390 laminate specifications govern internal coating approvals, creating compliance barriers for non-domestic producers. California's state-level bottle deposit law and emissions guidelines shape manufacturing location decisions across the Western seaboard.
France
Luxury fragrance houses and skincare formulators specify anodized aluminium with digital print personalization, commanding premium export pricing. ANSM and ECHA REACH constraints on coating chemistries force continuous reformulation of internal liners. Industrial concentration around Grasse and Paris Basin supports dedicated production cells for cosmetic-grade finishing.
China
Domestic beverage brands and aerosol manufacturers absorb the majority of regional aluminium bottle output, with limited premium export penetration. SAMR and GB standards govern food contact metal packaging, while MIIT industrial policy favors capacity consolidation. Yangtze River Delta forming clusters supply standard screw-cap formats for local carbonated drinks.
Netherlands
Personal care aerosol brands lead adoption of bag-on-valve aluminium systems under REACH F-Gas Regulation constraints on hydrofluorocarbon propellants. Rotterdam-Antwerp logistics corridors enable efficient raw material sourcing for converters serving Benelux and German markets. Eindhoven-region fabricators specialize in nitrogen dosing lines for compressed gas alternatives.
Aluminium Bottle Market Competitive Environment
On the supply side, the industry is consolidating around integrated metal-forming specialists with captive aluminium supply and aerospace-derived precision capabilities. Tiered competitive positioning separates high-volume beverage converters from premium cosmetic finishers and regional aerosol specialists. Dominant competitive moves include backward integration into primary aluminium sourcing and strategic partnerships with digital decoration technology providers.
Among North American metal-forming specialists, Ball Corporation and Crown Holdings exemplify scale-driven positioning through beverage can heritage and high-speed necking expertise. Trivium Packaging represents European integrated leadership across aerosol and beverage aluminium forming. These three anchors illustrate how geographic industrial heritage—American aerospace metalworking, European aerosol chemistry integration—shapes divergent capability portfolios without requiring identical strategic postures.
| Leading Market Players |
|---|
| Ball Corporation |
| Ardagh Group |
| Trivium Packaging |
| Crown Holdings |
| EXAL Corporation |
| CCL Container |
| Envases Group |
| Tournaire Group |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
Primary aluminium smelter concentration in China and Russia feeds directly into converter margin structures, with London Metal Exchange volatility transferring downstream to beverage brand procurement costs. This upstream geography locks in raw material exposure that shapes where premium finishing operations can sustain viable economics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate aluminium bottle procurement. Pricing stratifies across premium cosmetic finishing, standard beverage formats, and economy aerosol tiers based on surface treatment complexity and liner certification grade. Cost compression in standard beverage segments is intensifying because lightweighting alloy R&D spreads across higher volumes. Private-label beverage brands exhibit highest price sensitivity, while Swiss skincare houses tolerate premium positioning.
Supply Chain Analysis
Export control regimes on aerospace-grade metalworking equipment limit technology transfer to emerging converter markets. Supply concentrates in Germany, China, and the United States, with deep-draw tooling and ironing process expertise anchoring European competitive advantage. Raw material flows draw from primary aluminium ingot, 3104-H19 alloy sheet, and epoxy-phenolic liner chemistries. Single-source vulnerability around qualified die designers constrains brownfield expansion. Distribution runs through beverage co-packer networks and cosmetic brand direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around FDA 21 CFR 177.1390 and EU REACH compliance creates switching costs that freeze out unqualified competitors.
For Market Incumbents: Harden regulatory certification portfolios by accelerating multi-layer liner qualification timelines before EPA emissions guidelines tighten further. Deepen upstream control over captive aluminium supply through tolling arrangements with primary smelters. Ball Corporation and Trivium Packaging demonstrate how aerospace-derived metalworking heritage compounds this moat against emerging Asian fabricators. For New Entrants and Emerging Players: Pursue white-space in direct-to-retail cosmetic vessels where digital print personalization commands premium economics and minimum order quantities have collapsed. Personal care aerosol applications under REACH F-Gas Regulation constraints offer fastest penetration because legacy tinplate converters face stranded asset risk. Position through 72-hour fulfillment flexibility rather than scale. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with integrated forming-coating-decoration capabilities and established FDA laminate approvals. Long-term viability hinges on refillable bottle system infrastructure that sustains 50+ reuse cycles. Watch German Pfand deposit-return expansion rates as inflection signal for closed-loop revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminium | Tolling arrangements with Chinese and Russian smelters lock in raw material cost visibility against LME volatility. |
| Digital Print Decoration Capability | Single-pass inkjet infrastructure enables lot-size-one production for micro-brand access in California and Bavaria. |
| Multi-Layer Liner Qualification | FDA 21 CFR 177.1390 compliance testing secures barrier performance claims for carbonated beverage shelf life. |
| Refillable Bottle System Partnership | Pfand infrastructure integration in Germany creates closed-loop revenue models absent in single-use markets. |
| Aerosol-Compatible Forming Lines | Bag-on-valve and nitrogen dosing capacity captures personal care transition under REACH F-Gas constraints. |
Study Parameters
Desk research of trade association filings, customs export records, and regulatory compliance databases preceded structured interviews with beverage procurement directors, cosmetic packaging engineers, aluminium converter plant managers, and deposit-return system operators. Primary fieldwork across German bottling clusters, Yangtze River Delta forming facilities, and California craft beverage operations was cross-validated against secondary sources including EPA emissions inventories, ECHA REACH substance registrations, and London Metal Exchange price archives. Bottom-up volume triangulation against top-down macroeconomic drivers ensured segmentation coherence.
Assumptions around EU Single-Use Plastics Directive enforcement timelines and lightweighting alloy adoption curves were held fixed across the projection horizon, while primary aluminium price volatility and coating chemistry migration paths were stress-tested. Segmentation modeling spanned closure mechanism, end-use chemistry, surface finish tier, and regional regulatory cluster dimensions. CAGRs were derived from installed capacity expansion announcements, brand capex disclosures, and substitution elasticity estimates against PET packaging.
Sensitivities concentrate around London Metal Exchange price swing magnitude and FDA liner qualification timeline extensions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and alloy formulation stability. Material shifts in EU extended producer responsibility framework design or bisphenol-A epoxy liner ban acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Packaging Metallization Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Metal Packaging Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Metal Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Europe Metal Packaging Market