
 Asia Pacific Metal Cans Market | 2026-2036
Asia Pacific Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Metal Cans Market Outlook
China's aluminum can sheet rolling expansion is reconfiguring raw material flows across the region. Crown Holdings leverages backward integration into metal substrate supply to sustain margin stability amid volatile aluminum pricing. Ball Corporation anchors its position through high-speed two-piece can lines serving carbonated soft drink bottlers in Thailand and Vietnam. CPMC Holdings Limited competes on coated steel can formats for processed seafood exports, occupying a defensible niche against aluminum-centric rivals.
Asia Pacific metal cans are cylindrical containers fabricated from aluminum or tinplate steel, typically featuring internal epoxy-phenolic coatings to prevent corrosion and maintain shelf stability for oxygen-sensitive contents; they are formed through deep drawing, wall ironing, or three-piece welding processes and serve primarily as hermetic packaging for beverages, processed foods, and aerosol products. Aluminum beverage cans dominate volume due to their lightweight properties and infinite recyclability loop, while steel food cans retain structural importance in retort-ready applications requiring puncture resistance and thermal stability. Paint cans and industrial steel drums represent mature segments with slower growth but durable replacement demand from construction chemical and coatings manufacturers.
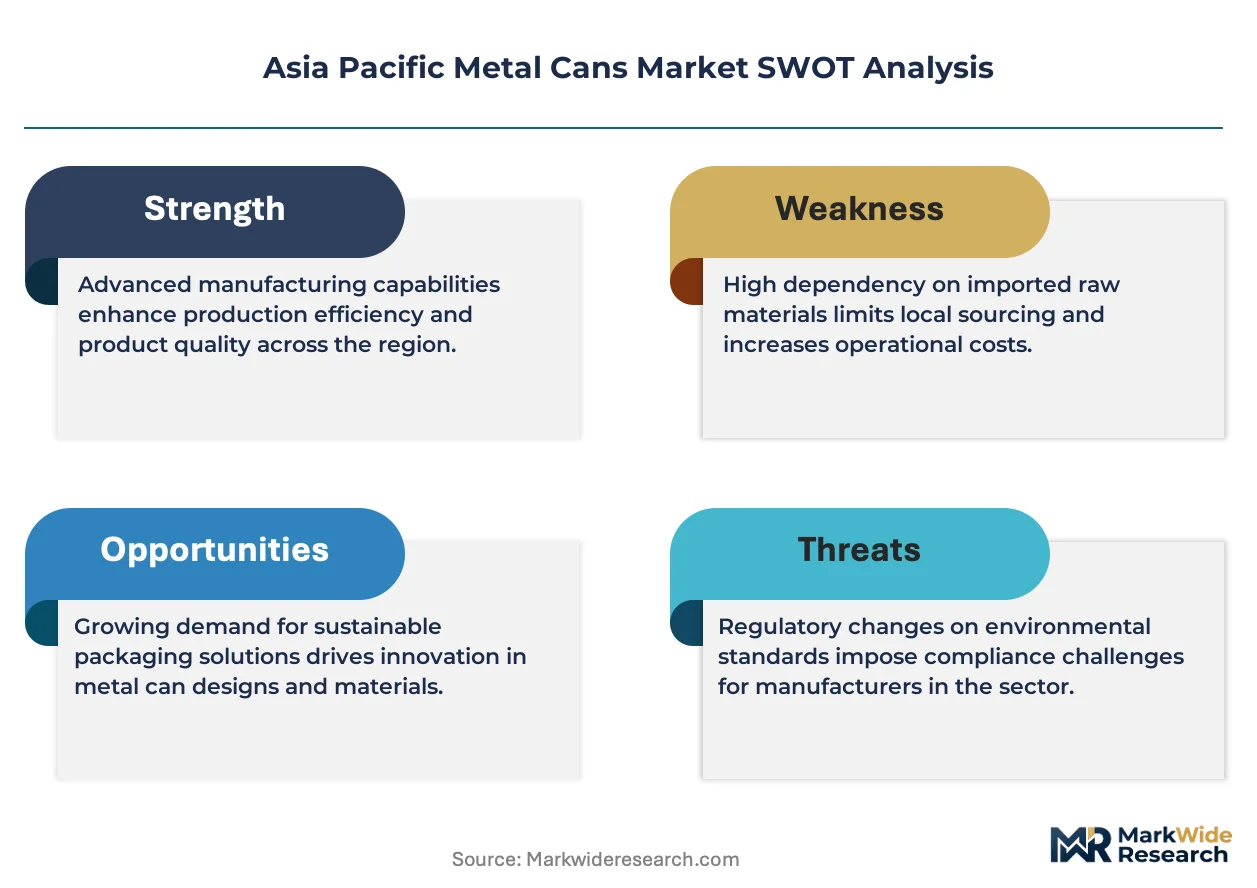
China's SAMR enforces GB 4806 food-contact material standards that mandate specific migration limits for can lining substances, while Japan's METI promotes resource circulation targets that incentivize lightweighting and closed-loop aluminum recovery. India's BIS certification requirements for metal packaging create compliance barriers for imported can stock, shaping local sourcing strategies among multinational filler's procurement teams. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate substitution economics as bioplastics and paper-based barriers test metal's cost-position in select beverage categories.
Market Dynamics
China's aluminum sheet rolling capacity expansion is redrawing raw material procurement maps across Southeast Asia, forcing beverage can manufacturers to renegotiate long-term supply contracts and relocate conversion assets closer to emerging demand clusters in Indonesia and Vietnam.
Growth Catalysts
- Indonesia's can manufacturing buildout:Domestic rolling mills and two-piece can lines are multiplying to serve both local beverage brands and export contracts to Australia and the Middle East.
- Japan's METI circular economy guidelines:Lightweighting mandates and closed-loop aluminum recovery targets are accelerating can-to-can recycling infrastructure investments.
- Epoxy-phenolic lining chemistry:Advances in internal coating formulations are extending shelf life for oxygen-sensitive craft beer and ready-to-drink coffee applications.
Market Restraints
- Aluminum LME price volatility:Input cost swings compress converter margins and complicate annual contract pricing with beverage bottlers.
- China's GB 4806 migration limits:SAMR enforcement of specific substance thresholds for food-contact materials creates compliance friction for imported can stock.
- Bioplastic bottle substitution:Plant-based barrier packaging is testing metal's cost-position in premium still water and functional beverage segments.
Strategic Opportunities
- Vietnam's underpenetrated craft beer segment:Small-batch brewers are converting from glass to aluminum for distribution efficiency and brand differentiation.
- India's BIS localization incentives:Certification requirements for metal packaging create captive demand for domestic can manufacturing joint ventures.
- Aerosol can-to-can recycling:Closed-loop aluminum recovery systems for personal care and household products remain technically and commercially underdeveloped.
Industry Challenges
- Deep-drawing die engineering talent:Southeast Asia lacks sufficient tool-and-die specialists for high-speed two-piece can line maintenance and optimization.
- Retort steel can qualification timelines:Seafood exporters face extended certification cycles for new coated tinplate formulations under evolving food-contact protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Metal Cans Market |
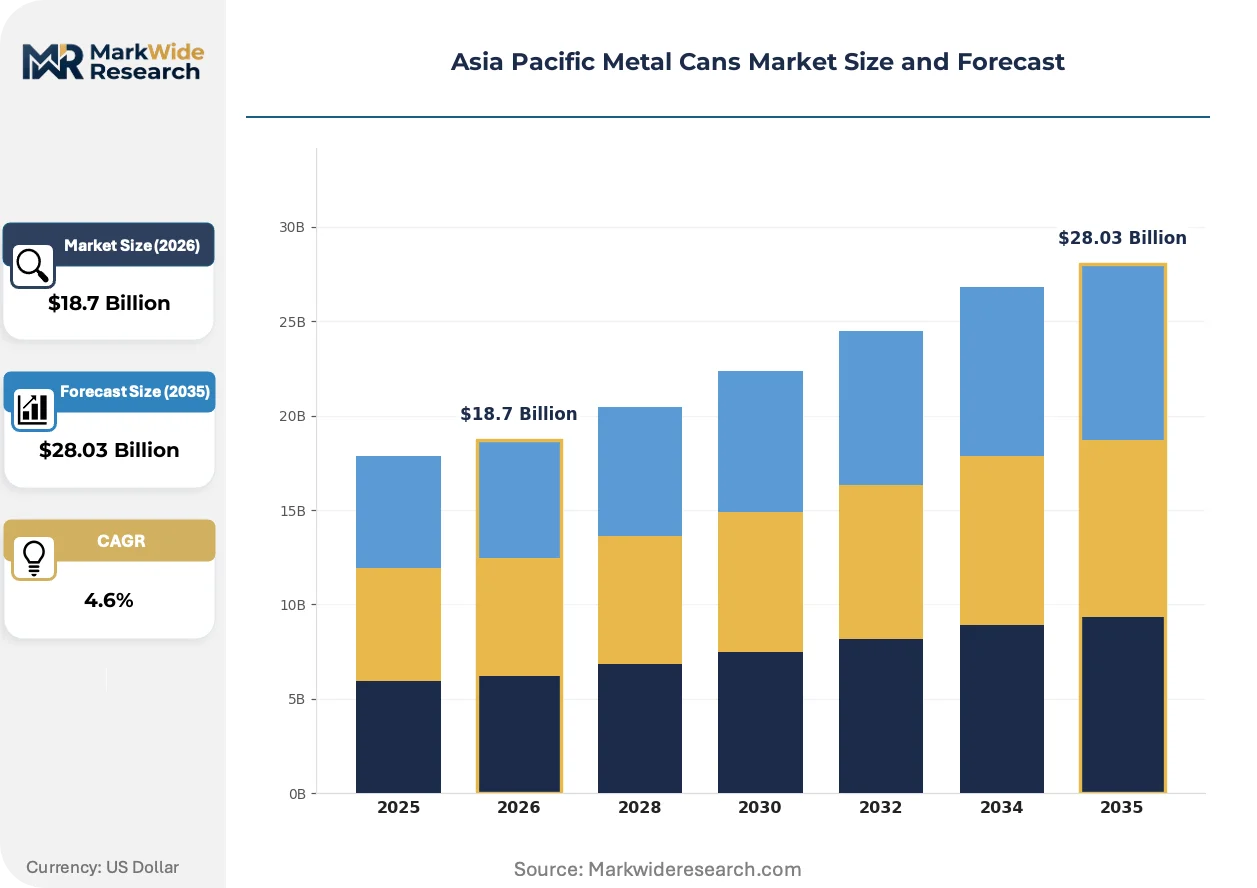
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Paint Cans, Beverage Cans Application: Food Packaging, Beverage Packaging, Personal Care, Industrial Use Capacity: Small Size, Medium Size, Large Size, Extra Large Size End User: Food Manufacturers, Beverage Producers, Retailers, Contract Packers |
| Companies Covered | Silgan Containers, Shanghai Jima Industrial Co Ltd, Ball Corporation, Sunrise Group Co., Ltd., BWAY Corporation, Crown Holdings, CPMC Holdings Limited, ORG Packaging Co. Ltd, Amcor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Metal Cans Market Strategic Shifts
Digital manufacturing systems and regulatory tightening around material traceability are compressing quality assurance cycles and enabling real-time substrate verification across Asia Pacific can production networks.
Smart factory instrumentation is digitizing quality control workflows in aluminum can plants. High-speed vision systems and laser gauging equipment now populate Thai and Vietnamese production floors. This infrastructure is digitizing defect detection from post-production sampling to in-line monitoring, compressing response times from hours to seconds.
China's GB standards for food-contact materials are mandating batch-level migration testing and documentation. SAMR enforcement is pushing converters toward blockchain-anchored supply chain traceability. Processed seafood and infant formula segments are absorbing the highest compliance costs and passing them through dedicated specification premiums.
Direct procurement relationships between beverage brand technical teams and can manufacturers are displacing traditional distributor intermediaries. Thai carbonated soft drink bottlers now negotiate lining chemistry specifications and lightweighting roadmaps directly with converter R&D functions. This channel compression is most visible in Vietnam's expanding ready-to-drink coffee segment.
Asia Pacific Metal Cans Market Segmentation
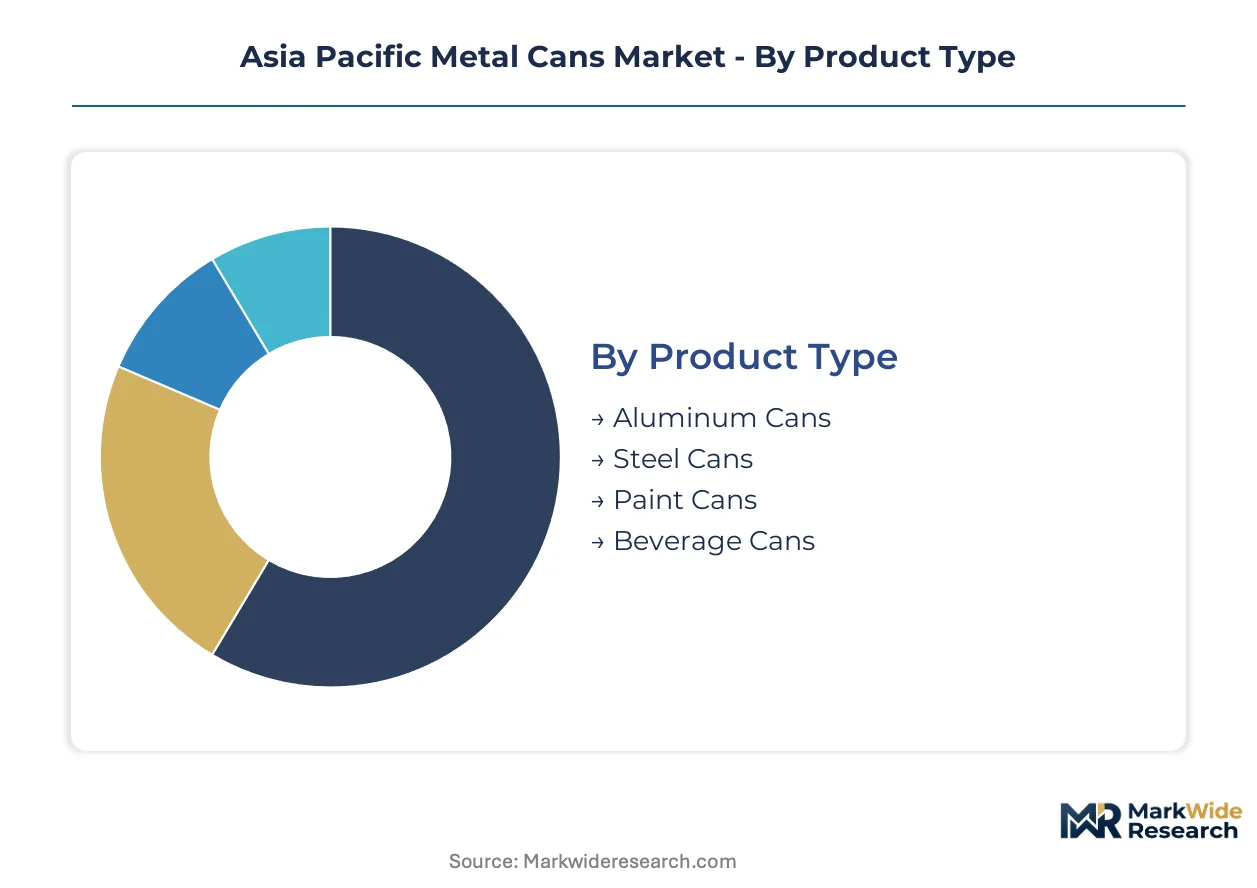
Metal can segmentation in Asia Pacific tracks substrate selection trade-offs between aluminum's recyclability and steel's puncture resistance, while application splits reveal diverging growth vectors across beverage carbonation and retort-ready food preservation. Capacity tiers map directly to channel economics, with smaller formats capturing premium single-serve positioning against bulk industrial containers.
Product Type:
Cost tier differentiation separates lightweight aluminum formats from structural steel alternatives, with specialty coatings commanding specification premiums in oxygen-sensitive applications.
- Aluminum Cans:Two-piece drawn-and-ironed construction delivers infinite recyclability and 60% weight reduction versus steel equivalents. Demand concentrates in Thailand and Vietnam carbonated soft drink bottling, where Crown Holdings and Ball Corporation anchor high-speed production corridors against volatile LME pricing.
- Steel Cans:Three-piece welded tinplate or tin-free steel construction provides puncture resistance and thermal stability for retort processing. Indonesia's processed seafood exporters under BIS-equivalent import protocols drive coated tinplate procurement, with CPMC Holdings occupying the defensible niche against aluminum-centric rivals.
- Paint Cans:Lever-cap and plug-lid cylindrical containers serve construction chemical and coatings manufacturers across China's property development corridors.
- Beverage Cans:Dedicated two-piece aluminum lines with internal epoxy-phenolic linings address oxygen-sensitive craft beer and ready-to-drink coffee segments.
Aluminum Cans command the established base. The steepest expansion runs through Beverage Cans.
Application:
Application splits trace diverging regulatory exposure, with food-contact migration limits tightening faster than industrial chemical containment standards.
- Food Packaging:Retort-ready coated steel preserves shelf-stable proteins and vegetables through high-temperature sterilization cycles. China's SAMR enforces GB 4806 substance migration thresholds that extend qualification timelines for new tinplate formulations serving infant formula and processed seafood exporters.
- Beverage Packaging:Hermetic aluminum containment for carbonated and still beverages leverages lightweighting roadmaps under Japan's METI circular economy guidelines. Vietnam's craft beer conversion from glass to aluminum accelerates demand for small-batch canning lines with rapid changeover capability.
- Personal Care:Aerosol aluminum cans for deodorants and hair sprays face underdeveloped closed-loop recycling infrastructure across Southeast Asia.
- Industrial Use:Steel drums and pails for lubricants, solvents, and construction chemicals serve replacement demand from manufacturing clusters in China's Pearl River Delta.
Food Packaging anchors volume throughput. Beverage Packaging climbs the fastest on lightweighting mandates and channel expansion.
Capacity:
Volume tier segmentation maps to distribution economics, with smaller formats capturing convenience premiums and larger sizes serving institutional procurement.
- Small Size:Sub-250ml aluminum cans target single-serve ready-to-drink coffee and energy drink segments in Japanese convenience retail.
- Medium Size:Standard 330ml and 355ml beverage cans dominate Southeast Asian carbonated soft drink bottling, with Indonesia's domestic manufacturing buildout absorbing regional conversion capacity.
- Large Size:500ml and 1-liter formats serve sharing occasions and value-positioned beer portfolios in Vietnam's emerging craft segment.
- Extra Large Size:Industrial steel drums and bulk paint containers serve construction chemical manufacturers with durable replacement cycles.
Medium Size commands the established base. Small Size gains share fastest on premium single-serve positioning.
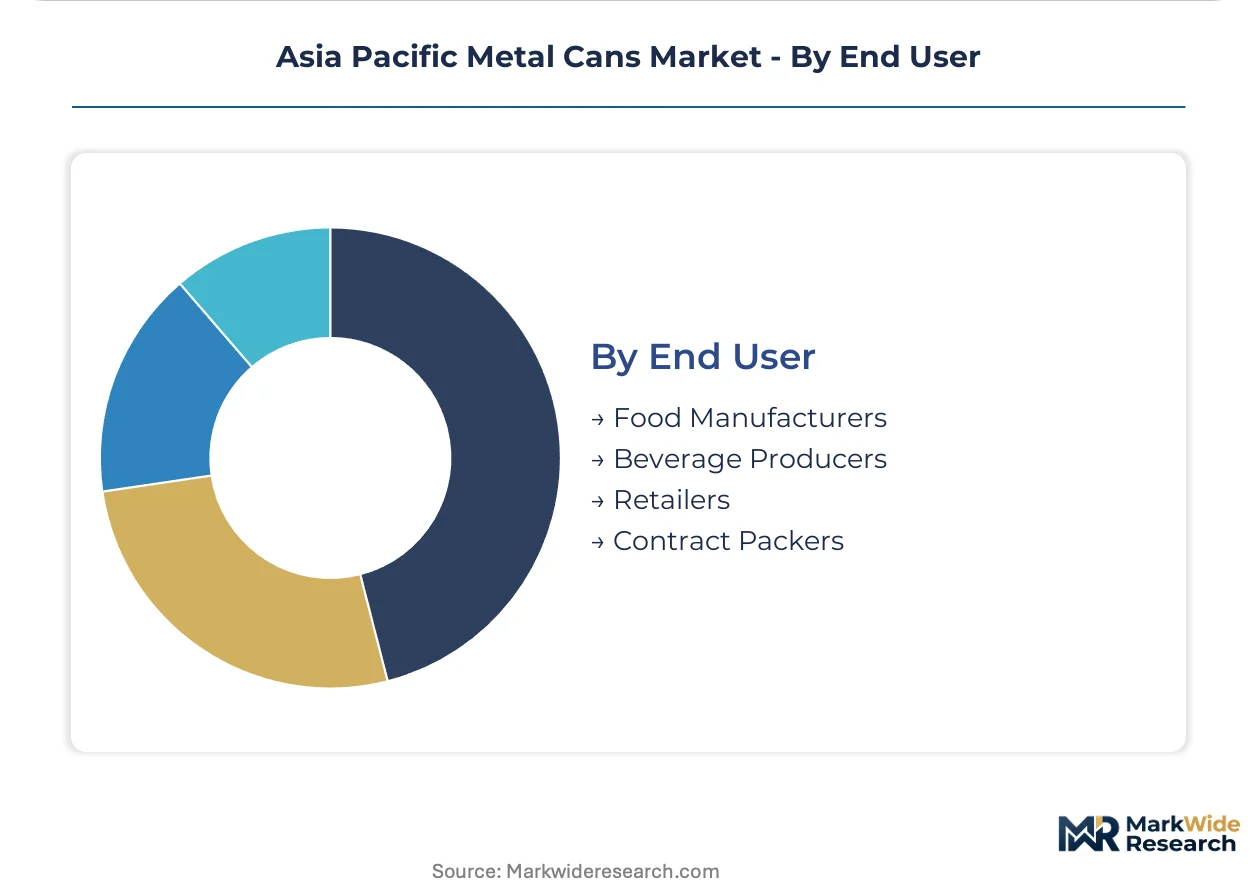
End User:
Customer type segmentation reveals channel compression, with technical procurement teams displacing traditional distributor intermediaries in direct converter negotiations.
- Food Manufacturers:Retort processors and preserved seafood exporters specify coated tinplate formulations under tightening food-contact protocols, with India's BIS certification creating captive demand for localized supply.
- Beverage Producers:Carbonated soft drink and craft beer bottlers negotiate lining chemistry and lightweighting roadmaps directly with converter R&D functions, compressing traditional distributor margins.
- Retailers:Private-label canned goods procurement drives specification standardization across Indonesian and Australian supermarket chains.
- Contract Packers:Third-party canning services for emerging beverage brands absorb small-batch capacity with rapid format changeover requirements.
Food Manufacturers command the established base. Beverage Producers drive the steepest expansion on direct technical engagement and portfolio premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia Pacific metal cans landscape. China deploys aluminum beverage cans for carbonated soft drinks at industrial scale. Japan prioritizes lightweighting mandates and closed-loop aluminum recovery. Southeast Asian markets concentrate demand in food-contact steel for processed seafood exports.
China
Carbonated soft drink bottlers and craft beer producers drive aluminum can procurement volumes. SAMR enforces GB 4806 food-contact material standards with specific migration limits for internal coatings. Shanghai and Guangdong manufacturing clusters host expanding two-piece can line capacity to serve domestic beverage brands.
Japan
Ready-to-drink coffee and premium beverage segments absorb small-format aluminum cans for convenience retail distribution. METI circular economy guidelines mandate lightweighting targets and closed-loop aluminum recovery infrastructure. Kanto and Kansai industrial corridors concentrate can-to-can recycling system investments.
Indonesia
Domestic beverage brands and export contracts to Australia and the Middle East accelerate can manufacturing buildout. National industrial policy supports rolling mill and conversion asset localization. Java-based manufacturing clusters expand two-piece can line capacity to serve regional demand growth.
Vietnam
Craft beer conversion from glass to aluminum packaging drives small-batch canning line demand. Direct procurement relationships between beverage technical teams and converter R&D functions compress traditional distributor channels. Ho Chi Minh City and Hanoi brewing clusters negotiate lining chemistry specifications directly.
India
Processed seafood exporters and infant formula processors specify coated tinplate formulations under tightening food-contact protocols. BIS certification requirements for metal packaging create captive demand for domestic manufacturing joint ventures. Maharashtra and Gujarat industrial zones attract can stock rolling investments.
Asia Pacific Metal Cans Market Competitive Environment
Capability concentration sits with integrated substrate suppliers; scale advantage sits with high-speed conversion specialists. The market structure tiers between backward-integrated aluminum sheet producers and independent can fabricators. Three archetypes dominate: captive substrate converters, independent line operators, and coated steel specialists. Competitive moves center on capacity relocation toward Indonesian demand clusters and direct technical engagement with beverage brand R&D functions.
Among North American-headquartered multinationals, Ball Corporation and Crown Holdings exemplify scale-driven conversion archetypes with regional production footprints. CPMC Holdings Limited occupies a position within the coated steel specialist tier serving food-contact applications. These three anchors represent distinct competitive vectors: aluminum beverage can scale, integrated substrate supply, and defensible steel food can positioning.
| Leading Market Players |
|---|
| Silgan Containers |
| Shanghai Jima Industrial Co Ltd |
| Ball Corporation |
| Sunrise Group Co., Ltd. |
| BWAY Corporation |
| Crown Holdings |
| CPMC Holdings Limited |
| ORG Packaging Co. Ltd |
| Amcor |
| Others |
Value Chain & Pricing Dynamics
China's aluminum sheet rolling capacity expansion concentrates upstream substrate supply, capturing margin pools that downstream converters in Indonesia and Vietnam must negotiate through long-term offtake structures or captive integration investments.
Pricing Analysis
Long-term offtake contracts dominate procurement between beverage bottlers and can manufacturers, insulating volume commitments from LME aluminum spot volatility. Price differentiation rests on volume scale and lining chemistry certification tiers under GB 4806 standards. Pricing pressure intensifies as bioplastic bottle substitution tests metal's cost-position in premium still water. Small-batch craft brewers exhibit highest price sensitivity, while carbonated soft drink multinationals absorb specification premiums for supply security.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian conversion markets dominates supply chain risk calculus for imported can stock. Raw material flows draw from Chinese rolling mills, Indonesian bauxite processing, and Australian alumina refineries. Distribution runs through direct technical procurement relationships displacing traditional distributor intermediaries. Single-source vulnerability concentrates in epoxy-phenolic coating chemical supply, with Japanese and Korean specialty chemical producers anchoring regional formulation availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific metal cans fragmentation creates niche opportunities as craft beverage proliferation and food-contact regulatory divergence splinter demand into specification-intensive segments requiring specialized converter capabilities.
For Market Incumbents: Entrench position through backward integration into aluminum substrate supply and high-speed two-piece line capacity additions in Indonesia. Bioplastic substitution threats in premium beverage segments demand accelerated lightweighting roadmaps under METI guidelines. Channel control through direct R&D engagement with beverage technical teams protects margin pools against distributor compression. For New Entrants and Emerging Players: Vietnam's craft beer conversion from glass packaging offers underpenetrated demand for small-batch canning lines with rapid changeover capability. India's BIS certification barriers create captive white space for domestic manufacturing joint ventures serving processed seafood exporters. Aerosol can-to-can recycling infrastructure gaps present technical service entry angles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum conversion specialists lacking substrate integration. Five-to-ten year viability hinges on regulatory compliance infrastructure and geographic proximity to Indonesian demand clusters. Watch for GB 4806 enforcement intensity as inflection indicator for specification-premium capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate | Crown Holdings' captive sheet supply insulates margins against LME volatility in Thai bottling corridors. |
| Small-Batch Canning Line Deployment | Vietnam craft brewers convert from glass to aluminum through rapid-changeover equipment investments. |
| GB 4806 Compliance Infrastructure | SAMR enforcement drives blockchain-anchored traceability for infant formula can specifications. |
| Indonesian Manufacturing Buildout | Domestic rolling mills capture export contract flows to Australian and Middle Eastern beverage markets. |
| Closed-Loop Aluminum Recovery Systems | METI circular economy guidelines accelerate can-to-can recycling infrastructure in Kanto industrial corridors. |
Study Parameters
Two parallel data streams informed the analysis: executive interviews with beverage procurement directors, can converter plant managers, and epoxy-phenolic coating technical specialists; and secondary validation through customs trade records, SAMR food-contact material filings, and METI resource circulation policy documents. Bottom-up capacity assessments across Indonesian and Vietnamese manufacturing clusters triangulated against top-down aluminum consumption forecasts.
Forecast inputs incorporated substrate selection trade-offs, application splits across retort-ready food and carbonated beverage segments, and capacity tier dynamics by format size. Modeled dimensions span aluminum versus steel substrate, food-contact versus beverage application, and small versus medium format positioning. CAGRs derived from volume trajectory analysis across the projection horizon, with specific weighting for Indonesia's domestic manufacturing buildout and Vietnam's craft beer conversion rates.
Practitioners should monitor LME aluminum price volatility, GB 4806 enforcement intensity, and bioplastic packaging cost parity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Global Laminated Steel for Cans Market