
 Global Laboratory Plasticware Market | 2026-2036
Global Laboratory Plasticware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Plasticware Market Intelligence
Asset-light manufacturing models, which reduce upfront capital expenditure on specialized molding equipment, is fragmenting the competitive landscape for commodity plasticware. Thermo Fisher Scientific leverages its extensive global distribution network and broad portfolio to counter this trend. Eppendorf AG differentiates through precision-engineered consumables for automated liquid handling systems. Corning Incorporated sustains its premium position through proprietary material science innovations, particularly in advanced cell culture products.
Laboratory plasticware encompasses a range of disposable and reusable items engineered for scientific experiments and analysis. These products are manufactured from medical-grade polymers like polypropylene or polystyrene via precision injection molding to ensure sterility, non-leaching properties, and chemical inertness. Pipette tips and microcentrifuge tubes represent the largest volume segments, driven by their high-throughput use in automated workflows. Polypropylene is the leading material due to its autoclavability and chemical resistance, while demand for specialty polycarbonates is rising in cryogenic storage applications.
Regulatory compliance is a critical market barrier, with manufacturers adhering to material and safety standards set by the US FDA and Europe's EMA. Conformance to international standards like ISO 13485 for quality management systems is essential for gaining access to clinical and pharmaceutical end-user segments. The ability to validate and document freedom from leachables and extractables will increasingly dictate supplier selection for sensitive applications.
Market Dynamics
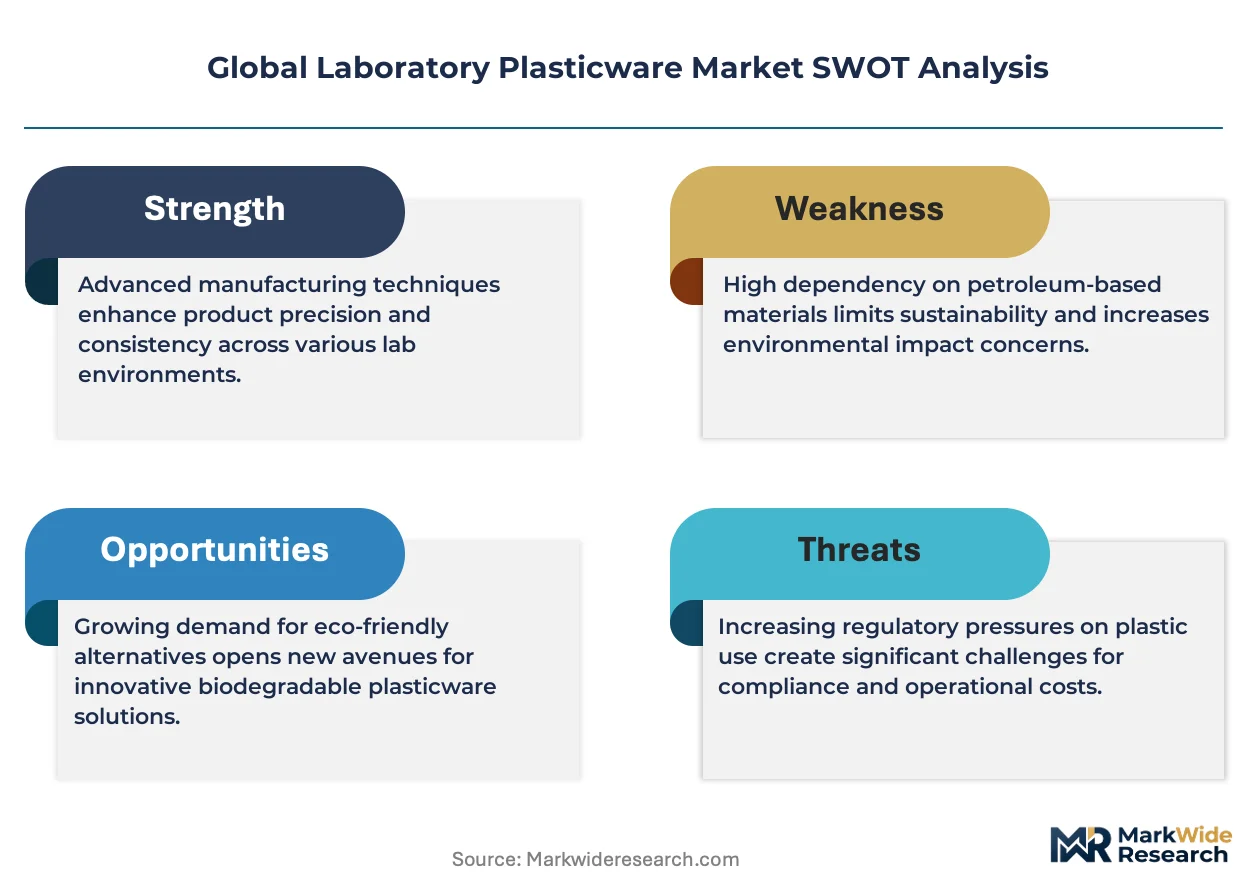
The central tension in the laboratory plasticware market is the growing requirement for validated, contaminant-free materials in regulated applications. This demand for documented purity, particularly regarding leachables and extractables, creates a performance and cost divide between commodity and specialized products.
Growth Catalysts
- Single-Use Systems:The adoption of disposable bioreactors and fluid-handling assemblies in pharmaceutical bioprocessing reduces cleaning validation burdens and cross-contamination risks, driving consumption of sterile, single-use plastic components.
- Cell and Gene Therapy:Research expansion in the United States and Europe for cell and gene therapies requires a high volume of specialized plasticware, including cell culture flasks, plates, and cryogenic vials designed for sensitive biologics.
- Diagnostic Automation:The global scale-up of molecular diagnostics, guided by WHO recommendations for infectious disease testing, accelerates demand for high-throughput plastic consumables like PCR plates and automated pipette tips.
Market Restraints
- Polymer Price Volatility:Unpredictable pricing for key raw materials like medical-grade polypropylene and polystyrene, tied to petrochemical market fluctuations, directly impacts manufacturing costs and compresses supplier margins.
- Microfluidics Substitution:Lab-on-a-chip devices and microfluidic systems, which integrate multiple processes onto a single chip, threaten to displace discrete plastic consumables like microplates and tubes in certain high-value analytical workflows.
- Regulatory Validation Costs:The extensive testing and documentation required to meet standards from the FDA and EMA for new materials, particularly for leachable and extractable profiles, creates a significant financial and time barrier to market entry.
Strategic Opportunities
- Cryogenic Storage Solutions:There is a developing need for plasticware engineered from specialty polycarbonates and other polymers that maintain integrity and prevent sample degradation at ultra-low temperatures for biobanking and cell therapy logistics.
- Emerging R&D Hubs:Pharmaceutical and biotechnology sectors in India and South Korea are expanding, presenting an opportunity for suppliers of ISO 13485-compliant labware to establish a foothold in these growing research ecosystems.
- Integrated Sample Tracking:Incorporating RFID tags or 2D barcodes directly onto tubes, plates, and vials during manufacturing enables seamless integration with laboratory information management systems (LIMS) for automated tracking.
Industry Challenges
- Sterilization Capacity:Limited global capacity for ethylene oxide (EtO) and E-beam sterilization services creates significant bottlenecks, delaying the market release of pre-sterilized plasticware and impacting supply chain reliability for end-users.
- Multi-Standard Compliance Burden:Manufacturers face operational complexity in maintaining certifications and documentation across different quality systems, including ISO 13485 for medical devices and specific cGMP requirements for pharmaceutical clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Plasticware Market |
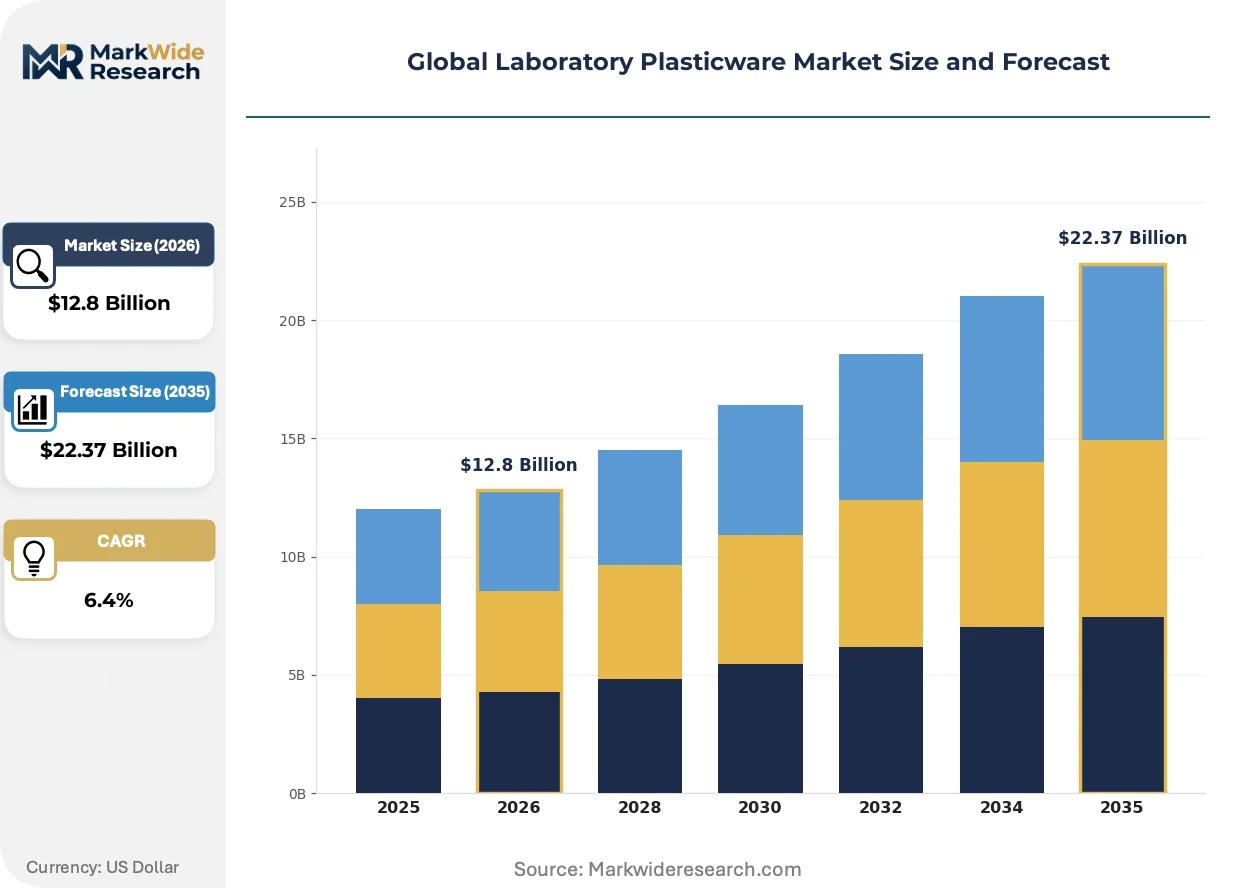
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petri Dishes, Pipette Tips, Microcentrifuge Tubes, Cryogenic Vials, Sample Containers Material: Polypropylene, Polystyrene, Polyethylene, Polycarbonate, Polymethyl Methacrylate Application: Clinical Diagnostics, Drug Discovery, Food Safety Testing, Environmental Analysis, Forensic Science End User: Academic Research Labs, Government Research Institutes, Pharmaceutical Manufacturers, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Eppendorf AG, Sartorius AG, DWK Life Sciences, Duran Group, Gerresheimer, Bellco Glass, BrandTech Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Plasticware Market Strategic Shifts & Innovations
The market is bifurcating between high-volume, price-sensitive consumables and high-performance, application-specific products. This split is driven by the parallel needs for cost efficiency in routine testing and absolute purity in advanced biological research and diagnostics.
Advanced surface modification is a key area of material science innovation for laboratory plasticware. Pharmaceutical and academic researchers are adopting these products for sensitive assays like proteomics and next-generation sequencing. The market for high-value applications is migrating from standard, untreated polypropylene to specialized polymers with ultra-low retention or specific binding properties, which improves assay accuracy and conserves precious reagents.
Europe's In Vitro Diagnostic Regulation (IVDR) imposes stricter requirements on products used in diagnostic testing. This regulation elevates many previously self-declared plastic consumables to a higher risk class, demanding more rigorous performance data and quality management. Manufacturers of items like pipette tips and microplates used in IVD kits must now provide extensive technical documentation to their customers, impacting product development timelines.
A shift toward consolidated purchasing models is altering distribution channels for high-volume consumables. Large hospital systems and contract research organizations (CROs) are implementing vendor-managed inventory programs to streamline supply and reduce carrying costs. This trend favors suppliers with sophisticated logistics capabilities and disrupts the traditional role of smaller, regional distributors, particularly in the North American market.
Global Laboratory Plasticware Market Segmentation
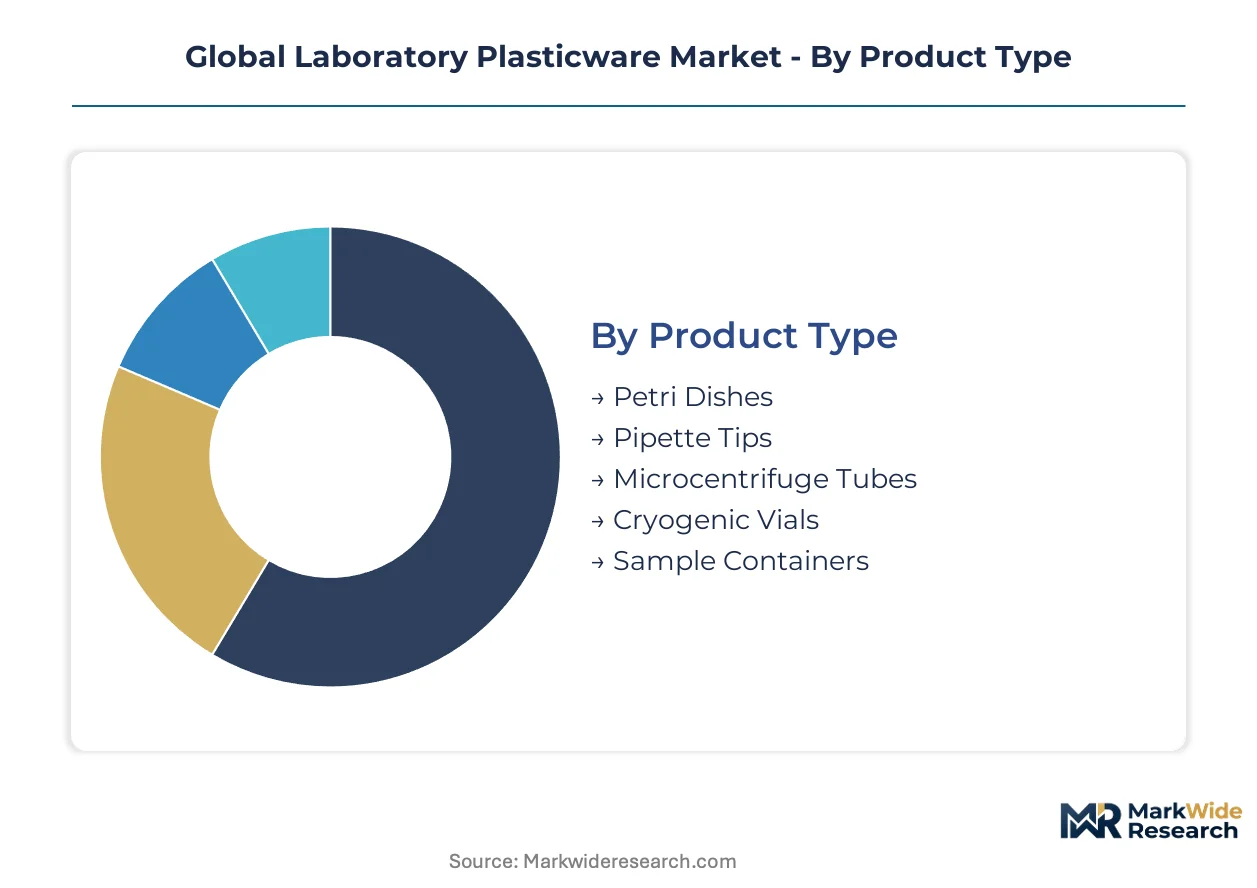
The market for laboratory plasticware navigates the performance and cost divide between commodity and specialized products, directly influencing supplier strategies. Understanding the distinct requirements of each market segment enables manufacturers to align product development with specific end-user needs and regulatory mandates.
Product Type:
The intensity of after-sales support and validation services varies considerably across different laboratory plasticware product types, impacting customer procurement decisions.
- Petri Dishes:Shallow, cylindrical dishes primarily from polystyrene, used for microbial culture and cell growth in academic settings.
- Pipette Tips:Precision-molded components for accurate liquid transfer, often with low-retention surfaces. Demand for these consumables concentrates in high-throughput automated workflows across pharmaceutical research and diagnostic labs in the United States.
- Microcentrifuge Tubes:Small, conical plastic tubes used for sample centrifugation and storage, typically made from polypropylene. Their high-volume use in molecular biology and biochemical assays drives consumption in academic research institutions and biotechnology firms.
- Cryogenic Vials:Specialized tubes designed for ultra-low temperature storage of biological samples, often from polycarbonate, ensuring sample integrity.
- Sample Containers:General-purpose vessels for collecting, storing, and transporting various laboratory specimens, requiring chemical inertness.
By volume, Pipette Tips lead the market. By growth pace, Cryogenic Vials are ahead.
Material:
Material selection directly influences the cost structure of laboratory plasticware, reflecting both raw polymer prices and specialized manufacturing processes required for compliance.
- Polypropylene:A versatile thermoplastic polymer widely used for its autoclavability, chemical resistance, and non-leaching properties. Its consumption concentrates in general labware and high-volume disposables for pharmaceutical manufacturing.
- Polystyrene:A rigid, transparent polymer used for disposable items like petri dishes and cell culture plates in educational and routine laboratory settings.
- Polyethylene:Employed in various forms for bottles, wash bottles, and low-cost containers due to its flexibility and chemical resistance.
- Polycarbonate:An engineering thermoplastic valued for its transparency, impact resistance, and ability to withstand extreme temperatures. Demand for polycarbonate is rising in specialized cryogenic storage applications and biobanking solutions.
- Polymethyl Methacrylate:A transparent, rigid polymer often utilized for optical applications and microfluidic devices due to its clarity and machinability.
The market shows a strong preference for Polypropylene due to its broad utility and chemical inertness across diverse applications.
Application:
Regulatory stringency and validation requirements vary significantly across different laboratory plasticware applications, influencing product design and material selection for end-users.
- Clinical Diagnostics:Utilizes plasticware for sample collection, preparation, and analysis in medical testing, including molecular diagnostics. This application drives substantial demand for sterile, high-throughput consumables like PCR plates and automated pipette tips, particularly in Europe.
- Drug Discovery:Employs specialized plasticware in pharmaceutical research for screening, cell culture, and assay development. Consumption is concentrated in biopharmaceutical companies and contract research organizations in the United States, driven by single-use system adoption.
- Food Safety Testing:Requires plasticware for sample preparation and analysis to detect contaminants and pathogens in food products, adhering to strict purity standards.
- Environmental Analysis:Uses labware for collecting and processing environmental samples to monitor pollutants and assess ecosystem health with consistent results.
- Forensic Science:Employs sterile and traceable plasticware for evidence analysis in criminal investigations, demanding stringent contamination control.
The growth in Clinical Diagnostics is largely attributable to global initiatives for infectious disease testing and diagnostic automation.
End User:
Procurement patterns and volume requirements differ substantially among various end-user segments, shaping distribution strategies for laboratory plasticware suppliers.
- Academic Research Labs:Consume a broad range of general and specialized plasticware for fundamental scientific investigations and educational purposes, often with budget constraints.
- Government Research Institutes:Purchase laboratory plasticware for publicly funded scientific projects, including health, environmental, and defense research, requiring adherence to national standards.
- Pharmaceutical Manufacturers:Require large volumes of sterile, compliant plasticware for drug discovery, development, and bioprocessing. Their demand is concentrated in regions with extensive R&D infrastructure, such as the United States and Europe, driven by single-use system adoption.
- Biotechnology Firms:Utilize specialized plasticware for cell and gene therapy research, biologics production, and diagnostics development. These firms, particularly in emerging R&D hubs like South Korea, demand high-purity consumables for sensitive applications.
The increasing complexity of biopharmaceutical applications drives demand for high-performance plasticware from Pharmaceutical Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and biotechnology firms represent the core buyer archetypes driving demand for laboratory plasticware globally. These specialized end-users concentrate their procurement in regions with advanced R&D infrastructure. Consequently, specific countries lead the consumption of high-purity consumables for sensitive applications.
United States
Demand for single-use systems in drug discovery applications propels the United States market. The US FDA's stringent guidelines on material purity ensure high-quality product adoption. Extensive biotechnology research infrastructure in Boston and San Francisco drives significant consumption of specialized labware.
Germany
German biopharmaceutical companies require advanced plasticware for vaccine development and biologics manufacturing. EMA regulations mandate rigorous testing for leachables and extractables in medical devices. The Munich biotech cluster fosters innovation in precision-engineered consumables for automated workflows.
India
India's expanding pharmaceutical sector, supported by the PLI scheme, increases demand for sterile plasticware in drug formulation. BIS standards ensure product quality for domestic and export-oriented manufacturing. Research institutions in Hyderabad and Bengaluru are expanding their use of high-throughput consumables.
South Korea
South Korean biotechnology firms, particularly in cell and gene therapy, require specialized cryogenic storage solutions. The MFDS enforces strict compliance for in vitro diagnostic products, impacting plasticware selection. The Seoul metropolitan area's biotech parks are centers for advanced diagnostics development.
France
French academic research labs and pharmaceutical companies utilize sterile plasticware for advanced biological assays. ANSM guidelines influence the procurement of certified laboratory consumables. The Paris-Saclay innovation cluster focuses on developing new materials for sensitive scientific experiments.
Global Laboratory Plasticware Market Key Industry Players
Channel-controlling players compete with product-specialist players across the laboratory plasticware market. The landscape shows fragmentation for commodity items, while specialized segments exhibit consolidation around differentiated offerings. Strategic archetypes include broad portfolio providers, precision engineering specialists, and material science innovators. Dominant competitive moves involve portfolio diversification and targeted M&A to secure niche capabilities.
Broad portfolio providers, such as Thermo Fisher Scientific, exemplify a strategy of extensive global distribution and diverse product lines, leveraging scale across multiple laboratory needs. Eppendorf AG occupies a position as a precision engineering specialist, differentiating its offerings through consumables optimized for automated liquid handling systems. Corning Incorporated sits within the material science innovator archetype, sustaining its premium status through proprietary material science innovations, particularly in advanced cell culture products, addressing sensitive application requirements. These companies anchor different segments of the market, from high-throughput general labware to highly specialized research consumables.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Eppendorf AG |
| Sartorius AG |
| DWK Life Sciences |
| Duran Group |
| Gerresheimer |
| Bellco Glass |
| BrandTech Scientific |
| Others |
Cost & Logistics Intelligence
Suez Canal shipping lanes' cost dynamics directly influence petrochemical feedstock prices, impacting the concentrated supply of medical-grade polymers and subsequent price differentiation for specialized labware. This global logistical sensitivity translates into manufacturing cost volatility for laboratory plasticware producers.
Pricing Analysis
Cost-plus contracts, often indexed to petrochemical feedstock prices, govern long-term supply agreements for medical-grade polymers. Material purity, regulatory compliance with FDA and EMA guidelines, and after-sales validation services differentiate specialized products. Commodity plasticware experiences downward pricing pressure from asset-light manufacturing models and market fragmentation. Academic research labs are highly price-sensitive for general consumables, while pharmaceutical manufacturers prioritize performance over cost for validated single-use systems.
Supply Chain Analysis
Ethylene oxide sterilization capacity bottlenecks create a significant supply chain risk, delaying market release of pre-sterilized labware. Production of medical-grade polymers concentrates in regions with established petrochemical industries. The supply chain relies on consistent access to high-purity polypropylene and specialty polycarbonates. Consolidated purchasing models and vendor-managed inventory programs streamline distribution for high-volume consumables, favoring suppliers with sophisticated logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory plasticware market is experiencing a buyer-power shift, driven by consolidated purchasing models from large hospital systems. This trend centralizes procurement decisions and demands greater logistical sophistication from suppliers.
For Market Incumbents:
Insulate core product lines from microfluidics substitution by investing in advanced surface modification technologies. Deepen vertical integration into specialized polymer compounding to control material purity and reduce reliance on volatile raw material markets. Leverage global distribution networks to counter fragmentation in commodity segments. Prioritize ISO 13485 certification for access to clinical and pharmaceutical end-user segments.
For New Entrants and Emerging Players:
Establish a beachhead in specialized cryogenic storage solutions, leveraging advanced polymer engineering. Target emerging R&D hubs like South Korea, focusing on cell and gene therapy applications with MFDS-compliant products. Differentiate through integrated sample tracking solutions (RFID/2D barcodes) for automated laboratory information management systems.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized material science innovators capable of addressing stringent regulatory requirements. Long-term viability depends on continued investment in advanced cell culture products and high-purity consumables for biologics. Target acquisition candidates include precision engineering specialists in automated liquid handling systems or firms with proprietary surface modification technologies. The signal to watch is an acceleration of M&A activity among sterilization service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in EtO Sterilization | Addresses critical supply chain bottlenecks and ensures product availability for end-users. |
| Investment in Advanced Surface Modification | Improves assay accuracy and conserves precious reagents for sensitive applications. |
| Partnership with LIMS Providers | Enables seamless integration of automated sample tracking for enhanced laboratory efficiency. |
| Geographic Expansion into India and South Korea | Captures demand from expanding pharmaceutical and biotechnology sectors in key regions. |
| Development of Specialty Cryogenic Polymers | Prevents sample degradation at ultra-low temperatures for biobanking logistics and cell therapy. |
Research Approach
Cross-validation between primary interviews with drug discovery executives and secondary analysis of FDA/EMA guidelines anchors the qualitative findings. This approach integrates insights from regulatory affairs specialists and lab managers with data from company annual reports and petrochemical market analyses. A rigorous bottom-up and top-down triangulation process ensured data consistency across various data points.
The forecast framework calibration integrates historical data with projected market dynamics across the analysis window. Segmentation dimensions modeled include product type, material, application, end-user, and regulatory compliance tier. Compound annual growth rates were derived from a synthesis of historical trends and anticipated industry shifts. Raw material price volatility indices and global biopharmaceutical R&D spending served as key forecast inputs.
Stress conditions across petrochemical market stability and sterilization capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. The forecasts reflect documented assumptions regarding regulatory stability and biopharmaceutical innovation. Geopolitical disruptions impacting petrochemical supply or unforeseen sterilization technology advancements could revise these projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Global Graduated Cylinder Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market