
 Electrophoresis Transilluminator Market | 2026-2036
Electrophoresis Transilluminator Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophoresis Transilluminator Market Foresight
LED excitation technology is reshaping the electrophoresis transilluminator landscape by displacing mercury-vapor UV sources with solid-state arrays that reduce sample photodamage and eliminate hazardous waste streams. Thermo Fisher Scientific leverages its fluorescence detection portfolio to dominate high-throughput sequencing workflows. Bio-Rad Laboratories anchors its position through backward integration into gel chemistry consumables that lock in instrument placement. Danaher Corporation competes via its Life Sciences platform, which extends service contracts across multiple instrument generations.
An electrophoresis transilluminator is an optical visualization device that emits specific wavelengths—typically 302 nm UV, 470 nm blue light, or narrow-band LED spectra—to excite fluorescent dyes bound to nucleic acids or proteins separated within agarose or polyacrylamide matrices. Its primary purpose is to enable real-time or captured documentation of band patterns for quantification, cloning verification, and downstream analytical decisions. LED transilluminators command expanding share in academic settings where operator safety protocols restrict UV exposure, while gel imaging systems with software integration capture the highest margin pools by bundling analysis algorithms with hardware. Blue light transilluminators occupy a growing niche in preparative DNA recovery workflows where damage-free excision improves cloning efficiency.
The FDA regulates these devices as laboratory equipment under 21 CFR Part 892 if used in diagnostic contexts, while OSHA standards govern UV radiation exposure in research environments. ISO 13485 certification shapes supplier qualification for clinical laboratories, and the EU MDR extends conformity requirements to transilluminators integrated into IVD workflows. Stakeholders must monitor how software integration features trigger medical device classification thresholds in major jurisdictions, as this determines regulatory burden and market access timelines.
Market Dynamics
LED excitation arrays are compressing replacement cycles for mercury-vapor UV transilluminators across academic core facilities, while optical safety enclosures face redesign mandates from FDA guidance updates that expand medical device classification scrutiny for integrated gel documentation systems.
Growth Catalysts
- EPA hazardous waste rules:Mercury-containing lamp disposal restrictions in the United States accelerate LED adoption in university environmental health and safety protocols.
- Max Planck Institute standardization:German research consortia consolidate procurement around integrated gel documentation platforms with embedded analysis software.
- Blue light excitation:Preparative DNA recovery workflows in cloning laboratories drive demand for damage-free band excision capabilities.
Market Restraints
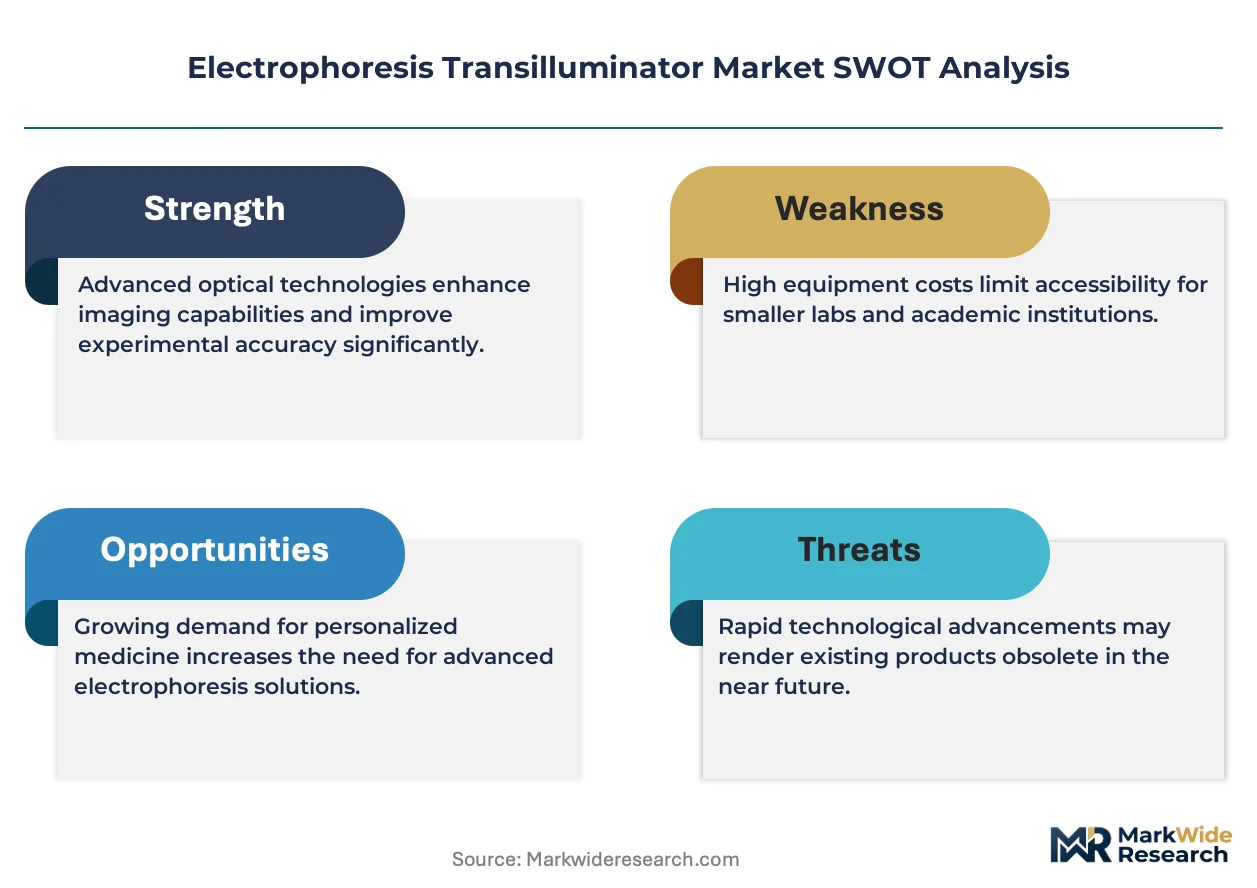
- Optical component supply:Narrow-bandpass filter fabrication concentrates among German and Japanese specialty glass manufacturers, creating single-source vulnerability.
- ISO 13485 certification costs:Clinical laboratory qualification requirements impose capital barriers for mid-tier instrument vendors seeking IVD-adjacent placement.
- UV exposure liability:OSHA workplace radiation standards elevate insurance and training burdens for facilities retaining legacy mercury systems.
Strategic Opportunities
- EU MDR convergence:Transilluminators bundled with diagnostic software face expanded conformity assessment pathways, favoring vendors with established notified body relationships.
- Cloud-connected documentation:Remote image storage and collaborative analysis platforms penetrate distributed research networks in the United States and Germany.
- CRISPR quality control:Gene editing verification workflows create specialized demand for high-sensitivity fluorescence detection in synthetic biology startups.
Industry Challenges
- Optical engineering talent:Shortage of fluorescence spectroscopy specialists constrains R&D velocity for solid-state excitation system optimization.
- Legacy system integration:Software interoperability gaps between new LED units and existing gel analysis databases complicate upgrade decisions at established laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophoresis Transilluminator Market |
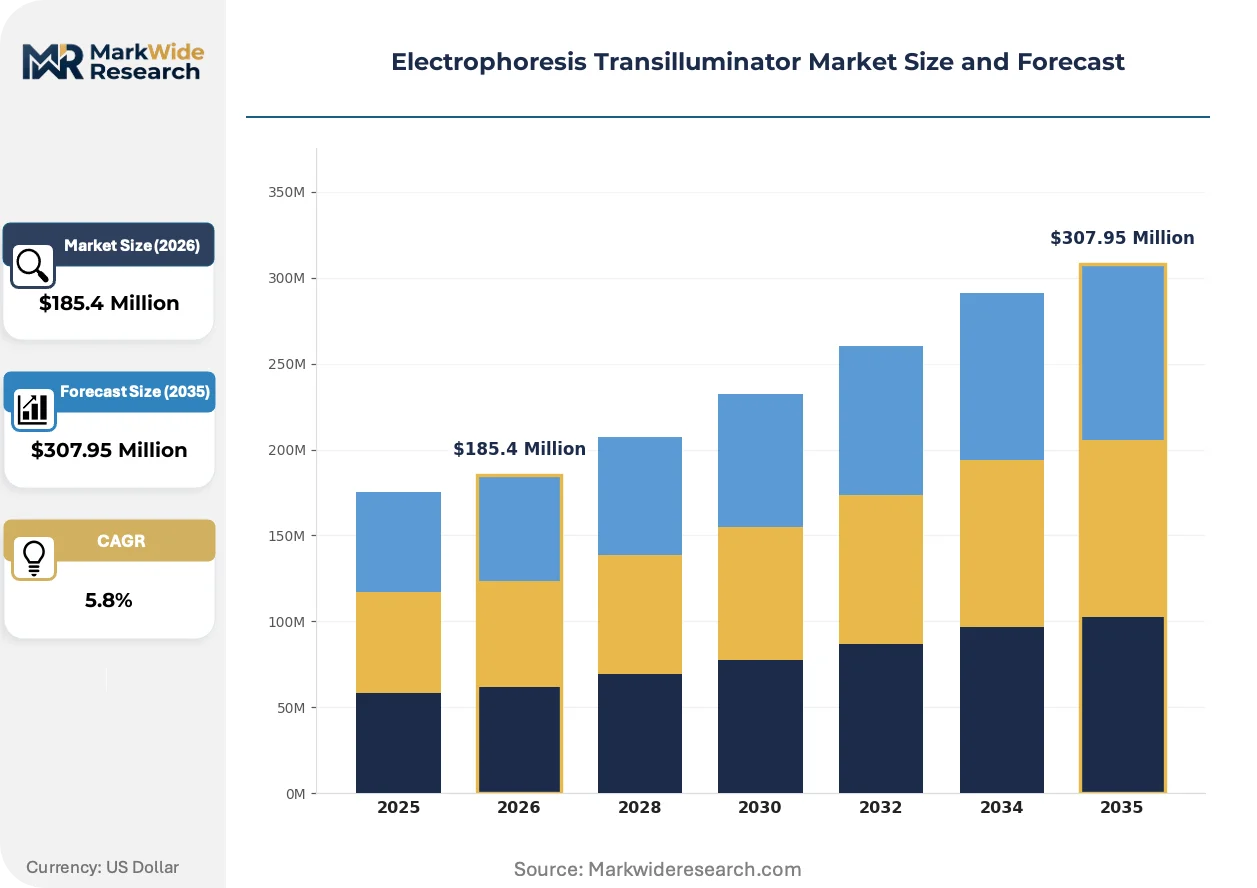
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Transilluminators, Blue Light Transilluminators, LED Transilluminators, Gel Imaging Systems End User: Academic Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Biotechnology Firms Technology: Fluorescence Detection, Image Capture, Laser Scanning, Software Integration Application: DNA Analysis, RNA Analysis, Protein Analysis, Gel Documentation |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Danaher Corporation, Agilent Technologies, GE HealthCare Technologies, Merck KGaA, PerkinElmer, QIAGEN N.V., Azure Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophoresis Transilluminator Market Shifts & Advancements
Computational imaging and solid-state light sources are compressing the traditional separation between hardware capture and software analysis, enabling real-time decision-making at the benchtop without darkroom workflows.
Solid-state LED arrays with tunable emission spectra are virtualizing the traditional UV transilluminator by embedding excitation, detection, and analysis within single integrated platforms. Core facilities at research universities in Germany and the United States adopt these systems at replacement-cycle velocity. The technology is virtualizing separate hardware categories into unified gel documentation workstations that eliminate manual image transfer steps.
REACH restrictions on mercury-containing products accelerate phase-out timelines for UV lamp-based transilluminators across European Union member states. Manufacturers redesign optical enclosures to satisfy EU MDR classification thresholds for devices integrated into in-vitro diagnostic workflows. German notified bodies report expanded conformity assessment queues for laboratory imaging equipment with embedded quantification algorithms.
Research procurement offices now bundle instrument acquisition with multi-year service and reagent supply agreements, compressing standalone hardware margins. Academic buyers in the United States negotiate total-cost-of-ownership contracts that lock in consumable chemistry placement alongside LED transilluminator installation. This pattern concentrates vendor relationships at major research universities while squeezing independent instrument distributors from high-value transactions.
Electrophoresis Transilluminator Market Segmentation
Segmentation in the electrophoresis transilluminator market reveals how procurement cycles, safety protocols, and workflow integration reshape vendor priorities. Understanding where LED displacement accelerates versus where legacy UV systems persist clarifies capital allocation and R&D investment timing.
Product Type:
Replacement velocity varies sharply across hardware categories, with mercury-dependent systems facing compressed obsolescence timelines while integrated platforms extend depreciation schedules through software refresh cycles.
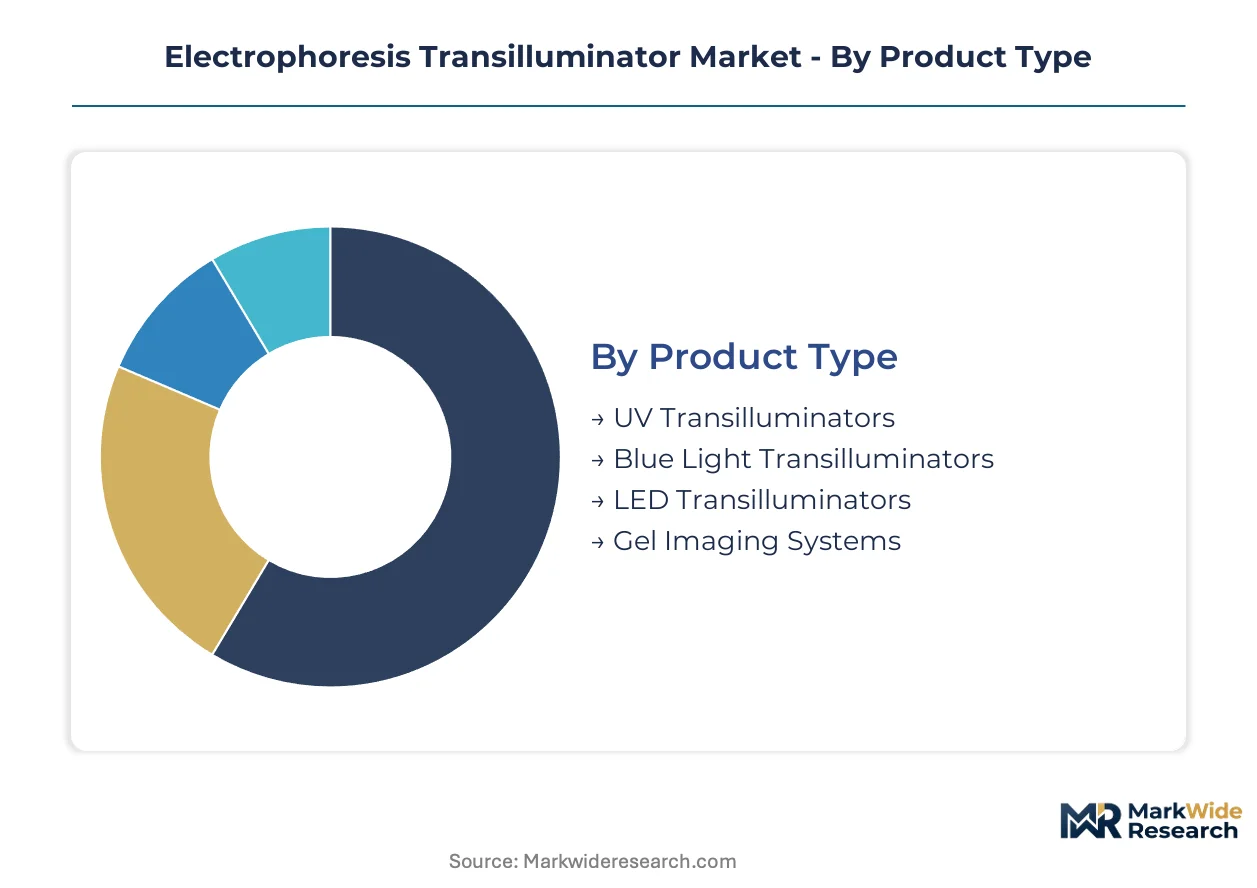
- UV Transilluminators:Mercury-vapor lamp systems emitting 302 nm wavelengths dominate legacy installed bases at academic facilities. EPA hazardous waste disposal restrictions in the United States and REACH phase-out mandates across European Union member states accelerate retirement timelines for these units.
- LED Transilluminators:Solid-state excitation arrays with tunable narrow-band spectra eliminate photodamage risks and hazardous material handling. German Max Planck Institute core facilities standardize procurement around these systems to satisfy operator safety protocols.
- Blue Light Transilluminators:470 nm excitation sources enable damage-free preparative DNA recovery for cloning workflows.
- Gel Imaging Systems:Integrated platforms bundle excitation, capture, and quantification software into unified workstations.
UV Transilluminators dominate installed base. LED Transilluminators is where expansion concentrates.
End User:
Budget authority and procurement complexity separate segments, with centralized research consortia negotiating multi-year service bundles while distributed clinical sites prioritize regulatory qualification speed.
- Academic Research Institutes:University core facilities command the highest unit volumes through centralized purchasing. United States research procurement offices bundle instrument acquisition with consumable supply agreements that lock in vendor relationships across replacement cycles.
- Diagnostic Laboratories:Clinical sites require ISO 13485 certification and FDA 21 CFR Part 892 compliance for diagnostic imaging workflows. Certification costs and notified body queue times constrain vendor entry.
- Pharmaceutical Companies:Quality control verification for biologics manufacturing drives demand for high-sensitivity fluorescence detection.
- Biotechnology Firms:Synthetic biology startups specializing in CRISPR workflows create specialized demand for rapid band verification.
Academic Research Institutes anchor volume procurement. Diagnostic Laboratories capture the steepest expansion trajectory as IVD-adjacent workflows proliferate.
Technology:
Margin concentration follows capability integration depth, with discrete hardware components commoditizing while embedded analysis algorithms command premium positioning.
- Software Integration:Embedded quantification algorithms and cloud-connected documentation platforms transform hardware into recurring-revenue systems. FDA medical device classification scrutiny intensifies for these integrated offerings.
- Fluorescence Detection:Optical path engineering with narrow-bandpass filters enables single-molecule sensitivity for sequencing workflows. Filter fabrication concentrates among German and Japanese specialty glass manufacturers.
- Image Capture:CMOS and CCD sensor modules standardize across mid-tier instrument portfolios.
- Laser Scanning:Confocal detection methods serve specialized proteomics applications requiring spatial resolution.
Fluorescence Detection dominates technical specifications. Software Integration is where margin expansion concentrates.
Application:
Workflow throughput requirements and sample integrity sensitivity determine instrument selection, with preparative applications prioritizing damage-free excitation over analytical speed.
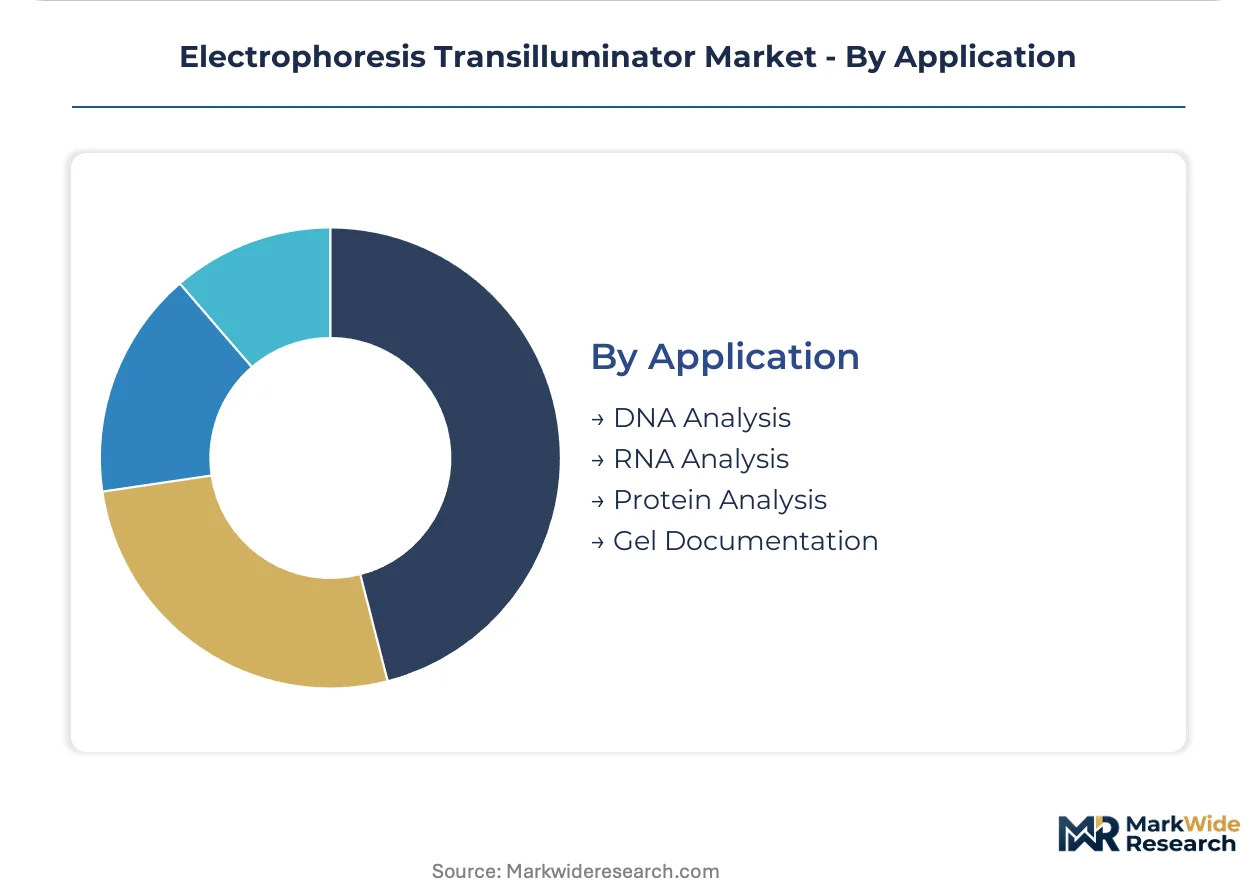
- DNA Analysis:Nucleic acid separation and visualization commands the largest addressable need across academic and clinical settings. Blue light excitation gains share in cloning workflows where band integrity determines downstream success.
- Gel Documentation:Archival imaging with metadata embedding satisfies regulatory audit requirements. EU MDR conformity assessment queues lengthen for systems with embedded quantification in diagnostic contexts.
- Protein Analysis:Western blot visualization and 2D gel documentation require specialized excitation wavelengths.
- RNA Analysis:Integrity assessment for sequencing library preparation demands high-sensitivity detection.
DNA Analysis dominates routine workflow volume. Gel Documentation is where regulatory-driven upgrade cycles concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export integrated gel documentation platforms to United States academic consortia, while Japanese optical component suppliers feed narrow-bandpass filter demand across European notified body queues.
United States
EPA hazardous waste disposal restrictions accelerate LED transilluminator procurement at university core facilities. FDA updated guidance for laboratory imaging equipment prompts optical safety enclosure redesigns. Greater Boston biotech clusters standardize on cloud-connected documentation platforms for distributed CRISPR verification workflows.
Germany
Max Planck Institute facilities consolidate purchasing around integrated systems with embedded analysis software. EU MDR conformity assessment queues lengthen for transilluminators bundled with diagnostic quantification algorithms. Bavarian research consortia negotiate multi-year service contracts that lock consumable chemistry placement alongside hardware installation.
Japan
Specialty glass manufacturers concentrate narrow-bandpass filter fabrication for fluorescence detection modules. METI industrial standards shape optical component qualification protocols for export markets. Osaka-area precision optics clusters supply filter substrates to German and United States instrument assemblers.
China
Synthetic biology startups in Yangtze River Delta cities create specialized demand for high-sensitivity band verification systems. NMPA medical device classification thresholds intensify scrutiny for software-integrated imaging platforms. Shenzhen hardware manufacturing ecosystems produce CMOS sensor modules for mid-tier instrument portfolios.
United Kingdom
Academic procurement offices bundle instrument acquisition with reagent supply agreements across replacement cycles. MHRA alignment with EU MDR extends conformity requirements to gel documentation systems in diagnostic contexts. Cambridge life science clusters prioritize blue light excitation systems for damage-free DNA recovery workflows.
Electrophoresis Transilluminator Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors that bundle hardware, software, and consumable chemistry into recurring-revenue relationships. The vendor base separates into three strategic archetypes: diversified life science conglomerates with fluorescence detection portfolios, specialized gel imaging firms with software integration capabilities, and regional instrument fabricators serving price-sensitive academic segments. Dominant competitive moves include backward integration into consumable chemistry and multi-year service contract extension across instrument generations.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform-scale positioning through life sciences segment integration. Bio-Rad Laboratories occupies a distinct anchor position through its consumables-backward strategy that locks instrument placement via gel chemistry bundling. These three entities represent the primary competitive vectors reshaping procurement dynamics at United States and German research consortia.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Agilent Technologies |
| GE HealthCare Technologies |
| Merck KGaA |
| PerkinElmer |
| QIAGEN N.V. |
| Azure Biosystems |
| Others |
Supply & Pricing Matrix
Japanese specialty glass manufacturers concentrate narrow-bandpass filter fabrication, anchoring margin capture in fluorescence detection modules while downstream instrument assemblers in Germany and the United States compete on bundled service contracts. This upstream concentration transfers pricing power to optical component suppliers even as LED excitation arrays commoditize basic transilluminator hardware.
Pricing Analysis
Legacy mercury-vapor UV systems, current-generation LED arrays, and next-generation integrated gel documentation platforms occupy distinct pricing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and software integration depth. Price differentiation stems from FDA medical device classification thresholds and multi-year consumable bundling agreements. Cost compression in mid-tier LED units is intensifying because Shenzhen-based CMOS sensor module suppliers expand manufacturing capacity. Academic research institutes exhibit highest price sensitivity, while diagnostic laboratories prioritize regulatory qualification speed over unit cost.
Supply Chain Analysis
Extended payment terms from German notified body service providers and supply-chain finance facilities at Max Planck Institute procurement offices reshape working capital dynamics across the value chain. Geographic supply concentration centers on Japan for specialty optical glass, Germany for precision filter assembly, and China for CMOS sensor module production. Raw material dependencies include rare-earth phosphors for LED excitation arrays, borosilicate glass substrates, and high-purity mercury for legacy lamp systems. Single-source vulnerability in narrow-bandpass filter fabrication creates structural risk. Distribution runs through academic core facility procurement consortia and clinical laboratory GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as CRISPR quality control workflows and synthetic biology startup formation create specialized demand niches beyond standardized academic procurement. LED displacement of legacy UV systems generates white-space for differentiated positioning.
For Market Incumbents: Pre-empt emerging entrant encroachment by accelerating backward integration into gel chemistry consumables and extending multi-year service contracts across LED replacement cycles. Certification investment in EU MDR conformity assessment pathways locks out mid-tier competitors. Channel control through university procurement office relationships defends placement against cloud-connected documentation platform challengers. For New Entrants and Emerging Players: Establish a beachhead in biotechnology firm CRISPR verification workflows where high-sensitivity fluorescence detection demands outstrip incumbent software integration capabilities. Synthetic biology startups in Yangtze River Delta cities represent the most penetrable segment. Go-to-market angle centers on damage-free blue light excitation systems for preparative DNA recovery with rapid installation protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected documentation platform development as software R&D scales over hardware fabrication. Long-term viability favors vendors with recurring-revenue service contract portfolios and notified body relationship assets. Acquisition target archetype: specialized gel imaging firms with embedded quantification algorithm IP. Signal to watch: EU MDR conformity assessment queue lengths for software-integrated systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gel Chemistry | Consumables bundling locks instrument placement at Max Planck Institute facilities. |
| EU MDR Conformity Assessment Investment | Notified body relationships accelerate market access for diagnostic-integrated platforms. |
| Cloud-Connected Documentation Platform Launch | Remote image storage penetrates distributed CRISPR verification workflows in Greater Boston. |
| Blue Light Excitation System Development | Damage-free DNA recovery addresses cloning laboratory preparative workflow demands. |
| Multi-Year Service Contract Extension | Recurring revenue compression defends margins against Shenzhen CMOS module price erosion. |
Research Methodology
Cross-validation between primary interviews with laboratory directors and secondary validation through FDA 510(k) filings anchors the qualitative findings. Stakeholder engagement encompassed core facility managers at United States research universities, biomedical engineers at German Max Planck Institutes, procurement officers at clinical diagnostic laboratories, and fluorescence detection specialists at optical component manufacturers. Secondary sources included EPA hazardous waste disposal records, EU MDR notified body conformity assessment databases, METI industrial standard publications, and customs trade data for optical glass imports. Bottom-up instrument shipment estimates and top-down addressable market sizing were triangulated against capital expenditure disclosures from academic consortia.
Calibration against historical replacement cycle velocities and technology diffusion patterns shaped the analytical framework. Segmentation dimensions modeled include product type, end user category, technology integration depth, and application workflow. CAGRs were derived from installed base retirement timelines for mercury-vapor systems and LED adoption curves across academic procurement offices. Industry-specific forecast inputs encompassed REACH phase-out enforcement schedules and NMPA medical device classification threshold adjustments.
Stress conditions across EPA enforcement intensity, EU MDR queue duration, and CMOS sensor module supply expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding LED cost reduction trajectories and software integration feature penetration. Macroeconomic contraction in academic research funding, regulatory reclassification of gel documentation systems, or solid-state excitation technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market