
 C-Reactive Protein Analyzers Market | 2026-2036
C-Reactive Protein Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
C-Reactive Protein Analyzers Market Outlook
Hospital emergency departments are rotating toward point-of-care CRP testing as a buyer archetype, displacing centralized laboratory workflows in triage settings. Siemens Healthineers anchors its position through automated analyzer platforms designed for high-throughput hospital laboratories. Abbott Laboratories differentiates via handheld point-of-care devices that compete for bedside deployment in critical care units. bioMérieux SA specializes in immunoassay-based systems that sustain strong presence in European diagnostic networks.
C-reactive protein analyzers are quantitative diagnostic instruments that measure serum or plasma CRP concentration, typically employing turbidimetric or nephelometric detection with sensitivity thresholds spanning 0.3 to 10 mg/L for standard assays and sub-0.3 mg/L for high-sensitivity cardiac applications. These devices serve primary clinical purposes in infection detection, inflammation monitoring, and cardiovascular risk stratification. Automated analyzers dominate installed base and revenue contribution due to established laboratory infrastructure and reimbursement alignment. Point-of-care devices represent the fastest-expanding segment as decentralized testing protocols gain protocol adoption in emergency and primary care settings. Immunoassay technology occupies the largest technology share while microfluidics platforms are penetrating near-patient environments through reduced sample volume requirements.
FDA 510(k) clearance pathways and Clinical Laboratory Improvement Amendments standards shape product development timelines and commercial access for CRP analyzer manufacturers targeting the United States market. The EU In Vitro Diagnostic Regulation and CE marking requirements under MDR frameworks impose strengthened clinical evidence demands on devices distributed across European member states. Stakeholders must monitor evolving payer coverage determinations for high-sensitivity CRP cardiovascular screening as these decisions will determine addressable market expansion beyond traditional infectious disease applications.
Market Dynamics
Hospital emergency departments are consolidating testing authority at the point of care, compressing turnaround times from centralized laboratory workflows and forcing manufacturers to reconfigure analyzer portfolios toward handheld form factors.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for moderate-risk diagnostic devices enable faster commercialization of next-generation CRP analyzers targeting bedside deployment.
- Cardiovascular risk stratification protocols:High-sensitivity CRP assays are gaining protocol inclusion in preventive cardiology guidelines, expanding addressable testing volume beyond infectious disease applications.
- Microfluidics integration:Reduced sample volume requirements enable fingerstick testing in primary care clinics previously constrained by phlebotomy infrastructure limitations.
Market Restraints
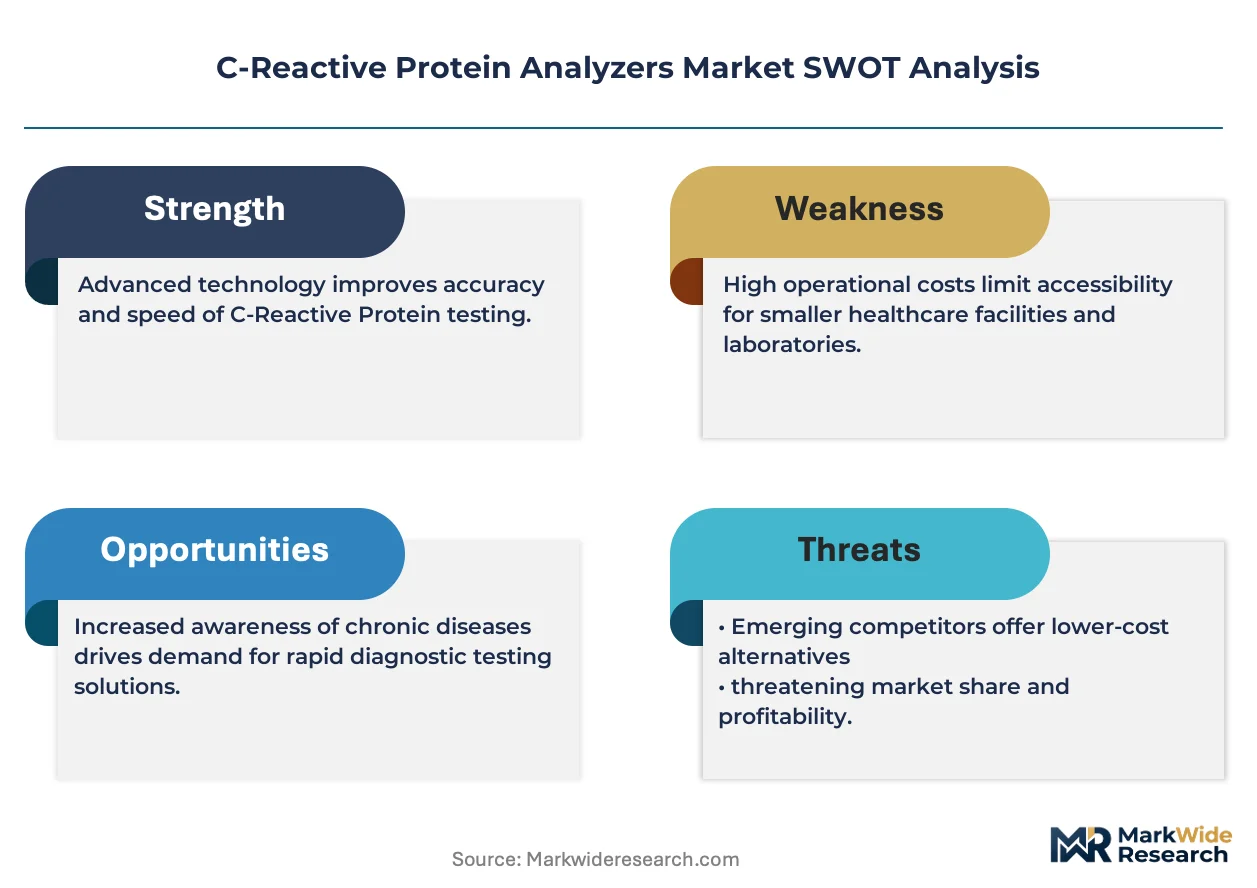
- Optical component supply concentration:Precision photodetectors and laser diodes for nephelometric detection concentrate among specialized Japanese and German component suppliers, creating input vulnerability.
- EU MDR clinical evidence demands:Strengthened post-market surveillance and performance documentation requirements under the In Vitro Diagnostic Regulation extend validation timelines and elevate regulatory compliance costs.
- Centralized laboratory reimbursement alignment:Established CPT coding and payment structures favor high-throughput automated analyzers, creating pricing headwinds for decentralized point-of-care alternatives.
Strategic Opportunities
- Retail pharmacy clinic expansion:MinuteClinic-style operations in the United States represent underpenetrated deployment channels for waived-complexity CRP devices serving acute respiratory triage.
- AI-assisted result interpretation:Machine learning algorithms converging with quantitative CRP outputs enable risk scoring integration into electronic health record workflows.
- India diagnostic network buildout:Ayushman Bharat health infrastructure investments create procurement scale for affordable analyzer platforms targeting district hospital laboratories.
Industry Challenges
- Multi-site instrument standardization:Health system consolidations spanning multiple states require harmonized quality control protocols across heterogeneous installed bases of competing analyzer brands.
- CAP proficiency testing compliance:College of American Pathologists accreditation mandates for high-sensitivity cardiac CRP assays impose ongoing external validation burdens on laboratory operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C-Reactive Protein Analyzers Market |
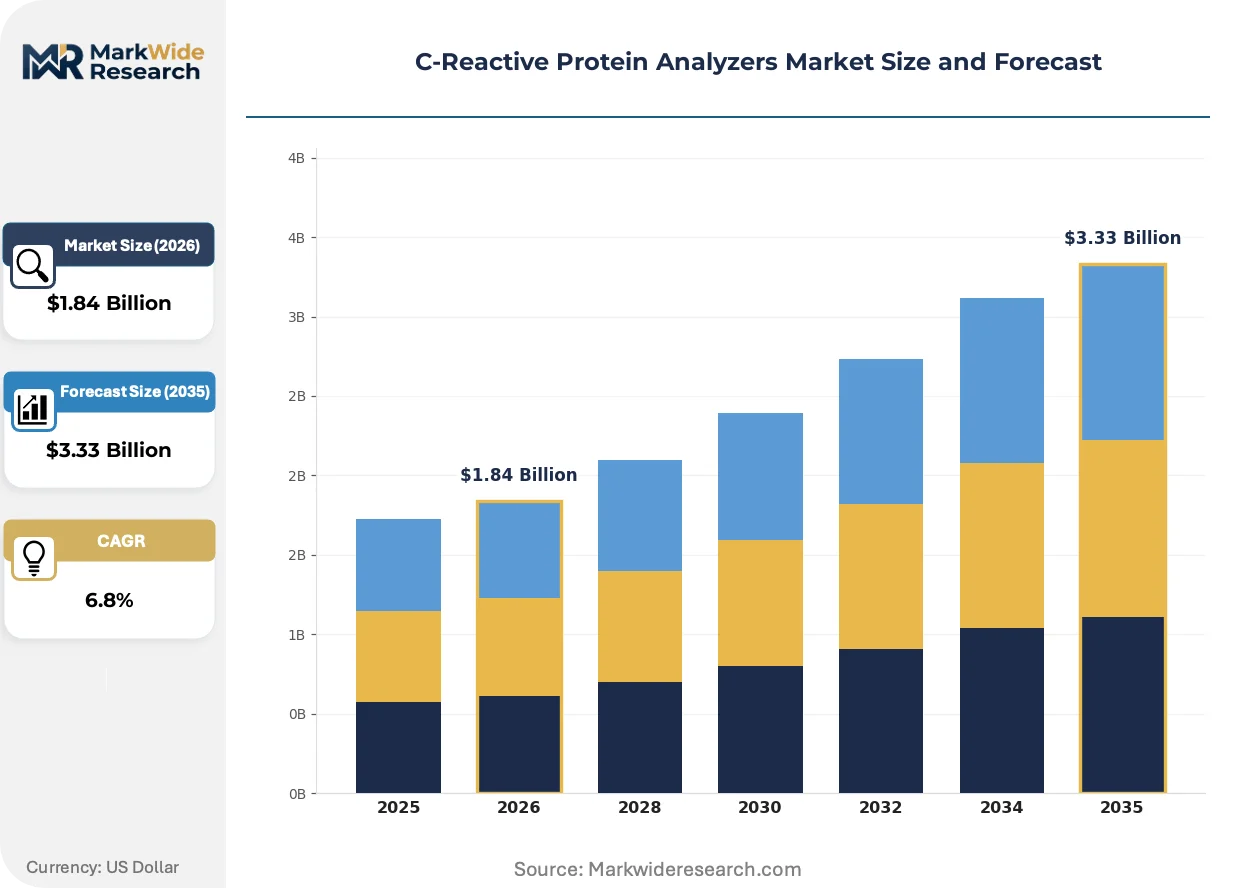
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Point-of-Care Devices, Laboratory Instruments, Rapid Test Kits End User: Hospitals, Diagnostic Laboratories, Home Healthcare, Research Institutions Technology: Immunoassay, Molecular Diagnostics, Microfluidics, Spectrophotometry Application: Infection Detection, Inflammation Monitoring, Cardiovascular Risk Assessment, Autoimmune Disease Screening |
| Companies Covered | F. Hoffmann-La Roche AG, Abbott Laboratories, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Danaher Corporation, Becton, Dickinson and Company, bioMérieux SA, Ortho Clinical Diagnostics, Randox Laboratories Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C-Reactive Protein Analyzers Market Strategic Shifts
Detection modalities and testing locations are diverging simultaneously, with sensitivity thresholds climbing for cardiac applications while physical device footprints shrink for emergency deployment.
Microfluidic cartridge systems are supplanting traditional cuvette-based sample handling in near-patient environments. Emergency department nursing staff are adopting these platforms for 90-second turnaround protocols during influenza season triage. This shift compresses revenue capture for hospital core laboratories while redirecting test economics toward device manufacturers and disposable consumables.
EU MDR performance evaluation requirements are tightening clinical evidence standards for quantitative immunoassay platforms. Manufacturers must now submit prospective analytical and clinical validation studies for CE marking renewal, not just technical file updates. High-sensitivity CRP assays with cardiovascular claims face heightened scrutiny from notified bodies in Germany and the Netherlands.
Integrated delivery networks are consolidating analyzer procurement through single-source contracting vehicles. Hospital systems spanning multiple states now negotiate enterprise agreements covering hundreds of affiliated laboratories, displacing site-by-site purchasing autonomy. This concentration is most visible in the United States, where Catholic health systems and for-profit chains command substantial leverage over analyzer vendors.
C-Reactive Protein Analyzers Market Segmentation
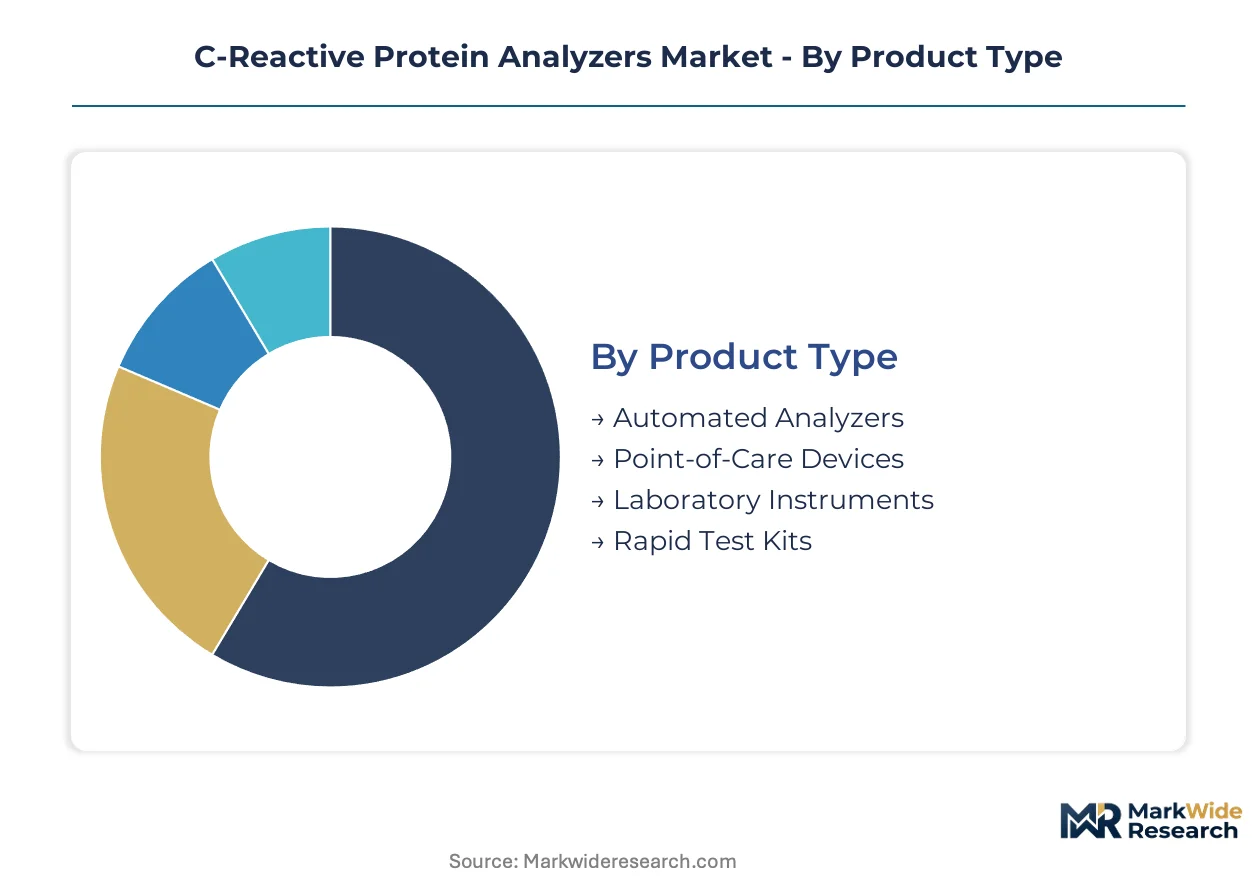
Segmentation in the C-reactive protein analyzers market reveals divergent channel strategies. Automated platforms flow through centralized procurement contracts. Point-of-care devices penetrate via emergency department budgets and retail clinic networks.
Product Type:
Automated analyzers dominate hospital laboratory procurement through multi-year service agreements. Point-of-care devices capture emergency department capital budgets with compressed purchasing cycles.
- Automated Analyzers:High-throughput platforms process 200-800 tests per hour using turbidimetric detection. Siemens Healthineers and Roche Diagnostics anchor installed bases in United States integrated delivery networks where core laboratories consolidate testing volume.
- Point-of-Care Devices:Handheld or compact benchtop units deliver results in under 5 minutes from capillary samples. Emergency departments in the United States are displacing send-out workflows during influenza season triage, compressing turnaround from 45 minutes to 90 seconds.
- Laboratory Instruments:Mid-throughput systems serve regional hospital laboratories with 50-200 test hourly capacity.
- Rapid Test Kits:Single-use lateral flow cassettes enable screening in resource-limited settings without instrument infrastructure.
By volume, automated analyzers lead. By growth pace, point-of-care devices are expanding most quickly.
End User:
Cost tier differentiation separates capital-intensive hospital deployments from consumable-driven home healthcare models. Diagnostic laboratories occupy the mid-tier with reagent rental structures.
- Hospitals:Emergency departments and core laboratories represent distinct buyer archetypes with conflicting procurement priorities. Emergency nursing staff in the United States are gaining testing authority previously held by laboratory medicine departments.
- Diagnostic Laboratories:Independent and hospital-affiliated labs drive reagent consumption through established high-throughput infrastructure. United States reference laboratories such as Quest Diagnostics and LabCorp negotiate volume-based pricing for automated analyzer placements.
- Home Healthcare:Remote monitoring applications for chronic inflammation management remain nascent due to reimbursement gaps.
- Research Institutions:Academic medical centers purchase specialized high-sensitivity platforms for cardiovascular biomarker studies.
Emergency departments within hospital systems are gaining procurement autonomy fastest. Diagnostic laboratories retain the largest aggregate reagent spend.
Technology:
Application requirements dictate technology selection. Cardiovascular risk stratification demands nephelometric sensitivity. Near-patient deployment favors microfluidic miniaturization.
- Immunoassay:Antibody-based quantification dominates installed base through proven analytical performance. Turbidimetric and nephelometric variants serve standard and high-sensitivity CRP applications respectively in United States hospital laboratories.
- Microfluidics:Cartridge-based platforms integrate sample preparation with optical detection in sub-milliliter volumes. Primary care clinics in the United States are adopting fingerstick protocols that bypass phlebotomy infrastructure constraints.
- Molecular Diagnostics:PCR-integrated platforms remain peripheral for CRP quantification given protein-based versus nucleic acid target mismatch.
- Spectrophotometry:Colorimetric endpoint detection serves cost-sensitive markets with reduced sensitivity requirements.
Immunoassay platforms command the largest installed base. Microfluidics systems are climbing the fastest as point-of-care protocols expand.
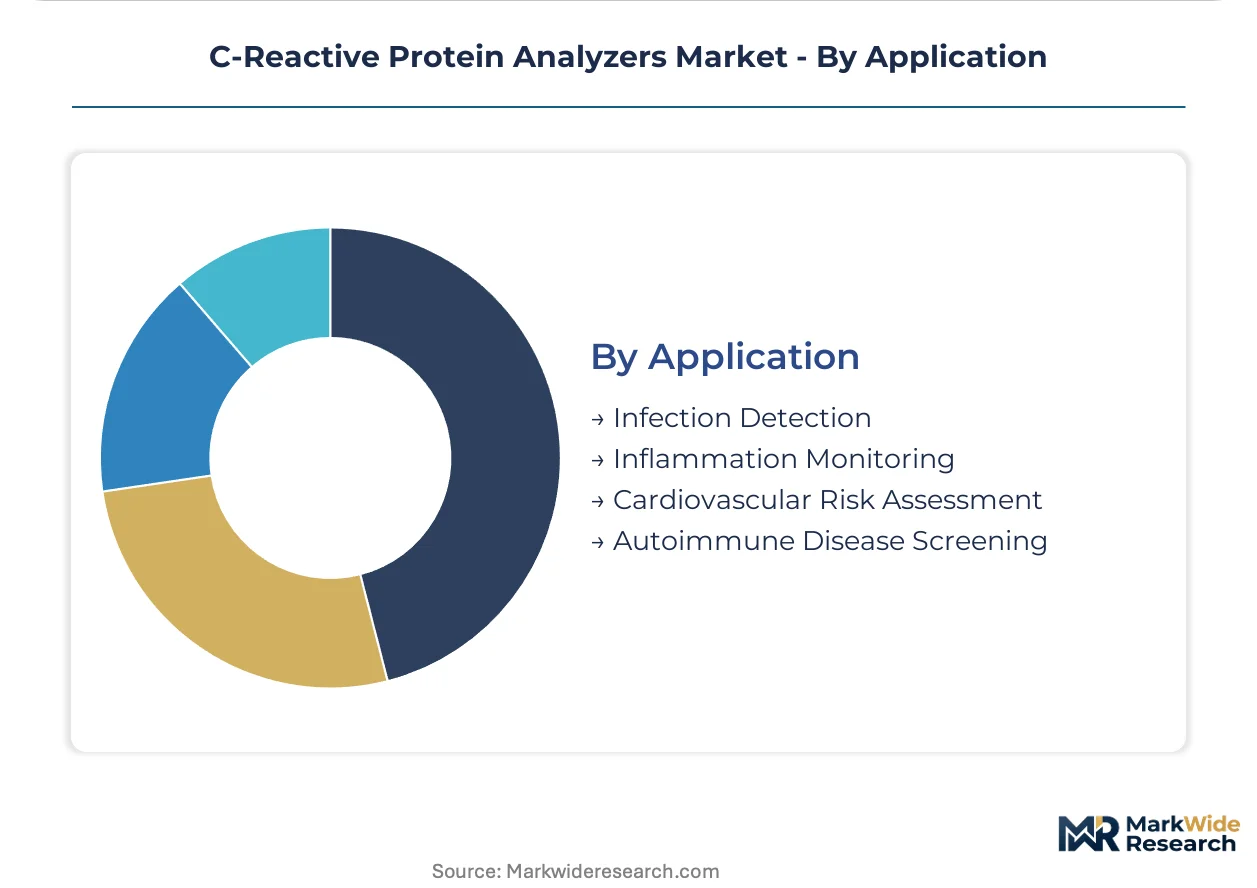
Application:
Customer type segmentation separates acute infection triage from chronic disease management workflows. Reimbursement alignment varies sharply across these use cases.
- Infection Detection:Bacterial versus viral differentiation protocols in emergency departments drive seasonal demand spikes. United States hospitals deploy point-of-care CRP during influenza season to reduce unnecessary antibiotic prescriptions.
- Cardiovascular Risk Assessment:High-sensitivity CRP assays below 0.3 mg/L detection thresholds enable preventive cardiology protocols. United States payer coverage determinations from CMS and commercial insurers remain inconsistent for screening applications.
- Inflammation Monitoring:Serial testing for rheumatoid arthritis and inflammatory bowel disease generates recurring revenue through chronic disease management.
- Autoimmune Disease Screening:Systemic lupus erythematosus and vasculitis workups contribute specialized testing volume in rheumatology practices.
Infection detection generates the highest test frequency. Cardiovascular risk assessment holds the steepest expansion trajectory pending reimbursement clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision optical components for nephelometric detection to United States hospital systems, while Japanese photodetector suppliers feed manufacturing lines across multiple end-markets. Trade corridors for CRP analyzer finished goods run predominantly from Western Europe and North America into Asia-Pacific diagnostic networks.
United States
Emergency departments in integrated delivery networks are consolidating point-of-care procurement authority, displacing traditional laboratory medicine departments. FDA 510(k) clearance pathways and CLIA waiver standards shape product validation timelines for bedside deployment. The Cleveland Clinic and Mayo Clinic health systems anchor multi-state contracting vehicles that command substantial vendor leverage.
Germany
High-sensitivity cardiac CRP assays face heightened scrutiny from notified bodies under EU MDR performance evaluation requirements. The country's national pharmaceutical regulator enforces strengthened post-market surveillance documentation for quantitative immunoassay platforms. The Rhine-Main cluster around Frankfurt concentrates diagnostic instrument engineering expertise serving European reference laboratories.
Japan
Precision photodetectors and laser diodes for turbidimetric detection concentrate among specialized component suppliers in Osaka and Nagoya industrial zones. METI industrial standards guide analytical performance specifications for domestic diagnostic device manufacturers. The Kanto region around Tokyo houses headquarters of conglomerates with diversified in vitro diagnostic portfolios.
India
Ayushman Bharat health infrastructure investments create procurement scale for affordable analyzer platforms targeting district hospital laboratories. CDSCO medical device regulations are aligning with international harmonization frameworks for in vitro diagnostic classification. The Maharashtra-Gujarat industrial corridor is emerging as a manufacturing location for export-oriented diagnostic consumables.
China
Domestic diagnostic device manufacturers are expanding production capacity for mid-throughput CRP analyzers serving tier-two and tier-three city hospitals. NMPA medical device registration requirements impose clinical trial obligations for novel detection technologies. The Yangtze River Delta around Shanghai concentrates reagent manufacturing and distribution logistics for the Asia-Pacific region.
C-Reactive Protein Analyzers Market Competitive Environment
Player mix skews toward diversified conglomerates with broad in vitro diagnostic portfolios, creating tiered competition between integrated platform vendors and specialized immunoassay houses. Market structure concentrates revenue among five to seven entities with established installed bases in hospital laboratories and emergency departments. Two strategic archetypes dominate: high-throughput automated platform specialists and handheld point-of-care device developers. Competitive moves center on enterprise contracting vehicles with multi-state health systems and microfluidics technology licensing for near-patient applications.
Among Swiss and German conglomerates with diversified healthcare portfolios, F. Hoffmann-La Roche AG and Siemens Healthineers AG occupy positions exemplifying the high-throughput automated platform archetype. Abbott Laboratories represents the point-of-care specialization vector with handheld form factors targeting emergency department deployment. These three entities anchor the competitive structure through contrasting channel strategies—centralized laboratory procurement versus decentralized bedside testing authority.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| bioMérieux SA |
| Ortho Clinical Diagnostics |
| Randox Laboratories Limited |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for precision photodetectors concentrate pricing power among Japanese and German component suppliers, while analyzer manufacturers absorb inventory carrying costs that compress margins on point-of-care devices sold through emergency department procurement channels.
Pricing Analysis
Next-generation microfluidic platforms command a forty-to-sixty percent premium over prior-generation turbidimetric systems, while legacy automated analyzers face pricing erosion from reagent rental structures. Three-tier pricing structure across premium, standard, and economy levels separates high-sensitivity cardiac assays from standard infection-detection protocols from rapid lateral-flow screening kits. Pricing pressure stems from integrated delivery network enterprise contracting that aggregates volume across multi-state health systems. Diagnostic laboratories exhibit the highest price sensitivity due to reagent cost-per-test optimization, while research institutions show the least sensitivity for specialized high-sensitivity platforms.
Supply Chain Analysis
Japan and Germany anchor precision optical component production, supplying photodetectors and laser diodes that feed analyzer assembly lines in the United States and Western Europe. German manufacturers draw from specialized glass substrate foundries and precision optics grinding operations concentrated in the Rhine-Main corridor. Single-source vulnerability concentrates in photodetector supply from Osaka-based component houses. Distribution runs through hospital GPO contracts and direct manufacturer agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation, with multi-state health systems commanding leverage over analyzer vendors through enterprise procurement vehicles spanning hundreds of affiliated laboratories.
For Market Incumbents: Compound installed base advantages by embedding AI-assisted result interpretation into existing analyzer software ecosystems, locking in switching costs against emerging microfluidics specialists. Pursue backward integration into precision photodetector supply through strategic partnerships with Japanese component houses, mitigating single-source exposure. Defend against point-of-care disruption by accelerating CLIA waiver acquisition for next-generation handheld platforms. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining offers accelerated clearance timelines for moderate-risk diagnostic devices targeting bedside deployment. Retail pharmacy clinic networks in the United States represent the most penetrable white-space channel, with MinuteClinic-style operations lacking established CRP testing protocols. Target emergency department nursing staff as direct economic buyers, bypassing traditional laboratory medicine procurement committees through 90-second turnaround value propositions. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because health system procurement concentration favors scale vendors with enterprise contracting capabilities. Acquisition targets should profile as microfluidics platform developers with cleared cardiovascular assay menus and established hospital pilot programs. Watch for CMS reimbursement determinations on high-sensitivity CRP screening as the inflection signal for addressable market expansion beyond infectious disease applications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines enable faster bedside deployment of next-generation analyzers in emergency departments. |
| CE Marking Pathway | EU MDR performance evaluation requirements demand strengthened clinical evidence for quantitative immunoassay platforms. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks aggregate procurement volume across multi-state laboratory operations. |
| Software Companion Development | AI-assisted result interpretation enables risk scoring integration into electronic health record workflows. |
| Reimbursement Strategy | Payer coverage determinations for high-sensitivity CRP cardiovascular screening determine market expansion beyond infection detection. |
Study Parameters
A spread of perspectives from emergency department clinicians, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up instrument placement estimates and top-down reagent consumption models underwent cross-triangulation to converge on market sizing.
Segmentation dimensions modeled include product type, end user, technology platform, and application across the analysis window. CAGRs were derived from instrument placement trajectories and per-test economics projected over the modeling period. Forecast inputs incorporated CLIA waiver expansion timelines, integrated delivery network consolidation patterns, and cardiovascular risk stratification protocol adoption curves.
Underlying assumptions cover regulatory clearance continuity and reimbursement stability, with deviation risk concentrated in EU MDR implementation delays and CMS coverage determination reversals. Recalibration cycles align with material shifts in FDA guidance document revisions and health system merger activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Microplate Luminometer Market