
 Laboratory Furniture Market | 2026-2036
Laboratory Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Furniture Market Intelligence
Aftermarket service revenue is reshaping competitive economics in laboratory furniture as installation complexity and certification requirements extend vendor relationships beyond the initial sale. Thermo Fisher Scientific leverages its integrated life sciences platform to bundle furniture with instrumentation and ongoing validation services. Waldner Laboreinrichtungen anchors its position through precision-engineered modular systems manufactured in Germany. Kewaunee Scientific Corporation competes on domestic manufacturing scale and rapid custom fabrication turnaround for North American research institutions.
Laboratory furniture encompasses specialized workstations, storage systems, and containment enclosures engineered to withstand chemical corrosion, thermal cycling, and biocontainment protocols, typically fabricated from 16-gauge stainless steel, chemical-resistant phenolic resin, or epoxy-coated substrates to meet SEFA 8 performance standards. Fume hoods and modular systems command premium positioning due to integrated ventilation engineering and reconfiguration flexibility demanded by multi-purpose research facilities. Stainless steel and epoxy resin materials dominate pharmaceutical and healthcare installations where sterilization protocols and aggressive disinfectant compatibility are non-negotiable. Academic institutions and research labs increasingly specify mobile and modular configurations to accommodate shifting project teams and shared instrumentation layouts.
SEFA, OSHA, and EPA standards govern laboratory furniture construction, chemical fume containment performance, and worker exposure limits in the United States, directly influencing hood face velocity specifications and material selection for compliance. The FDA's GMP guidelines for pharmaceutical manufacturing further constrain furniture surface finishes and cleanability requirements in drug development environments. Stakeholders must monitor evolving biosafety level classifications and net-zero building mandates as these frameworks increasingly dictate laboratory infrastructure investment priorities.
Market Dynamics
Biologics manufacturing expansion is compressing laboratory furniture procurement cycles as pharmaceutical developers demand faster facility commissioning timelines to capture patent windows. Modular containment systems now compete directly with fixed installations as project sponsors prioritize reconfiguration flexibility over permanence.
Growth Catalysts
- Biologics capacity buildouts:Pharmaceutical manufacturers are commissioning specialized containment suites for cell and gene therapy production, requiring SEFA 8-compliant stainless steel casework with integrated HVAC monitoring.
- EPA ventilation mandates:Tighter chemical fume hood performance standards under the EPA's Risk Management Plan are forcing research institutions to replace aging infrastructure with certified low-flow containment systems.
- Modular construction methods:Prefabricated cleanroom pods with pre-installed furniture systems are cutting facility build times by half, attracting contract research organizations in Boston and North Carolina's Research Triangle.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings are compressing margins for domestic fabricators who cannot pass through surcharges to locked university budgets.
- German equipment dominance:Precision-engineered modular systems from specialized Mittelstand manufacturers concentrate high-performance supply in a single geography, creating lead time vulnerability.
- Legacy infrastructure lock-in:Existing fixed-bench installations in academic institutions create switching friction that delays replacement cycles even when performance standards lapse.
Strategic Opportunities
- Net-zero laboratory mandates:The IRA's energy efficiency incentives for research facilities are creating demand for low-flow fume hoods with heat recovery and LED-integrated task lighting systems.
- Cell therapy manufacturing:Isolator-integrated workstations for aseptic processing represent an underpenetrated application where furniture vendors can bundle containment with environmental monitoring.
- Service revenue bundling:Validation, recertification, and predictive maintenance contracts are extending vendor relationships beyond initial sale, particularly among pharmaceutical quality assurance departments.
Industry Challenges
- Certification timeline compression:SEFA 8 performance testing and NSF/ANSI 49 biosafety cabinet validation create bottlenecks that delay revenue recognition on large institutional projects.
- Cross-functional coordination:Furniture specification now requires simultaneous input from facilities engineering, environmental health and safety, and procurement teams, extending sales cycles and increasing specification change orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Furniture Market |
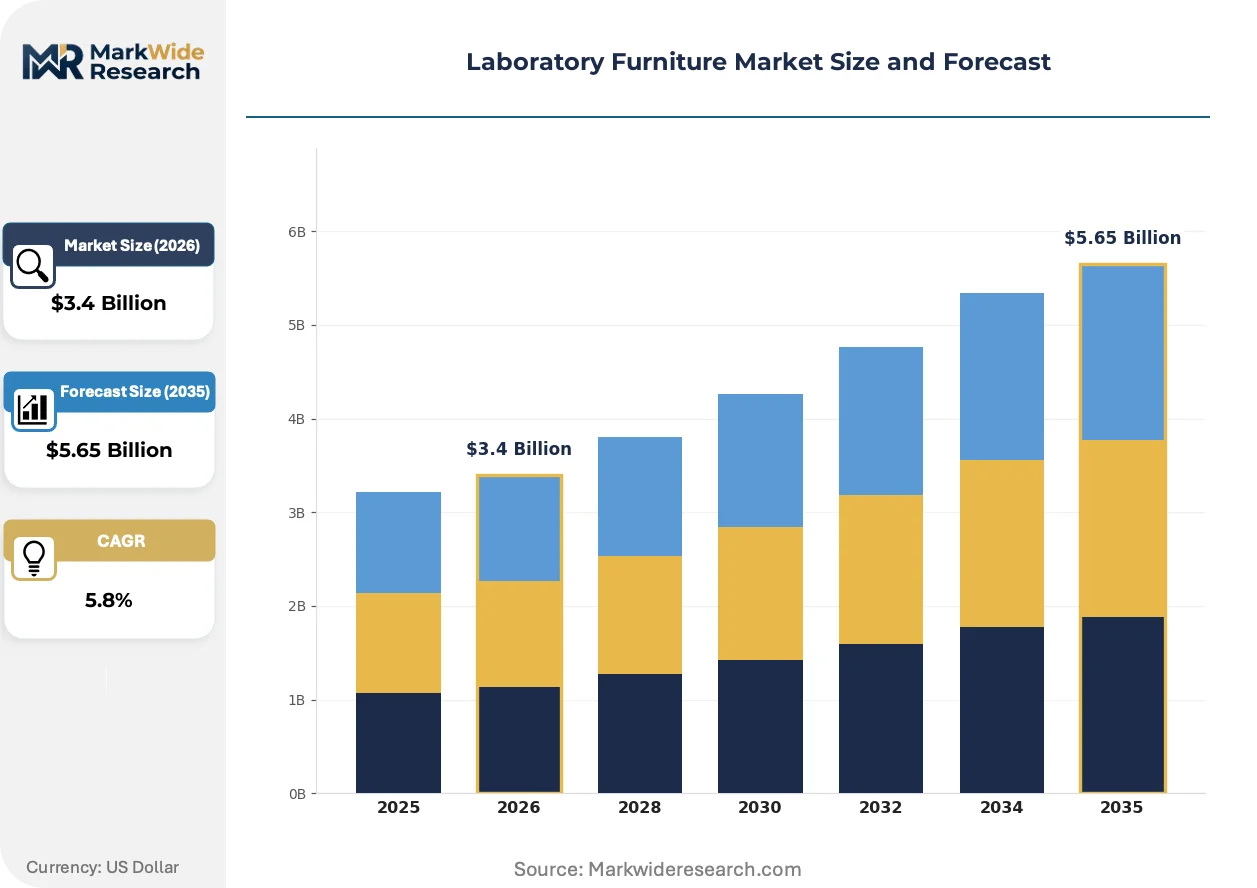
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Workbenches, Cabinets, Fume Hoods, Shelving Units Material: Stainless Steel, Wood, Laminate, Epoxy Resin End User: Academic Institutions, Pharmaceutical Companies, Research Labs, Healthcare Facilities Configuration: Modular Systems, Fixed Installations, Mobile Units, Custom Designs |
| Companies Covered | Labconco Corporation, Mott Manufacturing, Thermo Fisher Scientific, PSA Laboratory Furniture, ESCO Group, Kewaunee Scientific Corporation, Asecos GmbH, Diversified Woodcrafts, Waldner Laboreinrichtungen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Furniture Market Strategic Shifts & Innovations
Phenolic resin composites and adaptive ventilation controls are converging to redefine performance benchmarks for chemical resistance and energy intensity. Laboratory planners now specify furniture as integrated infrastructure nodes rather than standalone equipment.
Adaptive airflow management using real-time sash position sensors and variable frequency drives is collapsing the energy consumption profile of chemical fume hoods. Pharmaceutical manufacturers in Massachusetts and California are specifying these systems for new buildouts. The technology is collapsing the historical tradeoff between containment assurance and HVAC operating cost.
REACH restrictions on formaldehyde emissions and flame retardants are constraining substrate selection for European laboratory exports. Furniture manufacturers serving the EU market are reformulating particleboard cores and switching to water-based epoxy coatings. Academic consortia in Germany and the Netherlands are now requiring full material disclosure documentation as a procurement gate.
Research institutions are consolidating vendor relationships through master service agreements that bundle furniture, installation, and multi-year certification support. University procurement offices in the United States are displacing project-by-project bidding with preferred supplier panels. This consolidation is most visible among R1 research universities managing distributed laboratory portfolios across multiple campuses.
Laboratory Furniture Market Segmentation
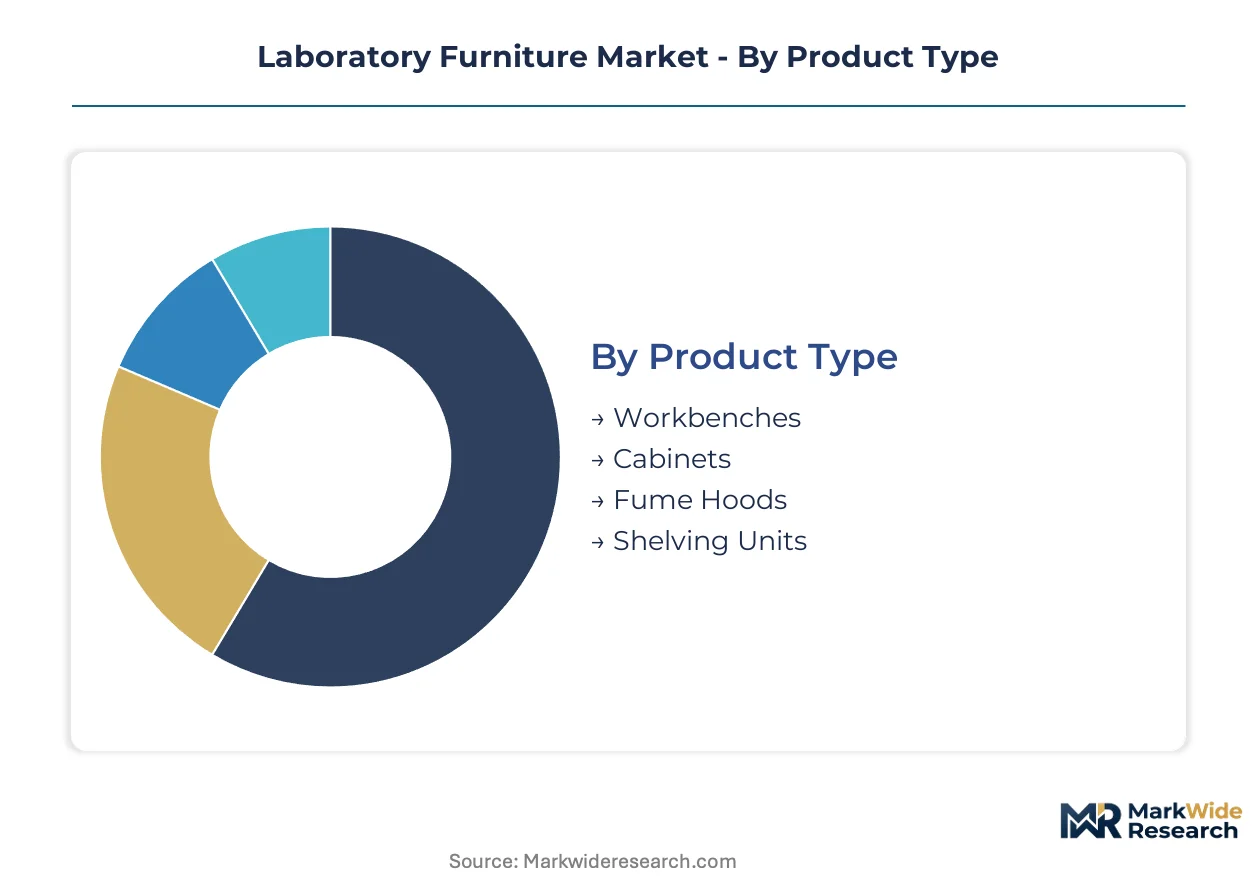
Laboratory furniture segmentation reflects divergent technical requirements across containment levels, sterilization protocols, and reconfiguration frequency. Material selection and configuration type increasingly determine procurement decisions as facilities balance SEFA compliance against operational flexibility demands.
Product Type:
Mature workstation categories dominate installed base volumes while containment-integrated systems emerge as specification priorities for biologics manufacturing.
- Workbenches:Fabricated from 16-gauge stainless steel or phenolic resin substrates with chemical-resistant edge banding, these surfaces withstand thermal cycling and aggressive disinfectant protocols. Academic institutions in the United States specify adjustable-height configurations to accommodate shared instrumentation layouts and rotating research teams.
- Fume Hoods:Engineered containment enclosures with integrated ventilation engineering face velocity specifications governed by EPA Risk Management Plan requirements. Pharmaceutical developers in Massachusetts and North Carolina's Research Triangle Park commission low-flow variants with heat recovery to capture IRA energy efficiency incentives.
- Cabinets:Storage systems for chemical inventory and consumables feature corrosion-resistant hardware and spill containment sumps.
- Shelving Units:Adjustable racking systems support reagent organization and bulk supply storage.
Workbenches handle the majority of throughput; fume hoods are the fastest mover on share.
Material:
Cost tier stratification separates premium corrosion-resistant substrates from budget-compatible alternatives in procurement specifications.
- Stainless Steel:304 and 316-grade alloys deliver sterilization protocol compatibility and biocontainment durability required for cell therapy manufacturing. Nickel and chromium input cost volatility compresses margins for domestic fabricators serving locked university budgets.
- Epoxy Resin:Thermoset polymer coatings provide chemical resistance and seamless surface finishes for pharmaceutical GMP environments. REACH restrictions on formaldehyde emissions constrain European export formulations.
- Laminate:High-pressure decorative surfaces balance cost and moderate chemical resistance for educational laboratories.
- Wood:Sealed hardwood substrates serve light-duty applications with limited chemical exposure.
Stainless steel commands premium positioning; epoxy resin is expanding most quickly in pharmaceutical specifications.
End User:
Customer type segmentation reveals divergent procurement authority structures and compliance burden tolerance across institutional categories.
- Pharmaceutical Companies:Biologics manufacturers commission SEFA 8-compliant containment suites with integrated HVAC monitoring for cell and gene therapy production. Faster facility commissioning timelines compress procurement cycles to capture patent windows.
- Academic Institutions:R1 research universities manage distributed laboratory portfolios through master service agreements bundling furniture, installation, and multi-year certification support. Legacy fixed-bench infrastructure creates switching friction that delays replacement cycles.
- Research Labs:Contract research organizations prioritize modular configurations for project-based flexibility.
- Healthcare Facilities:Clinical laboratories specify sterilization-compatible surfaces for diagnostic processing environments.
Pharmaceutical companies drive specification innovation; academic institutions represent the largest installed base.
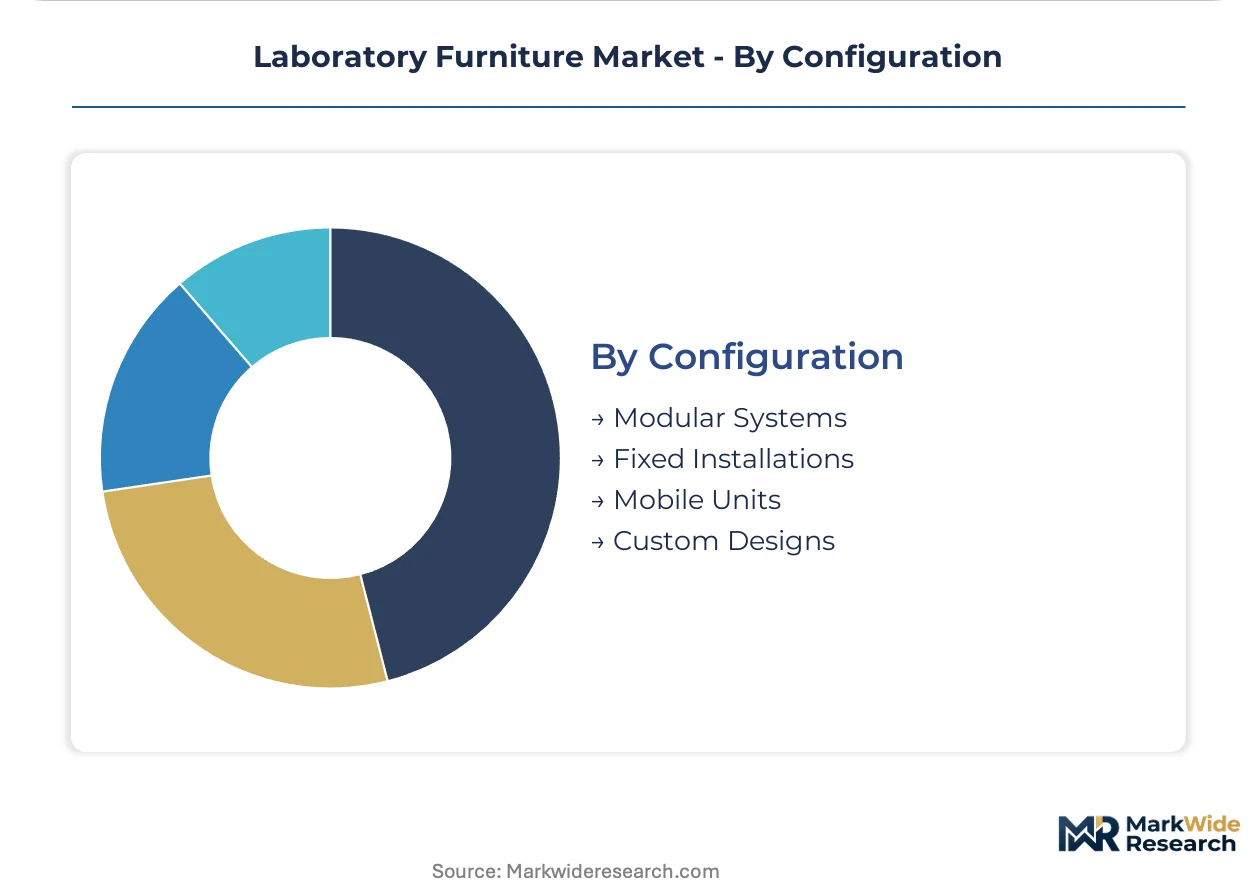
Configuration:
Application urgency separates permanent infrastructure investments from adaptive systems serving project-based research workflows.
- Modular Systems:Precision-engineered components manufactured in Germany enable reconfiguration without facility shutdown. Prefabricated cleanroom pods with pre-installed furniture cut build times by half for Boston and North Carolina contract research organizations.
- Mobile Units:Castor-mounted workstations and storage support shifting project teams and shared instrumentation layouts demanded by multi-purpose research facilities.
- Fixed Installations:Permanent bench and cabinet arrangements serve dedicated protocol environments with stable workflow requirements.
- Custom Designs:Bespoke fabrication addresses non-standard facility dimensions or specialized containment integration.
Modular systems capture specification momentum; mobile units are gaining share fastest in academic consolidation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering and United States biopharmaceutical capacity expansion anchor global laboratory furniture supply chains. Mittelstand manufacturers concentrate high-performance modular system production in southwestern Germany. North American demand clusters around Boston's biotech corridor and North Carolina's Research Triangle Park.
United States
Pharmaceutical developers in Massachusetts and North Carolina commission SEFA 8-compliant containment suites for cell and gene therapy manufacturing. EPA Risk Management Plan mandates force research institutions to replace aging fume hood infrastructure with certified low-flow systems. Boston's biotech corridor drives specification innovation for integrated HVAC monitoring.
Germany
Mittelstand manufacturers supply precision-engineered modular systems to pharmaceutical and academic customers across Europe. REACH restrictions on formaldehyde emissions constrain substrate selection for laboratory furniture exports. Baden-Württemberg's industrial cluster concentrates engineering-intensive cleanroom pod fabrication.
China
Domestic biopharmaceutical manufacturers expand laboratory capacity to support biosimilar and innovative drug development pipelines. NMPA GMP guidelines for pharmaceutical manufacturing constrain furniture surface finishes and cleanability requirements. Yangtze River Delta pharmaceutical parks drive procurement of stainless steel containment systems.
United Kingdom
Academic research consortia consolidate vendor relationships through master service agreements bundling furniture and certification support. MHRA pharmaceutical manufacturing standards influence cleanroom infrastructure specifications. The Oxford-Cambridge arc concentrates demand for modular laboratory configurations serving rotating research teams.
India
Contract research organizations and biosimilar manufacturers commission laboratory infrastructure to serve global pharmaceutical outsourcing contracts. CDSCO pharmaceutical regulations align facility requirements with international GMP standards. Hyderabad and Bangalore pharmaceutical clusters drive demand for cost-optimized stainless steel casework.
Laboratory Furniture Market Key Industry Players
Integrated life sciences conglomerates and specialized Mittelstand fabricators split the market across premium and performance tiers. Consolidation pressure concentrates among mid-scale domestic manufacturers facing raw material volatility and certification timeline compression. Three strategic archetypes dominate: full-platform integrators bundling instrumentation with furniture and services; precision modular specialists engineering reconfigurable containment systems; and regional fabricators competing on custom turnaround and installation proximity. Capacity expansion and service revenue bundling represent the dominant competitive moves as vendors extend relationships beyond initial sale through validation and predictive maintenance contracts.
Within the integrated platform tier, Thermo Fisher Scientific occupies a position exemplifying instrumentation-to-infrastructure bundling. Among specialized German fabricators, Waldner Laboreinrichtungen and Asecos GmbH represent the Mittelstand engineering archetype. Kewaunee Scientific Corporation anchors the North American domestic manufacturing vector.
| Leading Market Players |
|---|
| Labconco Corporation |
| Mott Manufacturing |
| Thermo Fisher Scientific |
| PSA Laboratory Furniture |
| ESCO Group |
| Kewaunee Scientific Corporation |
| Asecos GmbH |
| Diversified Woodcrafts |
| Waldner Laboreinrichtungen |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's Mittelstand engineering cluster concentrates precision modular system production, translating specialized manufacturing scarcity into premium pricing power for containment-integrated furniture across pharmaceutical and academic procurement channels.
Pricing Analysis
Service revenue tiers spanning validation contracts, predictive maintenance, and recertification bundles now drive lifetime value capture in laboratory furniture procurement. Three-tier pricing structure across premium SEFA 8-certified systems, standard institutional-grade configurations, and economy educational installations segments buyer access. Cost compression in the economy tier intensifies because locked university budgets resist nickel and chromium surcharge pass-throughs from domestic fabricators. Academic institutions exhibit highest price sensitivity; biologics manufacturers demonstrate lowest sensitivity due to patent window urgency.
Supply Chain Analysis
Export-control restrictions on advanced HVAC monitoring systems and isolator-integrated workstation technologies limit cross-border equipment flows between precision engineering hubs and biopharmaceutical manufacturing markets. Manufacturing gravity centers on Germany for modular containment systems, the United States for rapid custom fabrication, and China for cost-optimized stainless steel casework. Nickel, chromium, and phenolic resin substrate costs rest on commodity exchange volatility. Single-source vulnerability concentrates in German Mittelstand engineering capacity for cleanroom pod fabrication. Distribution runs through direct vendor relationships with master service agreements displacing project-by-project bidding at R1 research universities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics manufacturing capacity expansion represents a high-growth disruption as cell and gene therapy production timelines compress facility commissioning windows and reconfigure procurement authority structures across pharmaceutical quality departments.
For Market Incumbents: Pre-empt modular system commoditization by anchoring proprietary HVAC monitoring integration and isolator workstation bundling. Backward integration into captive stainless steel fabrication mitigates nickel and chromium margin compression from commodity volatility. Certification investment in SEFA 8 and NSF/ANSI 49 validation capabilities creates switching friction against mid-scale domestic competitors.
For New Entrants and Emerging Players: Build out cell therapy manufacturing isolator-integrated workstation offerings as the most penetrable white-space application, targeting contract research organizations in Boston and North Carolina's Research Triangle Park with prefabricated cleanroom pod partnerships. Geographic expansion into Indian biosimilar clusters via Hyderabad and Bangalore pharmaceutical parks offers secondary entry velocity.
For Investors and Strategic Acquirers: Long-term, this sits as a service-revenue compounding play because validation, recertification, and predictive maintenance contracts extend vendor relationships beyond initial sale and generate recurring cash flows. Acquisition targets should display installed base scale across multi-campus R1 university portfolios paired with captive certification capabilities. The signal to watch is EPA Risk Management Plan enforcement intensity accelerating fume hood replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Revenue Bundling | Validation and predictive maintenance contracts extend vendor relationships beyond initial equipment sale at pharmaceutical quality departments. |
| Modular System Integration | Prefabricated cleanroom pods with pre-installed furniture cut facility build times by half for Boston and North Carolina contract research organizations. |
| Low-Flow Fume Hood Development | IRA energy efficiency incentives drive specification of heat recovery and LED-integrated containment systems in Massachusetts and California. |
| Backward Integration | Captive stainless steel fabrication mitigates nickel and chromium input cost volatility compressing margins for domestic university suppliers. |
| Master Service Agreements | University procurement offices consolidate vendor relationships across distributed laboratory portfolios through multi-year certification support contracts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory facilities directors, pharmaceutical quality assurance managers, university procurement officers, and environmental health and safety leads. Secondary validation drew from EPA Risk Management Plan filings, SEFA certification registries, FDA GMP guidance documents, and IRA energy efficiency incentive program disclosures. Bottom-up triangulation across equipment shipment records and top-down reconciliation against facility construction permits anchored market sizing.
Calibration against historical SEFA 8 adoption curves and biologics manufacturing capacity announcements refined projection parameters across the analysis window. Segmentation modeling incorporated product type, material substrate, end-user category, and configuration flexibility dimensions. CAGRs derived from regression analysis of replacement cycle compression, regulatory mandate timing, and modular construction penetration rates. Forecast inputs included pharmaceutical patent cliff schedules and academic capital campaign cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Mittelstand engineering specialists or integrated life sciences conglomerates would shift outcomes beyond modeled ranges. Material shifts in EPA enforcement intensity, REACH substrate restriction scope, or nickel and chromium commodity volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Human Milk Analyzers Market