
 Laboratory Ovens Market | 2026-2036
Laboratory Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Ovens Market Intelligence
Good Manufacturing Practices (GMP) compliance for equipment validation is expanding the total cost of ownership for end users. This environment benefits established vendors like Thermo Fisher Scientific, which leverages its extensive service network for validation support. Niche players such as Carbolite Gero specialize in high-specification ovens for material science, while Memmert differentiates its products through precise temperature control technology for sensitive pharmaceutical applications.
Laboratory ovens are thermal convection instruments that provide uniform temperature environments for heating, drying, and sterilizing samples. These devices operate within precise temperature ranges, often from ambient to over 300°C, with chamber uniformity being a critical performance parameter. Forced air convection models lead the market due to superior heat distribution, essential for sensitive applications. Pharmaceutical testing and material testing applications are expanding quickly, fueled by rigorous quality and safety standards.
International standards such as ISO 9001 for quality management and specific electrical safety certifications like UL (in the United States) and CE marking (in Europe) govern manufacturing. Regulations from bodies like the FDA and EMA dictate equipment validation protocols, directly influencing design and documentation requirements for life sciences applications. Future competitive advantage will hinge on integrating advanced data logging and network connectivity features to meet stringent traceability demands.
Market Dynamics
The central dynamic shaping the laboratory ovens market is the escalating requirement for stringent performance validation under GMP, which conflicts with intense pressure on laboratories to reduce energy consumption and operational costs, as mandated by frameworks like ISO 50001.
Growth Catalysts
- Biopharmaceutical Expansion:Rapid growth in China's biopharmaceutical manufacturing hubs and contract research organizations necessitates investment in ovens for stability testing and process development, adhering to NMPA guidelines.
- Material Science Research:The development of advanced polymers and composites for the aerospace and automotive sectors requires high-specification ovens capable of precise temperature ramping and uniformity for material qualification.
- Stringent Food Safety Testing:Regulations from bodies like the EFSA and FDA for microbial and shelf-life testing are expanding the use of laboratory ovens in the food and beverage quality control sector.
Market Restraints
- Total Cost of Ownership:The mandatory validation, calibration, and documentation services required for GMP compliance significantly inflate the total cost of ownership beyond the initial hardware price, creating budget barriers for smaller labs.
- Specialized Component Sourcing:Manufacturers depend on a concentrated global supply chain for critical components like high-precision PID controllers and platinum resistance thermometers, creating vulnerability to supply disruptions.
- Energy Efficiency Demands:The high energy consumption of forced convection and high-temperature models conflicts with corporate and public sector sustainability mandates, such as the EU Green Deal, limiting adoption in some institutions.
Strategic Opportunities
- Network Connectivity and Data Logging:Integrating IoT capabilities for remote monitoring, automated data logging, and seamless LIMS integration addresses the growing demand for data integrity and traceability required by 21 CFR Part 11.
- Battery Material Testing:The electric vehicle industry's expansion creates a new application segment for specialized ovens designed for battery cell and module drying, aging, and thermal abuse testing.
- Service and Validation Contracts:Offering comprehensive, multi-year service contracts that bundle installation, operational qualification (OQ), performance qualification (PQ), and recalibration can create recurring revenue streams.
Industry Challenges
- Complex Validation Processes:End users face significant operational delays due to the lengthy and resource-intensive process of completing IQ/OQ/PQ documentation, which can stall the commissioning of new laboratory facilities.
- Software Interoperability:Ensuring that proprietary oven control software can securely and reliably interface with a diverse ecosystem of third-party Laboratory Information Management Systems (LIMS) is a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Ovens Market |
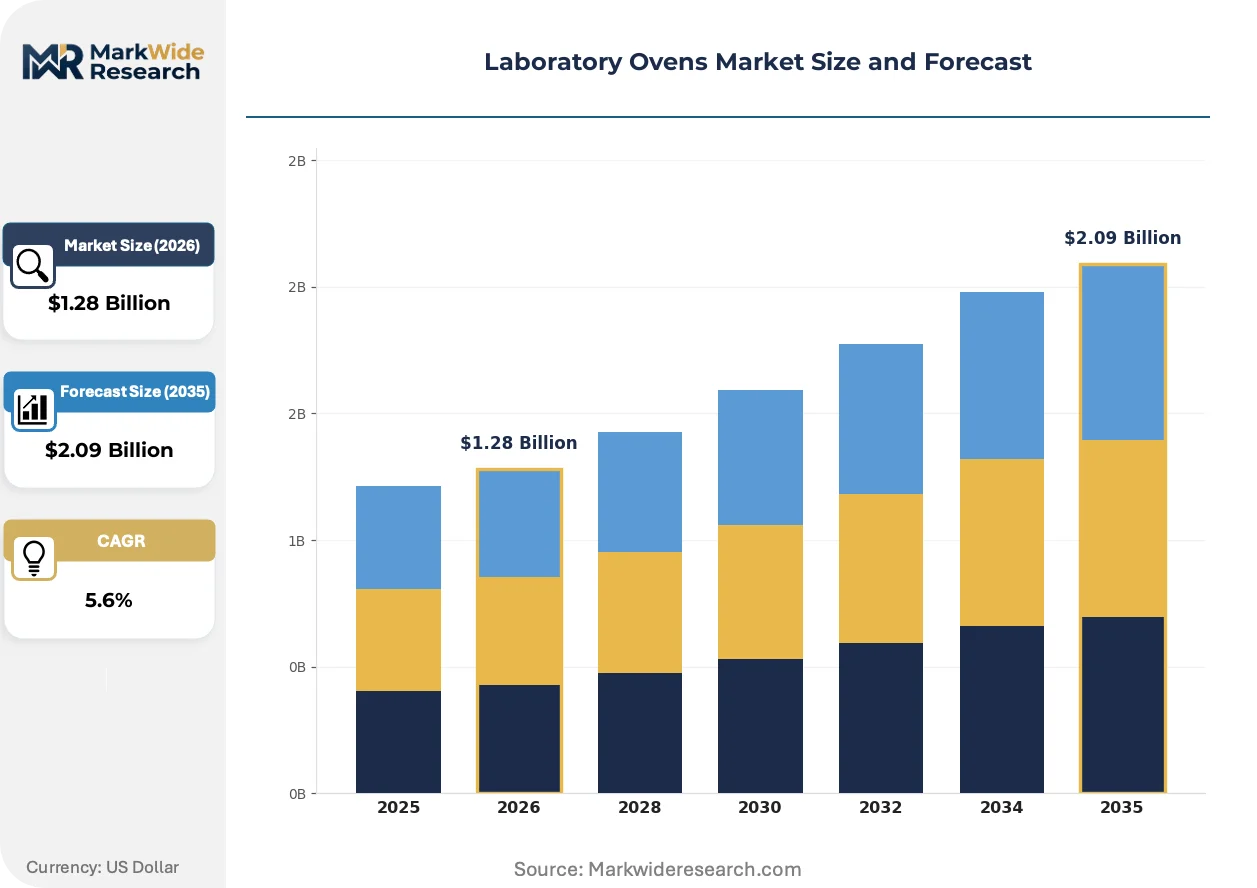
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.09 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gravity Convection, Forced Air Convection, Vacuum Ovens, Infrared Ovens Technology: Electric, Gas Powered, Hybrid, Solar Powered Application: Pharmaceutical Testing, Food Quality Analysis, Material Testing, Electronics Manufacturing End User: Research Institutions, Quality Control Laboratories, Manufacturing Facilities, Diagnostic Centers |
| Companies Covered | Quincy Lab, Yamato Scientific America, Thermo Fisher Scientific, Carbolite Gero, Memmert, Despatch, Sheldon Manufacturing, Tempo Instruments, Grieve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Ovens Market Strategic Shifts & Innovations
The laboratory oven is evolving from a standalone hardware unit into an intelligent, connected node within a data-driven laboratory ecosystem. This shift is driven by the convergence of advanced sensor technology, stringent regulatory demands for data integrity, and a focus on operational efficiency.
Advanced control systems featuring integrated multi-point sensors are becoming standard. These systems monitor temperature uniformity, energy consumption, and door openings with high granularity. Pharmaceutical and materials science laboratories are the primary adopters, seeking to eliminate process variability. This integration of sensing and control **is unifying** hardware performance with auditable data generation, creating a single source of truth for quality and compliance reporting.
Regulatory frameworks focused on energy efficiency are influencing equipment design. The EU Green Deal, alongside standards like ISO 50001, pressures manufacturers to develop ovens with improved insulation, more efficient heating elements, and low-power standby modes. This directly impacts product development for ovens sold into European academic and government research institutions, which increasingly use sustainability criteria in procurement decisions.
A preference for lifecycle service agreements is altering purchasing behavior. End users in regulated sectors like pharmaceuticals are moving away from simple capital purchases toward bundled solutions that include installation, validation, preventative maintenance, and calibration services. This disrupts the traditional distributor model focused on hardware sales, particularly in North America and Western Europe, where GMP compliance is paramount.
Laboratory Ovens Market Segmentation
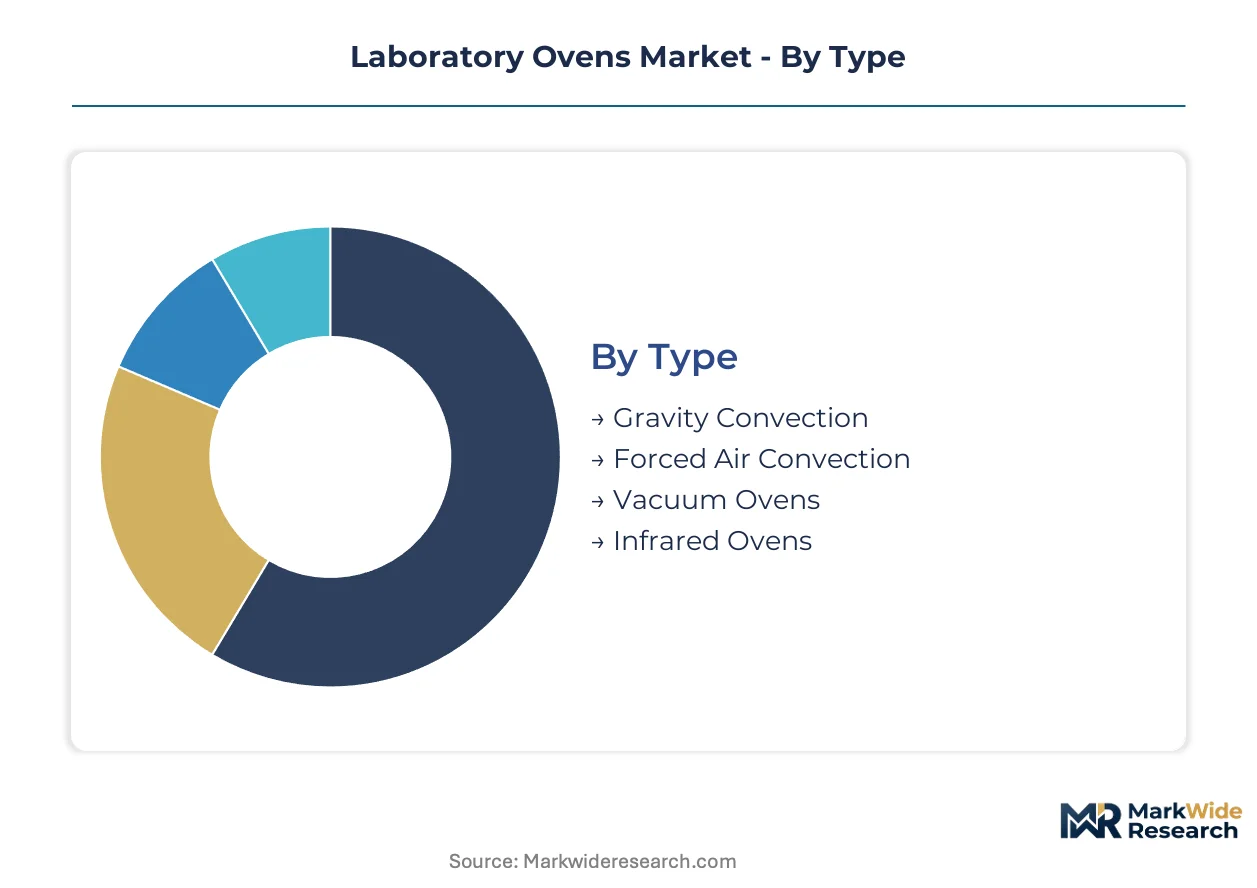
Understanding the distinct segments within the laboratory ovens market is crucial for identifying targeted growth avenues and addressing specific end-user needs. Varied technical specifications, application requirements, and operational scales significantly influence product design and procurement decisions across the industry.
Type:
The functional design and heat transfer mechanism define distinct oven types within the market, each suited for particular laboratory processes and sample characteristics.
- Forced Air Convection:These ovens utilize internal fans to circulate heated air, ensuring superior temperature uniformity and rapid heat distribution across the chamber. Demand concentrates in pharmaceutical testing and material science applications, driven by rigorous quality control and process validation needs.
- Vacuum Ovens:Operating under reduced pressure, these ovens facilitate drying and degassing at lower temperatures, preventing oxidation and preserving sensitive samples. Demand is strong in electronics manufacturing and advanced battery material testing, where delicate components require precise, oxygen-free processing.
- Gravity Convection:Relying on natural air circulation, these ovens offer a gentler drying environment, suitable for general laboratory tasks and non-critical drying.
- Infrared Ovens:Utilizing electromagnetic radiation, these ovens provide rapid, direct heating to sample surfaces, primarily used for quick drying or curing processes.
Mature deployment sits with Gravity Convection. Newer deployment is concentrated in Forced Air Convection.
Technology:
Operational costs and specific energy requirements differentiate laboratory ovens by their underlying heating technology, impacting environmental footprint and utility expenses.
- Electric:These ovens employ electrical resistance heaters for precise temperature control and clean operation, making them ubiquitous across research and quality control laboratories. Demand concentrates in pharmaceutical manufacturing and academic research institutions, valuing accuracy and environmental cleanliness.
- Hybrid:Combining two energy sources, such as electric with gas or solar, these systems aim for optimized performance, energy efficiency, or operational redundancy. Demand is emerging in large-scale manufacturing facilities and institutions prioritizing reduced energy consumption and sustainability mandates like the EU Green Deal.
- Gas Powered:Utilizing natural gas or propane, these ovens provide high heating capacity, often found in industrial settings requiring rapid temperature ramp-up or large volumes.
- Solar Powered:Integrating photovoltaic panels, these ovens reduce reliance on grid electricity, offering a sustainable option for remote laboratories or those with strong green initiatives.
The electric technology segment maintains market dominance, while hybrid solutions are expanding most quickly.
Application:
The intended use case dictates the necessary performance parameters and regulatory adherence for laboratory ovens, influencing design and validation requirements.
- Pharmaceutical Testing:This application involves stability studies, sterility assurance, and drying of active pharmaceutical ingredients, demanding high precision and GMP compliance. Demand concentrates in biopharmaceutical manufacturing hubs and contract research organizations, driven by NMPA and EMA guidelines.
- Material Testing:Encompassing polymer curing, composite drying, and heat treatment of metals, this segment requires ovens with precise temperature ramping and uniformity for material qualification. Demand is strong within the aerospace and automotive sectors for advanced material development and quality control.
- Food Quality Analysis:This includes moisture content determination, shelf-life studies, and microbial testing, essential for compliance with regulations from bodies like EFSA and FDA.
- Electronics Manufacturing:Applications involve component drying, circuit board curing, and outgassing, requiring precise temperature control to prevent damage to sensitive components.
Pharmaceutical testing represents the largest application segment, with material testing showing the steepest expansion trajectory.
End User:
Diverse organizational structures and operational scales shape end-user requirements for laboratory oven solutions, from basic research to high-volume manufacturing.
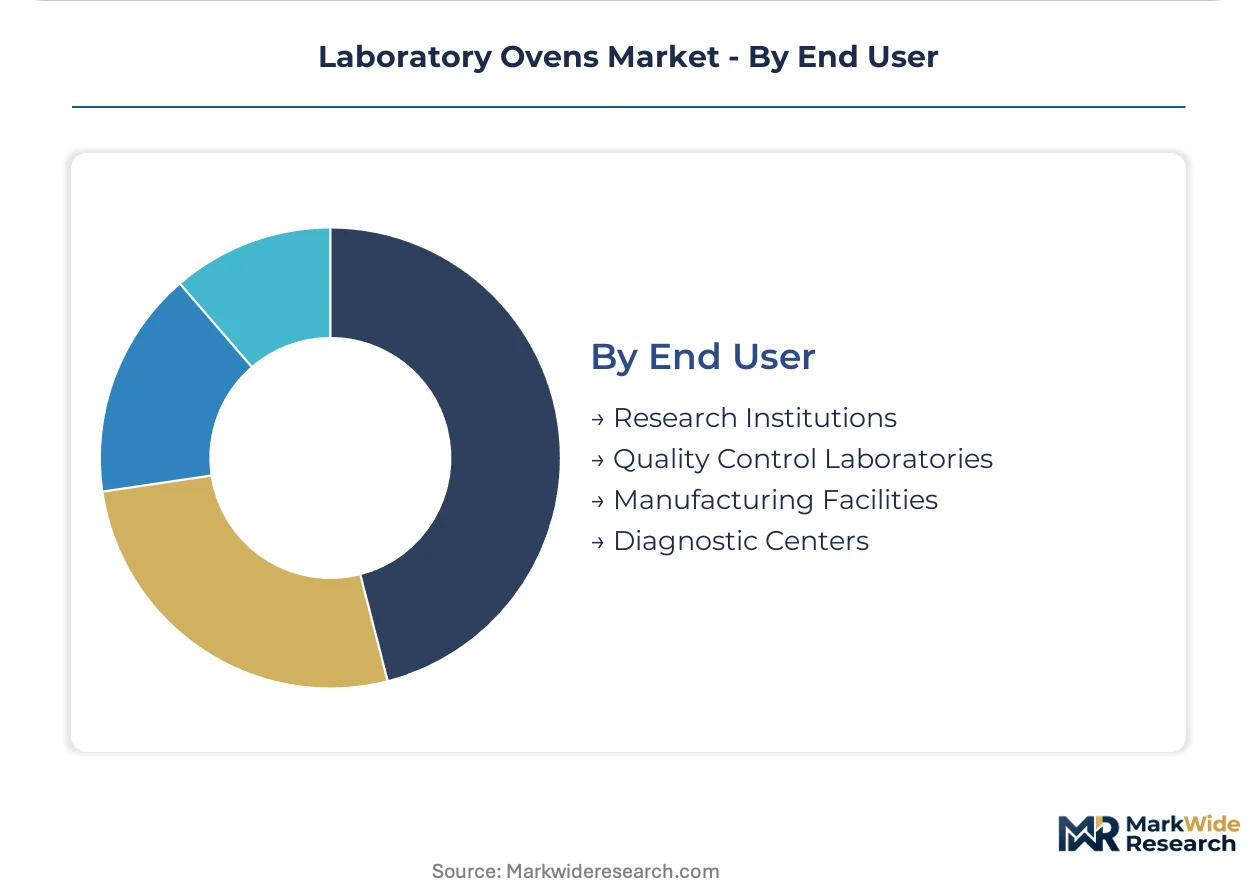
- Research Institutions:This segment includes academic laboratories, government research facilities, and corporate R&D departments requiring versatile and precise instruments for diverse experimental needs. Demand concentrates in universities and national laboratories for fundamental and applied scientific investigations.
- Manufacturing Facilities:Encompassing industrial production lines, pilot plants, and scale-up operations, these facilities require high-throughput, robust, and validated equipment for process development and quality control. Demand is significant in biopharmaceutical production and advanced materials fabrication.
- Quality Control Laboratories:This segment comprises independent testing labs and in-house QC units, focusing on routine compliance verification and product quality assurance.
- Diagnostic Centers:Medical laboratories and pathology clinics utilize ovens for sample preparation, sterilization of equipment, and drying of biological samples.
Research institutions remain foundational purchasers, while manufacturing facilities are rapidly increasing their equipment investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biopharmaceutical manufacturing hubs, particularly those supported by NMPA guidelines, significantly drive demand for laboratory ovens. These zones foster rapid growth in stability testing and process development. Such concentrated industrial development requires substantial investment in validated equipment.
United States
Demand for laboratory ovens in the United States stems from extensive pharmaceutical R&D and advanced material testing. FDA regulations for equipment validation directly influence procurement in life sciences. Boston's biotech corridor consistently invests in high-precision ovens for drug discovery and quality control.
Germany
Germany's robust pharmaceutical sector and advanced engineering industries create strong demand for precise laboratory ovens. CE marking and ISO 50001 standards guide product design and energy efficiency requirements. The Rhine-Main region, with its chemical and pharmaceutical clusters, shows sustained equipment investment.
China
China's expanding biopharmaceutical manufacturing hubs and material science research fuel significant oven demand. NMPA guidelines for process development and stability testing are critical for market access. Shanghai's Zhangjiang Hi-Tech Park drives investments in ovens for drug development and testing.
Japan
Japan's strong focus on advanced materials and high-tech electronics necessitates specialized laboratory ovens. METI policies encourage innovation in manufacturing processes and quality assurance. The Kansai region's electronics and materials research centers frequently upgrade their thermal processing capabilities.
India
India's growing pharmaceutical manufacturing and food safety testing sectors require increased laboratory oven capacity. CDSCO regulations for drug quality control and FSSAI standards for food analysis are paramount. Hyderabad's Pharma City drives significant equipment purchases for drug stability and process validation.
Laboratory Ovens Market Key Industry Players
United States producers anchor one tier, specializing in high-compliance solutions for biopharmaceuticals, while European specialists hold strong positions in energy-efficient and precision models. The market exhibits a tiered structure, from large, diversified instrument manufacturers to niche providers of high-specification equipment for advanced research. Strategic archetypes include integrated solution providers, specialized technology innovators, and regional value-segment suppliers. Portfolio diversification and strategic partnerships are dominant competitive moves among established players seeking to expand application reach.
Specialists in high-compliance and precision applications include Thermo Fisher Scientific, which exemplifies the integrated solution provider archetype, leveraging extensive service networks. Carbolite Gero, a UK-based manufacturer, represents the niche provider of high-specification ovens for material science. Memmert GmbH + Co. KG, a German entity, anchors the precision control segment, differentiating products through advanced temperature technology for sensitive pharmaceutical uses. These companies consistently focus on meeting stringent regulatory demands and expanding their global footprint through service excellence. Their offerings target segments requiring auditable data generation and robust validation support.
| Leading Market Players |
|---|
| Quincy Lab |
| Yamato Scientific America |
| Thermo Fisher Scientific |
| Carbolite Gero |
| Memmert |
| Despatch |
| Sheldon Manufacturing |
| Tempo Instruments |
| Grieve Corporation |
| Others |
Cost & Logistics Intelligence
The global platinum price index significantly influences laboratory oven costs, cascading through the supply chain into distinct pricing tiers for precision components. This commodity benchmark directly impacts manufacturing expenses for high-accuracy temperature sensors.
Pricing Analysis
Lead-time-driven pricing premiums apply to highly customized laboratory ovens requiring specialized component sourcing, while standard models often utilize spot inventory discounts. The dominant pricing structure remains per-unit transactional, though bundled service contracts gain traction in regulated sectors. Price differentiation stems from certification level (e.g., GMP compliance) and the degree of temperature precision. Pricing pressure stems from increased competition in the general-purpose oven segment, driven by regional manufacturers. Research institutions and smaller quality control laboratories are most price-sensitive, while biopharmaceutical manufacturers prioritize validated performance over initial cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by end-users, especially for high-precision PID controllers and platinum resistance thermometers. Geographic supply concentration for these specialized components centers on China, Germany, and Japan. Manufacturers depend on these regions for high-grade insulation materials and advanced sensor technology. A key structural risk is single-source vulnerability for highly specialized microprocessors. Distribution runs through a network of specialized laboratory equipment distributors and direct sales channels, particularly for integrated solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a vertical-integration race, with players actively pursuing in-house development of advanced control software to enhance data integrity and LIMS interoperability.
For Market Incumbents: Anticipate the need to continuously invest in advanced data logging and network connectivity features to meet evolving 21 CFR Part 11 requirements. Secure proprietary software integration serves as a key defensive move against emerging software-centric competitors. Consolidating market share through comprehensive service and validation contracts protects against margin erosion from lower-cost hardware. The lever for incumbents is investing in next-generation sensor technology to improve chamber uniformity and energy efficiency, addressing sustainability mandates like the EU Green Deal.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants to differentiate through highly energy-efficient oven designs. White-space targets include specialized ovens for battery material testing within the electric vehicle sector and modular solutions for smaller contract research organizations. The most penetrable segment is general laboratory applications in developing regions, where basic functionality combined with robust local support can gain traction. A specific go-to-market angle involves offering subscription-based models for validation and maintenance services, reducing upfront costs for budget-conscious labs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists in Germany with strong intellectual property in precise temperature control. Long-term viability over a five-to-ten-year window favors companies that can demonstrate consistent innovation in data traceability and energy efficiency. Acquisition target archetypes include niche providers of high-specification ovens for material science or firms with established IoT integration platforms. The signal to watch is the increasing stringency of global pharmaceutical data integrity regulations, driving demand for auditable solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate IoT for Data Logging | Enhance traceability for regulatory compliance in pharmaceutical testing. |
| Develop Energy-Efficient Models | Meet sustainability mandates in European academic and government research institutions. |
| Expand Service & Validation Contracts | Create recurring revenue streams in regulated biopharmaceutical sectors. |
| Target Battery Material Testing | Capture growth in the electric vehicle industry's material qualification. |
| Strategic Partnerships for LIMS Integration | Improve interoperability with laboratory information management systems for end-users. |
Research Approach
Industry journals, technical specifications from leading manufacturers, and regulatory guidelines from the FDA and EMA formed the secondary backbone of this analysis. This was combined with primary interviews with laboratory managers, procurement specialists, and R&D directors in biopharmaceutical and material science sectors. Further validation came from discussions with equipment engineers and quality control officers. The approach utilized both bottom-up market sizing from specific application data and top-down validation against overall industry expenditure trends.
Historical trendline analysis across key market segments provided the foundation for projecting future growth trajectories. The analysis modeled segmentation dimensions including oven type, heating technology, application, end-user, and regional regulatory adherence. Compound annual growth rates were derived from a multi-variant regression analysis, incorporating demand drivers such as biopharmaceutical R&D expenditure and material science innovation. Key forecast inputs included projected investments in laboratory infrastructure and evolving energy efficiency standards across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for rapid IoT integration or novel heating technologies would alter the outlook. Forecasts reflect assumptions regarding stable geopolitical conditions and consistent regulatory enforcement. Specific risk factors, such as significant supply chain disruptions for critical components or unforeseen shifts in energy costs, could revise these projections. A model refresh is warranted upon material change in global biopharmaceutical investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Laboratory Temperature Control Units Market