
 Global Graduated Cylinder Market | 2026-2036
Global Graduated Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graduated Cylinder Market Analysis
Market Context
Modular cylinder kits are decoupling single-unit purchasing from bundled accessory sets, giving buyers flexibility to source stands, brushes, and stoppers separately. Thermo Fisher Scientific leverages its distribution breadth to sustain laboratory channel dominance across North America and Europe. DURAN Group anchors premium borosilicate positioning through German manufacturing heritage and DIN-standard compliance. Vitlab GmbH competes on polypropylene disposables for high-throughput pharmaceutical quality-control environments.
Technical Definition and Segmentation
A graduated cylinder is a tall, narrow cylindrical vessel with volumetric markings etched or printed along its side, designed to measure liquid volumes with typical accuracy within one percent of nominal capacity for Class B and tighter tolerances for Class A certified instruments. Its primary commercial purpose spans quantitative liquid transfer, solution preparation, and density determination in analytical chemistry, pharmaceutical manufacturing, and educational instruction. Borosilicate glass commands the premium tier due to thermal shock resistance and chemical inertness, while polypropylene displaces glass in educational and field applications where breakage risk outweighs precision demands. The 100 mL and 1000 mL capacity bands concentrate volume procurement in pharmaceutical quality-control and industrial pilot-plant settings respectively, with smaller sizes retaining steady replacement cycles in academic laboratories.
Regulatory Environment and Outlook
ISO 4788 dimensional standards, REACH substance restrictions on borosilicate additives, and FDA 21 CFR Part 211 equipment qualification requirements collectively govern material selection, calibration protocols, and market access for graduated cylinder suppliers serving regulated industries. Germany's national metrology institute PTB and China's NIM enforce traceable calibration hierarchies that OEMs must satisfy for pharmaceutical and forensic laboratory contracts. Stakeholders should monitor tightening EU MDR in vitro diagnostic equipment rules and China's GB/T metrology standard revisions, as these frameworks will determine which material grades and certification levels gain preferential procurement status in the highest-margin end-use segments.
Market Dynamics
ISO 17025 accreditation mandates are compressing replacement cycles for Class A certified instruments, forcing laboratories to retire older volumetric glassware ahead of physical end-of-life. This structural pressure favors suppliers with embedded calibration services and traceable metrology hierarchies.
Growth Catalysts
- REACH chemical safety rules:European ECHA substance restrictions on borosilicate additives are accelerating premium-grade cylinder turnover as laboratories pre-empt compliance retrofits.
- Pharmaceutical quality-control expansion:Biologics manufacturing in Germany, China, and the United States is driving volumetric analysis infrastructure buildouts with strict DIN-standard compliance requirements.
- Polypropylene displacement:High-throughput screening workflows are rewriting material specifications in educational and field applications where breakage risk dominates precision tradeoffs.
Market Restraints
- Raw material concentration:Specialty borosilicate glass feedstock concentrates among German and Chinese suppliers, exposing procurement to geopolitical friction and energy cost volatility.
- Calibration infrastructure scarcity:PTB-traceable calibration hierarchies require capital-intensive metrology labs that smaller OEMs cannot replicate, consolidating contract access.
- Disposable cost compression:Single-use polypropylene alternatives face margin pressure from commodity resin price swings and Asian manufacturing overcapacity.
Strategic Opportunities
- Modular kit unbundling:Separate sourcing of stands, brushes, and stoppers from cylinder units opens direct-to-laboratory e-commerce channels bypassing traditional distribution.
- EU MDR in vitro diagnostic alignment:Tightening medical device regulations create premium positioning for graduated cylinders certified as accessory equipment under diagnostic equipment qualification protocols.
- China GB/T metrology revision:National Institute of Metrology standard updates favor domestic suppliers with integrated NIM-traceable calibration services.
Industry Challenges
- Metrology talent scarcity:ISO 17025 assessor certification programs face enrollment gaps, delaying laboratory accreditation timelines and freezing procurement decisions.
- Legacy glassware integration:Automated liquid handling platforms require dimensional tolerances that vintage borosilicate inventories cannot satisfy, forcing write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graduated Cylinder Market |
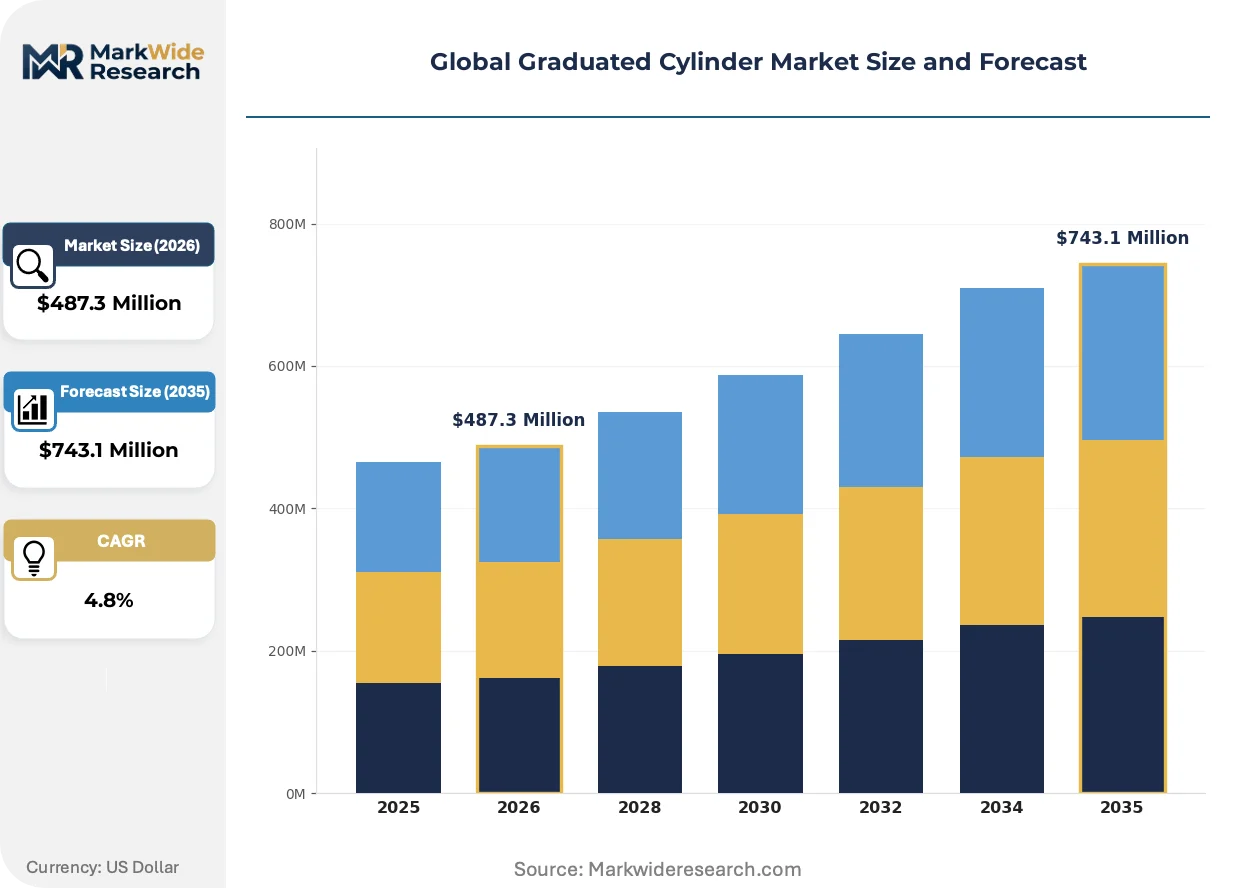
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Glass, Acrylic, Borosilicate Capacity: 10 mL, 50 mL, 100 mL, 1000 mL Feature: Unbreakable, Graduated, Heavy-Duty, Stackable End User: Laboratories, Educational Institutions, Pharmaceuticals, Research Facilities |
| Companies Covered | ELE International, Atlas Glassworks, Thermo Fisher Scientific, ProSicTech Pty Ltd, Wilmad-LabGlass, DURAN Group, Controls, Indigo Instruments, Vitlab GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graduated Cylinder Market Emerging Trajectories
Laser-etched volumetric markings and embedded RFID calibration certificates are compressing the traditional distinction between consumable glassware and capital equipment. These innovations reshape how laboratories manage asset lifecycle and compliance documentation.
Digital volumetric systems with integrated meniscus detection and automated reading are rewriting precision workflows in pharmaceutical quality-control environments. Thermo Fisher Scientific and DURAN Group are embedding these sensors into premium cylinder lines. The technology compresses technician training requirements while tightening measurement repeatability beyond Class A tolerances.
EU MDR in vitro diagnostic equipment rules are elevating accessory qualification requirements for graduated cylinders used in diagnostic manufacturing. EMA-aligned notified bodies now demand design dossiers and post-market surveillance for volumetric instruments previously treated as unregulated consumables. German and Swiss diagnostic OEMs are consolidating supplier bases to reduce qualification burden.
Academic laboratories are fragmenting purchasing authority between principal investigators and centralized procurement offices, compressing order sizes while elevating SKU complexity. E-commerce platforms with real-time DIN-standard filtering are displacing catalog-based distributor relationships. This pattern concentrates in United States research universities with decentralized grant funding structures.
Global Graduated Cylinder Market Segmentation
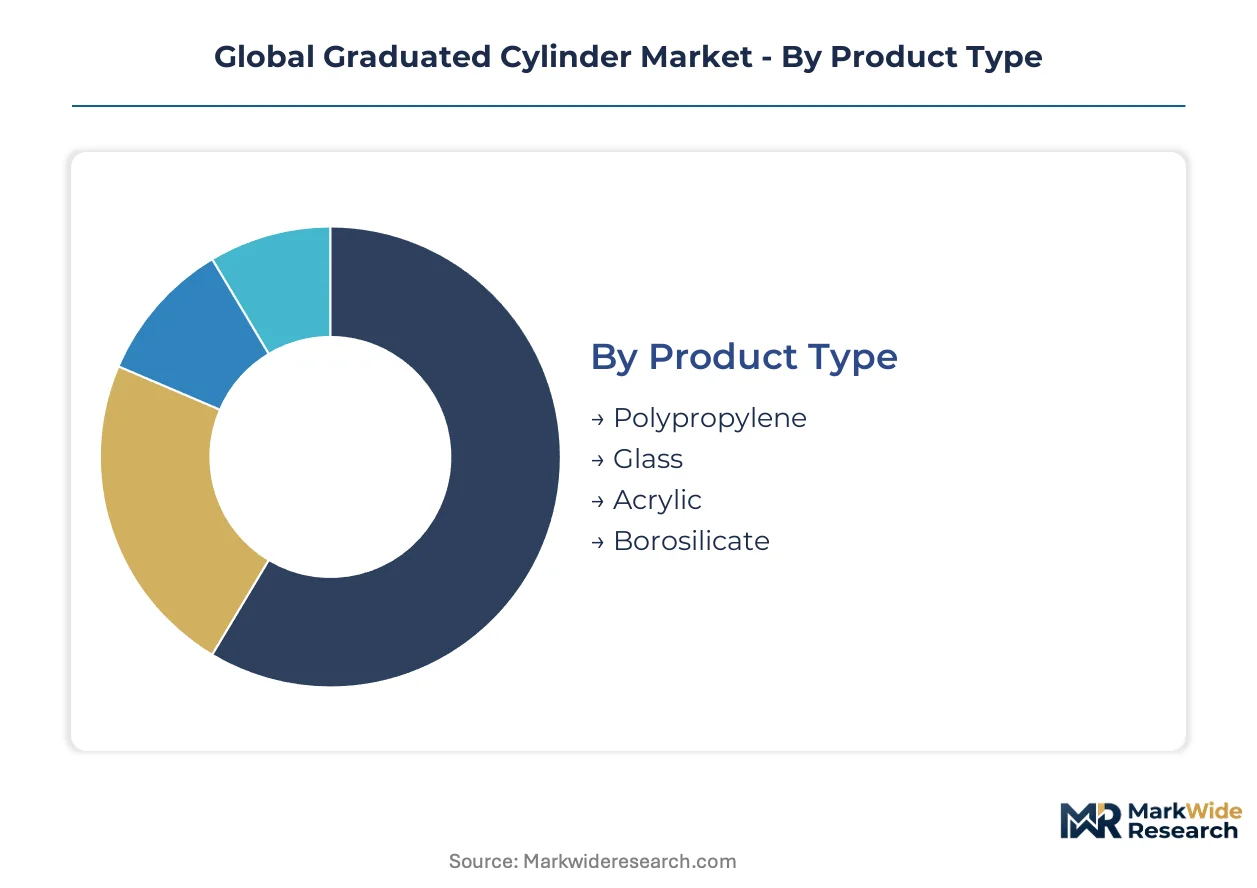
Graduated cylinder procurement patterns diverge sharply across material grades, capacity bands, and certification tiers. Laboratories in Germany, China, and the United States drive premium borosilicate demand while educational buyers in emerging markets compress unit economics through polypropylene substitution.
Product Type:
Specialty borosilicate glass feedstock concentrates among German and Chinese suppliers, exposing procurement to energy cost volatility and geopolitical friction. Raw material scarcity elevates pricing power for integrated manufacturers with captive melting capacity.
- Borosilicate:Thermal shock resistance and chemical inertness define this premium tier. Pharmaceutical quality-control laboratories in Germany and the United States specify DIN-standard compliant instruments for volumetric analysis under ISO 17025 protocols.
- Polypropylene:High-throughput screening workflows favor this disposable alternative. Educational institutions and field applications across China and India accept precision tradeoffs to eliminate breakage risk and reduce replacement logistics.
- Glass:Soda-lime compositions serve cost-sensitive academic markets with moderate thermal stability requirements.
- Acrylic:Transparent polymer cylinders address visual demonstration needs in secondary education settings where chemical resistance demands remain minimal.
Borosilicate absorbs the bulk of installed capacity in regulated industries; polypropylene is expanding most quickly in high-throughput environments.
Capacity:
Volume specifications cluster around analytical workflow requirements, with smaller sizes dominating replacement cycles and larger units anchoring pilot-plant infrastructure.
- 100 mL:The workhorse specification for pharmaceutical quality-control titrations and buffer preparations. Biologics manufacturing expansion across Germany, China, and the United States sustains steady procurement velocity for Class A certified instruments.
- 1000 mL:Industrial pilot-plant settings and bulk solution preparations drive demand for this capacity band. DIN-standard compliance remains mandatory for contract manufacturing organizations serving EMA-regulated markets.
- 10 mL:Micro-volume analytical procedures and pediatric pharmaceutical formulations utilize this compact specification.
- 50 mL:Intermediate capacity serves educational demonstrations and routine quality-control sampling with balanced handling ergonomics.
100 mL cylinders command the highest unit volumes; 1000 mL instruments deliver the steepest margin expansion.
Feature:
Functional differentiation increasingly determines procurement specifications as laboratories automate liquid handling workflows and compress training timelines.
- Graduated:Laser-etched volumetric markings with embedded RFID calibration certificates now compress the distinction between consumable glassware and capital equipment. Thermo Fisher Scientific and DURAN Group embed these features in premium lines.
- Unbreakable:Polypropylene and composite polymer constructions address field deployment and educational safety mandates. Chinese manufacturing clusters exploit resin cost advantages to serve price-sensitive Asian markets.
- Heavy-Duty:Reinforced wall thickness and protective bases extend service life in industrial environments with elevated mechanical stress.
- Stackable:Nesting geometries optimize storage density for high-SKU inventory management in centralized university procurement systems.
Graduated instruments with digital integration absorb premium pricing; unbreakable alternatives gain share fastest in educational and field segments.
End User:
Procurement authority fragmentation between principal investigators and centralized purchasing offices reshapes order patterns across institutional categories.
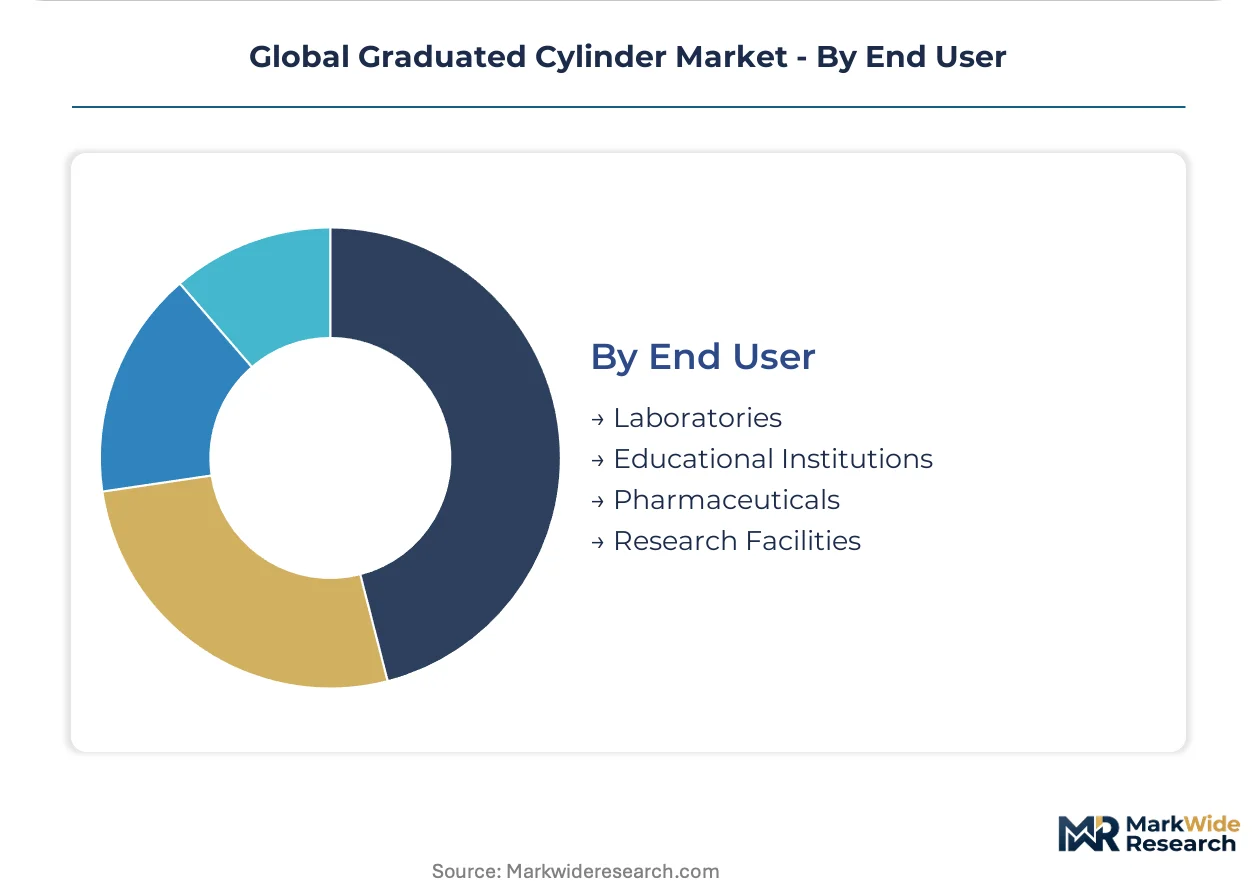
- Pharmaceuticals:Biologics manufacturing and biosimilar development in Germany, China, and the United States drive volumetric analysis infrastructure buildouts. FDA 21 CFR Part 211 equipment qualification requirements and EMA-aligned notified body demands consolidate supplier bases.
- Laboratories:ISO 17025 accreditation mandates compress replacement cycles for Class A certified instruments. PTB-traceable calibration hierarchies in Germany and NIM-traceable services in China determine contract access.
- Educational Institutions:Decentralized grant funding structures in United States research universities fragment purchasing authority. E-commerce platforms with real-time DIN-standard filtering displace catalog-based distributor relationships.
- Research Facilities:Academic and government laboratories balance precision requirements against budget constraints through mixed material procurement strategies.
Pharmaceutical end users concentrate premium demand; educational institutions represent the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical zones in Germany, China's Yangtze River Delta industrial corridor, and United States research clusters concentrate graduated cylinder procurement. Tax incentives for biologics manufacturing and metrology infrastructure investments drive demand concentration in these three markets.
Germany
Biologics manufacturing expansion in Baden-Württemberg and Bavaria sustains premium borosilicate demand. PTB traceability requirements under DIN standards elevate compliance costs for imported instruments. The Rhine-Main biotech corridor concentrates contract manufacturing organizations serving EMA-regulated markets.
China
National Institute of Metrology (NIM) standard revisions favor domestic suppliers with integrated calibration services. Shanghai and Suzhou pharmaceutical clusters drive 1000 mL cylinder procurement for pilot-plant infrastructure. GB/T metrology updates tighten dimensional tolerances for export-oriented manufacturers.
United States
FDA 21 CFR Part 211 equipment qualification requirements compress supplier qualification timelines. Greater Boston and San Francisco Bay Area biotech clusters fragment purchasing authority between principal investigators and centralized procurement offices. Decentralized grant funding structures elevate e-commerce platform penetration.
India
CDSCO manufacturing compliance deadlines for pharmaceutical exports accelerate quality-control laboratory buildouts. Hyderabad and Ahmedabad API manufacturing clusters drive polypropylene displacement in high-throughput screening workflows. BIS certification requirements for laboratory equipment tighten import specifications.
Japan
METI subsidies for domestic pharmaceutical manufacturing reshore precision glassware procurement. Osaka and Kansai chemical clusters maintain preference for Class A certified instruments under JIS standards. PMDA alignment with ICH Q7 guidelines elevates equipment qualification documentation requirements.
Global Graduated Cylinder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and certification tiers. Thermo Fisher Scientific leverages distribution breadth against DURAN Group's German manufacturing heritage. Three archetypes dominate: integrated borosilicate manufacturers with captive melting capacity, polypropylene disposable specialists serving high-throughput environments, and calibration-service-embedded distributors. Geographic expansion and modular kit unbundling represent the dominant competitive vectors.
Among German-anchored precision glassware specialists, DURAN Group and Vitlab GmbH exemplify divergent material-grade strategies. Thermo Fisher Scientific occupies a position bridging premium instrumentation with distribution scale. These three entities represent the structural tension between manufacturing heritage and channel dominance.
| Leading Market Players |
|---|
| ELE International |
| Atlas Glassworks |
| Thermo Fisher Scientific |
| ProSicTech Pty Ltd |
| Wilmad-LabGlass |
| DURAN Group |
| Controls |
| Indigo Instruments |
| Vitlab GmbH |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions on borosilicate additives gate qualified supply and premium-tier pricing access for graduated cylinder manufacturers serving European pharmaceutical laboratories. Compliance with ECHA chemical safety mandates forces laboratories to pre-emptively retire non-conforming glassware, accelerating replacement demand for certified instruments while compressing margins on legacy inventory.
Pricing Analysis
Margin tightening in polypropylene disposables reflects commodity resin price swings and Asian manufacturing overcapacity. Three-tier pricing structure across Class A certified, Class B standard, and uncertified economy levels differentiates procurement specifications for pharmaceutical quality-control, educational, and field applications. Price differentiation hinges on ISO 17025 traceability and DIN-standard compliance, with pharmaceutical buyers least sensitive and educational institutions most responsive to unit cost fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese suppliers of specialty borosilicate glass feedstock. Raw material procurement draws from Schott AG's melting capacity in Germany and domestic Chinese glassworks serving the Yangtze River Delta pharmaceutical corridor. Geopolitical friction and energy cost volatility constitute the dominant supply chain risk. Distribution runs through laboratory channel distributors with embedded calibration services, though modular kit unbundling is fragmenting traditional procurement pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Graduated Cylinder Market operates as a cost-of-compliance story where ISO 17025 accreditation requirements create barrier-to-entry moats for suppliers with traceable metrology hierarchies. Regulatory stringency consolidates procurement authority around certified incumbents while squeezing marginal competitors.
For Market Incumbents: Cement PTB-traceable calibration hierarchies in Germany and NIM-traceable services in China as non-replicable competitive assets. Expand captive borosilicate melting capacity to insulate margin structures from raw material volatility. Defend against polypropylene displacement by embedding RFID calibration certificates and laser-etched markings that elevate glassware toward capital-equipment status.
For New Entrants and Emerging Players: Small-batch research laboratories in United States universities with decentralized grant funding represent the most penetrable buyer archetype. E-commerce platforms with real-time DIN-standard filtering displace catalog-based distributor relationships in this segment. Target modular kit unbundling strategies that separate cylinder units from stands, brushes, and stoppers to bypass entrenched channel intermediaries.
For Investors and Strategic Acquirers: Consolidation of supplier bases by German and Swiss diagnostic OEMs under EU MDR in vitro diagnostic equipment rules is the leading indicator that calibration-service-embedded distributors will command premium valuations. Long-term viability favors integrated manufacturers with captive borosilicate capacity and embedded metrology services. Watch for GB/T metrology standard revisions in China as the signal for domestic supplier preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | Captive feedstock supply insulates German manufacturers from energy cost volatility and geopolitical friction. |
| Embedded Calibration Service Expansion | PTB-traceable and NIM-traceable hierarchies lock in pharmaceutical laboratory contracts under ISO 17025 mandates. |
| Modular Kit Unbundling | Direct-to-laboratory e-commerce channels bypass traditional distributors in United States research university procurement. |
| Laser-Etched RFID Certification Integration | Thermo Fisher Scientific and DURAN Group compress asset lifecycle management for automated liquid handling platforms. |
| EU MDR Accessory Qualification Alignment | Design dossiers and post-market surveillance protocols elevate graduated cylinders from consumables to regulated equipment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with laboratory procurement managers, metrology service directors, pharmaceutical quality-control leads, and educational institution purchasing officers combined with secondary validation from DIN standard documentation, ECHA substance restriction databases, and FDA 21 CFR Part 211 guidance. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Data-stream reconciliation across material grade, capacity band, certification tier, and end-user industry dimensions structured the analytical framework. CAGRs derived from replacement cycle compression under ISO 17025 mandates, biologics manufacturing expansion in Germany and China, and polypropylene displacement rates in educational segments. Industry-specific inputs included PTB calibration hierarchy penetration and NIM standard revision timelines.
Revisions become necessary when ECHA expands REACH substance restrictions, China accelerates GB/T metrology enforcement, or automated liquid handling platforms obsolete dimensional tolerances in vintage glassware inventories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Blood Volume Analyzer Market