
 Global Bowel Management System Market | 2026-2036
Global Bowel Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bowel Management System Market Foresight
The bowel management system market is pivoting on a widening gap between premium silicone-based catheter platforms and commodity PVC alternatives. Hollister Incorporated leverages its integrated manufacturing footprint to sustain cost advantages in high-volume disposable segments. Coloplast Corp anchors its position through specialized hydrophilic coating technologies that command preference in spinal cord injury care. Becton Dickinson and Company competes across hospital and surgical center channels with broad portfolio breadth.
Bowel management systems comprise medical devices designed for controlled fecal collection, diversion, and evacuation, typically incorporating soft silicone or latex constructs with inflatable retention balloons rated between 5–30 mL capacity and drainage lumens calibrated to 18–36 Fr diameters. These systems serve patients with neurogenic bowel dysfunction, post-operative ileus, or traumatic spinal injury where voluntary continence is compromised. Fecal management catheters lead product type revenue due to established reimbursement codes and repeat purchase cycles, while enema delivery systems represent the fastest-growing segment as home care protocols shift toward patient-administered regimens. Among end users, long-term care facilities capture the deepest margin pools through centralized procurement contracts, though home care channels are expanding fastest as telehealth-supported self-management protocols proliferate.
The FDA enforces 510(k) clearance pathways with substantial equivalence benchmarks for fecal collection devices, while the EU MDR demands renewed clinical evaluation reports and post-market surveillance systems that elevate compliance costs for mid-tier manufacturers. Japan's PMDA maintains distinct biocompatibility testing protocols under JIS T 0993 that create separate technical barriers for market entry. Stakeholders must monitor how reimbursement recalibrations across Medicare, NHS England, and Germany's G-BA interact with shifting site-of-care preferences to determine capital allocation between institutional and home-based product development pipelines.
Market Dynamics
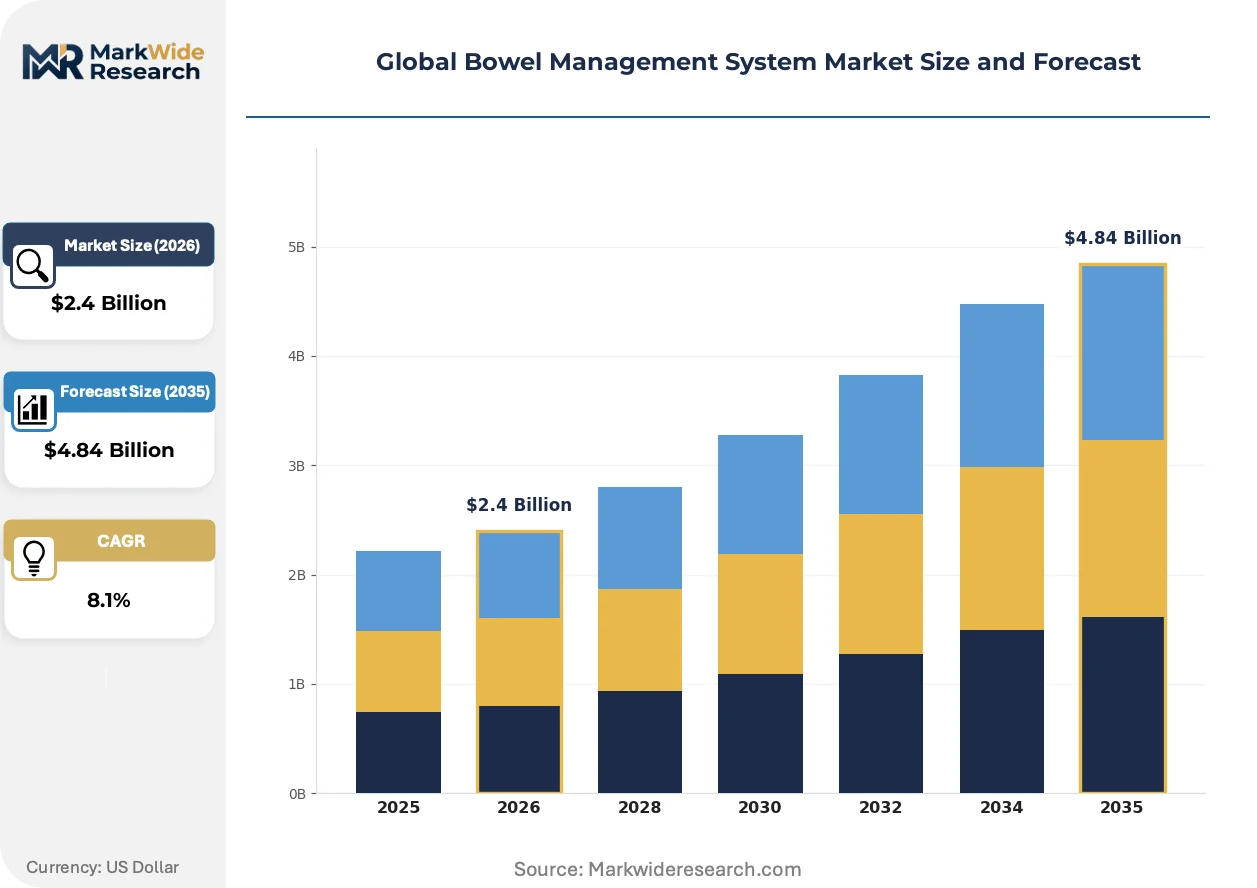
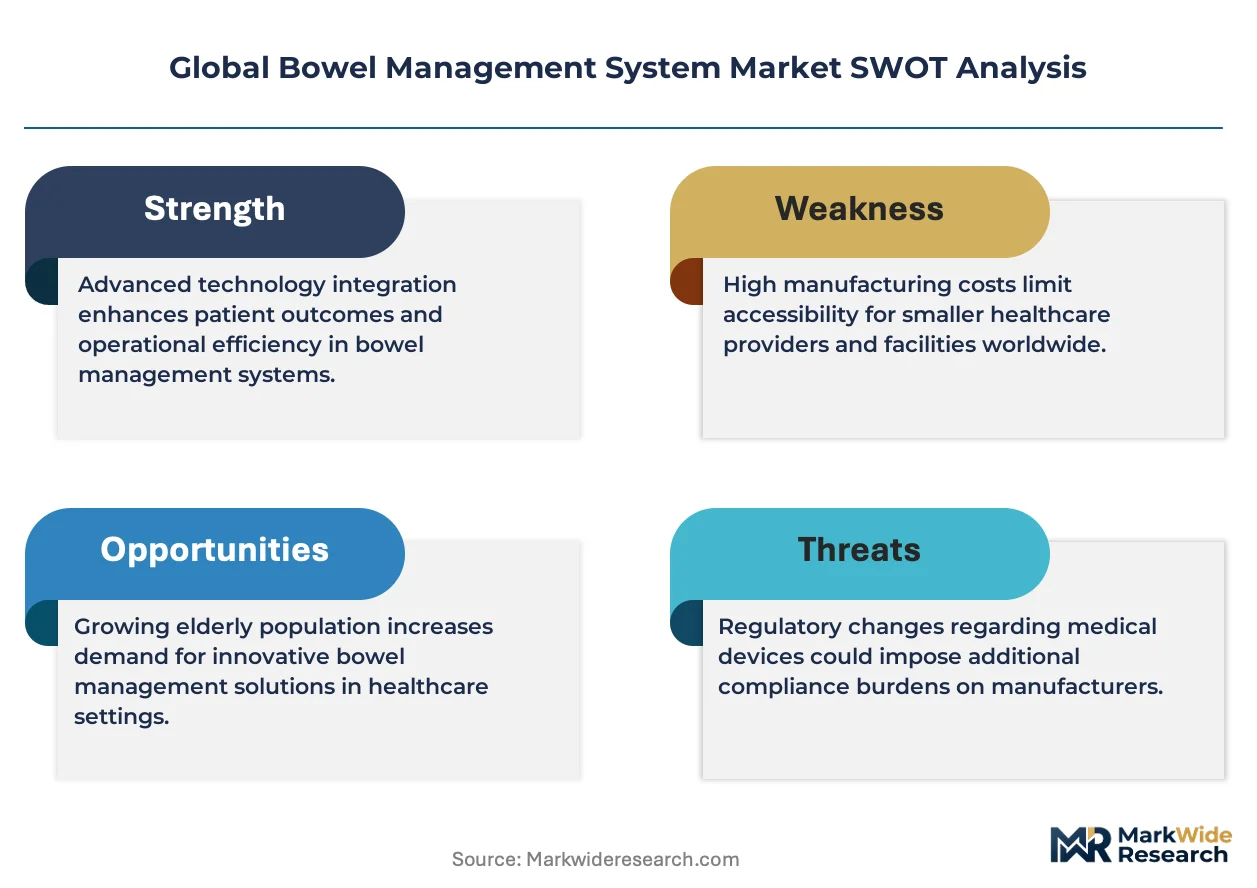
The bowel management system market is compressing around a regulatory bifurcation where EU MDR clinical evidence requirements for Class IIa and IIb devices are forcing mid-tier manufacturers toward consolidation or exit, while premium silicone catheter platforms capture margin from PVC commodity segments.
Growth Catalysts
- Aging Demographics:Japan's super-aged population and Germany's expanding home care reimbursement pathways are institutionalizing repeat purchase cycles for fecal management catheters in long-term care settings.
- EU MDR Compliance:The Medical Device Regulation's tightened biocompatibility standards are accelerating hospital procurement shifts toward hydrophilic-coated silicone platforms with established clinical evaluation reports.
- Telehealth Integration:Remote patient monitoring protocols in US Medicare Advantage plans are enabling self-administered enema delivery systems to displace facility-based evacuation procedures.
Market Restraints
- Medical-Grade Silicone Supply:Concentrated production of platinum-cured silicone elastomers among three German and US chemical suppliers creates input cost volatility for catheter manufacturers.
- Japan PMDA Barriers:JIS T 0993 biocompatibility testing protocols require separate technical dossiers that extend market entry timelines by 18-24 months for non-domestic manufacturers.
- Catheter-Associated Infection Risk:Colonization of retention balloons by multidrug-resistant organisms limits dwell time recommendations and compresses per-patient revenue yields.
Strategic Opportunities
- India Home Care Penetration:Underdeveloped distribution infrastructure for neurogenic bowel dysfunction management in tier-2 and tier-3 cities offers first-mover positioning for catheter-as-a-service models.
- AI-Enabled Irrigation Systems:Convergence of pressure-sensing balloon technology with machine learning algorithms is automating evacuation timing optimization for spinal cord injury patients.
- US IRA Reimbursement:Inflation Reduction Act provisions expanding durable medical equipment coverage for home-based bowel management are creating new channel economics for direct-to-patient delivery.
Industry Challenges
- Specialized Clinical Training:Shortage of enterostomal therapy nurses certified in fecal catheter insertion and balloon inflation protocols limits expansion into surgical center channels.
- 510(k) Substantial Equivalence:FDA clearance pathways for next-generation drainage lumen geometries require predicate device matching that delays product iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bowel Management System Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fecal Management Catheters, Anal Plugs, Absorbent Pads, Enema Delivery Systems, Rectal Tubes Application: Chronic Constipation, Fecal Incontinence, Spinal Cord Injury Care, Post-Surgical Care, Neurogenic Bowel Dysfunction End User: Long-Term Care Facilities, Rehabilitation Centers, Home Care, Surgical Centers, Specialized Clinics Deployment: Disposable Systems, Reusable Devices, Portable Units, Bedside Equipment, Inflatable Devices |
| Companies Covered | Hollister Incorporated, Becton Dickinson and Company, Coloplast Corp, Axonics Inc, Wellspect Healthcare, Convatec Inc, B. Braun Melsungen AG, ProSys International Ltd, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bowel Management System Market Shifts & Advancements
Active innovation in bowel management is compressing around three vectors: sensor-enabled automation of evacuation protocols, regulatory harmonization pressures across FDA and EU MDR frameworks, and procurement model evolution favoring bundled home care solutions over discrete device sales.
Smart catheter systems with integrated pressure transducers and wireless connectivity are automating real-time balloon inflation monitoring for spinal cord injury patients in US rehabilitation centers. Long-term care facilities in Germany are piloting these platforms to reduce unplanned catheter removals and associated nursing labor. The technology is automating the shift from scheduled manual checks to exception-based clinical workflows, compressing per-patient monitoring costs.
EU MDR post-market surveillance requirements are mandating annual clinical evaluation report updates for Class IIb fecal collection devices, elevating documentation burdens for manufacturers with legacy product portfolios. Hospital procurement committees in France and Italy are now requiring MDR certificates of conformity as gate criteria for tender participation. Small and mid-cap manufacturers without dedicated regulatory affairs teams are outsourcing compliance to specialized consultancies or exiting the European market entirely.
Site-of-care migration is fragmenting traditional distributor relationships as US health systems consolidate bowel management purchasing under centralized specialty pharmacy contracts. Home medical equipment suppliers are capturing catheter and irrigation system volumes previously flowing through acute care distributors, particularly in Medicare Advantage networks with capitated bowel dysfunction benefits. This channel rotation is most visible in Florida and Arizona retirement corridors where telehealth-supported self-management protocols have achieved highest penetration.
Global Bowel Management System Market Segmentation
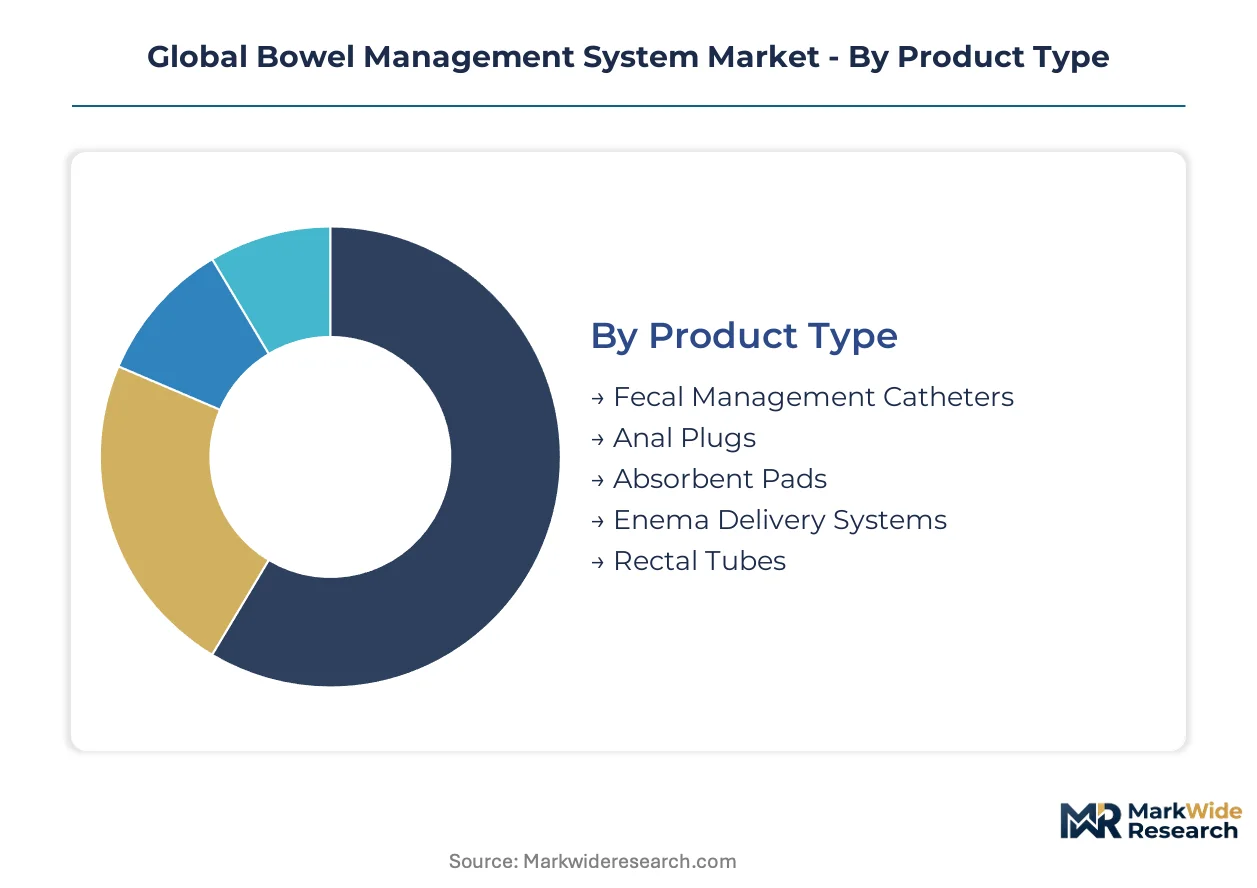
Bowel management systems fragment across four distinct category axes, each with divergent capital requirements and margin structures. Product type and application segments command the deepest R&D investment, while end-user and deployment categories shape channel economics and reimbursement pathways.
Product Type:
Capital intensity peaks with enema delivery systems requiring precision pump engineering and biocompatible reservoir materials, while absorbent pads demand minimal fixed asset deployment.
- Fecal Management Catheters:Soft silicone constructs with inflatable retention balloons (5–30 mL capacity) and drainage lumens (18–36 Fr) dominate institutional procurement. Long-term care facilities in Germany drive repeat purchase volumes through centralized contracting with established hydrophilic-coated platforms.
- Enema Delivery Systems:Battery-powered or gravity-fed pumps with temperature-controlled reservoirs and pressure-limiting valves. Medicare Advantage telehealth protocols in the US are accelerating home-based adoption, displacing facility-administered evacuation procedures.
- Anal Plugs:Medical-grade silicone or foam inserts with retrieval cords for ambulatory fecal containment. Neurological rehabilitation centers in Japan specify JIS T 0993-certified variants for spinal cord injury protocols.
- Absorbent Pads:Multi-layer cellulose and superabsorbent polymer composites with moisture-wicking back sheets. Lowest capital barrier to entry attracts commodity competition from Asian contract manufacturers.
- Rectal Tubes:Single-use PVC or silicone drainage conduits for acute decompression. Surgical centers in France prioritize MDR-compliant Class IIa certificates for tender eligibility.
Most installed capacity flows through fecal management catheters. Expansion is steepest in enema delivery systems.
Application:
Clinical complexity and reimbursement coding density concentrate investment in neurogenic bowel dysfunction and spinal cord injury segments, where specialized training requirements create service-layer moats.
- Neurogenic Bowel Dysfunction:Automated irrigation systems with pressure-sensing balloon technology and machine learning evacuation timing. Rehabilitation centers in the US pilot wireless monitoring to reduce unplanned catheter removals.
- Spinal Cord Injury Care:Hydrophilic-coated catheter platforms with extended dwell protocols. Germany's mature provider training networks and stabilized home care reimbursement anchor premium product demand.
- Fecal Incontinence:Anal plugs and absorbent pads for ambulatory management. Elderly populations in Japan's super-aged prefectures institutionalize repeat purchase cycles.
- Chronic Constipation:Enema delivery systems with patient-administered protocols. India's tier-2 and tier-3 cities present first-mover opportunities for catheter-as-a-service distribution models.
- Post-Surgical Care:Short-term fecal diversion in ileus recovery. Acute care hospitals prioritize disposable systems to minimize multidrug-resistant organism transmission risks.
Revenue concentrates in neurogenic bowel dysfunction applications. Patient volume is expanding most quickly in spinal cord injury care.
End User:
Procurement centralization and capitated reimbursement models are compressing distributor margins in long-term care while fragmenting home care channel relationships.
- Long-Term Care Facilities:Centralized purchasing contracts with bundled catheter and irrigation system volumes capture deepest margin pools. EU MDR compliance certificates now gate tender participation in France and Italy.
- Home Care:Direct-to-patient delivery via specialty pharmacy contracts in US Medicare Advantage networks. Telehealth-supported self-management protocols achieve highest penetration in Florida and Arizona retirement corridors.
- Rehabilitation Centers:Smart catheter systems with integrated pressure transducers for spinal cord injury patients. Germany pilots exception-based clinical workflows to compress per-patient monitoring costs.
- Surgical Centers:Short-dwell disposable catheters for post-operative ileus. Enterostomal therapy nurse shortages limit expansion despite favorable reimbursement.
- Specialized Clinics:Outpatient fecal management for complex neurological conditions. Concentrated in urban clusters with academic medical center affiliations.
Long-term care facilities deploy the most units annually. Home care channels are gaining share fastest.
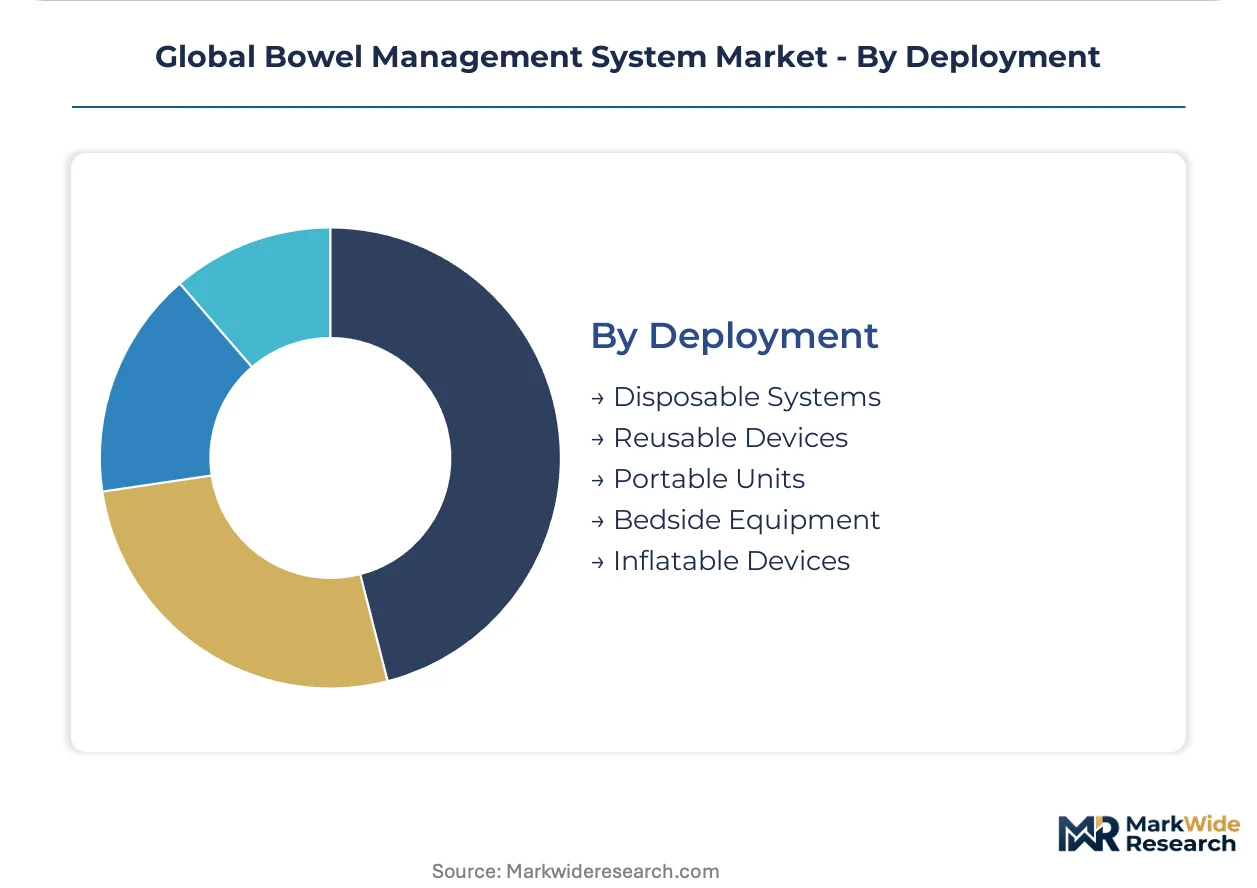
Deployment:
Regulatory bifurcation between single-use and reusable systems is elevating compliance costs for mid-tier manufacturers while premium disposable platforms capture hospital procurement shifts.
- Disposable Systems:Single-use silicone or PVC catheters with pre-lubricated hydrophilic coatings. FDA 510(k) substantial equivalence pathways and EU MDR clinical evaluation reports favor established predicate devices.
- Inflatable Devices:Retention balloon systems with real-time pressure monitoring. US rehabilitation centers automate inflation protocols to reduce nursing labor.
- Reusable Devices:Autoclavable silicone constructs for cost-conscious home care. Japan's PMDA extends market entry timelines with separate JIS T 0993 biocompatibility dossiers.
- Portable Units:Battery-powered enema pumps for ambulatory patients. Medicare IRA provisions are expanding durable medical equipment coverage eligibility.
- Bedside Equipment:Gravity-fed irrigation stands with collection canisters. Surgical centers specify integrated systems for post-operative monitoring.
Disposable systems carry the highest shipment volumes. Inflatable devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's stabilized home care reimbursement pathways contrast with Japan's extended regulatory timelines, revealing how policy architecture shapes catheter adoption velocity across mature healthcare systems.
United States
Medicare Advantage telehealth protocols are accelerating self-administered enema delivery in Florida and Arizona retirement corridors. The FDA's 510(k) substantial equivalence pathways govern fecal collection device clearance. Greater Boston rehabilitation centers pilot smart catheter systems with pressure-sensing balloon automation.
Germany
Centralized procurement contracts for long-term care facilities institutionalize repeat purchase cycles for hydrophilic-coated platforms. The EU MDR mandates renewed clinical evaluation reports for Class IIb devices. North Rhine-Westphalia's provider training networks anchor premium product demand in spinal cord injury care.
Japan
Super-aged prefectures drive institutionalized repeat purchase cycles for anal plug and absorbent pad regimens. The PMDA enforces JIS T 0993 biocompatibility testing protocols with separate technical dossiers. Kanto region rehabilitation centers specify certified variants for neurological protocols.
India
Tier-2 and tier-3 cities present first-mover positioning for catheter-as-a-service distribution models in chronic constipation management. The CDSCO regulates medical device imports under the Medical Device Rules framework. Maharashtra's underdeveloped home care infrastructure concentrates neurogenic bowel dysfunction demand in urban clusters.
France
Hospital procurement committees now require MDR certificates of conformity as gate criteria for tender participation. ANSM oversees post-market surveillance alignment with EU harmonized standards. Île-de-France academic medical centers consolidate bowel management purchasing under centralized specialty pharmacy contracts.
Global Bowel Management System Market Competitive Landscape
Top-tier vendors anchor integrated manufacturing and coating technology positions, while mid-tier specialists face consolidation pressure from EU MDR compliance burdens. The vendor base stratifies across three functional archetypes: diversified medical device conglomerates with broad portfolio breadth, specialized continence care platforms with hydrophilic coating expertise, and regional contract manufacturers serving commodity PVC segments. Competitive moves concentrate on regulatory dossier outsourcing partnerships and automated production line investments to offset biocompatibility testing cost inflation.
Among diversified medical device conglomerates, Becton Dickinson and Company and Medtronic plc occupy positions spanning hospital and surgical center channels. Hollister Incorporated exemplifies the integrated manufacturing archetype with cost advantages in high-volume disposable segments. Coloplast Corp anchors the specialized coating technology tier, commanding preference in spinal cord injury care through established clinical evaluation report portfolios.
| Leading Market Players |
|---|
| Hollister Incorporated |
| Becton Dickinson and Company |
| Coloplast Corp |
| Axonics Inc |
| Wellspect Healthcare |
| Convatec Inc |
| B. Braun Melsungen AG |
| ProSys International Ltd |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Platinum-cured silicone elastomer production consolidation among three German and US chemical suppliers simultaneously elevates input cost volatility for catheter manufacturers and compresses margin buffers for mid-tier competitors lacking backward integration into raw material sourcing.
Pricing Analysis
The bundled-vs-unbundled service split separates institutional procurement from home care channels. Three-tier pricing structure across premium hydrophilic-coated silicone, standard PVC, and economy uncoated variants reflects EU MDR certification grade and volume scale. Cost compression in commodity PVC segments is intensifying because of Asian contract manufacturer overcapacity. Long-term care facilities with centralized GPO contracts exhibit lowest price sensitivity; tier-2 Indian distributors face acute margin pressure.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume acute care demand while specialty pharmacy distributors serve Medicare Advantage home care networks. Manufacturing concentrates in Germany, the United States, and Malaysia for silicone catheter platforms; China dominates PVC component molding. Supply chains draw from medical-grade silicone elastomers, hydrophilic coating polymers, and platinum catalyst systems. Single-source vulnerability in platinum-cured silicone feedstock creates procurement risk for non-integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's clinical evidence requirements for Class IIa and IIb devices compound competitive advantage for established manufacturers with dedicated regulatory affairs infrastructure and predicate device portfolios.
For Market Incumbents: Cement market position by acquiring mid-tier competitors facing EU MDR compliance exit pressures. Prioritize backward integration into platinum-cured silicone elastomer supply to offset raw material cost volatility. Channel control through long-term GPO contracts with German long-term care facilities anchors recurring revenue against emerging hydrophilic coating specialists.
For New Entrants and Emerging Players: Launch via catheter-as-a-service distribution models in India's tier-2 and tier-3 cities where neurogenic bowel dysfunction management infrastructure remains underdeveloped. Target chronic constipation applications with patient-administered enema delivery systems. Partner with US Medicare Advantage telehealth platforms to bypass entrenched acute care distributor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking EU MDR clinical evaluation report portfolios but possessing established hospital procurement relationships. Long-term viability hinges on regulatory dossier completion timelines and predicate device matching capabilities. Watch FDA 510(k) clearance velocity for next-generation pressure-sensing balloon platforms as inflection indicator for smart catheter adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Report Completion | MDR certificates gate tender participation in France and Italy procurement committees. |
| Platinum-Cured Silicone Backward Integration | German chemical supplier partnerships reduce input cost volatility for catheter manufacturers. |
| Telehealth Platform Partnership | Medicare Advantage network integration enables direct-to-patient enema system delivery. |
| Pressure-Sensing Balloon R&D Investment | US rehabilitation center pilots validate automated inflation monitoring for spinal cord injury protocols. |
| India Distribution Infrastructure Buildout | Tier-2 city catheter-as-a-service models capture first-mover positioning in chronic constipation management. |
Research Methodology
Coverage spans Germany, the United States, Japan, India, and France, with primary inputs from each market's stakeholder ecosystem. Primary interviews with enterostomal therapy nurses, hospital procurement committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation report databases, CMS Medicare reimbursement data, and hospital procurement contract registries. Bottom-up unit shipment estimates and top-down value reconstructions triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, application, end user, and deployment segmentation dimensions. CAGRs derive from regression-adjusted trend extrapolation incorporating EU MDR compliance cost inflation, Medicare Advantage telehealth penetration curves, and Japan's super-aged demographic trajectories. Modeled inputs include catheter dwell time protocols, reimbursement code density by care setting, and silicone elastomer price indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity shifts and platinum catalyst supply disruptions. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and site-of-care migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Global Otoscopes Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Global Cardiac Holter Monitor Market