
 Automated Blood Analyzer Market | 2026-2036
Automated Blood Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Blood Analyzer Market Insights
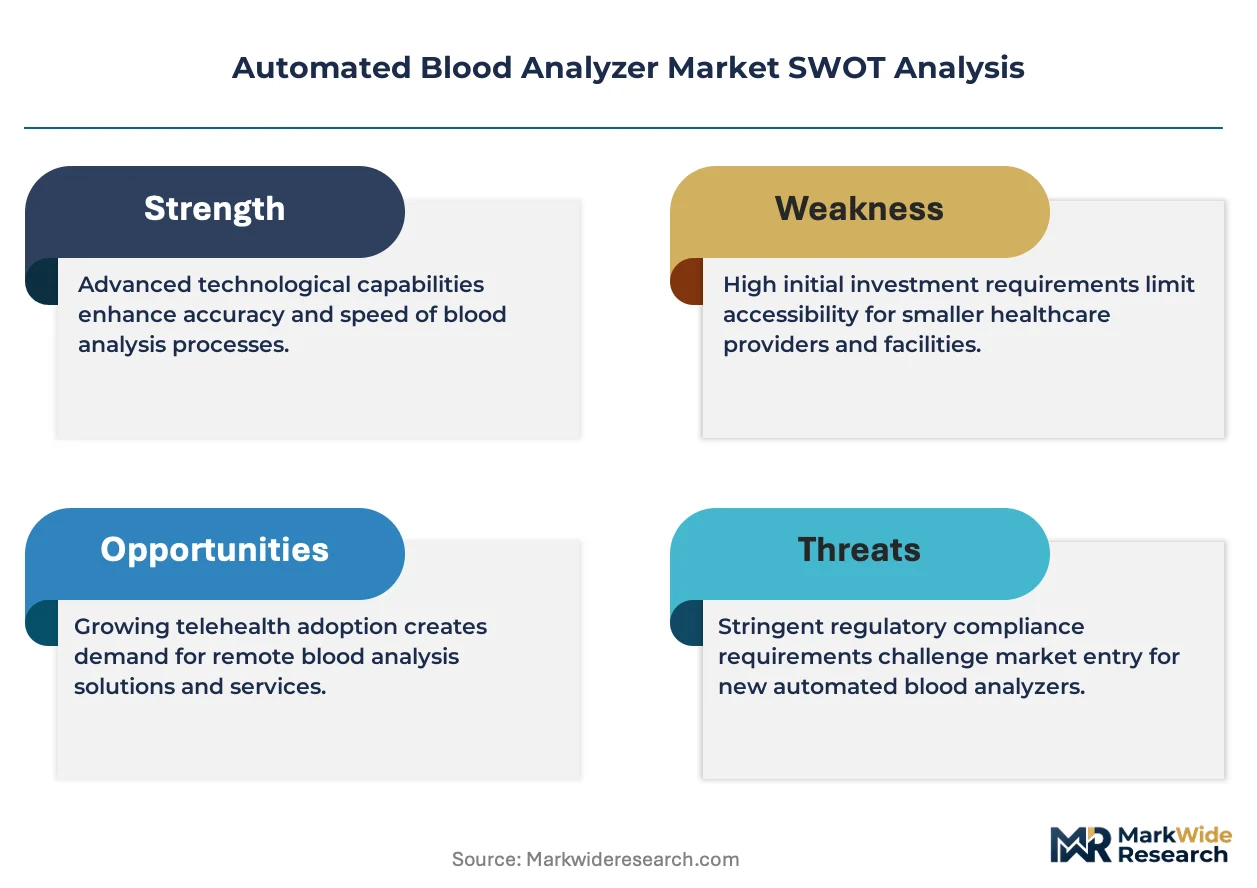
Modular analyzer configurations is recalibrating how mid-sized laboratories evaluate capital equipment purchases. Sysmex Corporation leverages its dominance in hematology automation to anchor recurring reagent revenue streams. Danaher Corporation sustains competitive positioning through backward integration into consumables and software ecosystems. Abbott Laboratories differentiates via point-of-care connectivity that bridges decentralized testing with central lab oversight.
An automated blood analyzer is a clinical diagnostic instrument that processes blood specimens through automated sampling, reagent-based reaction chambers, and optical or electrochemical detection to quantify cellular components, coagulation parameters, or biochemical markers. Hematology analyzers typically measure complete blood counts with five-part white cell differentials at throughput rates exceeding 100 samples per hour, serving as workhorses in high-volume screening environments. Chemistry analyzers command the largest installed base due to broad menu breadth spanning metabolic panels to therapeutic drug monitoring. Microfluidics-based platforms represent the fastest-expanding technology segment as manufacturers miniaturize fluidic pathways to reduce sample volume requirements and reagent waste. Immunoassay analyzers concentrate margin pools in specialty testing categories including cardiac biomarkers and infectious disease serology.
The FDA governs premarket clearance and ongoing quality system regulation for analyzer hardware and assay kits, while Clinical Laboratory Improvement Amendments establish proficiency testing and personnel competency requirements that directly shape equipment specification sheets. ISO 15189 accreditation standards for medical laboratories create secondary compliance pathways that influence purchasing criteria across hospital networks and independent reference labs. Procurement teams must weigh total cost-of-ownership models against assay menu expansion roadmaps as vendor consolidation narrows the field of viable long-term partners.
Market Dynamics
Hospital consolidation across the United States is concentrating purchasing power into centralized procurement committees that demand modular, scalable analyzer platforms capable of serving multi-site networks from single reference laboratories.
Growth Catalysts
- CLIA Quality Standards:The FDA's enforcement of Clinical Laboratory Improvement Amendments proficiency testing mandates pushes mid-sized diagnostic laboratories toward integrated analyzer systems that automate compliance documentation and reduce manual quality control steps.
- Microfluidics Miniaturization:Advances in microfluidic channel engineering reduce sample volume requirements below 100 microliters, expanding testing access to pediatric and geriatric populations previously excluded from high-throughput screening protocols.
- Technician Shortage:The shrinking pool of certified medical laboratory scientists in the United States drives demand for walk-away automation that eliminates manual pipetting and slide preparation from routine hematology workflows.
Market Restraints
- Reagent Lock-In Economics:Closed-system analyzer architectures bind laboratories to proprietary consumable contracts, inflating total cost-of-ownership and limiting vendor switching flexibility over ten-year equipment lifecycles.
- Capital Intensity Barriers:High-throughput modular systems require upfront investments exceeding $500,000 per installation, excluding independent physician office laboratories and rural critical access hospitals from advanced automation tiers.
- Optical Component Supply Concentration:Precision photomultiplier tubes and laser diodes for flow cytometry modules concentrate manufacturing in Japanese and German supplier bases, exposing lead times to geopolitical trade friction.
Strategic Opportunities
- Point-of-Care Connectivity:Bridging decentralized testing devices with central laboratory information systems creates new revenue streams through remote quality oversight and real-time result validation.
- AI-Assisted Morphology:Machine learning algorithms for automated white blood cell differential review reduce manual microscopy workload, addressing pathologist shortages in the United Kingdom and Scandinavian health systems.
- India's Diagnostic Expansion:The country's National Health Mission targets universal health coverage by 2030, driving public sector tenders for mid-volume analyzers in district hospital networks across Maharashtra and Tamil Nadu.
Industry Challenges
- Interoperability Complexity:Integrating next-generation analyzers with legacy laboratory information systems requires custom HL7 interface development, extending deployment timelines by three to six months.
- Specialized Field Service Scarcity:The limited pool of factory-trained engineers capable of calibrating laser optics and fluidic pumps creates maintenance backlogs that reduce instrument uptime below 95% in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Blood Analyzer Market |
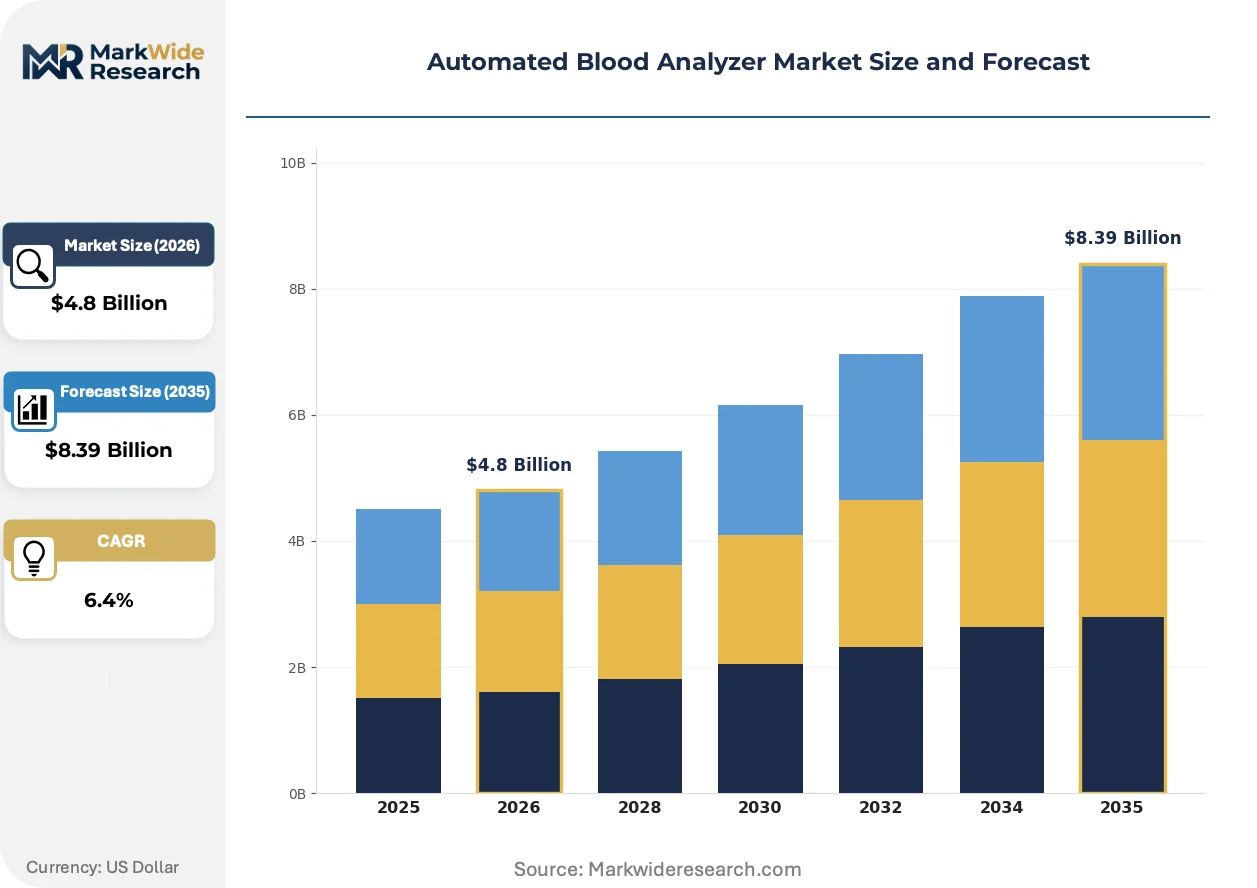
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemoglobin Analyzers, Coagulation Analyzers, Chemistry Analyzers, Immunoassay Analyzers End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutes Technology: Optical, Electrochemical, Immunofluorescence, Microfluidics Configuration: Compact, Bench-top, Standalone, Modular |
| Companies Covered | Sysmex Corporation, Danaher Corporation, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, Horiba Ltd, F. Hoffmann-La Roche Ltd, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Boule Diagnostics AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Blood Analyzer Market Trends and Innovations
Digital pathology integration and artificial intelligence-assisted result interpretation are compressing turnaround times while reshaping staffing models across high-volume screening environments.
Microfluidics-based sample processing is integrating electrochemical detection with miniaturized reaction chambers. Reference laboratories in Germany and Japan are adopting these platforms for STAT testing. This convergence is integrating previously separate pre-analytical and analytical phases into single-cartridge workflows that eliminate manual transfer steps.
The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for in-vitro diagnostic devices. Manufacturers must now submit post-market surveillance data for analyzer software updates. This regulatory burden is compressing product development cycles for mid-tier vendors seeking CE marking approval.
Consolidated purchasing committees now unbundle service contracts from equipment leases, negotiating separate multi-vendor maintenance agreements. Hospital networks in Texas and California lead this shift toward performance-based service level agreements. This procurement evolution pressures original equipment manufacturers to defend margin through captive reagent contracts rather than bundled service premiums.
Automated Blood Analyzer Market Segmentation
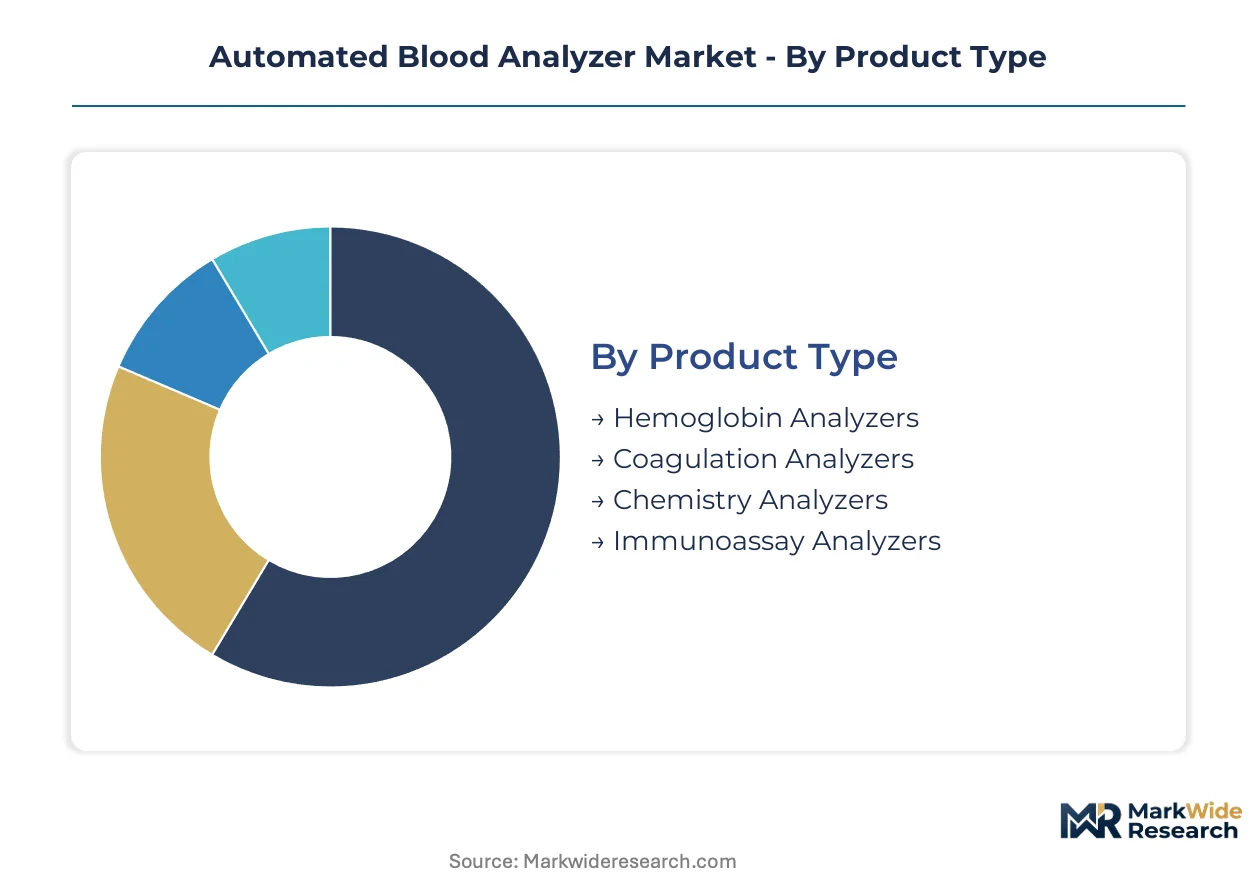
Automated blood analyzer procurement hinges on matching regulatory clearance tiers to test volume requirements. Laboratories segment investments across product categories, end-user settings, and technology platforms to optimize capital deployment against CLIA compliance burdens.
Product Type:
FDA premarket notification pathways vary sharply across analyzer categories, with 510(k) clearance timelines stretching longest for novel immunoassay platforms and shortest for iterative hematology hardware.
- Hemoglobin Analyzers:These devices quantify hemoglobin concentration through spectrophotometric or electrical impedance methods, typically processing 60-120 samples hourly. Demand clusters in blood bank screening networks across the United States, where the FDA's blood banking regulations mandate continuous quality monitoring for donor eligibility.
- Chemistry Analyzers:Multi-parameter platforms measuring metabolic panels, enzymes, and electrolytes through photometric or ion-selective electrode detection. Hospital consolidation in Texas and California favors high-throughput modular chemistry systems capable of serving centralized reference lab networks from single installations.
- Coagulation Analyzers:Clot-based and chromogenic assay systems for PT/INR and aPTT testing, requiring specialized optical detection modules.
- Immunoassay Analyzers:Chemiluminescence and ELISA-based platforms for cardiac biomarkers and infectious disease serology, carrying the steepest regulatory validation burdens.
Chemistry analyzers sit at the top of the volume ranking, with immunoassay analyzers climbing the fastest.
End User:
Capital intensity thresholds and staffing models create distinct purchasing patterns across customer categories, from centralized hospital networks to distributed research facilities.
- Hospitals:Acute care settings deploy analyzers in core laboratories and satellite stat labs, prioritizing turnaround time for emergency department throughput. Consolidated purchasing committees in multi-hospital systems negotiate enterprise-wide service agreements spanning equipment, reagents, and informatics integration.
- Diagnostic Laboratories:Independent reference labs and hospital outreach programs drive demand for walk-away automation that reduces medical laboratory scientist headcount. CLIA proficiency testing mandates push mid-sized labs toward integrated platforms with automated quality control documentation.
- Blood Banks:Transfusion services require dedicated hemoglobin and immunohematology analyzers with specialized software for donor management.
- Research Institutes:Academic medical centers and CROs purchase analyzers for clinical trial sample processing, prioritizing flexibility over throughput.
Diagnostic laboratories command the largest installed base, with blood banks expanding most quickly as donor screening protocols tighten.
Technology:
Detection modality determines reagent cost structures, maintenance intervals, and the technical skill required for calibration and troubleshooting.
- Optical:Photometric and flow cytometric detection systems dominate hematology and chemistry applications, leveraging laser diodes and photomultiplier tubes for cellular enumeration. Supply concentration of precision optical components in Japanese and German manufacturing bases exposes lead times to trade friction.
- Microfluidics:Miniaturized fluidic channels integrate sample preparation with analytical detection in single-cartridge workflows. Pediatric and geriatric testing programs in Germany and Japan adopt these platforms to access sub-100-microliter sample volumes previously excluded from high-throughput protocols.
- Electrochemical:Ion-selective electrodes and amperometric sensors for electrolyte and glucose measurement, offering lower per-test costs.
- Immunofluorescence:Fluorophore-labeled antibody detection for high-sensitivity protein quantification in specialty testing menus.
Optical platforms retain the dominant share, with microfluidics gaining share fastest as manufacturers miniaturize fluidic pathways.
Configuration:
Physical footprint and scalability architecture shape lease-versus-buy decisions and long-term capacity planning.
- Modular:Scalable platforms allowing incremental addition of analytical modules, sample handling units, and informatics nodes. Hospital networks in the United States favor modular configurations to align capital expenditure with test volume growth across consolidated multi-site operations.
- Bench-top:Mid-volume systems for laboratories with space constraints, balancing throughput against physical footprint.
- Compact:Point-of-care and physician office analyzers with limited menus and minimal maintenance requirements.
- Standalone:Fixed-capacity systems for stable test volumes, offering lower acquisition cost but limited expansion pathways.
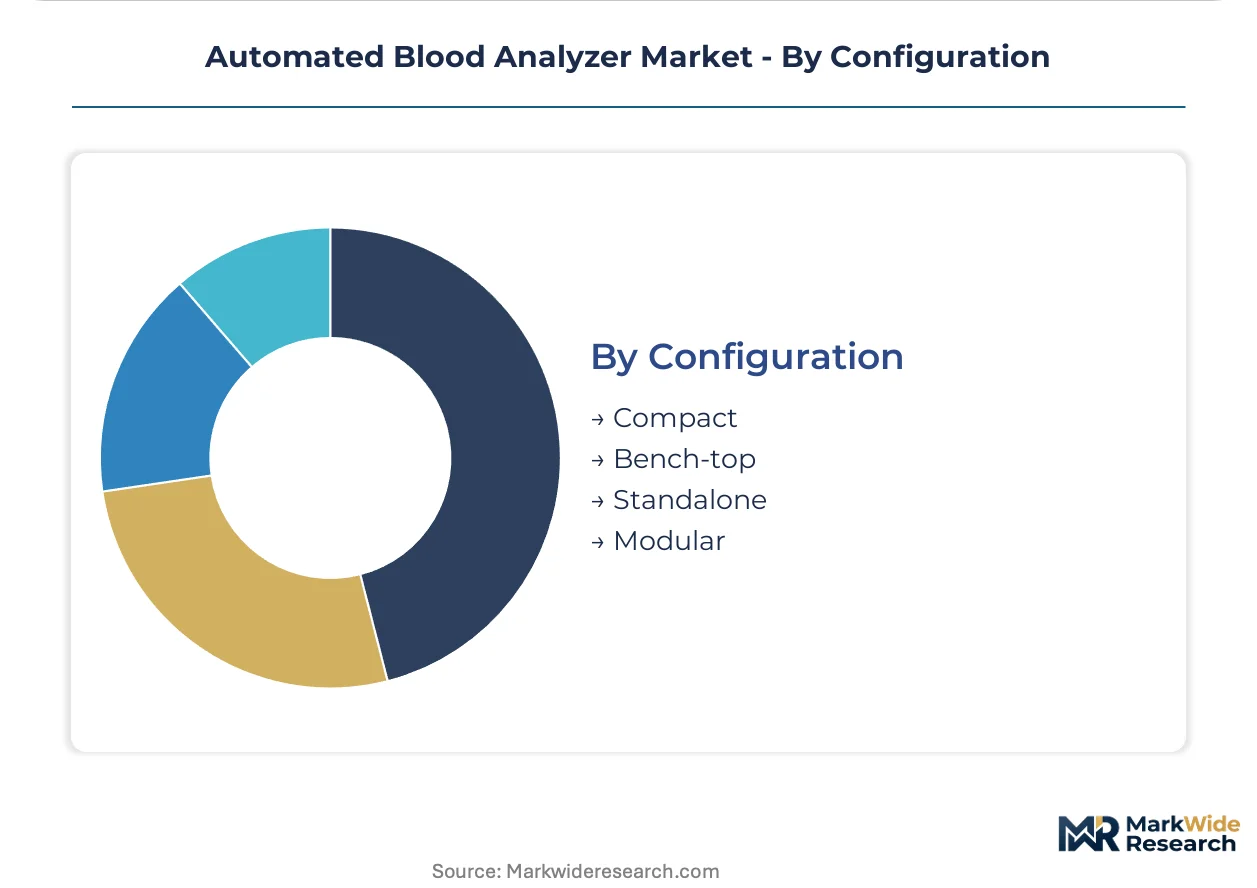
Modular systems lead in new installations, with compact configurations expanding most quickly in decentralized testing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated blood analyzer technology originated in post-war Japan and Germany, where precision optical engineering and clinical laboratory standardization first converged. These foundations established the regulatory and manufacturing templates that now shape procurement patterns across major healthcare economies.
United States
Hospital consolidation into multi-site networks drives demand for modular, high-throughput platforms serving centralized reference laboratories. The FDA enforces Clinical Laboratory Improvement Amendments proficiency testing mandates that push mid-sized diagnostic labs toward integrated automation. Texas and California hospital networks lead unbundled procurement of service contracts from equipment leases.
Germany
Reference laboratories in Bavaria and Baden-Württemberg adopt microfluidics-based STAT testing platforms to reduce sample volumes below 100 microliters. The EU Medical Device Regulation imposes stricter clinical evidence requirements for in-vitro diagnostic software updates. Stuttgart and Mannheim clusters concentrate precision photomultiplier tube manufacturing for flow cytometry modules.
Japan
Domestic demand for walk-away hematology automation addresses technician shortages in aging prefectural health systems. METI industrial standards and PMDA premarket approvals shape product development cycles for export-oriented manufacturers. Tokyo-Osaka corridor facilities supply laser diodes and optical detection components to global analyzer assembly lines.
India
The National Health Mission targets universal health coverage by 2030, driving public sector tenders for mid-volume analyzers in district hospital networks. CDSCO regulatory pathways for in-vitro diagnostics are streamlining import clearance timelines. Maharashtra and Tamil Nadu state health systems expand automated hematology workflows in urban tertiary care centers.
China
NMPA regulatory harmonization with international standards accelerates market access for multinational analyzer platforms. Domestic manufacturers in Shenzhen and Shanghai scale production of electrochemical detection modules for chemistry analyzers. The country's dual carbon goals pressure reagent supply chains toward reduced packaging waste and localized production.
Automated Blood Analyzer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reagent lock-in economics and service contract bundling. The vendor base organizes into three tiers: integrated platform specialists with captive consumable streams, modular hardware fabricators, and point-of-care connectivity providers. Consolidation pressure narrows viable long-term partnerships as procurement committees demand decade-spanning assay menu roadmaps. Dominant competitive moves include backward integration into precision optical components and geographic expansion through distributor networks in India's district hospital systems.
Among Japanese precision engineering specialists, Sysmex Corporation exemplifies the integrated platform archetype through hematology automation dominance. Danaher Corporation occupies a position within the North American life sciences conglomerate tier, sustaining positioning through consumables and software ecosystems. Abbott Laboratories represents the point-of-care connectivity vector, bridging decentralized testing with central laboratory oversight architectures.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Danaher Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter |
| Horiba Ltd |
| F. Hoffmann-La Roche Ltd |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Boule Diagnostics AB |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement committees in Texas and California hospital networks now unbundle service contracts from equipment leases, forcing original equipment manufacturers to recapture margin through captive reagent streams rather than bundled premiums. This procurement shift concentrates pricing power among buyers with multi-site networks while squeezing mid-tier vendors unable to match decade-spanning assay menu roadmaps.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates analyzer procurement, separating FDA-cleared high-throughput modular systems from mid-volume bench-top units and compact point-of-care devices. Price differentiation rests on CLIA compliance tier and reagent lock-in contract duration, with premium configurations commanding captive consumable premiums. Cost compression in the economy tier intensifies as domestic Chinese manufacturers scale electrochemical detection modules. Independent physician office laboratories exhibit highest price sensitivity, while consolidated hospital networks prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Factory-trained engineer shortages in Japan and Germany constrain field service capacity for laser optics calibration and fluidic pump maintenance. Precision photomultiplier tube manufacturing concentrates in Stuttgart and Mannheim clusters, while Tokyo-Osaka corridor facilities supply laser diodes for flow cytometry modules. Raw material dependencies span optical-grade glass, rare-earth laser crystals, and medical-grade polymer tubing. Single-source vulnerability in Japanese photomultiplier supply exposes lead times to trade friction. Distribution runs through authorized distributor networks with factory-direct service for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated blood analyzer market functions as a regulatory compounder, where FDA enforcement of CLIA proficiency testing mandates creates recurring demand for integrated compliance automation. Each regulatory tightening cycle accelerates replacement of manual workflows with walk-away systems.
For Market Incumbents: Anchor hematology automation dominance through backward integration into precision optical components, denying mid-tier competitors access to photomultiplier tube supply. Expand captive reagent revenue streams by embedding proprietary assay chemistries into closed-system architectures that bind laboratories to decade-long consumable contracts. Counter emerging microfluidics specialists by accelerating AI-assisted morphology roadmaps that reduce pathologist review burden.
For New Entrants and Emerging Players: Microfluidics-based single-cartridge workflows offer entry wedge into pediatric and geriatric testing segments previously excluded from high-throughput protocols. India's district hospital networks under the National Health Mission represent the most penetrable geography, with public sector tenders favoring mid-volume analyzers over premium modular systems. Pursue CDSCO regulatory clearance pathways ahead of multinational incumbents to establish installed base before competitive consolidation.
For Investors and Strategic Acquirers: Asymmetric upside sits with point-of-care connectivity providers bridging decentralized testing with central laboratory oversight architectures. Five-to-ten year viability favors vendors with software ecosystem depth over pure hardware fabricators facing reagent lock-in erosion. Target acquisition candidates with established HL7 interface libraries and hospital information system integration credentials. Monitor FDA 510(k) clearance timelines for novel immunoassay platforms as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Lock-In Contract Expansion | Captive consumable streams defend margin against unbundled procurement pressure from consolidated hospital networks. |
| Microfluidics Platform Development | Sub-100-microliter sample volumes unlock pediatric and geriatric testing segments in Germany and Japan. |
| AI-Assisted Morphology Integration | Machine learning algorithms address pathologist shortages in United Kingdom and Scandinavian health systems. |
| Point-of-Care Connectivity Architecture | Remote quality oversight bridges decentralized testing devices with central laboratory information systems. |
| India District Hospital Network Expansion | National Health Mission tenders for mid-volume analyzers in Maharashtra and Tamil Nadu drive public sector volume. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at FDA-cleared manufacturers with secondary validation against hospital procurement databases, CMS Medicare reimbursement data, GPO contract repositories, and 510(k) premarket notification filings. Bottom-up instrument shipment modeling and top-down reagent revenue analysis triangulated market sizing across the projection horizon.
Historical reference periods anchored volume and value outputs to installed base evolution and replacement cycle patterns, with segmentation modeling across product type, end-user setting, detection technology, and physical configuration dimensions. CAGRs derived from regression analysis against CLIA compliance expenditure trends and technician shortage indices. Forecast inputs incorporated microfluidics adoption curves and AI-assisted morphology penetration assumptions.
The model holds under stable FDA enforcement intensity and continued hospital consolidation; deviation in CLIA regulatory postponement or supply chain normalization would shift replacement timing. Practitioners should monitor CDSCO regulatory streamlining progress and EU MDR software update requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Laboratory Fume Hoods Market