
 Electronic Multichannel Pipettes Market | 2026-2036
Electronic Multichannel Pipettes Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Multichannel Pipettes Market Foresight
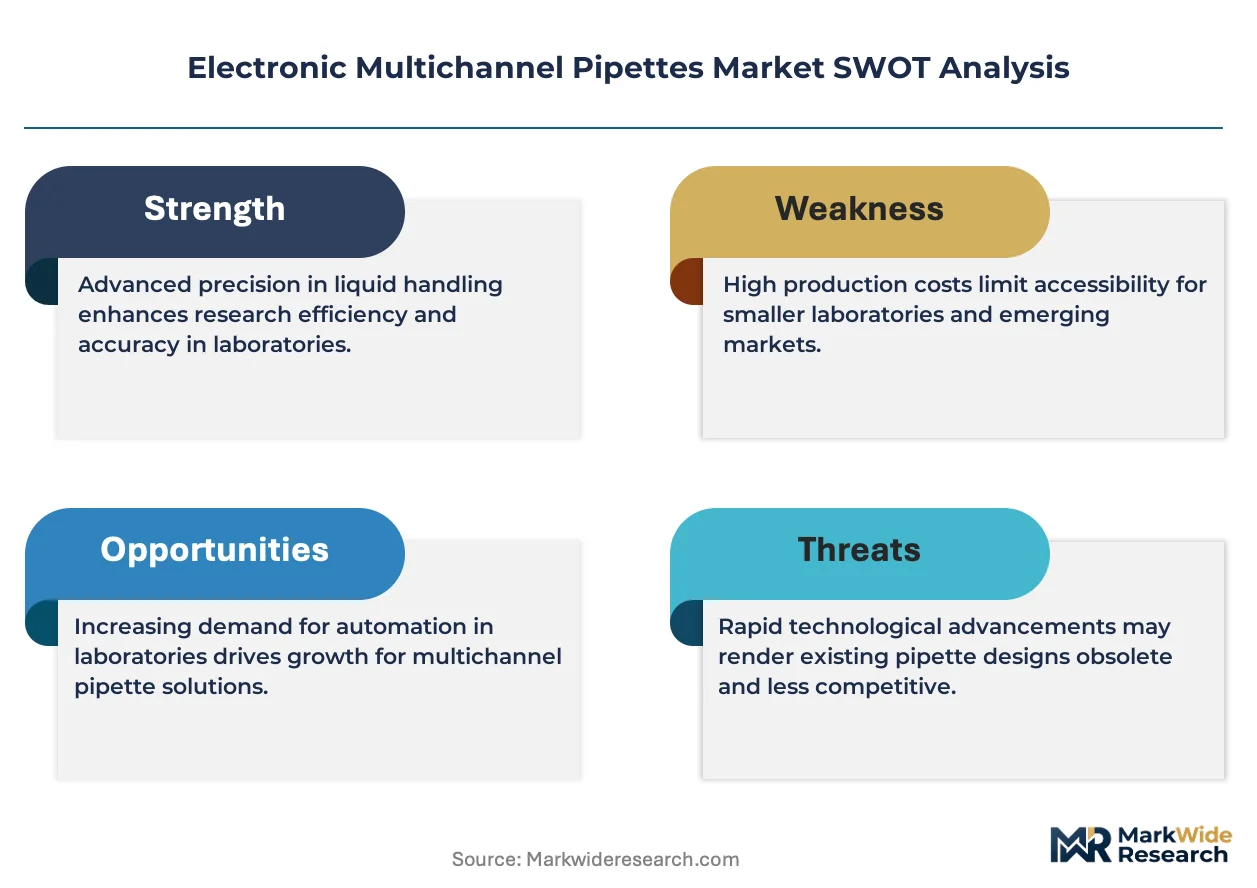
REACH compliance is restructuring the cost-of-entry calculus for electronic multichannel pipettes sold across Europe, forcing manufacturers to document substance safety across complex supply chains. Eppendorf AG leverages its German manufacturing base to sustain premium positioning in calibrated precision instruments. Thermo Fisher Scientific anchors North American distribution through extensive service networks and bundled consumables programs. Gilson competes on ergonomic design heritage while navigating evolving electromagnetic compatibility standards.
Electronic multichannel pipettes are motorized precision liquid-handling instruments equipped with microprocessor-controlled piston drives, typically offering volume ranges from 0.5 microliters to 1200 microliters per channel with programmable aspiration and dispensing sequences for high-throughput workflows. These instruments serve pharmaceutical discovery, clinical diagnostics, and academic research by reducing operator fatigue and improving reproducibility across 96-well and 384-well plate formats. Eight-channel and twelve-channel configurations dominate installed bases in pharmaceutical labs where plate-based screening protocols are standard. Bluetooth-enabled and touchscreen interface technologies are capturing disproportionate interest from quality control laboratories seeking audit-trail integration and remote monitoring capabilities.
FDA 21 CFR Part 11 and EU IVDR together shape validation requirements for electronic pipettes used in regulated clinical and pharmaceutical environments, elevating documentation burdens for market access. ISO 8655 calibration standards govern piston-operated volumetric apparatus performance testing, directly influencing service revenue attachments and replacement cycles. Stakeholders must weigh capital deployment toward connected instrument platforms against the operational drag of legacy equipment retrofitting as compliance thresholds tighten.
Market Dynamics
Bluetooth-enabled electronic pipettes with touchscreen interfaces are compressing replacement cycles as pharmaceutical labs prioritize audit-trail integration and remote monitoring capabilities over legacy manual instruments.
Growth Catalysts
- EU IVDR compliance mandates:Clinical diagnostics laboratories across Germany, France, and Italy must upgrade to calibrated precision instruments with documented performance traceability, accelerating equipment refresh rates.
- High-throughput screening expansion:Pharmaceutical discovery pipelines in Basel and Boston are standardizing on twelve-channel configurations to reduce operator fatigue during 384-well plate protocols.
- ISO 8655 calibration enforcement:Third-party service providers are capturing recurring revenue streams as regulated environments mandate piston-operated volumetric apparatus performance verification.
Market Restraints
- Premium component sourcing concentration:Microprocessor-controlled piston drives and precision manufacturing depend on specialized suppliers clustered in southern Germany and Switzerland.
- REACH documentation burden:Substance safety verification across complex supply chains elevates administrative costs for manufacturers distributing across European Economic Area member states.
- Manual pipette residual utility:Academic research institutions with intermittent usage patterns retain cost-advantaged single-channel manual alternatives for low-volume workflows.
Strategic Opportunities
- India's CDSCO regulatory alignment:Contract research organizations in Hyderabad and Bengaluru are adopting international calibration standards, opening import substitution potential for certified instruments.
- Cloud-connected service models:Remote diagnostic capabilities and predictive maintenance algorithms are unbundling traditional capital sales into recurring subscription architectures.
- CRISPR workflow integration:Gene editing laboratories require programmable aspiration sequences that manual instruments cannot execute, creating specification-driven demand.
Industry Challenges
- Electromagnetic compatibility certification:Bluetooth-enabled instruments face extended testing timelines against evolving IEC 61326 standards for laboratory equipment.
- Legacy LIMS integration friction:Quality control laboratories struggle to retrofit data output formats from connected pipettes into established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Multichannel Pipettes Market |
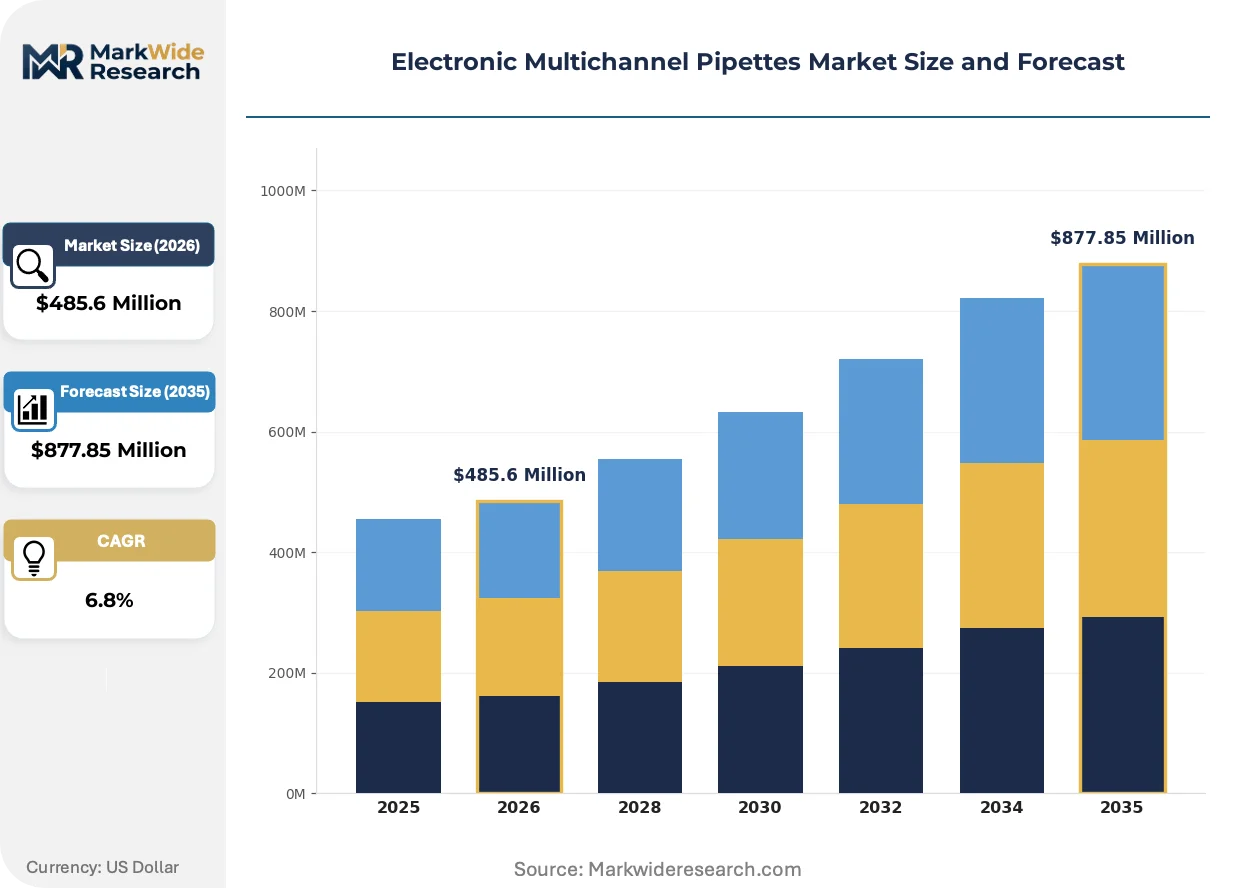
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Eight-Channel, Twelve-Channel, Sixteen-Channel Technology: Microprocessor-Controlled, Bluetooth Enabled, Touchscreen Interface, Manual Override End User: Pharmaceutical Labs, Academic Research, Clinical Laboratories, Quality Control Delivery Mode: Automatic, Semi-Automatic, Manual, Remote Operation |
| Companies Covered | Eppendorf AG, Thermo Fisher Scientific, Gilson, Mettler-Toledo International, BRAND GmbH + CO KG, Corning Incorporated, Integra Biosciences AG, Hamilton Company, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Multichannel Pipettes Market Shifts & Advancements
Touchscreen interface architectures and wireless connectivity protocols are redefining how precision liquid-handling instruments capture, transmit, and validate operational data across regulated workflows.
Bluetooth Low Energy modules paired with capacitive touchscreen displays are consolidating operator interaction paradigms around gesture-based programming and encrypted data transmission. Quality control laboratories in pharmaceutical manufacturing facilities are adopting these interfaces at accelerated replacement cycles. This consolidation is compressing demand for button-actuated mechanical instruments with limited programmability.
EU IVDR performance documentation requirements are elevating validation burdens for electronic pipettes deployed in clinical diagnostic settings. Manufacturers must now maintain technical files demonstrating volumetric accuracy traceability across instrument lifecycles. In vitro diagnostic laboratories in Germany and the Netherlands are responding by consolidating supplier relationships toward vendors with established notified body partnerships.
Service contract unbundling is fragmenting traditional capital equipment procurement into performance-based subscription arrangements. Academic research consortia and mid-sized biotechnology firms are shifting from outright purchase toward calibrated-instrument leasing with embedded maintenance. This pattern is most pronounced in the United Kingdom and Scandinavian markets where research funding volatility favors operational expenditure flexibility.
Electronic Multichannel Pipettes Market Segmentation
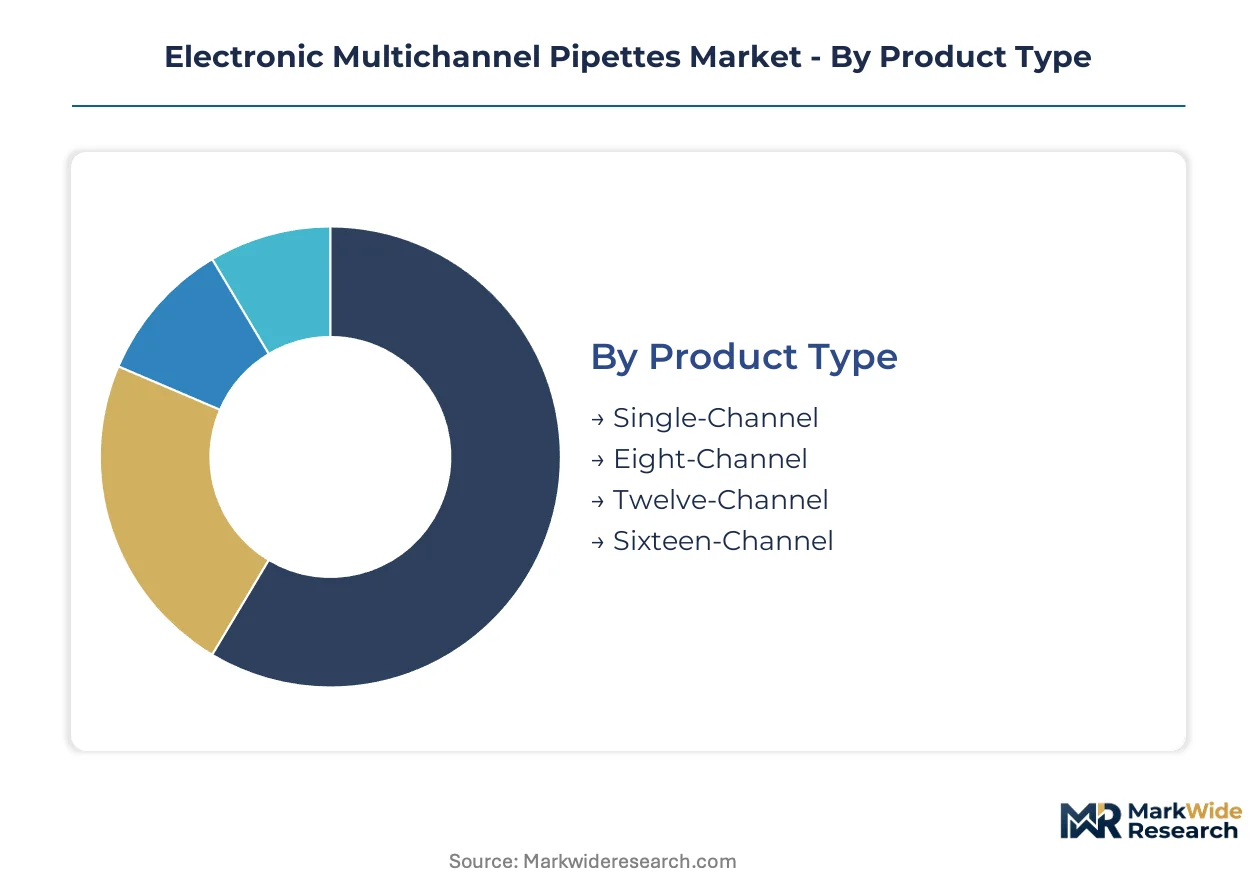
Electronic multichannel pipettes fragment across four distinct category axes, each reflecting divergent buyer priorities ranging from throughput requirements to connectivity mandates. Procurement decisions hinge on matching channel configurations to plate formats, interface technologies to LIMS integration needs, and delivery modes to regulatory validation burdens.
Product Type:
Channel count dictates throughput economics and operator fatigue trade-offs in high-volume screening environments.
- Eight-Channel:Dominates pharmaceutical discovery workflows where 96-well plate standardization balances throughput against capital outlay. Basel and Boston biotech clusters deploy these configurations for compound library screening where operator rotation limits fatigue-related pipetting errors.
- Twelve-Channel:Compresses processing time for 384-well plate protocols in genomic screening applications. CRISPR workflow laboratories in Heidelberg and San Diego specify these units for programmable multi-step aspiration sequences manual instruments cannot execute.
- Single-Channel:Retains utility in method development and low-throughput validation work where flexibility outweighs speed.
- Sixteen-Channel:Serves specialized 1536-well ultra-high-throughput screening in contract research organizations with dedicated automation infrastructure.
Volume sits with Eight-Channel configurations; growth tilts toward Twelve-Channel as 384-well plate adoption accelerates.
Technology:
Interface sophistication separates audit-trail-compliant instruments from legacy mechanical alternatives in regulated procurement.
- Microprocessor-Controlled:Foundation technology enabling programmable volume settings, multi-dispense sequences, and piston drive precision. German and Swiss manufacturing clusters concentrate supply for these motor assemblies.
- Bluetooth Enabled:Demand concentrates in quality control laboratories requiring encrypted data transmission to LIMS platforms. FDA 21 CFR Part 11 validation protocols favor these units for electronic signature capture.
- Touchscreen Interface:Gesture-based programming reduces training burden in high-turnover contract research environments.
- Manual Override:Provides backup operation during power failure or firmware malfunction in clinical diagnostic settings.
Microprocessor-Controlled units anchor installed base volume; Bluetooth Enabled configurations are climbing the fastest as remote monitoring capabilities become procurement prerequisites.
End User:
Regulatory exposure and funding stability shape replacement cycle timing across institutional categories.
- Pharmaceutical Labs:Drive premium segment demand with standardized twelve-channel deployments for target validation and lead optimization. Basel-based discovery operations refresh equipment at compressed cycles to maintain ISO 8655 calibration compliance.
- Clinical Laboratories:EU IVDR documentation requirements are forcing equipment upgrades across German, French, and Italian diagnostic networks. These buyers prioritize vendors with established notified body partnerships for technical file maintenance.
- Academic Research:Funding volatility favors manual pipette retention for intermittent usage patterns.
- Quality Control:Pharmaceutical manufacturing sites specify connected instruments for batch record integration.
Pharmaceutical Labs command the largest revenue share; Clinical Laboratories are gaining share fastest as IVDR enforcement tightens.
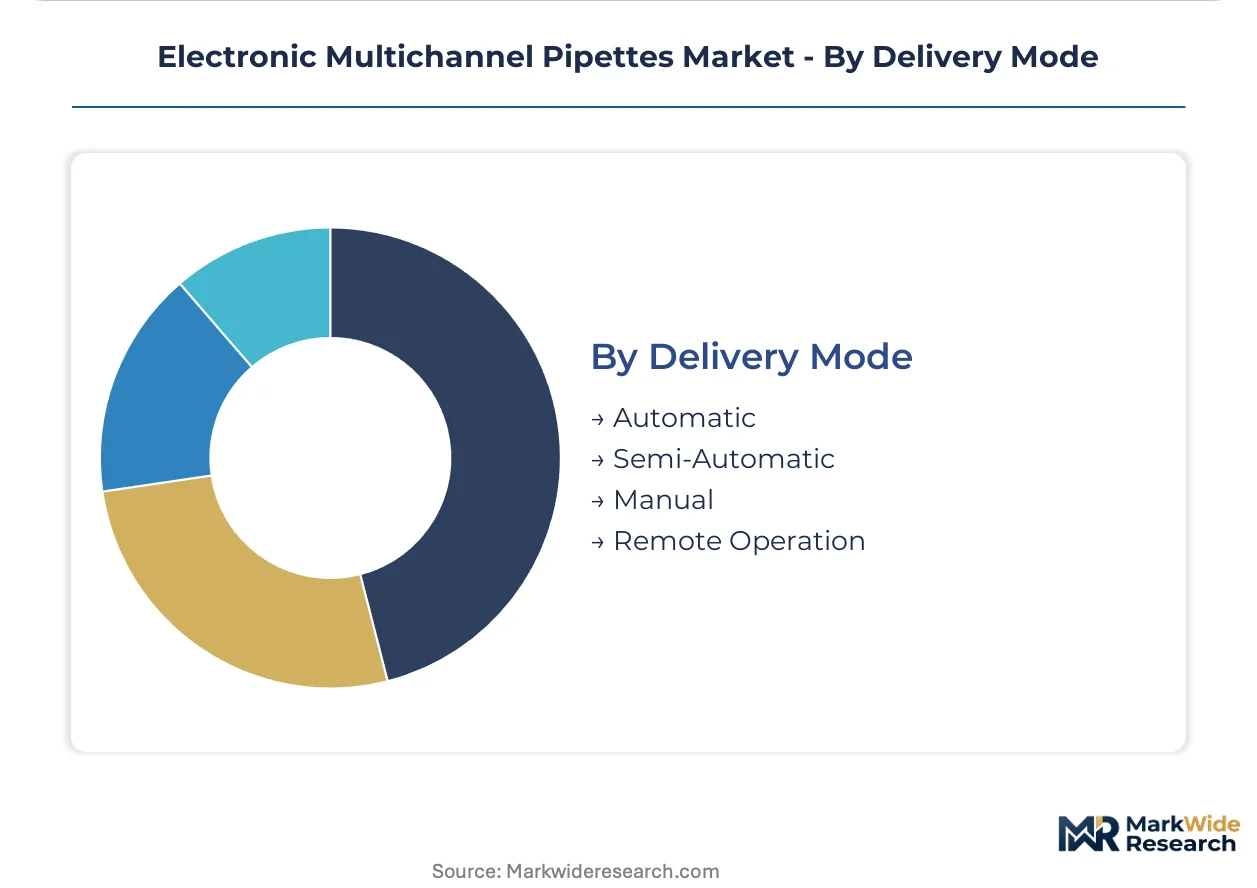
Delivery Mode:
Automation depth correlates with labor cost structure and contamination control requirements.
- Automatic:Eliminates operator variability through motorized piston control with programmable aspiration and dispensing speeds. High-throughput screening facilities in Boston and Basel specify these for walk-away operation during extended compound library processing.
- Semi-Automatic:Balances programmability with manual tip ejection and plate positioning. Academic core facilities favor this tier for multi-user environments where full automation capital cannot be justified.
- Manual:Retains cost advantage in low-volume workflows with minimal regulatory documentation burden.
- Remote Operation:Emerging specification for biosafety level containment laboratories where operator proximity introduces contamination risk.
Automatic systems dominate value capture; Remote Operation is expanding most quickly as containment laboratory construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical discovery operations in Basel and Boston drive concentrated demand for twelve-channel configurations, while EU IVDR compliance mandates reshape procurement patterns across European diagnostic networks.
Germany
Clinical diagnostics laboratories in Berlin and Munich face EU IVDR documentation requirements that force upgrades to calibrated precision instruments. ECHA REACH compliance adds substance safety verification burdens for manufacturers distributing across the European Economic Area. Eppendorf AG and Sartorius AG anchor a dense manufacturing cluster in Hamburg and Göttingen that supplies precision piston assemblies to global markets.
United States
FDA 21 CFR Part 11 validation protocols drive quality control laboratories toward Bluetooth-enabled instruments with electronic signature capture. High-throughput screening facilities in Greater Boston standardize on automatic systems for walk-away compound library processing. Thermo Fisher Scientific leverages extensive service networks across the Midwest and Northeast to anchor North American distribution.
Switzerland
Pharmaceutical discovery pipelines in Basel deploy twelve-channel configurations to reduce operator fatigue during extended 384-well plate protocols. Swissmedic oversight of in vitro diagnostic devices elevates technical file maintenance requirements for precision liquid-handling instruments. Precision manufacturing for microprocessor-controlled piston drives concentrates around Zurich and the Swiss-German border region.
India
Contract research organizations in Hyderabad and Bengaluru adopt international calibration standards as CDSCO regulatory alignment progresses. Academic research institutions retain cost-advantaged manual alternatives for intermittent usage patterns. Import substitution potential opens for certified instruments as domestic biotechnology manufacturing scales in Karnataka and Telangana.
United Kingdom
Research funding volatility favors operational expenditure flexibility through calibrated-instrument leasing with embedded maintenance. Academic research consortia shift from outright purchase toward subscription arrangements. Service contract unbundling fragments traditional capital equipment procurement most pronouncedly in the Southeast and Greater London research clusters.
Electronic Multichannel Pipettes Market Competitive Landscape
German producers anchor the premium-calibration tier; North American specialists hold distribution scale advantages through bundled consumables programs. The vendor base concentrates around precision manufacturing heritage in southern Germany and Switzerland against extensive service networks in the United States. Three archetypes dominate: vertically integrated precision instrument manufacturers, distribution-scale life sciences conglomerates, and ergonomic design specialists. Competitive moves center on cloud-connected service model unbundling and predictive maintenance algorithm deployment.
Among German-based precision manufacturers, Eppendorf AG and Sartorius AG exemplify the vertically integrated archetype with captive supply of calibrated piston assemblies. Thermo Fisher Scientific occupies a position representing North American distribution-scale consolidation through extensive service networks. Gilson sits within the ergonomic design heritage tier while navigating electromagnetic compatibility certification timelines. These three anchors illustrate how geographic manufacturing concentration competes against service infrastructure scale.
| Leading Market Players |
|---|
| Eppendorf AG |
| Thermo Fisher Scientific |
| Gilson |
| Mettler-Toledo International |
| BRAND GmbH + CO KG |
| Corning Incorporated |
| Integra Biosciences AG |
| Hamilton Company |
| Sartorius AG |
| Others |
Supply & Pricing Matrix
Family-owned precision instrument specialists in southern Germany anchor supply-side discipline through captive manufacturing of microprocessor-controlled piston assemblies, translating upstream control into premium pricing power for calibrated instruments while constraining discount flexibility for commodity-grade alternatives.
Pricing Analysis
Short lead-time premiums compress price elasticity for EU IVDR-compliant instruments with documented calibration traceability, while spot inventory discounts concentrate in academic channels with intermittent usage patterns. Three-tier pricing structure across premium, standard, and economy levels separates ISO 8655-certified precision units from basic microprocessor-controlled alternatives and residual manual pipette segments. Pricing pressure stems from REACH documentation burdens elevating administrative overhead across European distribution. Contract research organizations exhibit highest price sensitivity due to funding volatility, whereas pharmaceutical quality control laboratories prioritize audit-trail integration over unit cost.
Supply Chain Analysis
Direct-to-laboratory channels serve high-throughput pharmaceutical screening facilities with bundled calibration services, while distributor networks handle fragmented academic procurement. Manufacturing gravity centers on Germany, Switzerland, and the United States for precision piston assemblies and microprocessor modules. Supply chains draw from specialized suppliers for capacitive touchscreen displays, Bluetooth Low Energy modules, and precision-machined polymer components. Single-source vulnerability concentrates in southern German suppliers of calibrated drive mechanisms. Distribution runs through authorized service partners for regulated environments requiring ISO 8655 compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic multichannel pipette manufacturing is consolidating around backward integration into precision piston assembly production, with players racing to capture captive supply of calibrated drive mechanisms as the primary margin-defense lever.
For Market Incumbents: Anticipate margin compression from emerging ergonomic-design specialists by deepening captive supply of microprocessor-controlled piston drives and securing notified body partnerships for EU IVDR technical file maintenance. Consolidate service network density in Basel and Boston biotech clusters to anchor replacement cycle capture against Bluetooth-enabled entrants.
For New Entrants and Emerging Players: Academic core facilities represent the most penetrable segment, where funding volatility favors leasing-based procurement over capital purchase. Target cloud-connected subscription models with embedded predictive maintenance algorithms to bypass incumbent service infrastructure advantages. Partner with third-party calibration providers to shortcut ISO 8655 compliance credibility.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-manufacturing mid-caps in southern Germany with established ECHA REACH documentation systems and notified body relationships. Long-term viability hinges on conversion from transactional equipment sales to recurring service revenue architectures. Monitor CDSCO regulatory alignment progress in India as inflection signal for import substitution potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piston Assembly Manufacturing | Captive supply of calibrated drive mechanisms defends margin position against component cost volatility. |
| Notified Body Partnership Expansion | Established EU IVDR technical file maintenance accelerates clinical laboratory procurement cycles in Germany. |
| Cloud-Connected Service Model Launch | Remote diagnostic capabilities convert capital sales to recurring subscriptions in UK academic consortia. |
| CRISPR Workflow Protocol Integration | Programmable aspiration sequences capture specification-driven demand from gene editing laboratories in Heidelberg. |
| CDSCO Certification Investment | Regulatory alignment opens import substitution potential in Hyderabad and Bengaluru contract research markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with laboratory equipment procurement managers, biomedical engineers at pharmaceutical quality control facilities, calibration service technicians, and regulatory affairs specialists at notified bodies. Bottom-up triangulation across equipment shipment records and top-down validation against laboratory capital expenditure surveys ensured segmentation coherence.
Data-stream reconciliation across product type, technology tier, end-user category, and delivery mode dimensions shaped the analytical framework across the projection horizon. CAGRs were derived from instrument replacement cycle analysis, regulatory compliance-driven refresh rate modeling, and high-throughput screening facility expansion tracking. Bluetooth adoption curves and IVDR implementation timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including hypothetical REACH substance restrictions on specific polymer formulations and unannounced FDA guidance revisions for electronic signature capture. Forecasts reflect assumptions about calibration standard enforcement continuity and research funding stability across European academic networks. Periodic stress-testing of base assumptions against electromagnetic compatibility certification timeline delays is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market