
 Global Automated Suturing Devices Market | 2026-2036
Global Automated Suturing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Suturing Devices Market Foresight
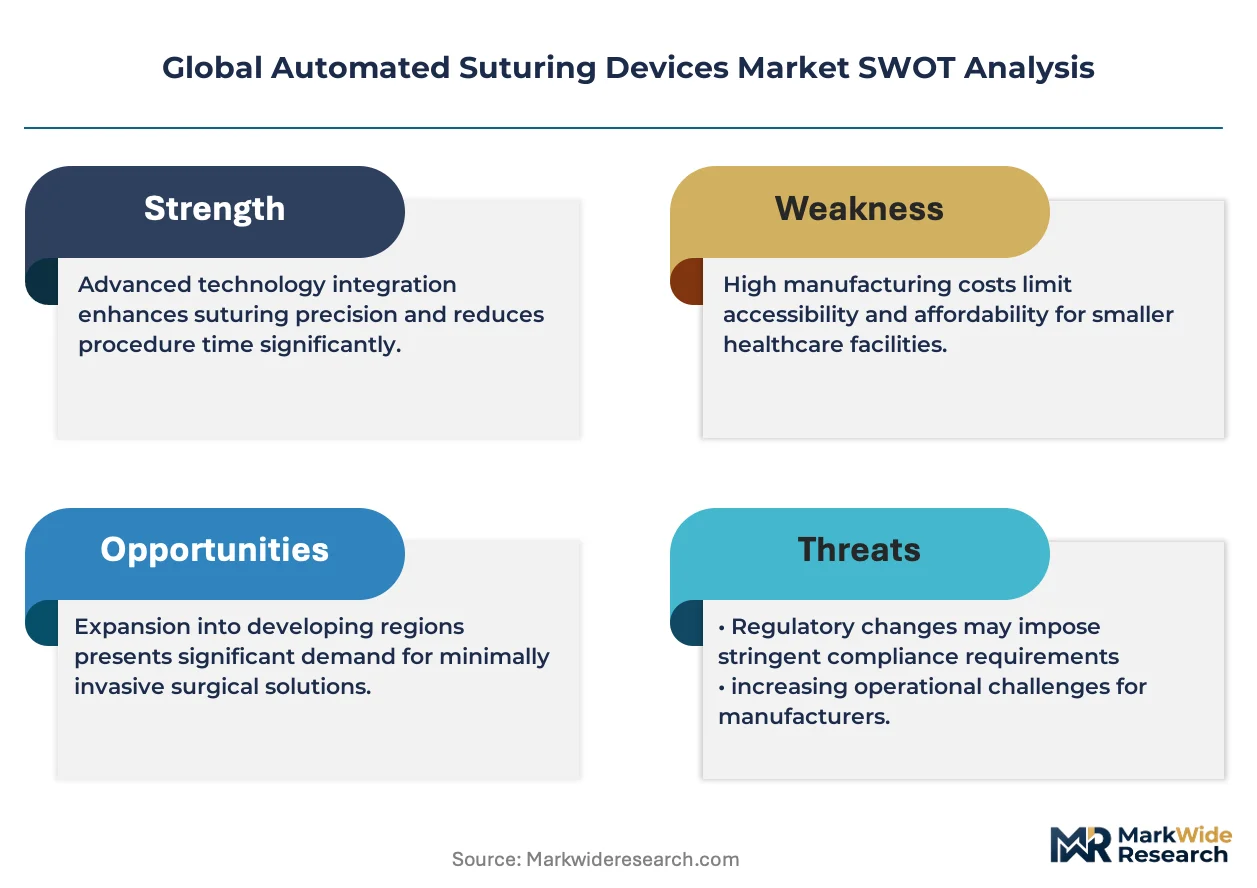
Project finance and operating lease structures for robotic surgical suites is fragmenting the competitive landscape for automated suturing devices. Medtronic leverages its installed base of surgical robotics to bundle suturing modules with capital equipment contracts. Smith & Nephew sustains competitiveness through specialized orthopedic suturing applications that integrate with its arthroscopy platforms. Sutrue differentiates via precision-engineered reusable handheld devices that reduce per-procedure supply costs for mid-tier surgical centers.
Automated suturing devices are electromechanical or robotic instruments that place, tension, and secure sutures with programmable needle trajectories and knot-replacement mechanisms, typically operating at 5-15 mm working diameters for minimally invasive access. Their primary commercial purpose is to standardize wound closure quality while reducing operative time and surgeon fatigue in laparoscopic, endoscopic, and open procedures. Handheld devices dominate current volume due to lower capital barriers and compatibility with existing surgical workflows, while robotic suturing systems capture disproportionate value in cardiac and microsurgical applications where precision tolerances are narrowest. Barbed sutures represent the fastest-expanding technology segment as they eliminate knot-tying steps and distribute tension evenly across wound edges.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending product commercialization cycles and elevating clinical evidence thresholds for novel suturing mechanisms. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility testing protocols that force manufacturers to run parallel validation programs for Asia-Pacific registration. Stakeholders must monitor how reimbursement coding for robotic-assisted suturing procedures evolves across Medicare, NHS England, and Japan's MHLW fee schedules, as these determinations will directly shape hospital capital allocation priorities.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) clearance pathways are extending product commercialization cycles, forcing manufacturers to front-load clinical evidence generation and parallelize biocompatibility validation across Japan's PMDA and South Korea's MFDS protocols.
Growth Catalysts
- Barbed suture technology:Elimination of knot-tying steps reduces operative time in laparoscopic closures. Ambulatory surgical centers in Germany accelerate adoption of disposable units.
- EU MDR compliance frameworks:Elevated clinical evidence thresholds favor established manufacturers with robust quality management systems. Market consolidation benefits firms with pre-existing technical documentation libraries.
- Robotic surgical suite financing:Project finance and operating lease structures lower capital barriers for mid-tier hospitals. Bundled suturing modules with capital equipment contracts expand addressable market.
Market Restraints
- Biocompatibility validation costs:Parallel testing protocols for PMDA and MFDS registration double pre-market expenditure. Smaller manufacturers face resource constraints.
- Reimbursement coding uncertainty:Medicare, NHS England, and Japan's MHLW fee schedules lack standardized codes for robotic-assisted suturing. Hospital capital allocation delays result.
- Reusable device sterilization complexity:Precision-engineered handheld units require specialized maintenance protocols. Surgical centers without adequate sterile processing infrastructure face operational friction.
Strategic Opportunities
- Orthopedic arthroscopy integration:Specialized suturing applications for sports medicine procedures remain underdeveloped. Integration with existing visualization platforms creates differentiation.
- Mid-tier surgical center penetration:Reusable handheld devices reduce per-procedure supply costs. Cost-conscious facilities in Japan represent expansion targets.
- Cardiac microsurgery precision:Narrow tolerance applications currently capture disproportionate value. Robotic systems with programmable needle trajectories address unmet needs.
Industry Challenges
- Surgeon training and credentialing:Electromechanical suturing requires distinct motor skills versus manual techniques. Fellowship programs lack standardized curricula.
- Legacy workflow integration:5-15 mm working diameter devices must interface with existing trocar placements. Operating room configuration changes meet institutional resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Suturing Devices Market |
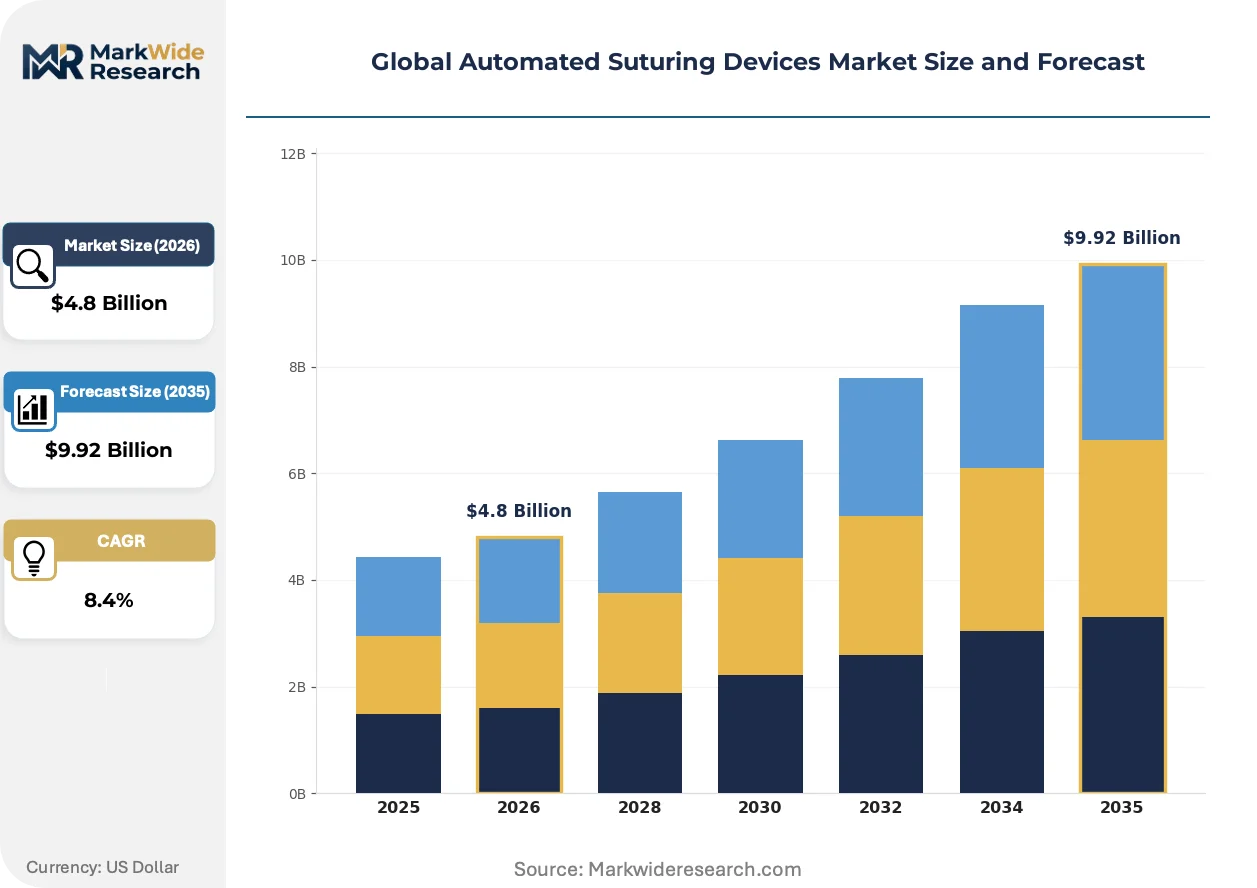
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Robotic Suturing Systems, Disposable Units, Reusable Equipment Technology: Stapling, Barbed Sutures, Needleless Closure, Laser Assistance, Thermal Sealing Application: General Surgery, Orthopedic Procedures, Cardiothoracic Operations, Gynecologic Treatments, Plastic Surgery End User: Surgical Centers, Ambulatory Clinics, Specialty Hospitals, Research Institutes |
| Companies Covered | Medtronic, Smith & Nephew, Boston Scientific Corporation, Ethicon, B. Braun, Sutrue, Apollo Endosurgery, BD, LSI Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Suturing Devices Market Shifts & Advancements
Automated suturing is converging with robotic surgical platforms and disposable supply models, compressing the traditional distinction between capital equipment and consumables while elevating precision requirements in cardiac and microsurgical applications.
Barbed suture technology is collapsing the knot-tying step in wound closure protocols. Ambulatory surgical centers in Germany and the United States adopt these devices at accelerating pace. The elimination of tension-distribution failures is compressing operative time and reducing surgeon fatigue in high-volume laparoscopic settings.
EU MDR technical documentation requirements are elevating clinical evidence thresholds for novel suturing mechanisms. Manufacturers must submit comprehensive biocompatibility and performance data before CE marking authorization. Class III device reclassifications are forcing portfolio reviews among firms with legacy product lines.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts. Surgical centers now demand discrete pricing for maintenance, software updates, and consumable supply. This shift is most visible in United States health systems responding to Medicare reimbursement pressure and constrained capital budgets.
Global Automated Suturing Devices Market Segmentation
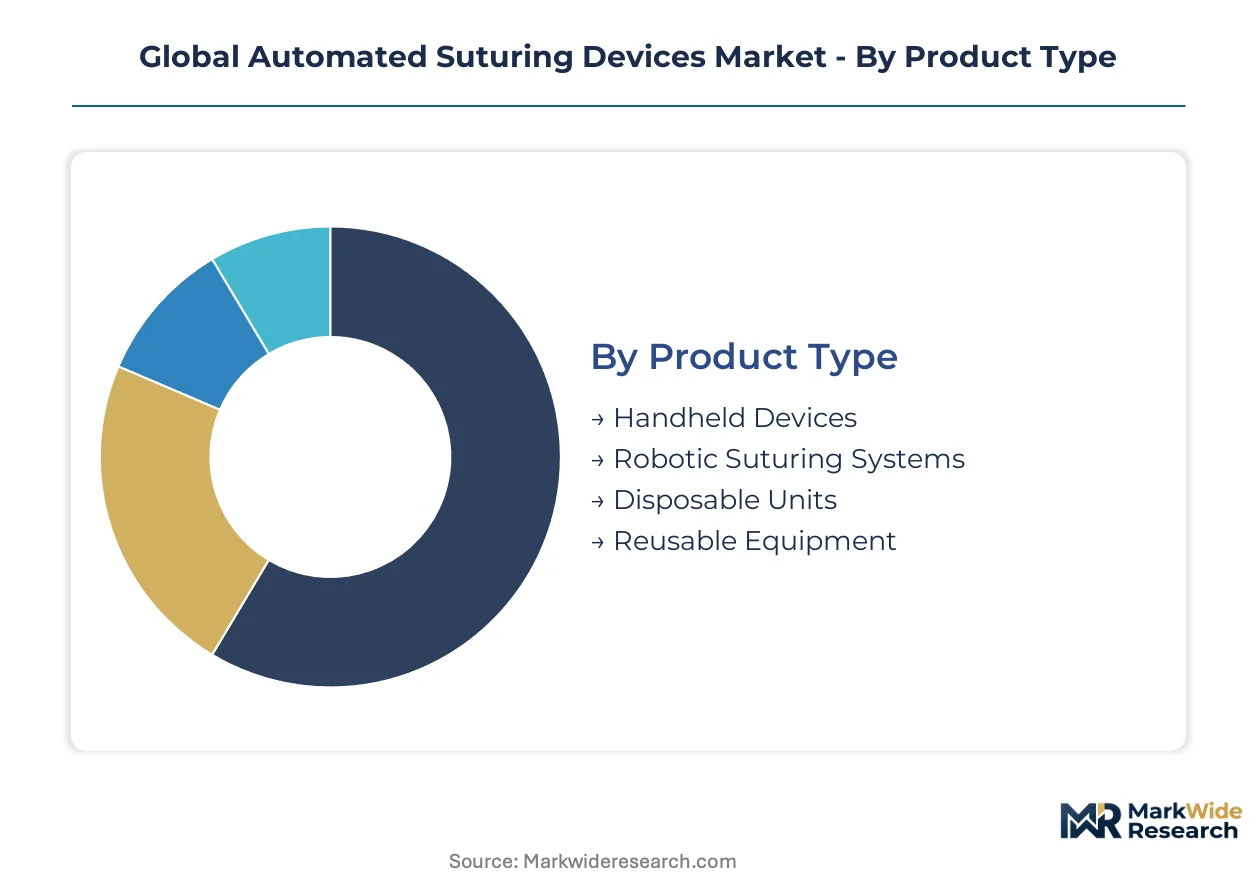
Automated suturing devices fragment across four critical dimensions: product architecture, underlying mechanism, procedural setting, and purchaser type. Each axis reveals distinct margin profiles and regulatory pathways that determine competitive positioning.
Product Type:
Mature capital equipment competes with emerging disposable formats as procurement departments restructure purchasing logic.
- Handheld Devices:Electromechanical instruments with 5-15 mm working diameters interface with standard trocar placements. Surgical centers in Germany prioritize these units for laparoscopic volume where capital constraints limit robotic adoption.
- Robotic Suturing Systems:Programmable needle trajectory platforms with knot-replacement mechanisms command premium positioning. Cardiac applications in Japan's specialty hospitals drive demand for sub-millimeter precision tolerances.
- Disposable Units:Single-use cartridges eliminate sterilization protocols and cross-contamination risk.
- Reusable Equipment:Precision-engineered instruments reduce per-procedure supply costs for mid-tier facilities.
Handheld devices handle the majority of throughput; disposable units are expanding most quickly on share.
Technology:
Cost tier stratification separates premium precision mechanisms from standard closure alternatives.
- Barbed Sutures:Unidirectional or bidirectional projections distribute tension evenly across wound edges without knot-tying. Ambulatory surgical centers in the United States accelerate adoption for time-compressed laparoscopic closures.
- Stapling:Metal or polymer fasteners deploy rapid mechanical closure for high-volume abdominal procedures.
- Needleless Closure:Adhesive and adhesive-strip mechanisms reduce tissue trauma in superficial applications.
- Laser Assistance:Photothermal welding of collagen structures enables bloodless microsurgical anastomosis.
- Thermal Sealing:Resistive heating elements fuse tissue planes in vessel-rich operative fields.
Stapling maintains installed base dominance; barbed sutures are gaining share fastest.
Application:
Volume concentration in high-throughput specialties contrasts with margin concentration in precision disciplines.
- General Surgery:Abdominal, colorectal, and hernia procedures generate the highest absolute device consumption. United States health systems prioritize operative efficiency in these high-frequency closures.
- Cardiothoracic Operations:Coronary artery bypass and valve repair demand sub-millimeter suture placement. Japanese specialty hospitals invest in robotic systems for these narrow-tolerance applications.
- Orthopedic Procedures:Arthroscopic rotator cuff and meniscal repair require specialized suturing angles.
- Gynecologic Treatments:Hysteroscopic and laparoscopic fertility procedures favor smaller-diameter devices.
- Plastic Surgery:Aesthetic and reconstructive closures prioritize cosmetic outcome minimization.
General surgery handles the majority of throughput; cardiothoracic operations command the steepest expansion trajectory.
End User:
Customer type determines financing structure and service bundling requirements.
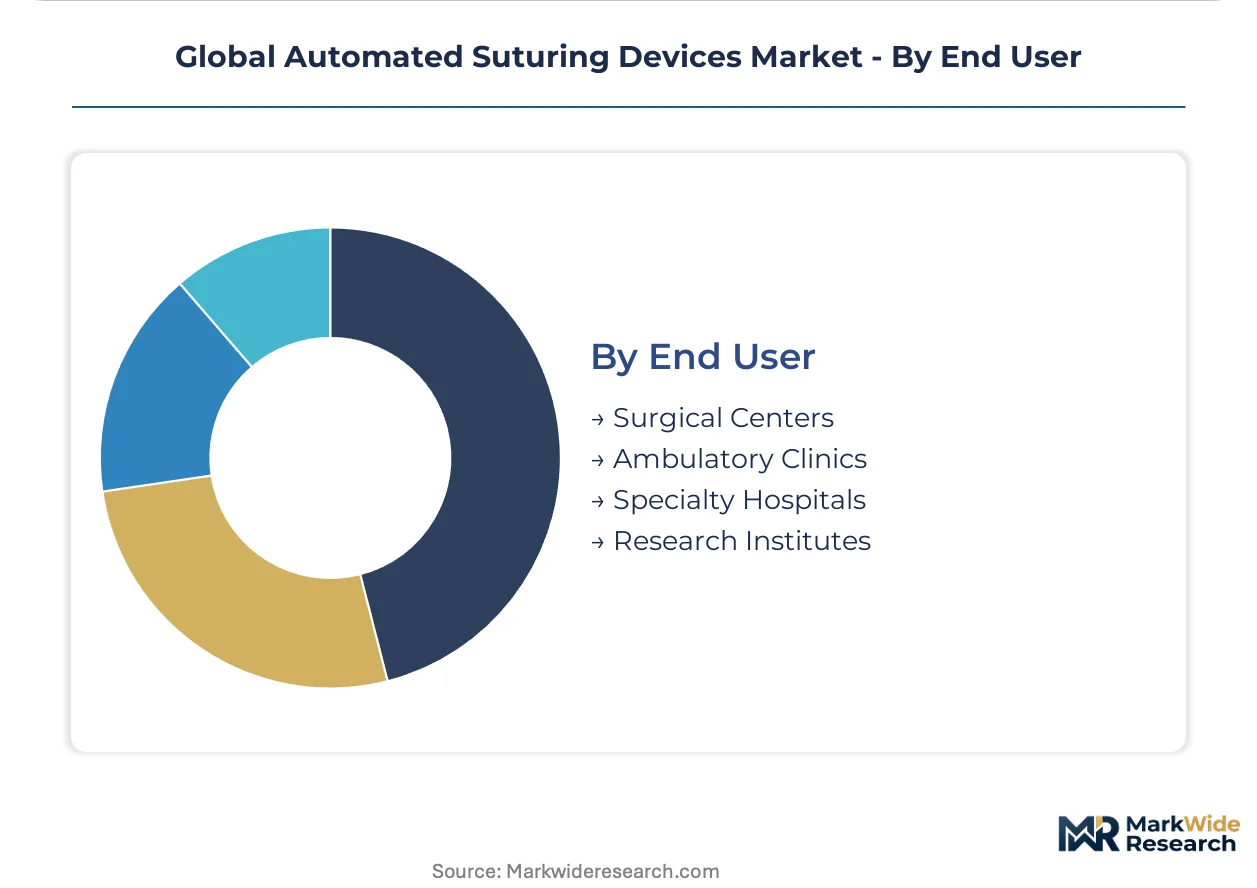
- Surgical Centers:High-volume facilities with established sterile processing infrastructure favor reusable equipment and capital purchase models.
- Ambulatory Clinics:Cost-conscious settings with constrained capital budgets drive disposable unit adoption.
- Specialty Hospitals:Cardiac and orthopedic-focused institutions invest in robotic suturing modules bundled with visualization platforms.
- Research Institutes:Academic medical centers pilot next-generation laser and thermal sealing technologies.
Surgical centers handle the majority of throughput; ambulatory clinics are climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives in the United States, Germany, and Japan are concentrating capital deployment toward operative efficiency technologies. FDA 510(k) pathways, EU MDR compliance frameworks, and Japan's PMDA biocompatibility protocols are reshaping product registration strategies across manufacturer portfolios.
United States
Medicare reimbursement pressure and ASC volume growth drive disposable unit adoption in high-frequency laparoscopic settings. FDA 510(k) clearance timelines extend commercialization cycles for novel suturing mechanisms. The Cleveland Clinic and Mayo Clinic surgical networks pilot robotic suturing modules bundled with capital equipment contracts.
Germany
Ambulatory surgical centers prioritize handheld electromechanical devices for cost-conscious laparoscopic closures. EU MDR technical documentation requirements elevate clinical evidence thresholds for CE marking authorization. The Munich-Bavaria medical technology cluster hosts specialized sterilization infrastructure for precision-engineered reusable instruments.
Japan
Specialty hospitals invest in robotic systems for cardiac microsurgery applications demanding sub-millimeter precision. PMDA maintains distinct biocompatibility testing protocols that force parallel validation programs. Tokyo's Keiyō industrial corridor concentrates surgical robotics R&D facilities serving the domestic market.
United Kingdom
NHS England procurement departments unbundle after-sales service from capital equipment contracts to reduce fixed costs. MHRA post-Brexit regulatory divergence from EU MDR creates dual compliance burdens for manufacturers. London's academic medical centers pilot next-generation laser-assisted closure technologies.
South Korea
Mid-tier hospitals adopt operating lease structures for robotic surgical suites to bypass capital constraints. MFDS registration protocols require localized biocompatibility validation separate from PMDA pathways. Seoul's Digital Healthcare Cluster attracts manufacturers establishing Asia-Pacific technical documentation centers.
Global Automated Suturing Devices Market Competitive Landscape
On the supply side, the industry is consolidating around diversified medtech conglomerates with pre-existing surgical robotics installed bases and specialized precision engineering firms with reusable device expertise. Three strategic archetypes dominate: capital equipment bundlers leveraging robotics platforms, orthopedic integration specialists, and cost-focused reusable instrument manufacturers. Competitive moves concentrate on M&A for technical documentation libraries and strategic partnerships for Asia-Pacific registration support.
Within the capital equipment bundler tier, Medtronic and Boston Scientific Corporation exemplify scale-driven positioning through robotics platform integration. Smith & Nephew occupies a specialist position anchoring orthopedic arthroscopy applications. Among precision-engineered reusable device manufacturers, Sutrue represents the cost-optimization archetype targeting mid-tier surgical centers with reduced per-procedure supply economics.
| Leading Market Players |
|---|
| Medtronic |
| Smith & Nephew |
| Boston Scientific Corporation |
| Ethicon |
| B. Braun |
| Sutrue |
| Apollo Endosurgery |
| BD |
| LSI Solutions |
| Others |
Supply & Pricing Matrix
The Keihin industrial corridor connecting Tokyo to Yokohama imposes freight cost premiums that concentrate supply planning around Japan's PMDA-registered facilities, compressing margins for manufacturers without localized sterilization infrastructure while amplifying price spreads between FDA-grade and standard CE-marked device tiers across German and United States procurement channels.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE MDR-grade) creates the primary spread between premium robotic suturing modules and economy handheld units. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service unbundling and software update subscriptions. Cost compression in the disposable cartridge segment intensifies because ambulatory surgical centers in Germany negotiate volume-based procurement contracts. Mid-tier surgical centers in Japan exhibit highest price sensitivity, while cardiac specialty hospitals in the United States demonstrate lowest sensitivity due to bundled capital equipment financing.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized EMS providers in Germany, Japan, and the United States holding ISO 13485-certified cleanroom capacity for electromechanical assembly. Precision servo motors, biocompatible polymers, and surgical-grade stainless steel feed from discrete supplier networks. Single-source vulnerability concentrates in Japanese suppliers of miniature drive systems. Distribution runs through hospital procurement consortia and GPO contracts in the United States, direct tender processes in Germany, and specialty distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation requirements and FDA 510(k) pathway extensions constitute a dual regulatory inflection that will consolidate competitive positioning around firms with pre-existing quality management infrastructure and technical documentation libraries.
For Market Incumbents: Entrench market position by deepening backward integration into biocompatible polymer compounding and captive sterilization capacity in Germany's Munich-Bavaria cluster. Acquire technical documentation libraries from distressed mid-cap competitors facing EU MDR reclassification costs. Prioritize certification investment in Japan's PMDA parallel validation protocols to preempt emerging entrant access. For New Entrants and Emerging Players: Mid-tier surgical centers in South Korea represent the most penetrable entry point given MFDS registration protocols that favor localized biocompatibility validation partnerships. Orthopedic arthroscopy applications for sports medicine procedures remain underdeveloped relative to cardiac and general surgery saturation. Pursue go-to-market angles through operating lease structures for robotic suturing modules that bypass hospital capital budget constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates with legacy suturing product lines facing EU MDR Class III reclassification burdens. Long-term viability over the next decade hinges on reimbursement coding resolution for robotic-assisted procedures across Medicare and NHS England fee schedules. Monitor FDA 510(k) clearance timelines for novel barbed suture mechanisms as the primary inflection indicator for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Accelerates market access for manufacturers with pre-existing quality systems in Germany. |
| Hospital System Partnership | Bundles suturing modules with visualization platforms at Cleveland Clinic and Mayo Clinic networks. |
| Reimbursement Strategy | Secures favorable coding for robotic-assisted procedures in Medicare and NHS England schedules. |
| Software Companion Development | Enables programmable needle trajectory updates for cardiac microsurgery applications in Japan. |
| CE Marking Pathway | Validates barbed suture biocompatibility for accelerated adoption in German ambulatory centers. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records preceded structured interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from PMDA registration filings, MFDS biocompatibility protocols, and CMS reimbursement coding updates. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Assumption sets held regulatory pathway timelines and reimbursement coding stability fixed while varying ambulatory surgical center adoption rates and robotic suite financing penetration across the analysis window. Segmentation dimensions modeled include product architecture (handheld versus robotic), technology mechanism (barbed versus standard suture), procedural application (general surgery versus cardiothoracic versus orthopedic), and end-user type (surgical center versus ambulatory clinic). CAGRs derived from logistic adoption curves fitted to historical laparoscopic procedure growth patterns and capital equipment replacement cycles.
Stress conditions across FDA clearance timeline extensions, EU MDR reclassification severity, and Japan's PMDA biocompatibility protocol changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and could revise upon reimbursement coding determinations by Medicare or NHS England. Quarterly review of 510(k) submission volumes and MDR technical documentation approval rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tissue Embedding Center Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
Annuloplasty System Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market