
 Microplate Luminometer Market | 2026-2036
Microplate Luminometer Market Size, Share, and Industry Trends Forecast 2026-2036
Microplate Luminometer Market Foresight
China is narrowing its technology gap in microplate luminometer component manufacturing, particularly in photomultiplier tube assemblies and precision optical filters. Thermo Fisher Scientific leverages its integrated life sciences platform to sustain instrument placement across pharmaceutical and academic accounts. PerkinElmer anchors its position through deep specialization in chemiluminescence detection modules for drug discovery workflows. BioTek Instruments competes by extending its multi-mode reader architecture into lower-throughput research segments.
A microplate luminometer is an analytical instrument that quantifies light emission from samples arranged in standardized 96-, 384-, or 1536-well microplates, utilizing photomultiplier tubes or charge-coupled devices to detect chemiluminescent, bioluminescent, or fluorescent signals with detection limits reaching femtomolar concentrations. The device serves as a workhorse platform for high-throughput screening, immunoassay quantification, and reporter gene assays in pharmaceutical and clinical laboratories. Multi-mode instruments dominate installed bases because they consolidate luminescence, fluorescence, and absorbance measurements into single platforms, reducing capital expenditure and bench space requirements for resource-constrained facilities. Portable and hybrid configurations represent the fastest-expanding product categories, driven by decentralized clinical testing and field-based environmental monitoring applications that demand battery-operated, lightweight detection hardware.
FDA bioanalytical method validation guidelines, EPA environmental monitoring protocols, and ISO 13485 quality management standards collectively shape instrument performance specifications, software validation requirements, and market access pathways for microplate luminometer manufacturers serving regulated industries. The EU In Vitro Diagnostic Regulation and MDR frameworks impose additional conformity assessment burdens on systems deployed in European clinical diagnostics settings, extending certification timelines and elevating documentation intensity. Stakeholders must monitor evolving harmonization efforts between FDA and EMA bioanalytical guidance documents, as divergence in acceptance criteria for luminescence-based assays could fragment instrument specification requirements across major pharmaceutical markets.
Market Dynamics
High-throughput screening consolidation across pharmaceutical pipelines is compressing procurement cycles for detection hardware, forcing vendors to bundle multi-mode capabilities into single-platform contracts or risk displacement from core laboratory infrastructure.
Growth Catalysts
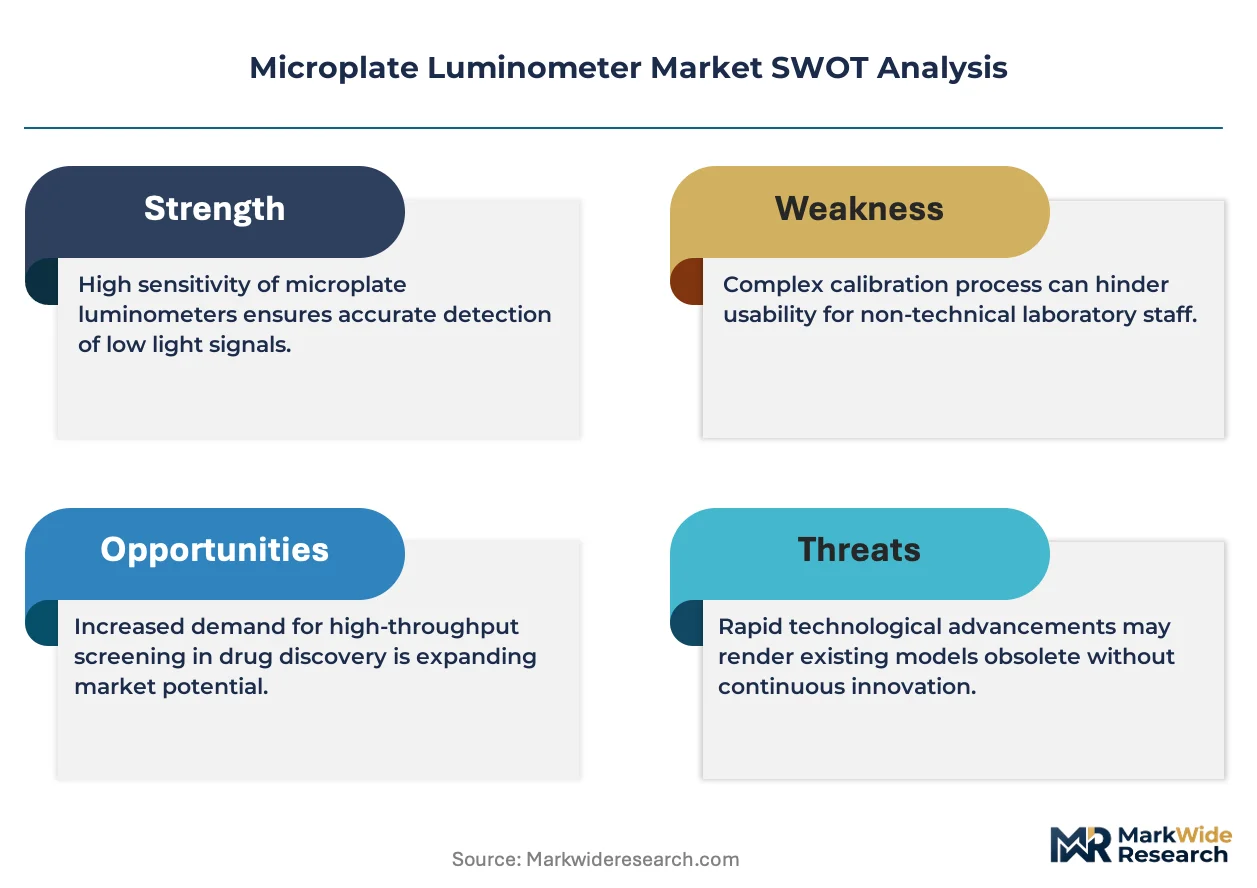
- FDA Bioanalytical Method Validation:Tightened luminescence assay acceptance criteria are mandating sensitivity upgrades across contract research organization fleets, driving replacement demand for older single-mode instruments.
- Photomultiplier Tube Assembly Localization:China's precision optical component manufacturing is reducing sensor procurement costs for mid-tier instrument builders, expanding addressable market penetration in academic laboratories.
- Decentralized Clinical Testing:Battery-operated portable luminometers are penetrating point-of-care infectious disease diagnostics, creating new deployment channels outside traditional core lab settings.
Market Restraints
- Photomultiplier Tube Supply Concentration:Japanese and Russian vacuum tube manufacturers control critical photodetector supply, exposing instrument builders to single-source fragility and extended lead times.
- ISO 13485 Certification Burden:Clinical diagnostic luminometer deployments require 18-24 month quality management system audits, delaying revenue recognition and elevating working capital requirements for manufacturers.
- Fluorescence Detection Substitution:Time-resolved fluorescence modules in competing multi-mode readers are capturing immunoassay workflows previously dominated by chemiluminescence methods.
Strategic Opportunities
- Environmental Field Monitoring:EPA water quality surveillance mandates are creating demand for IP65-rated portable luminometers capable of ATP bioluminescence testing outside laboratory environments.
- AI-Assisted Assay Optimization:Machine learning integration with luminometer software is enabling real-time well-to-well variation correction, differentiating premium instrument tiers from commodity detection hardware.
- India Contract Research Expansion:CDSCO streamlined medical device registration pathways are accelerating market entry for multi-mode readers serving domestic pharmaceutical outsourcing clusters in Hyderabad and Bangalore.
Industry Challenges
- Optomechanical Calibration Expertise Scarcity:Precision alignment of photomultiplier tube assemblies requires specialized photonics technicians, constraining manufacturing scale-up and service network expansion.
- Legacy LIMS Integration Complexity:Pharmaceutical buyers demand seamless data transfer to validated laboratory information management systems, forcing vendors to maintain expensive backward-compatible software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplate Luminometer Market |
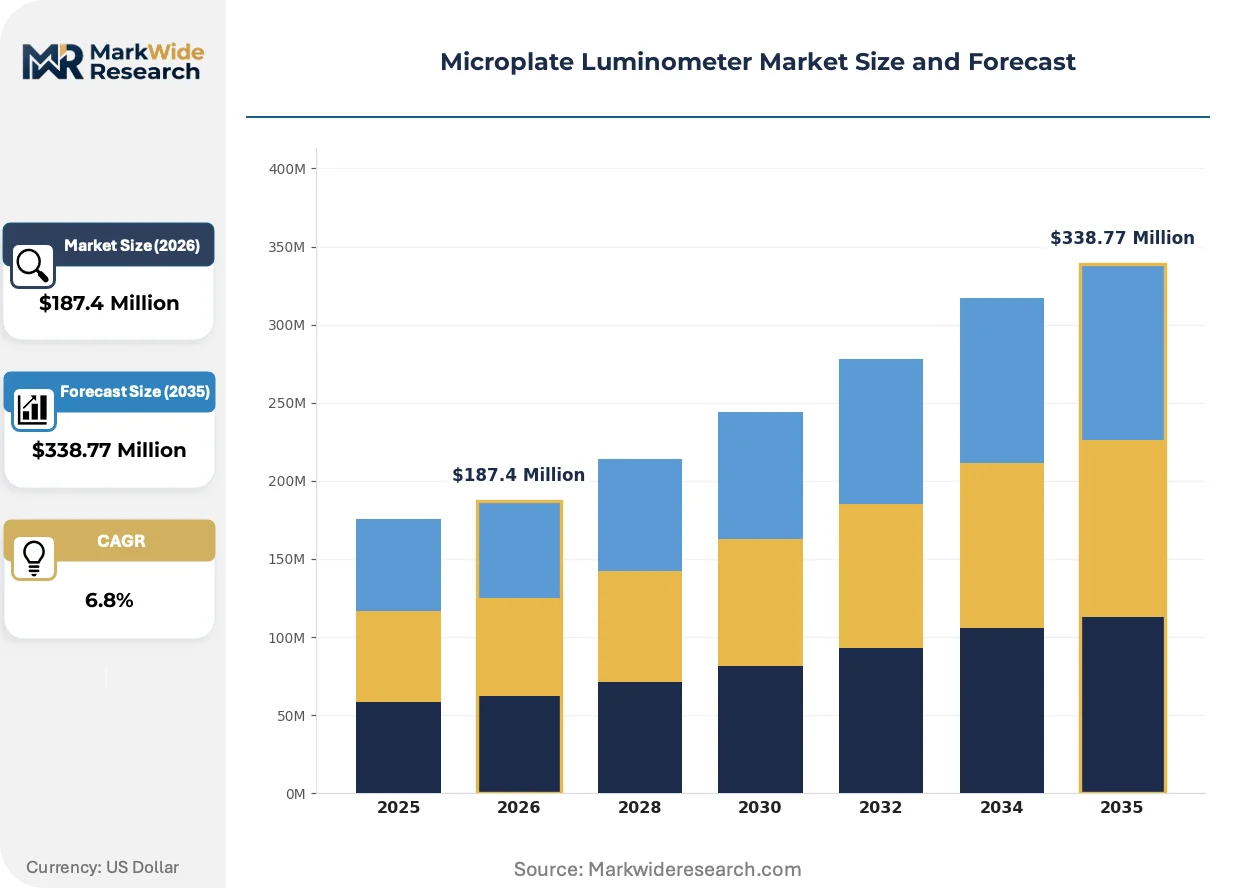
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Hybrid, Portable Technology: Chemiluminescence, Bioluminescence, Fluorescence, Luminance Application: Drug Discovery, Clinical Diagnostics, Environmental Testing, Food Safety End User: Research Labs, Pharmaceutical Companies, Clinical Laboratories, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific, PerkinElmer, BioTek Instruments, Agilent Technologies, Tecan Group, BMG LABTECH, Berthold Technologies, Danaher Corporation, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplate Luminometer Market Shifts & Advancements
Detection modality convergence and miniaturization are redrawing competitive boundaries between dedicated luminometer specialists and multi-mode platform vendors, while regulatory data integrity requirements are embedding compliance features deeper into instrument firmware.
CMOS sensor arrays with cooled deep-depletion architectures are achieving photon-counting sensitivity previously exclusive to vacuum photomultiplier tubes. Academic core facilities and mid-tier pharmaceutical screening groups are adopting these solid-state detectors for 384-well throughput applications. The shift is rendering obsolete traditional photomultiplier tube maintenance contracts and their associated service revenue streams for legacy instrument installed bases.
EMA bioanalytical guidance harmonization efforts with FDA are tightening cross-Atlantic acceptance criteria for luminescence-based pharmacokinetic assays. European contract research organizations must now demonstrate equivalence between instrument platforms across multiple detection modes, elevating documentation burdens and extending validation timelines. Multi-mode reader vendors with pre-validated software modules are capturing preference in EMA-regulated submission workflows.
Instrument-as-a-service contracting is displacing capital purchase models among early-stage biotechnology companies with constrained balance sheets. Leasing providers bundle preventive maintenance, reagent supply, and assay development support into per-plate pricing structures. This model concentrates in Boston and San Francisco metropolitan clusters where venture-backed drug discovery startups prioritize operational flexibility over asset ownership.
Microplate Luminometer Market Segmentation
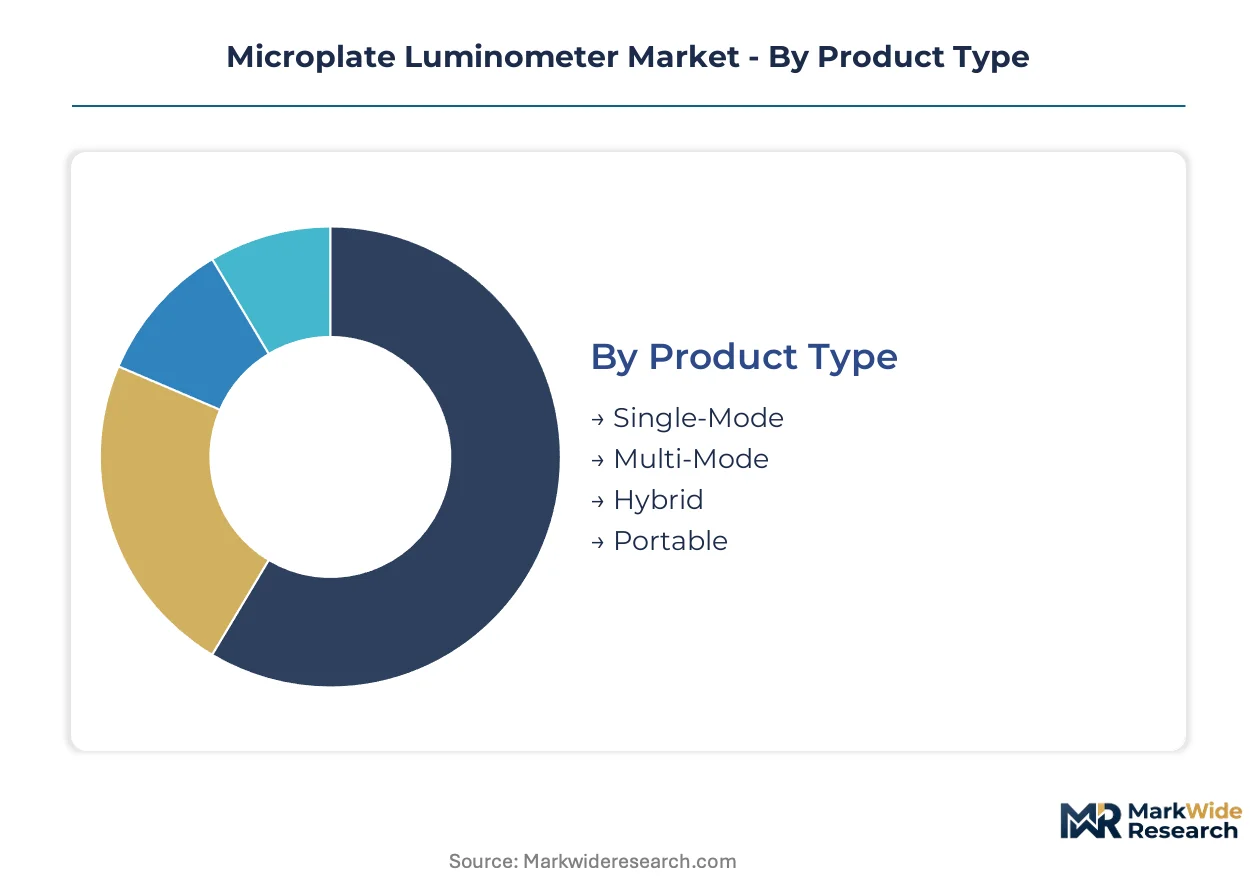
Microplate luminometer procurement patterns diverge sharply across detection modality, throughput requirement, and regulatory exposure. Vendors must configure product architectures to match distinct sensitivity specifications and workflow integration demands.
Product Type:
Instrument selection tracks the tension between dedicated performance and operational flexibility across laboratory infrastructure tiers.
- Multi-Mode:These platforms consolidate chemiluminescence, fluorescence, and absorbance detection into single hardware footprints. Pharmaceutical screening facilities in the United States favor multi-mode contracts to compress capital expenditure and reduce bench space allocation.
- Single-Mode:Dedicated luminometers deliver superior detection limits for high-sensitivity pharmacokinetic assays. Contract research organizations facing FDA bioanalytical validation mandates maintain single-mode fleets for regulated bioanalysis workflows.
- Hybrid:Configurations combine microplate formats with alternative sample presentation modes. Environmental monitoring agencies deploy hybrid systems for ATP bioluminescence testing outside fixed laboratory infrastructure.
- Portable:Battery-operated units with IP65 environmental sealing enable point-of-care infectious disease diagnostics. Decentralized clinical testing networks in India and Brazil are scaling portable deployments for field-based screening programs.
The dominant share belongs to Multi-Mode, while Portable is closing the gap fastest.
Technology:
Detection chemistry selection determines instrument specification, reagent compatibility, and downstream data interpretation requirements.
- Chemiluminescence:Enzyme-amplified light emission enables femtomolar detection limits for immunoassay quantification. High-throughput screening groups at pharmaceutical companies standardize on chemiluminescence for reporter gene assays and cell viability measurements.
- Bioluminescence:ATP-dependent luciferase reactions support rapid microbial contamination testing. Food safety laboratories across the European Union deploy bioluminescence-based luminometers for HACCP verification and environmental hygiene monitoring.
- Fluorescence:Excitation-emission detection expands multiplexing capacity for multi-analyte panels. Academic core facilities integrate fluorescence modules to consolidate nucleic acid quantification and protein binding assays.
- Luminance:Direct photon counting without enzymatic amplification serves specialized glow-type assay formats. Niche applications include oxidative stress research and reactive oxygen species detection in toxicology studies.
Chemiluminescence commands the largest installed base, though Bioluminescence is expanding most quickly in food safety and environmental compliance testing.
Application:
End-use verticals impose distinct throughput, sensitivity, and documentation requirements that shape instrument specification.
- Drug Discovery:Ultra-high-throughput screening demands 1536-well compatibility and sub-second read times. Boston and San Francisco metropolitan clusters concentrate automated luminometer procurement for target validation and lead optimization workflows.
- Clinical Diagnostics:In vitro diagnostic deployments require ISO 13485 quality management certification and traceable calibration protocols. CDSCO registration pathways in India are accelerating multi-mode reader adoption for domestic diagnostic manufacturing.
- Environmental Testing:EPA water quality surveillance mandates drive demand for ruggedized portable detection hardware. ATP bioluminescence testing of recreational water sources represents a standardized compliance application.
- Food Safety:Rapid microbial detection requirements align with bioluminescence-based hygiene verification systems. Processing facilities integrate luminometers into environmental monitoring programs to satisfy regulatory audit expectations.
Drug Discovery retains the dominant revenue position, while Clinical Diagnostics is climbing the fastest on point-of-care decentralization trends.
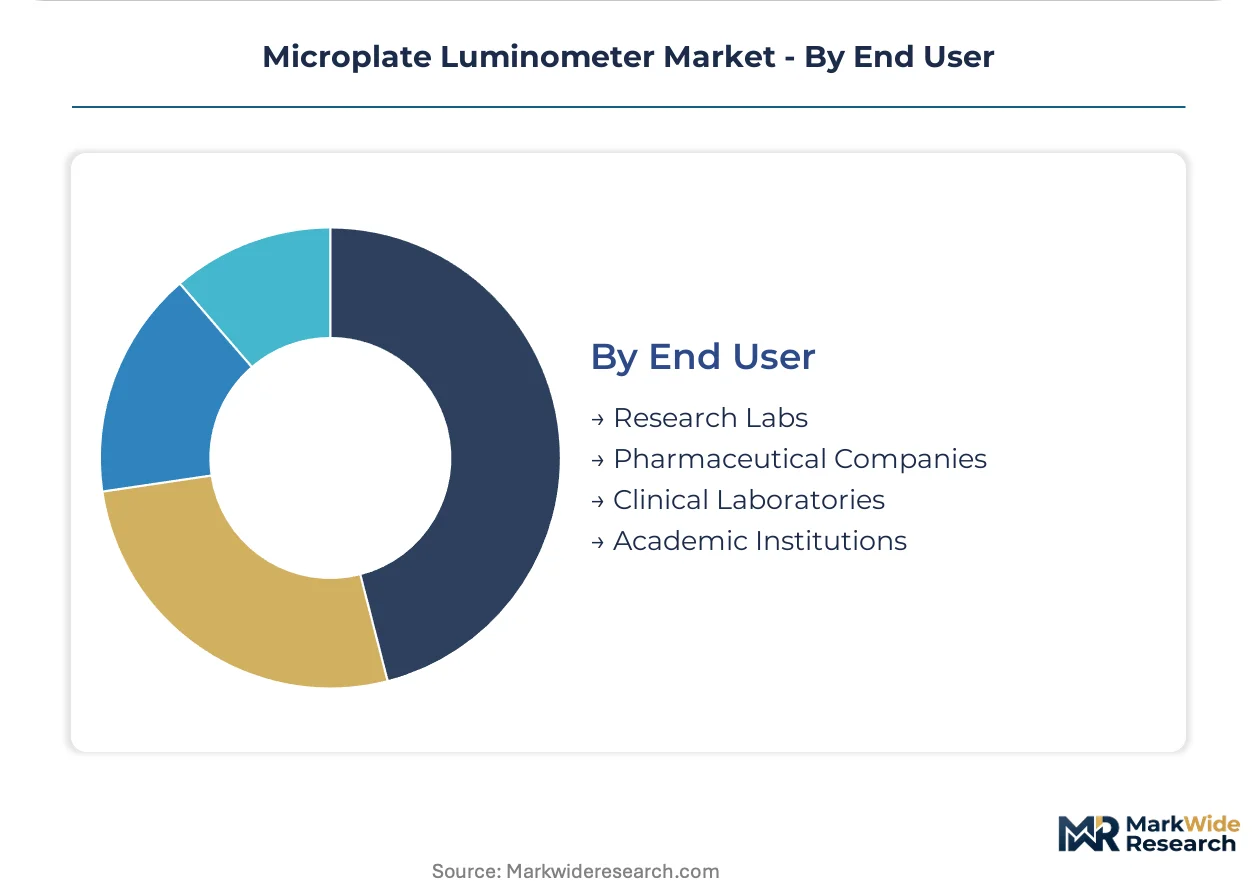
End User:
Procurement authority and budget cycles vary substantially across organizational categories, fragmenting vendor sales motion and support requirements.
- Pharmaceutical Companies:Centralized purchasing functions negotiate enterprise-wide detection platform contracts. Multi-year service agreements with guaranteed uptime provisions predominate in large-cap pharmaceutical accounts.
- Research Labs:Principal investigator-driven acquisition favors modular upgrade paths and flexible financing. Core facility managers prioritize interoperability with existing liquid handling robotics and LIMS infrastructure.
- Clinical Laboratories:Hospital system procurement committees evaluate total cost of ownership across reagent and maintenance contracts. IVD-registered instruments command premium positioning in clinical diagnostic workflows.
- Academic Institutions:Grant-funded acquisition cycles concentrate in federal fiscal year windows. Shared equipment facilities distribute capital costs across multiple research groups, favoring multi-mode versatility.
Pharmaceutical Companies hold the dominant procurement volume, while Clinical Laboratories are gaining share fastest on infectious disease testing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photomultiplier tube assembly manufacturing concentrates in Japan and Russia, while precision optical filter production localizes in China. This supply geography shapes procurement costs and lead time exposures for instrument builders across end markets. Demand clusters concentrate where pharmaceutical screening infrastructure and clinical diagnostic networks scale fastest.
United States
FDA bioanalytical method validation mandates are forcing contract research organizations to upgrade single-mode instrument fleets for luminescence assay compliance. The 21 CFR Part 11 electronic records framework elevates software validation requirements for multi-mode reader deployments. Boston and San Francisco metropolitan clusters concentrate automated high-throughput screening procurement for target validation workflows.
Germany
EMA bioanalytical guidance harmonization with FDA is tightening cross-Atlantic acceptance criteria for pharmacokinetic luminescence assays. The EU In Vitro Diagnostic Regulation imposes extended conformity assessment timelines on clinical diagnostic luminometer registrations. Bavaria and Baden-Württemberg host precision photonics manufacturing clusters supplying optical component assemblies to mid-tier instrument builders.
China
Domestic precision optical component manufacturing is narrowing technology gaps in photomultiplier tube assemblies and filter fabrication. NMPA streamlined medical device registration pathways are accelerating multi-mode reader adoption for domestic pharmaceutical outsourcing. Yangtze River Delta and Pearl River Delta clusters concentrate contract research expansion and academic core facility procurement.
India
CDSCO medical device registration streamlining is reducing market entry barriers for multi-mode reader vendors serving domestic diagnostic manufacturing. Government Production Linked Incentive schemes for pharmaceuticals are expanding high-throughput screening infrastructure in contract research clusters. Hyderabad and Bangalore concentrate pharmaceutical outsourcing facility construction and automated detection hardware procurement.
Japan
Domestic vacuum tube manufacturers control critical photodetector supply for global instrument builders, creating single-source procurement exposure. PMDA quality management requirements for in vitro diagnostics extend validation timelines for clinical luminometer deployments. Kanto and Kansai regions concentrate precision photonics manufacturing and pharmaceutical R&D facility instrumentation.
Microplate Luminometer Market Competitive Landscape
Integrated life sciences conglomerates and specialized detection module builders split the market between platform breadth and technical depth. Consolidation pressures favor vendors with validated multi-mode architectures capable of satisfying FDA and EMA bioanalytical requirements simultaneously. Two strategic archetypes dominate: diversified instrumentation platforms bundling luminescence with fluorescence and absorbance, and dedicated chemiluminescence specialists optimizing for regulated bioanalysis workflows. Competitive moves center on multi-mode capability bundling into single-platform contracts and AI-assisted assay optimization software differentiation.
Among diversified instrumentation platforms, Thermo Fisher Scientific and PerkinElmer occupy positions representing integrated life sciences and deep detection specialization archetypes respectively. BioTek Instruments exemplifies the modular multi-mode architecture approach extending into lower-throughput research segments. These three companies anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| PerkinElmer |
| BioTek Instruments |
| Agilent Technologies |
| Tecan Group |
| BMG LABTECH |
| Berthold Technologies |
| Danaher Corporation |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Photomultiplier tube supply concentration in Japanese and Russian vacuum tube manufacturers exposes instrument builders to single-source fragility, compressing pricing tier spreads between premium multi-mode systems and economy single-mode units while forcing vendors to absorb sensor procurement volatility or pass through cost escalation to price-sensitive academic buyers.
Pricing Analysis
FDA bioanalytical method validation dictates the pricing tier structure across the Microplate Luminometer Market, separating ISO 13485-certified clinical diagnostic platforms from research-grade instruments. Three-tier pricing structure across premium, standard, and economy levels reflects detection sensitivity specifications and software validation depth. Cost compression in the mid-tier segment is intensifying because CMOS sensor arrays are displacing vacuum photomultiplier tubes in 384-well applications. Academic institutions exhibit the highest price sensitivity, while pharmaceutical companies prioritize guaranteed uptime provisions over per-unit capital expenditure.
Supply Chain Analysis
Export controls on vacuum photodetector technology limit flows from Russian manufacturers, constraining global instrument builders to dual-source strategies. Precision optical component manufacturing concentrates in China, Japan, and Germany, with photomultiplier tube assemblies drawing from Japanese and Russian suppliers. Supply chain risk centers on single-source vulnerability for high-sensitivity photodetectors, compounded by extended lead times for specialized optical filters. Distribution runs through authorized dealer networks serving pharmaceutical accounts, direct sales forces for clinical diagnostic deployments, and academic core facility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as instrument-as-a-service contracting displaces capital purchase models, with interoperability demands from validated LIMS infrastructure becoming the primary ecosystem lock-in mechanism.
For Market Incumbents: Entrench multi-mode platform dominance by pre-validating software modules for simultaneous FDA and EMA bioanalytical submission workflows. Backward integration into precision optical filter fabrication reduces exposure to Chinese supply volatility. Defensive patenting around AI-assisted well-to-well variation correction preserves premium pricing tiers against CMOS-based commodity entrants.
For New Entrants and Emerging Players: Portable battery-operated luminometers for point-of-care infectious disease diagnostics in India and Brazil represent the most penetrable entry point, exploiting CDSCO and ANVISA registration streamlining. Environmental field monitoring applications with IP65-rated ATP bioluminescence hardware offer secondary white-space access. Go-to-market execution should prioritize per-plate leasing structures aligned with venture-backed biotechnology cash flow constraints.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified detection platform vendors over dedicated chemiluminescence specialists. Long-term viability over the next decade rests on multi-mode architecture scalability and software validation moats. Acquisition targets should demonstrate pre-installed base density in Boston and San Francisco metropolitan clusters. The signal to watch is EMA-FDA harmonization divergence on luminescence assay acceptance criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Mode Platform Integration | Consolidated detection capabilities reduce pharmaceutical capital expenditure and bench space allocation. |
| AI-Assisted Assay Optimization | Machine learning integration differentiates premium tiers through real-time well-to-well variation correction. |
| Instrument-as-a-Service Contracting | Per-plate pricing structures align with early-stage biotechnology operational flexibility requirements. |
| CMOS Sensor Array Adoption | Solid-state photon counting disrupts traditional photomultiplier tube maintenance revenue streams. |
| Environmental Field Certification | IP65-rated portable systems capture EPA water quality surveillance mandate demand outside laboratories. |
Research Methodology
The analysis maps multi-mode, single-mode, hybrid, and portable instrument configurations, each validated through instrument procurement directors at pharmaceutical companies, regulatory affairs leads at contract research organizations, academic core facility managers, and clinical laboratory directors. Primary interview intelligence combines with secondary validation from FDA bioanalytical guidance documents, EMA submission databases, ISO 13485 audit records, and NMPA registration filings. Bottom-up installed base enumeration and top-down pharmaceutical R&D expenditure allocation triangulate market sizing across detection modality segments.
Assumptions held fixed include continued FDA-EMA bioanalytical guidance convergence and sustained photomultiplier tube supply from Japanese manufacturers, while CMOS sensor performance trajectories and decentralized clinical testing adoption rates were varied across sensitivity scenarios. The projection framework models instrument placement by product type, technology chemistry, application vertical, and end-user category, with CAGRs derived from weighted average of segment growth rates calibrated to pharmaceutical screening infrastructure expansion. Forecast inputs incorporate CDSCO registration pathway acceleration and EPA environmental monitoring protocol evolution.
Practitioners should monitor photomultiplier tube export control expansion and EMA bioanalytical guidance divergence for early signals of supply constraint or regulatory fragmentation. Forecasts reflect these documented assumptions without contingency for abrupt trade policy shifts. Material shifts in vacuum photodetector supply availability or cross-Atlantic regulatory harmonization failure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Automated Blood Processing Equipment Market