
 Global Biologics Safety Testing Market | 2026-2036
Global Biologics Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biologics Safety Testing Market Foresight
Buyer concentration among contract research organizations is pivoting as large pharmaceutical manufacturers build captive safety testing capabilities. Thermo Fisher Scientific leverages its end-to-end bioproduction platform to anchor service relationships across North America and Europe. Charles River Laboratories competes through specialized virology and cell-based assay expertise that sustains premium positioning with mid-tier biotech clients. WuXi AppTec dominates Asia-Pacific outsourced testing through integrated chemistry and biology services that extend from discovery into commercial release.
Biologics safety testing encompasses analytical and biological methods used to detect contaminants, verify identity, and ensure sterility of protein-based, cell-based, and nucleic acid therapeutics, employing techniques such as Limulus amebocyte lysate assays for endotoxin quantification and quantitative PCR for adventitious virus detection to prevent patient harm and batch failures. Cell-based assays lead product type revenue due to their irreplaceable role in potency and cytotoxicity evaluation, while molecular diagnostics represents the fastest-expanding category as gene and cell therapy pipelines multiply. Among therapy areas, oncology commands the largest absolute spend on safety testing, though rare diseases concentrates margin pools because of smaller batch sizes and higher per-unit analytical intensity.
The FDA, EMA, and NMPA each mandate phased testing protocols that shape product development timelines and force manufacturers to validate methods against compendial standards before commercial approval. ISO 17025 accreditation and ICH Q5A guidelines further constrain which laboratories can participate in regulated biologics release programs. Stakeholders must monitor how gene therapy-specific guidance documents from FDA and EMA evolve, as these will determine whether existing safety testing infrastructure satisfies emerging vector purity requirements or demands entirely new analytical investments.
Market Dynamics
Gene therapy pipelines are forcing safety testing laboratories to validate entirely new analytical methods for vector purity and replication-competent virus detection, compressing method development timelines against regulatory submission deadlines.
Growth Catalysts
- FDA and EMA gene therapy guidance:Phased testing mandates for adeno-associated virus vectors require expanded adventitious agent screening, pulling demand toward specialized virology capacity.
- Cell-based assay automation:High-content imaging platforms reduce manual microscopy burden while preserving irreplaceable biological relevance for potency testing.
- China biologics manufacturing clusters:Suzhou and Shanghai production hubs deepen, creating concentrated demand for local release testing and stability programs.
Market Restraints
- Reference standard supply concentration:Horseshoe crab population constraints in the southeastern United States threaten Limulus amebocyte lysate raw material availability for endotoxin testing.
- ISO 17025 accreditation timelines:Eighteen-to-twenty-four-month validation cycles delay laboratory participation in commercial release programs.
- Recombinant factor C substitution limits:Synthetic endotoxin detection alternatives face pharmacopeial acceptance gaps that prevent full displacement of animal-derived methods.
Strategic Opportunities
- India CDSCO pathway acceleration:Biosimilar approval streamlining creates demand for comparability immunogenicity testing and biosafety evaluation.
- Continuous bioprocessing integration:Real-time in-line analytics convergence with at-line rapid microbiological methods enables parametric release models.
- Japan PMDA regenerative medicine framework:Conditional approval pathways for induced pluripotent stem cell therapies require novel tumorigenicity and karyotype stability assays.
Industry Challenges
- Vector analytical skill scarcity:Quantitative PCR and next-generation sequencing expertise for adeno-associated virus titer and empty-full ratio determination outstrips trained personnel supply.
- Legacy LIMS integration friction:Electronic batch record connectivity with automated liquid handling platforms demands costly middleware development for data integrity compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biologics Safety Testing Market |
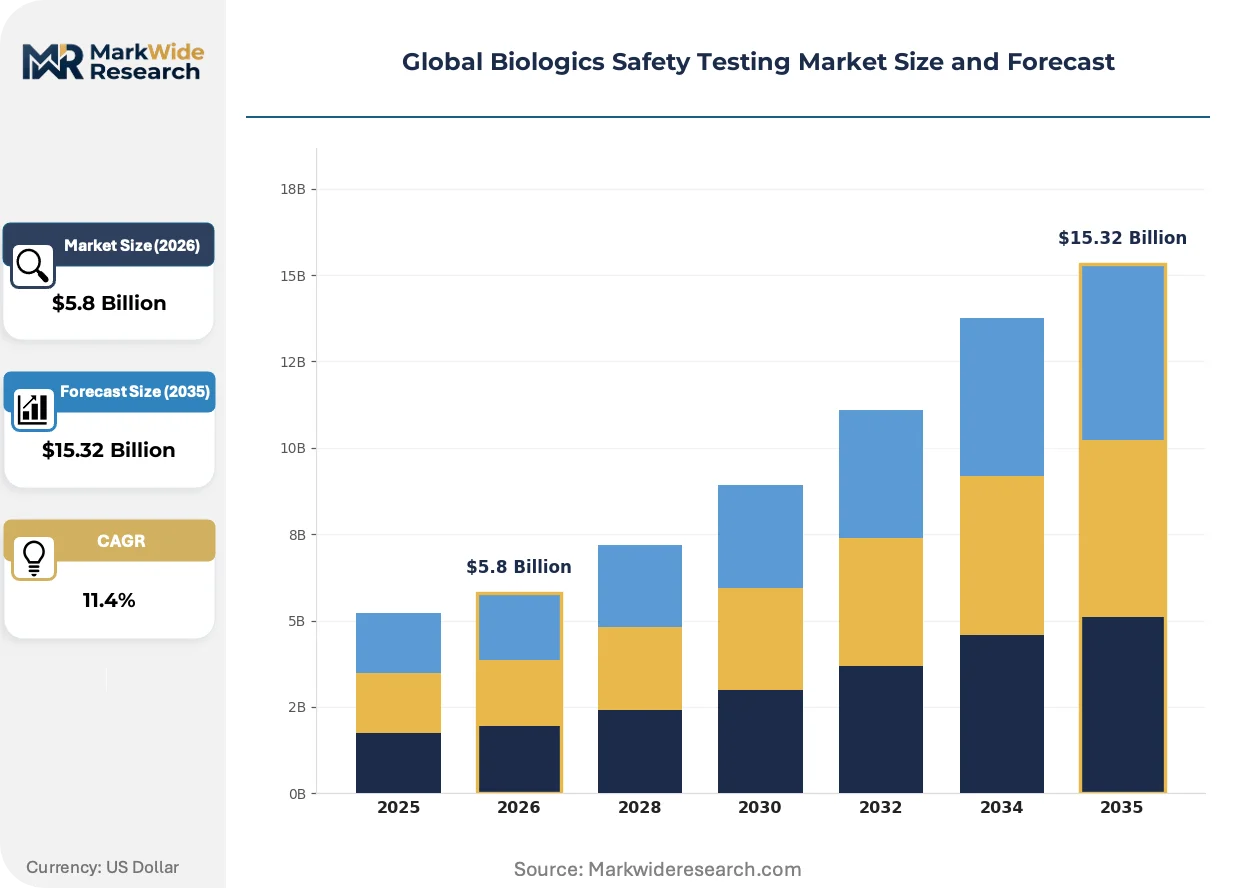
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell-based Assays, Immunoassays, Molecular Diagnostics, Microbial Testing, Chromatography Techniques, Others Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Rare Diseases, Neurological Conditions, Cardiovascular Disorders End User: Pharmaceutical Manufacturers, Contract Research Organizations, Regulatory Agencies, Biotech Firms, Academic Research Centers, Quality Control Labs Deployment: In-house Testing, Outsourced Testing, Hybrid Models, Mobile Labs |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Charles River Laboratories, Eurofins Scientific, Lonza Group, Sartorius AG, SGS Société Générale de Surveillance SA, bioMérieux, WuXi AppTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biologics Safety Testing Market Shifts & Advancements
Digitalization of biological assay workflows is compressing turnaround times while raising data integrity expectations, with artificial intelligence-assisted image analysis and cloud-based stability trending programs reshaping laboratory operations.
Next-generation sequencing for adventitious virus detection is rewriting safety testing economics. Contract testing organizations in Germany and the United States are adopting platform-based metagenomic screening to replace in vivo and in vitro virus panels. The structural consequence is collapsing multi-week traditional testing into days, enabling faster batch disposition but requiring massive bioinformatics infrastructure investment.
EMA's updated guideline on quality, non-clinical and clinical aspects of gene therapy medicinal products is tightening replication-competent virus detection requirements. Manufacturers must now demonstrate absence of replication-competent adenovirus or lentivirus below single-copy sensitivity. Small and mid-tier gene therapy developers in the Netherlands and Sweden are outsourcing to specialized virology laboratories rather than building captive capacity.
Consolidated procurement of safety testing services through preferred provider agreements is displacing transactional project-by-project contracting. Large pharmaceutical manufacturers in Massachusetts and Basel are negotiating multi-year master service agreements that bundle release testing, stability, and method development. This concentration is most visible in oncology biologics, where single sponsors now anchor significant portions of contract laboratory revenue.
Global Biologics Safety Testing Market Segmentation
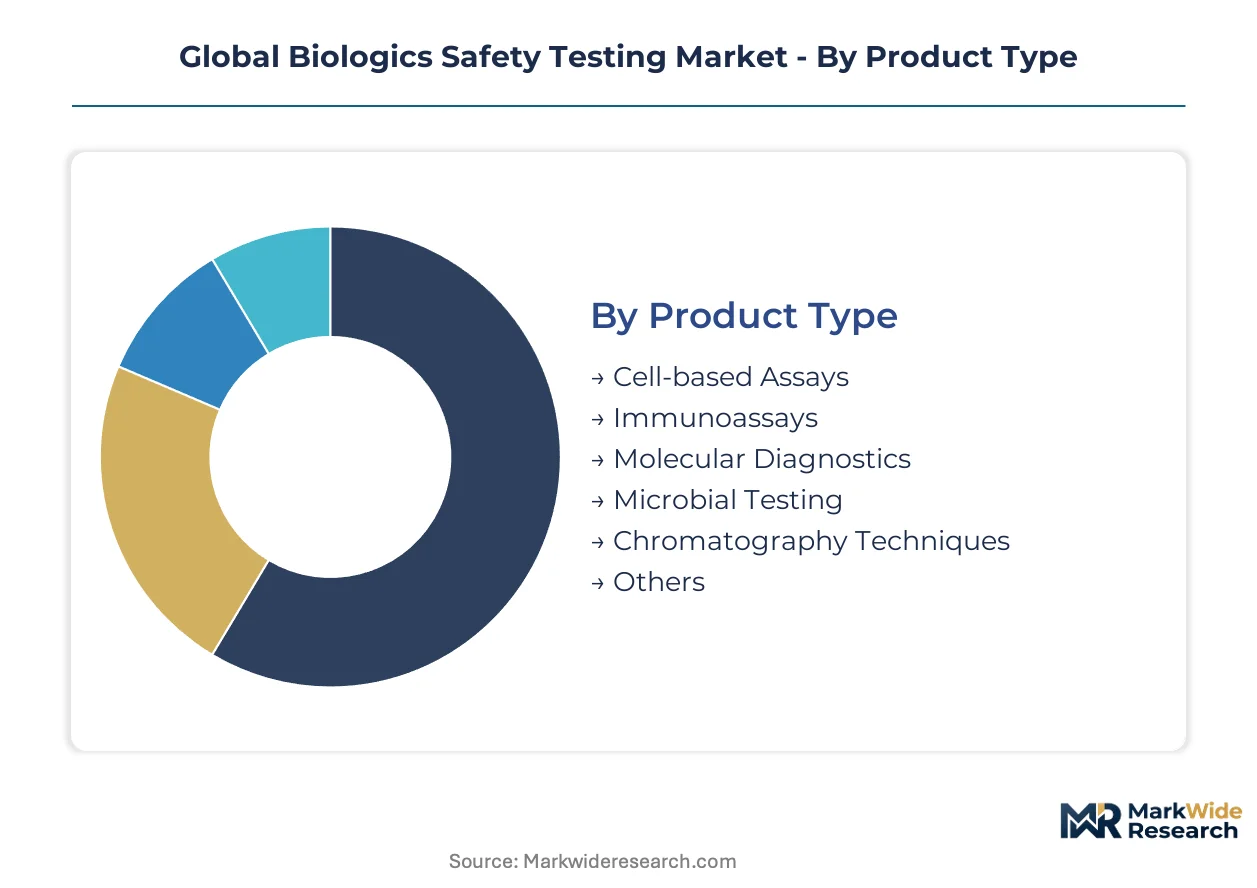
Biologics safety testing segments diverge sharply in regulatory burden, with cell-based assays and molecular diagnostics commanding distinct ISO 17025 and FDA validation pathways. Understanding these certification tiers enables manufacturers to align testing investments with pipeline risk profiles and commercial timelines.
Product Type:
FDA gene therapy guidance and EMA vector purity mandates impose tiered certification requirements, with adventitious agent screening methods facing steeper validation hurdles than traditional endotoxin detection.
- Cell-based Assays:Functional potency and cytotoxicity evaluation relies on primary cell cultures and reporter gene systems that resist full automation. Demand concentrates among mid-tier biotech developers in Massachusetts and Basel seeking irreplaceable biological relevance for IND-enabling studies.
- Molecular Diagnostics:Quantitative PCR and next-generation sequencing platforms detect replication-competent virus and vector titer with single-copy sensitivity. Gene therapy sponsors in the Netherlands and Sweden are outsourcing these methods rather than building captive bioinformatics infrastructure.
- Immunoassays:ELISA and electrochemiluminescence formats quantify host cell protein impurities and product identity with established pharmacopeial recognition.
- Microbial Testing:Sterility and bioburden methods using traditional culture and rapid microbiological alternatives support batch release across mammalian cell production.
- Chromatography Techniques:Size-exclusion and ion-exchange methods separate aggregate species and charge variants for monoclonal antibody quality control.
- Others:Mass spectrometry and capillary electrophoresis address specialized characterization needs for complex glycoprotein therapeutics.
Leading the category by volume: Cell-based Assays. Growing fastest: Molecular Diagnostics.
Therapy Area:
Oncology biologics generate absolute testing volume through large-batch manufacturing, while rare disease programs concentrate margin through higher per-unit analytical intensity and specialized release protocols.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates require extensive potency and immunogenicity testing across multi-site manufacturing networks. Large pharmaceutical sponsors in Germany and the United States anchor contract laboratory revenue through consolidated procurement agreements.
- Rare Diseases:Enzyme replacement therapies and gene therapies for small patient populations demand customized assays with limited reference standard availability. Developers face compressed timelines where batch failures carry disproportionate commercial consequences.
- Autoimmune Disorders:Biosimilar monoclonal antibodies for rheumatoid arthritis and multiple sclerosis require comparability immunogenicity testing against originator products.
- Infectious Diseases:Vaccine and antiviral biologics necessitate adventitious agent screening with enhanced sensitivity for blood-derived raw materials.
- Neurological Conditions:Alzheimer's and Parkinson's biologics present blood-brain barrier penetration challenges that complicate potency assay design.
- Cardiovascular Disorders:Recombinant proteins and cell therapies for heart failure require specialized stability programs under ICH Q5C guidelines.
Category anchor by revenue: Oncology. Steepest expansion trajectory: Rare Diseases.
End User:
Pharmaceutical manufacturers and contract research organizations occupy opposite ends of a capability-building spectrum, with captive investment decisions shaped by pipeline scale and regulatory jurisdiction concentration.
- Pharmaceutical Manufacturers:Large sponsors in China and Switzerland are deepening in-house virology and cell-based assay capacity to secure supply chains and reduce release testing dependencies. Suzhou production hubs now anchor regional quality control infrastructure.
- Contract Research Organizations:Specialized testing providers in Germany and the United States compete through ISO 17025 accreditation breadth and gene therapy method validation expertise that mid-tier developers cannot replicate economically.
- Regulatory Agencies:FDA, EMA, and NMPA reference laboratories set compendial standards and proficiency testing programs that shape commercial laboratory qualification requirements.
- Biotech Firms:Venture-backed developers in Cambridge and South San Francisco rely on outsourced testing through discovery into Phase II, delaying captive build decisions.
- Academic Research Centers:University-affiliated laboratories contribute early-stage method development and training pipelines for specialized analytical techniques.
- Quality Control Labs:Dedicated release testing facilities at manufacturing sites execute validated protocols under GMP documentation requirements.
Dominant volume share: Pharmaceutical Manufacturers. Fastest capability expansion: Contract Research Organizations.
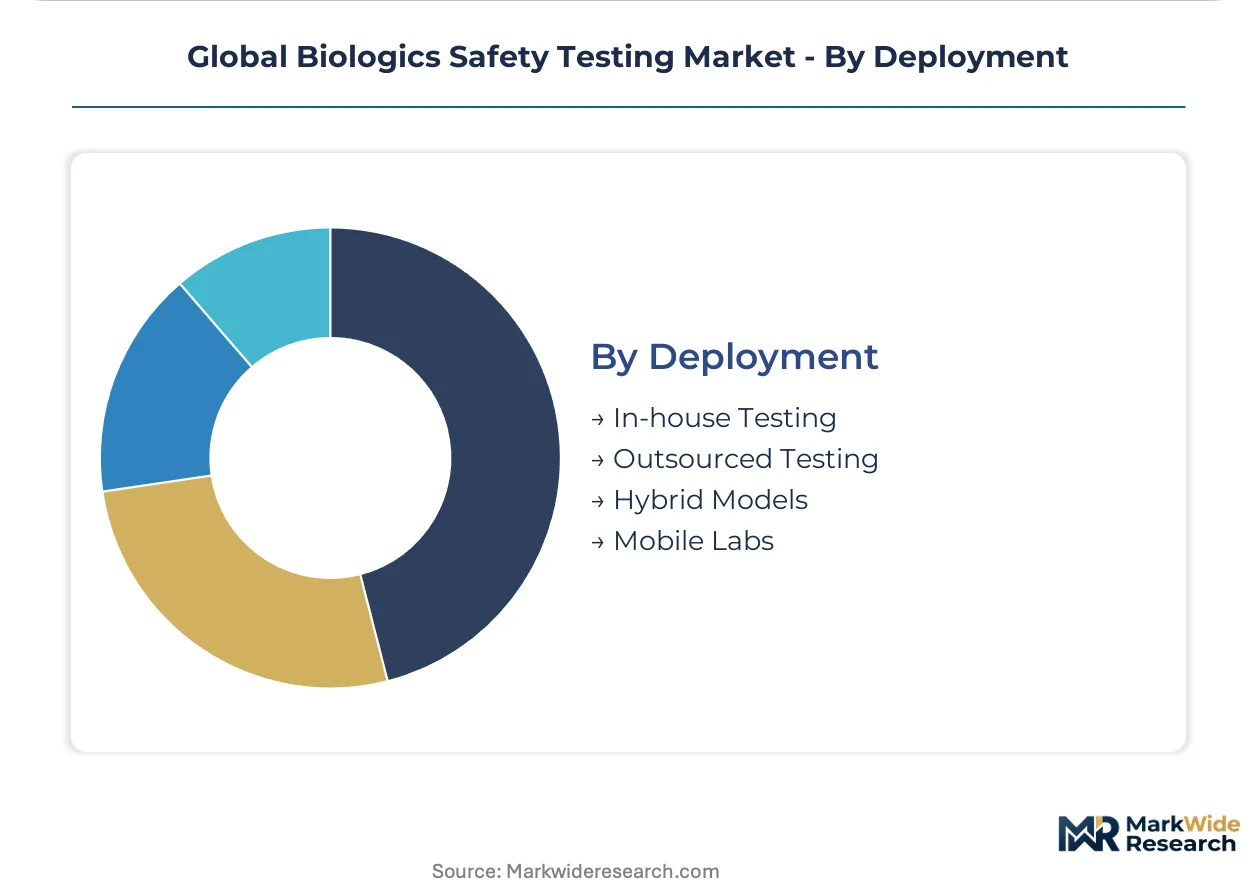
Deployment:
Hybrid testing models are gaining traction as manufacturers balance control over critical release methods against capital efficiency in specialized virology and sequencing applications.
- In-house Testing:Captive endotoxin and sterility methods at manufacturing sites enable immediate batch disposition with reduced logistics risk. Thermo Fisher Scientific and Charles River Laboratories anchor platform relationships that defend against full insourcing.
- Outsourced Testing:Adventitious agent screening and gene therapy vector characterization concentrate at specialized laboratories with NGS infrastructure and trained bioinformatics personnel that replicate uneconomically at single-sponsor scale.
- Hybrid Models:Manufacturers retain routine release testing while contracting novel method development and stability programs, optimizing capital deployment across pipeline phases.
- Mobile Labs:Containerized rapid microbiological methods support distributed manufacturing in emerging biologics clusters with limited local testing infrastructure.
Prevalent configuration: Hybrid Models. Fastest structural shift: Outsourced Testing for gene therapy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for biologics safety testing concentrates in manufacturing clusters where gene therapy and monoclonal antibody production co-locate with specialized analytical capacity. The United States, Germany, China, Switzerland, and Japan anchor this geographic pattern through distinct regulatory and industrial configurations.
United States
Massachusetts and California biotech corridors drive outsourcing demand for adventitious agent screening and vector characterization. FDA gene therapy guidance mandates phased testing protocols that compress method development timelines against IND submission deadlines. The greater Boston area anchors specialized virology laboratory capacity serving venture-backed developers.
Germany
Rhineland and Bavarian pharmaceutical manufacturing hubs deepen in-house endotoxin and sterility testing to secure supply chains. EMA vector purity requirements for replication-competent virus detection pull demand toward accredited contract laboratories with next-generation sequencing infrastructure. Heidelberg and Munich clusters concentrate gene therapy sponsor activity requiring local release testing partnerships.
China
Suzhou and Shanghai production facilities expand quality control infrastructure as NMPA biologics approval pathways mature. CDSCO-aligned biosimilar developers seek comparability immunogenicity testing as domestic manufacturing scales. Yangtze River Delta biologics parks now anchor regional captive safety testing buildouts.
Switzerland
Basel pharmaceutical headquarters drive consolidated procurement of multi-year safety testing service agreements. Swissmedic gene therapy frameworks align with EMA standards while maintaining distinct validation requirements for commercial release. The Basel-Zurich corridor concentrates oncology biologics manufacturing demanding integrated stability and potency programs.
Japan
Kanto region regenerative medicine developers require novel tumorigenicity assays under PMDA conditional approval pathways for induced pluripotent stem cell therapies. Tokyo-Osaka manufacturing networks balance in-house microbial testing against outsourced molecular diagnostics for vector-based products. Japanese sponsors prioritize ISO 17025-accredited partners with ICH Q5A validation depth.
Global Biologics Safety Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gene therapy specialization and automated assay platforms. The market structures around three maturity tiers: integrated bioproduction platform providers, specialized virology and cell-based assay laboratories, and regional quality control service networks. Consolidation pressure intensifies as large pharmaceutical manufacturers negotiate preferred provider agreements bundling release testing, stability programs, and method development. Capacity expansion and strategic partnerships dominate competitive maneuvering, with laboratories investing in next-generation sequencing infrastructure and high-content imaging automation to defend service relationships.
Among integrated platform providers, Thermo Fisher Scientific anchors end-to-end bioproduction relationships across North America and Europe. Charles River Laboratories exemplifies specialized virology expertise sustaining premium positioning with mid-tier biotech developers. WuXi AppTec occupies the Asia-Pacific outsourced testing tier through integrated chemistry and biology services extending from discovery into commercial release. These three entities represent distinct competitive archetypes: platform integration, specialized biological expertise, and regional scale with vertical service extension.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Charles River Laboratories |
| Eurofins Scientific |
| Lonza Group |
| Sartorius AG |
| SGS Société Générale de Surveillance SA |
| bioMérieux |
| WuXi AppTec |
| Others |
Supply & Pricing Matrix
EMA's updated gene therapy quality guidelines gate qualified supply access for laboratories lacking ISO 17025 accreditation and validated next-generation sequencing infrastructure, compressing premium-tier pricing power into a narrow tier of specialized virology providers while excluding uncertified competitors from high-margin replication-competent virus detection contracts.
Pricing Analysis
High-volume oncology biologics generate transactional revenue through large-batch sterility and endotoxin programs, while rare disease gene therapies concentrate margin pools through small-batch molecular diagnostics requiring single-copy sensitivity and extended method validation timelines. Pricing stratifies across ISO 17025-accredited premium laboratories, standard GMP-compliant facilities, and economy-tier regional quality control networks based on certification depth and vector characterization expertise. Cost compression in standard-tier microbial testing is intensifying as automated liquid handling platforms reduce manual labor intensity. Mid-tier biotech developers in Massachusetts and Basel exhibit highest price sensitivity for routine release testing, while large pharmaceutical manufacturers in Switzerland demonstrate lowest sensitivity for specialized adventitious agent screening.
Supply Chain Analysis
Logistics costs for temperature-sensitive reference standards and primary cell cultures constrain laboratory location decisions, with multi-day cold-chain transit threatening assay viability for distant manufacturing sites. Raw material supply draws from horseshoe crab populations in the southeastern United States for Limulus amebocyte lysate, recombinant protein production facilities in China and Germany for host cell protein standards, and specialized media suppliers in Japan and the United States for primary cell culture maintenance. Single-source vulnerability concentrates in southeastern US horseshoe crab harvesting regions, where population constraints threaten endotoxin testing raw material availability. Distribution runs through direct laboratory-to-manufacturer relationships for validated release testing, with regional hub models emerging for stability program logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next-generation sequencing for adventitious virus detection is displacing in vivo and in vitro virus panels, compressing multi-week traditional testing into days while demanding massive bioinformatics infrastructure investment that separates capable laboratories from legacy-dependent competitors.
For Market Incumbents: Deploy ISO 17025 accreditation breadth as a defensive moat by expanding gene therapy method validation capabilities and securing preferred provider agreements with large pharmaceutical manufacturers in Massachusetts and Basel. Anchor platform relationships through integrated bioproduction partnerships that bundle release testing, stability programs, and method development into multi-year master service agreements. Threat substitution from automated high-content imaging platforms demands counterinvestment in irreplaceable cell-based assay biological relevance. For New Entrants and Emerging Players: Artificial intelligence-assisted image analysis for potency testing offers a technology-first wedge into mid-tier biotech outsourcing demand, with automated cytotoxicity evaluation presenting lower capital barriers than next-generation sequencing infrastructure. Target India CDSCO biosimilar approval acceleration for comparability immunogenicity testing white space, where regulatory streamlining creates demand without entrenched incumbent relationships. Go-to-market positioning should emphasize rapid method development timelines against compressed IND submission deadlines. For Investors and Strategic Acquirers: FDA and EMA gene therapy guidance document releases are the leading indicator that vector purity requirement evolution will determine whether existing safety testing infrastructure satisfies emerging standards or demands entirely new analytical investments. Long-term viability centers on laboratories with demonstrated next-generation sequencing bioinformatics depth and trained quantitative PCR personnel for adeno-associated virus titer determination. Acquisition target archetype: specialized virology laboratories with replication-competent virus detection validation depth serving Netherlands and Sweden gene therapy developers.| Strategic Initiative | Industry Significance |
|---|---|
| Next-Generation Sequencing Infrastructure Investment | Platform-based metagenomic screening collapses adventitious virus detection timelines from weeks to days for gene therapy sponsors. |
| ISO 17025 Accreditation Expansion | Extended certification breadth qualifies laboratories for EMA and FDA commercial release programs in Germany and the United States. |
| High-Content Imaging Automation | Reduced manual microscopy burden preserves biological relevance for cell-based potency assays while compressing turnaround times. |
| Preferred Provider Agreement Negotiation | Multi-year master service agreements with large pharmaceutical manufacturers anchor revenue visibility across oncology biologics. |
| Regional Quality Control Hub Establishment | Suzhou and Shanghai facilities capture NMPA-aligned biologics manufacturing cluster demand for local release testing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across drug development executives, regulatory affairs leads, quality control laboratory directors, and contract research organization procurement managers validating demand-side assumptions. FDA gene therapy guidance documents, EMA quality guidelines, NMPA biologics approval pathway records, and ISO 17025 accreditation databases provided secondary validation. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from pharmaceutical manufacturing capacity expansion disclosures.
Data-stream reconciliation across product type, therapy area, end user, and deployment model dimensions shaped the analytical framework, with regional regulatory cluster variations explicitly modeled for the United States, Germany, China, Switzerland, and Japan. CAGRs were derived from segment-level volume and value trajectories, with gene therapy pipeline expansion rates and biosimilar approval acceleration serving as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen regulatory guideline revisions, horseshoe crab population collapse impacts on endotoxin testing supply, and recombinant factor C pharmacopeial acceptance breakthroughs that could displace animal-derived methods. Forecasts reflect assumptions about continued gene therapy pipeline expansion and stable accreditation timeline durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Urodynamic Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
US Viral Clearance Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
North America Newborn Screening Market
Testing Services
Solid Tumor Testing Market