
 Laboratory Rockers and Shakers Market | 2026-2036
Laboratory Rockers and Shakers Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Rockers and Shakers Market Foresight
The gap between premium programmable units and basic mechanical rockers is repositioning procurement patterns across end-user categories. Thermo Fisher Scientific leverages its digital platform ecosystem to anchor high-value contracts in pharmaceutical quality control labs. Heidolph Instruments competes through specialized electromagnetic drive technology that sustains precision in protein crystallography workflows. Benchmark Scientific occupies the academic and clinical entry-level tier with cost-optimized mechanical designs.
Laboratory rockers and shakers are electromechanical devices that generate controlled orbital, reciprocal, or rocking motion to maintain suspension homogeneity in liquid samples, typically operating at speeds from 20 to 500 rpm with programmable tilt angles and temperature integration. Their primary purpose spans cell culture maintenance, reagent mixing, and sample preparation where consistent agitation prevents sedimentation or thermal stratification. Orbital shakers lead product type demand due to their dominance in microbial fermentation and mammalian cell expansion protocols, while digital technology platforms capture expanding margin pools as laboratories replace manual speed controls with networked, data-logging systems. Electromagnetic drive technology represents the fastest-growing segment within motion platforms, displacing belt-driven mechanical assemblies in applications requiring sub-rpm precision.
FDA 21 CFR Part 11 compliance requirements shape demand for audit-trail-capable digital shakers in US pharmaceutical manufacturing, while ISO 9001 and ISO 13485 quality frameworks govern supplier qualification across European medical device and diagnostic markets. REACH substance restrictions and RoHS directives constrain motor component and coating material selections for equipment sold into EU member states. Stakeholders must monitor evolving GMP Annex 1 contamination control revisions and determine whether to prioritize backward integration into motion control electronics or partner with specialized automation component suppliers.
Market Dynamics
The transition from analog mechanical controls to networked digital platforms is fragmenting procurement hierarchies in laboratory equipment, as pharmaceutical quality control labs now demand audit-trail compliance and remote monitoring capabilities that legacy belt-drive systems cannot deliver.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in US pharmaceutical manufacturing are forcing replacement cycles for non-compliant mechanical units, creating pull for programmable digital shakers with embedded data logging.
- Cell culture automation:Mammalian cell expansion workflows in contract development organizations require precision motion control that sustains viability across multi-day runs, accelerating electromagnetic drive adoption.
- ISO 13485 supplier qualification:European medical device manufacturers are consolidating vendor lists around certified equipment providers, concentrating contract awards among quality-system-compliant suppliers.
Market Restraints
- Rare earth magnet cost volatility:Electromagnetic drive assemblies depend on neodymium supply concentrated in Chinese processing facilities, exposing margins to export quota fluctuations.
- REACH substance restrictions:RoHS-compliant motor windings and coating formulations impose material substitution costs that compress margins on economy-tier mechanical rockers.
- Precision manufacturing concentration:Sub-rpm motion control electronics fabrication clusters in southern Germany and Switzerland, creating geographic supply risk for non-integrated vendors.
Strategic Opportunities
- India's biopharma manufacturing expansion:CDSCO-aligned production facilities in Hyderabad and Bengaluru lack domestic precision agitation equipment suppliers, creating white space for quality-certified entrants.
- Gene therapy vector production:Suspension culture protocols for AAV manufacturing require specialized low-shear orbital motion that incumbent general-purpose shakers do not optimize.
- EU Green Deal procurement incentives:Member state research funding now prioritizes energy-efficient laboratory equipment, advantaging electromagnetic drives over legacy belt systems in grant-funded purchases.
Industry Challenges
- Mechatronics talent scarcity:Integration of motion control firmware with thermal management systems requires embedded systems engineers that equipment manufacturers struggle to recruit.
- Legacy system interoperability:Digital shakers must communicate with existing LIMS and building management systems through non-standard protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Rockers and Shakers Market |
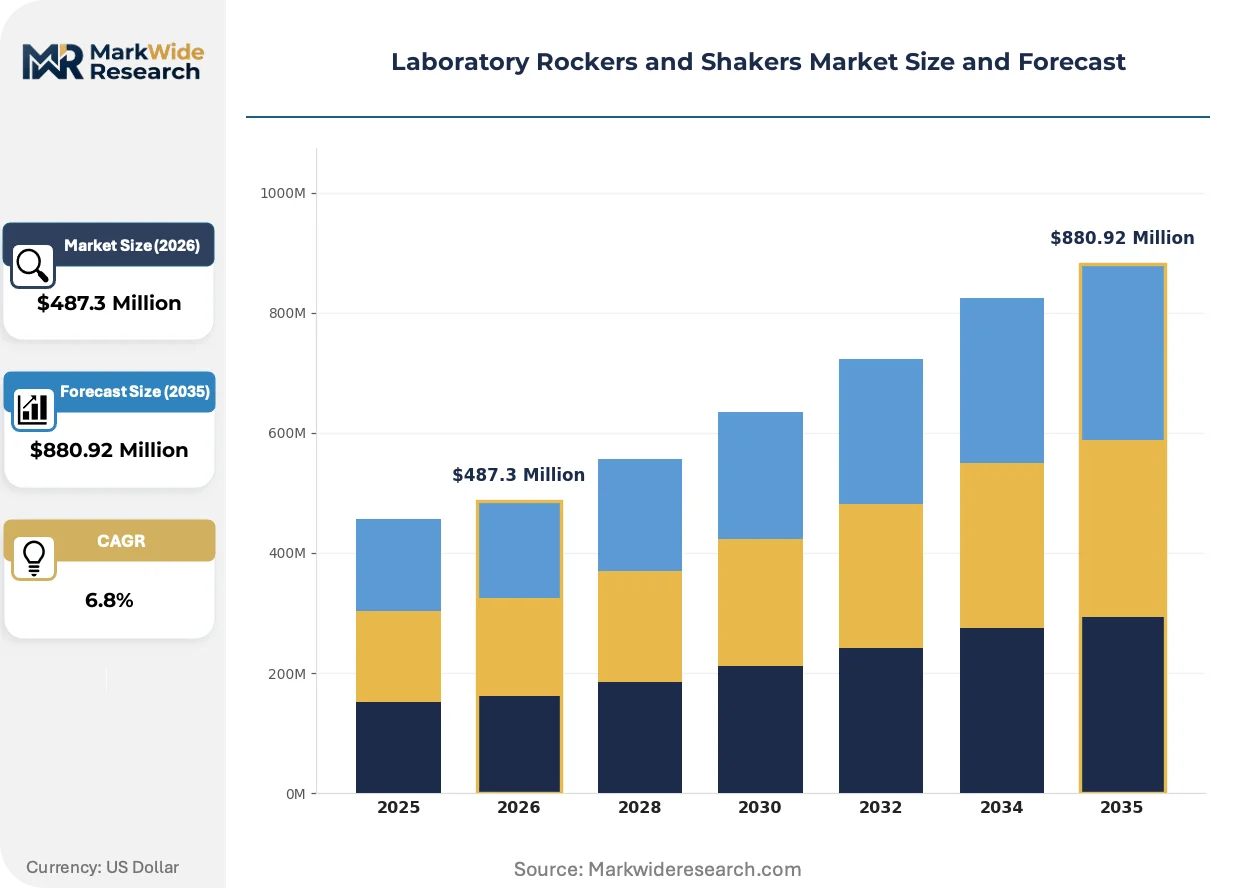
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orbital Shakers, Vortex Mixers, Reciprocal Shakers, Rocking Mixers End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Clinical Laboratories Application: Cell Culture, Chemical Analysis, Sample Preparation, Protein Studies Technology: Mechanical, Electromagnetic, Digital, Manual |
| Companies Covered | Avantor, Scientific Industries, Thermo Fisher Scientific, Boekel Scientific, Heidolph Instruments, Eppendorf, Corning, Benchmark Scientific, IKA Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Rockers and Shakers Market Shifts & Advancements
Digital platform architectures are collapsing the traditional boundary between hardware procurement and software service contracts, as laboratories seek integrated workflow management rather than standalone electromechanical devices.
Magnetic levitation drive technology is modularizing laboratory shaker construction by separating motion generation from mechanical bearing assemblies, enabling field-replaceable subsystems. Pharmaceutical quality control labs in Switzerland and Germany are piloting these units for protein crystallography workflows where vibration isolation determines experimental yield. This architecture is modularizing supplier relationships, as end-users source motion control electronics from specialized automation component vendors rather than integrated equipment manufacturers.
EMA's evolving GMP Annex 1 contamination control revisions are mandating closed-system designs for cell culture applications, forcing redesign of open-platform orbital shakers. Equipment manufacturers serving European biologics production facilities must now integrate HEPA filtration and vaporized hydrogen peroxide compatibility into standard product lines. Mammalian cell therapy producers in the Netherlands and Belgium are advancing purchase decisions pending final guidance publication.
Consolidated purchasing through group procurement organizations is compressing vendor negotiation cycles and unbundling after-sales service contracts from equipment sales. Academic consortia in the Boston-Cambridge cluster now negotiate enterprise-wide pricing for programmable shaker fleets, displacing individual laboratory purchasing autonomy. This concentration is most visible in US research universities where shared instrumentation facilities centralize capital equipment decisions across multiple principal investigator labs.
Laboratory Rockers and Shakers Market Segmentation
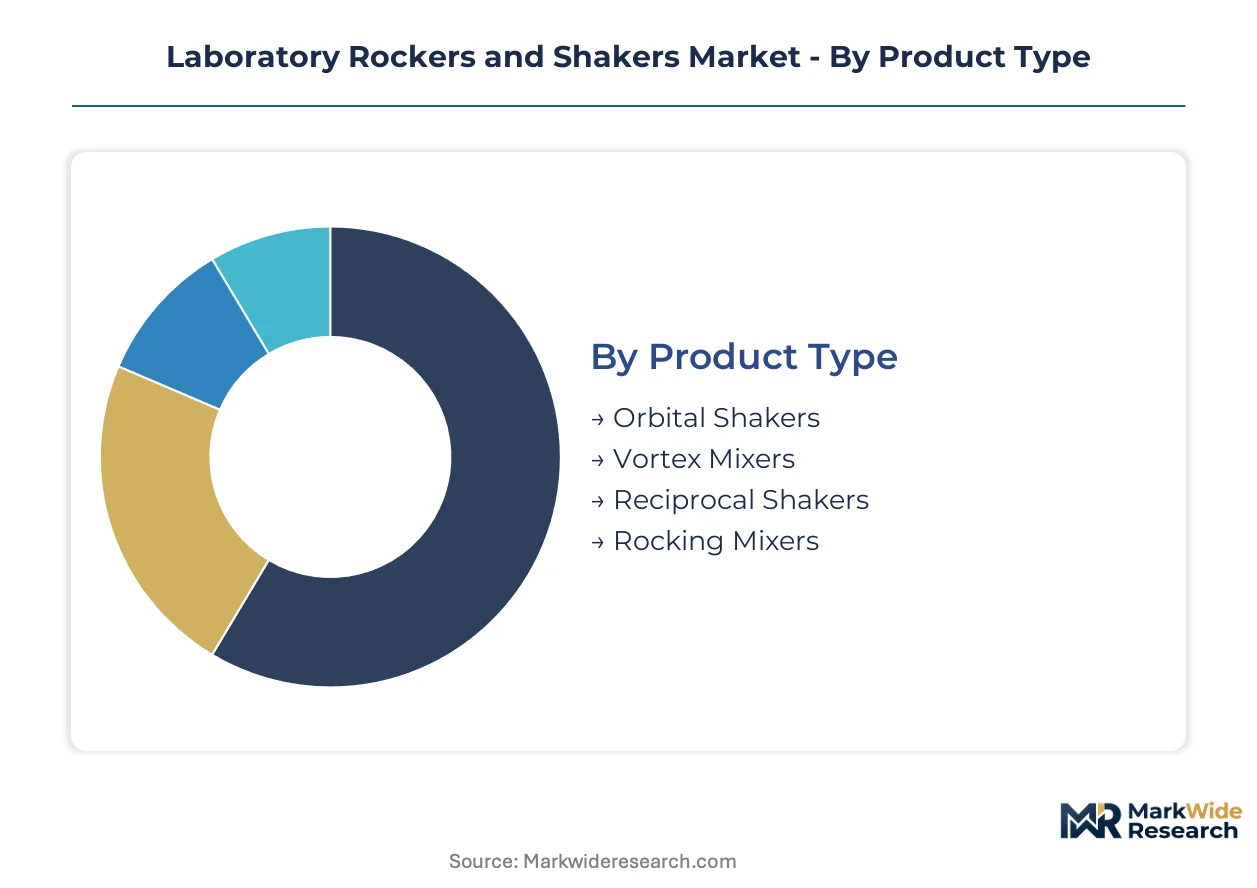
Segmentation in laboratory rockers and shakers reveals how motion control specifications diverge across precision requirements and regulatory environments. Equipment buyers select platforms based on protocol complexity, with pharmaceutical manufacturing demanding validated digital systems while academic settings prioritize mechanical simplicity.
Product Type:
Customization versus standardization splits sharply across this category, with programmable orbital systems commanding premium positioning against fixed-mechanism alternatives.
- Orbital Shakers:These units generate circular motion through offset drive mechanisms, typically spanning 20-400 rpm with adjustable orbit diameters from 3mm to 50mm. Mammalian cell expansion workflows in US pharmaceutical manufacturing drive specification requirements for CO2 incubator compatibility and low-shear motion profiles. FDA 21 CFR Part 11 audit trail mandates accelerate replacement of legacy analog speed controls with networked digital platforms.
- Vortex Mixers:Compact devices utilizing eccentric motor drives to create high-frequency orbital motion for rapid reagent homogenization in microtubes and flasks. Clinical diagnostic laboratories in Germany's precision engineering corridor specify touch-activated operation and multiple tube head configurations for high-throughput sample processing. REACH-compliant coating formulations constrain economy-tier supplier participation in EU member state tenders.
- Reciprocal Shakers:Linear back-and-forth motion platforms optimized for gel staining and washing protocols in protein electrophoresis workflows.
- Rocking Mixers:Tilt-angle devices generating gentle wave-like agitation for hybridization and blotting applications where minimal shear preserves biomolecular integrity.
Leading the category by volume: Orbital Shakers. Growing fastest: Vortex Mixers.
End User:
Procurement authority concentrates differently across customer types, with centralized purchasing in pharmaceutical conglomerates contrasting distributed decision-making in academic settings.
- Research Laboratories:Discovery-focused facilities spanning biotechnology startups and government research institutes. Boston-Cambridge cluster operations prioritize programmable motion profiles for CRISPR editing workflows and organoid culture maintenance. Shared instrumentation facilities consolidate capital decisions across multiple principal investigator groups, compressing vendor negotiation cycles.
- Pharmaceutical Companies:Quality control and manufacturing operations governed by GMP protocols and electronic records requirements. Contract development organizations in Switzerland and the Netherlands specify electromagnetic drive precision for multi-day cell therapy production runs. EMA GMP Annex 1 contamination control revisions mandate closed-system designs pending final guidance.
- Academic Institutions:University teaching and research laboratories with constrained capital budgets and decentralized purchasing autonomy.
- Clinical Laboratories:Hospital-based and independent diagnostic facilities processing patient samples under ISO 15189 quality frameworks.
Pharmaceutical Companies capture the highest average selling prices. Academic Institutions expand most quickly in absolute unit terms.
Application:
Protocol complexity determines motion control specifications, with live cell applications demanding sub-rpm precision that chemical mixing protocols do not require.
- Cell Culture:Maintenance of suspension and adherent cell lines requiring controlled oxygen transfer and minimal mechanical stress. AAV vector production for gene therapy applications in Belgium and the Netherlands drives demand for specialized low-shear orbital motion that general-purpose equipment does not optimize. Temperature integration and CO2 compatibility separate premium from standard-tier offerings.
- Chemical Analysis:Reagent dissolution and reaction acceleration in analytical chemistry workflows. Solubility testing and extraction protocols in environmental monitoring laboratories specify vortex mixing with timer-controlled operation. RoHS-compliant motor windings impose material substitution costs on economy-tier suppliers serving price-sensitive segments.
- Sample Preparation:Pre-analytical processing including mixing, dilution, and homogenization prior to instrumental analysis.
- Protein Studies:Crystallization screening, blotting, and binding assays where vibration isolation determines experimental yield.
Cell Culture commands the largest revenue share. Protein Studies show the steepest specification escalation.
Technology:
Margin architecture shifts dramatically across drive mechanisms, with electromagnetic platforms capturing expanding value pools as mechanical belt systems commoditize.
- Mechanical:Belt-driven and direct-drive motor assemblies with analog speed control and fixed motion parameters. Entry-tier positioning in academic and clinical settings where capital constraints outweigh precision requirements. Cost-optimized designs from Chinese and Indian manufacturers compress pricing in developing market tenders.
- Electromagnetic:Direct magnetic drive systems enabling sub-rpm precision and programmable motion profiles without mechanical wear components. Protein crystallography workflows in southern Germany and Switzerland specify vibration isolation performance that magnetic levitation architectures deliver. Neodymium supply concentration in Chinese processing facilities exposes margins to export quota volatility.
- Digital:Networked platforms with embedded data logging, remote monitoring, and LIMS integration capabilities.
- Manual:Hand-operated or simple spring-driven devices for basic mixing without electrical power requirements.
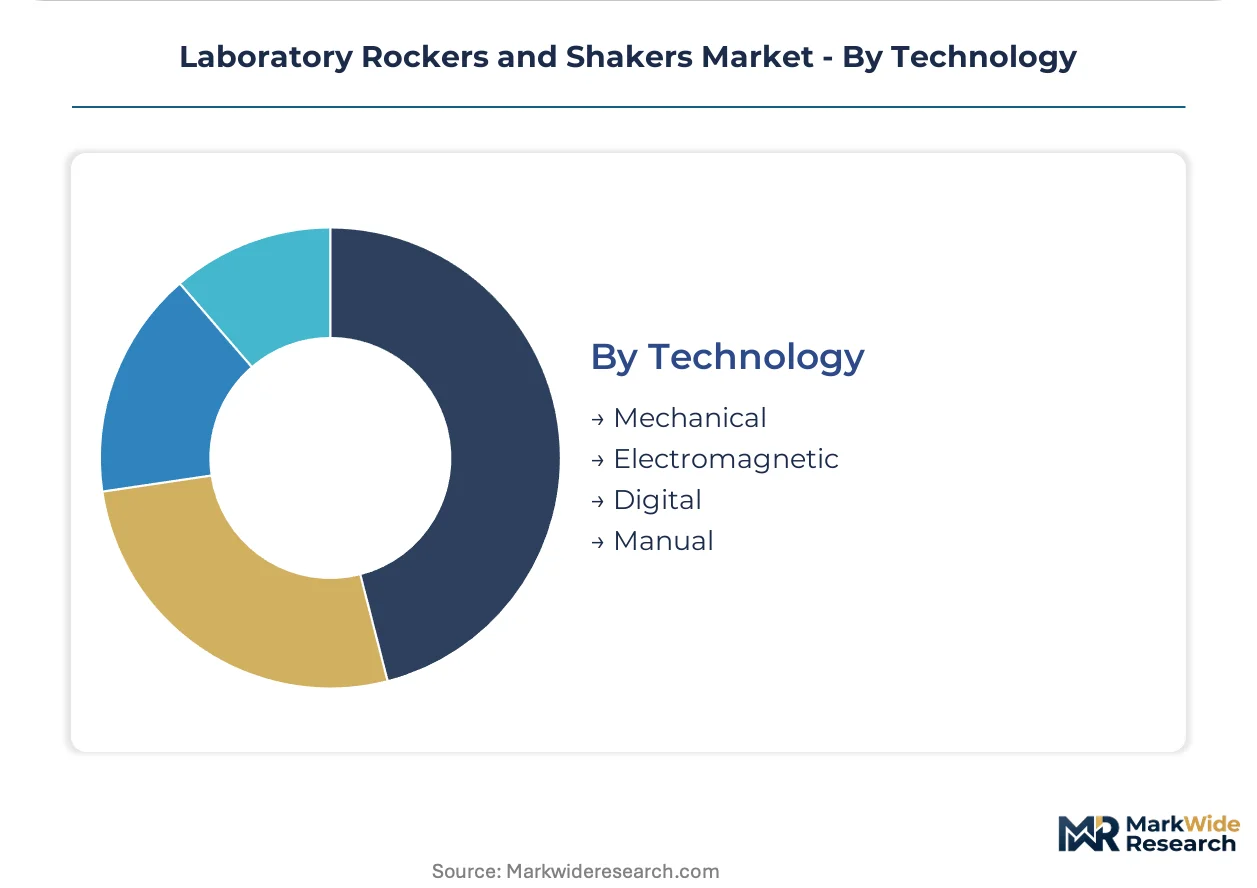
Mechanical technology retains the largest installed base. Electromagnetic systems gain share fastest in premium applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors pharmaceutical demand for programmable orbital shakers, while precision engineering clusters in southern Germany and Switzerland concentrate electromagnetic drive manufacturing capabilities.
United States
FDA 21 CFR Part 11 mandates drive replacement cycles in pharmaceutical quality control labs across New Jersey and North Carolina manufacturing belts. Contract development organizations in the Research Triangle Park specify audit-trail-capable digital platforms for multi-day cell therapy production runs. The Boston-Cambridge cluster consolidates shared instrumentation purchasing through academic consortia, compressing vendor negotiation cycles for programmable shaker fleets.
Germany
ISO 13485 supplier qualification requirements concentrate contract awards among quality-system-certified equipment providers serving medical device manufacturers in Baden-Württemberg. REACH substance restrictions and RoHS directives constrain motor component selections for equipment sold into EU member states. The precision engineering corridor spanning Bavaria and Baden-Württemberg fabricates sub-rpm motion control electronics for protein crystallography workflows.
Switzerland
Swissmedic GMP oversight and EMA Annex 1 contamination control revisions mandate closed-system designs for biologics production facilities in Basel and Zurich. Pharmaceutical quality control labs pilot magnetic levitation drive technology where vibration isolation determines experimental yield. The Basel biotech cluster advances purchase decisions pending final EMA guidance on vaporized hydrogen peroxide compatibility requirements.
India
CDSCO-aligned production facilities in Hyderabad and Bengaluru lack domestic precision agitation equipment suppliers, creating white space for quality-certified entrants. The government's PLI scheme for pharmaceuticals incentivizes local manufacturing infrastructure investments. Contract research organizations in Genome Valley, Hyderabad, expand automated cell culture workflows requiring programmable motion control systems.
China
NMPA medical device registration requirements and GB standards govern equipment procurement for diagnostic manufacturers in Shanghai and Suzhou. Neodymium processing concentration in Chinese facilities exposes electromagnetic drive margins to export quota volatility. The Yangtze River Delta biopharma manufacturing base imports precision orbital shakers for mammalian cell expansion protocols in gene therapy vector production.
Laboratory Rockers and Shakers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and motion control precision capabilities. The vendor base stratifies into three tiers: integrated life science conglomerates with digital platform ecosystems, specialized electromechanical equipment manufacturers with electromagnetic drive expertise, and cost-optimized mechanical fabricators serving academic entry segments. Dominant competitive moves include backward integration into motion control firmware development and strategic partnerships with specialized automation component suppliers for magnetic levitation architectures.
Within the integrated conglomerate tier, Thermo Fisher Scientific anchors high-value contract positions through digital platform ecosystems that bundle equipment with LIMS integration services. Heidolph Instruments and IKA Works occupy the specialized precision equipment segment, representing German-origin manufacturers with electromagnetic drive competencies for sub-rpm applications. Benchmark Scientific exemplifies the cost-optimized mechanical tier, serving academic and clinical entry-level demand with simplified fixed-mechanism designs.
| Leading Market Players |
|---|
| Avantor |
| Scientific Industries |
| Thermo Fisher Scientific |
| Boekel Scientific |
| Heidolph Instruments |
| Eppendorf |
| Corning |
| Benchmark Scientific |
| IKA Works |
| Others |
Supply & Pricing Matrix
Embedded systems engineering talent concentration in southern Germany and Switzerland feeds directly into pricing-tier spreads, as labor-cost differentials between electromagnetic drive specialists and mechanical assembly technicians widen the gap between premium programmable units and economy-tier belt-driven alternatives. This workforce geography forces equipment manufacturers to either absorb specialized labor costs in premium pricing or offshore mechanical production to cost-advantaged regions.
Pricing Analysis
Throughput-based pricing anchors the laboratory rockers and shakers market, with pharmaceutical quality control labs paying premium rates for validated digital platforms that guarantee multi-day cell culture viability. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-compliant audit-trail systems from basic mechanical units. Cost compression in the economy tier is intensifying because REACH-compliant motor windings and RoHS-compatible coatings impose material substitution burdens. Academic institutions exhibit the highest price sensitivity, while contract development organizations in Switzerland and the Netherlands demonstrate minimal elasticity for electromagnetic drive precision.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese processing facilities that concentrate rare earth refining capacity, creating single-source vulnerability for electromagnetic drive assemblies. Motion control electronics fabrication draws from southern Germany and Switzerland, while cost-optimized mechanical components source from Chinese and Indian manufacturers. Tariff exposure runs through neodymium export quotas that Beijing adjusts periodically. Distribution runs through life science equipment distributors and direct sales forces serving pharmaceutical conglomerates, with group procurement organizations consolidating vendor negotiations in the Boston-Cambridge cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over motion control firmware development determines margin capture, with leading players pursuing backward integration into embedded systems engineering while others partner with specialized automation component suppliers.
For Market Incumbents: Anchor high-value contract positions through digital platform ecosystems that bundle equipment with LIMS integration services, defending against specialized electromagnetic drive entrants from Germany's precision engineering corridor. Pursue captive supply of sub-rpm motion control electronics to reduce dependency on southern German and Swiss fabrication clusters. Certification investment in ISO 13485 and FDA 21 CFR Part 11 compliance creates switching costs that lock in pharmaceutical quality control accounts. For New Entrants and Emerging Players: Begin with CDSCO-aligned production facilities in Hyderabad and Bengaluru, where domestic precision agitation equipment suppliers remain absent and contract research organizations expand automated cell culture workflows. Target gene therapy vector production applications in Belgium and the Netherlands, where specialized low-shear orbital motion requirements exceed general-purpose equipment capabilities. A equipment-as-a-service go-to-market angle bypasses capital constraints at academic shared instrumentation facilities. For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic drive specialists given EMA GMP Annex 1 contamination control revisions that mandate closed-system designs and vaporized hydrogen peroxide compatibility. Long-term viability favors vendors with integrated firmware development capabilities rather than mechanical assemblers dependent on outsourced motion control electronics. Watch final EMA guidance publication timing as the inflection signal that triggers pharmaceutical biologics producers to advance purchase decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control Firmware | Captive embedded systems development reduces dependency on southern German and Swiss electronics fabrication clusters. |
| ISO 13485 Supplier Qualification Investment | European medical device manufacturers consolidate vendor lists around certified equipment providers in Baden-Württemberg. |
| Magnetic Levitation Drive Technology Licensing | Swiss pharmaceutical quality control labs pilot modular architectures that separate motion generation from mechanical bearings. |
| CDSCO-Aligned Manufacturing Footprint in India | Hyderabad and Bengaluru biopharma facilities lack domestic precision agitation equipment suppliers. |
| Closed-System Design for GMP Annex 1 Compliance | EMA contamination control revisions mandate HEPA filtration and vaporized hydrogen peroxide compatibility in Basel biotech cluster. |
Research Methodology
Independent corroboration across equipment procurement managers at pharmaceutical quality control labs, regulatory affairs leads at contract development organizations, and aftermarket service heads at life science distributors underwrites the qualitative findings. Primary interviews with plant engineers specifying motion control systems, biomedical engineers maintaining cell culture workflows, and GPO contracts managers consolidated purchasing decisions combined with secondary validation through FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 1 revision drafts, and ISO 13485 certification databases. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects as laboratories replace mechanical belt systems with electromagnetic drives. Segmentation dimensions modeled include motion platform type, drive technology tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from protocol-level demand forecasting for cell culture, protein studies, and chemical analysis applications, with specific inputs from mammalian cell expansion workflow automation trends and gene therapy vector production capacity buildouts.
Underlying measurement precision varies by segment; pharmaceutical company and contract development organization demand carries tighter precision than academic institution purchasing given centralized procurement data availability. Forecasts reflect assumptions about EMA guidance finalization timing, neodymium export quota stability, and mechatronics talent pipeline expansion. A small set of triggers—GMP Annex 1 revision publication, Chinese rare earth policy shifts, and electromagnetic drive patent expirations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market