
 Global Internet of Things (IoT) Agriculture Market | 2026-2036
Global Internet of Things (IoT) Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Things (IoT) Agriculture Market Intelligence
Platform bundling of hardware sensors with subscription analytics is hardening as the dominant procurement pattern for commercial growers. Deere & Company leverages its proprietary Operations Center to anchor long-term service contracts across North American grain operations. Trimble Inc. competes through modular correction services that let farm operators scale GNSS precision without full equipment replacement. AGCO Corporation differentiates via Fuse Smart Farming, an open-architecture platform that integrates third-party devices into mixed-fleet environments.
The Global Internet of Things (IoT) Agriculture comprises networked sensor arrays, edge computing nodes, and cloud analytics platforms that collect and process field-level data on soil moisture, crop canopy health, machinery telemetry, and microclimate conditions, typically transmitting via LPWAN, cellular, or satellite protocols with latency tolerances under 500 milliseconds for real-time irrigation actuation. Its primary commercial purpose is to convert spatial and temporal variability into actionable input prescriptions that reduce resource waste while stabilizing yield outcomes. Precision farming solutions occupy the largest value pool within solution type segmentation, though livestock monitoring is expanding fastest as dairy and poultry operations deploy biometric ear tags and automated milking analytics to meet processor traceability requirements. Cloud-based deployment leads in new installations, yet edge computing is gaining share where bandwidth constraints or data sovereignty concerns limit centralized processing.
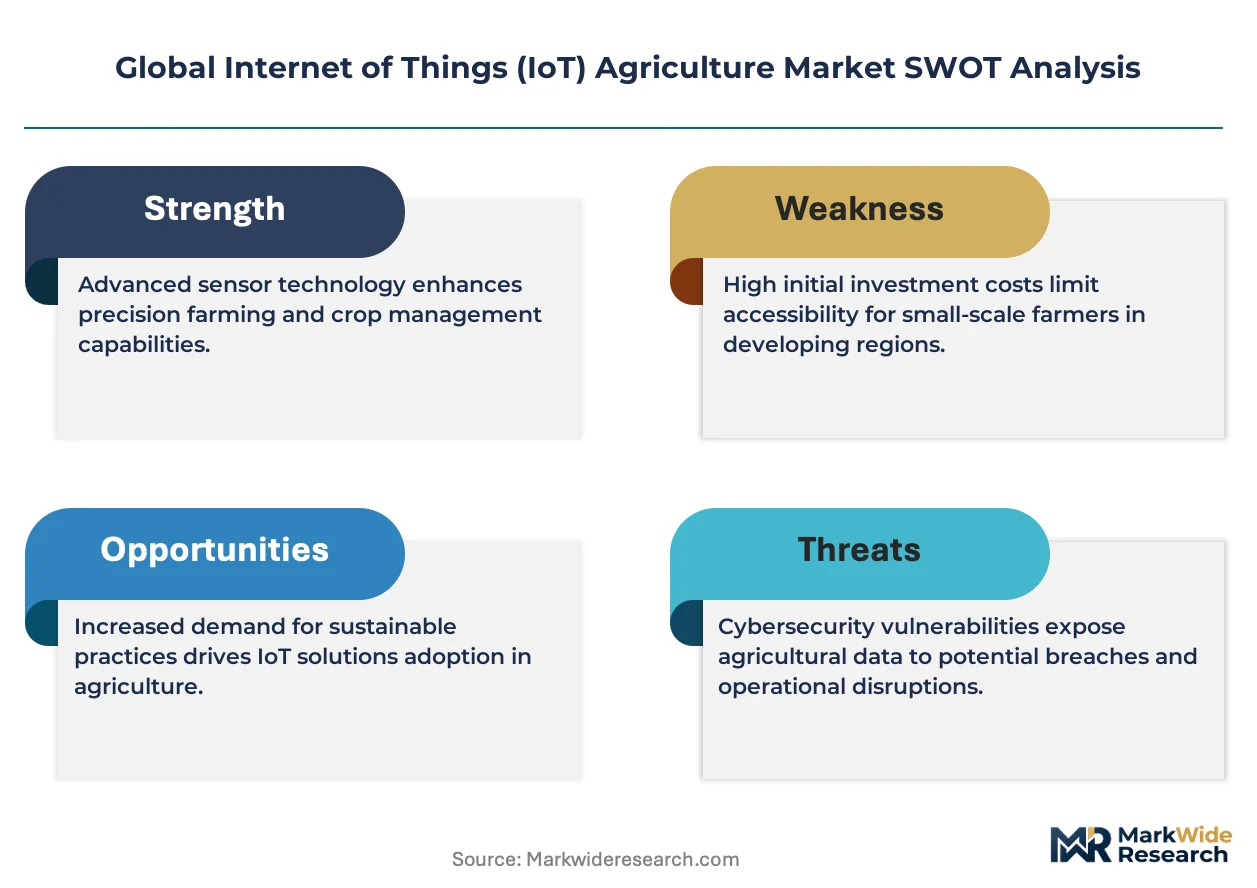
The EPA regulates pesticide application rates that IoT systems must document for compliance, while the EU Green Deal and F-Gas Regulation impose equipment efficiency standards that shape sensor and actuator specifications in European markets. FDA food safety traceability rules are extending data-retention requirements backward through supply chains, forcing farm-level IoT platforms to maintain immutable audit logs. Stakeholders must weigh interoperability investments against the risk of proprietary platform lock-in as equipment manufacturers and independent software vendors compete to own the data layer between field operations and downstream food processors.
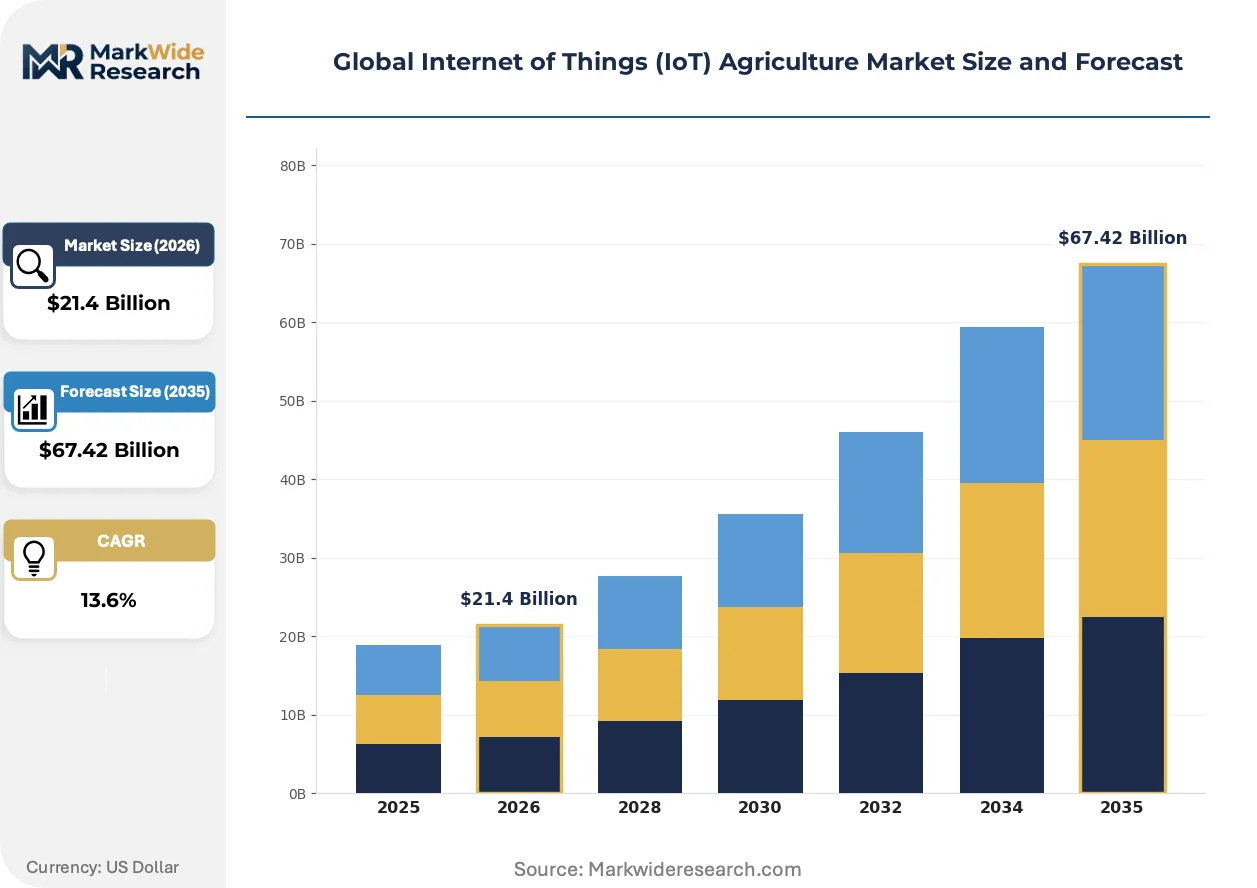
Market Dynamics
Platform bundling of hardware sensors with subscription analytics is hardening as the dominant procurement pattern, locking commercial growers into multi-year service contracts that reshape equipment replacement cycles and vendor switching costs.
Growth Catalysts
- EU Green Deal digital agriculture mandates:European farming cooperatives must deploy sensor networks and autonomous machinery to meet emissions monitoring requirements, accelerating precision farming adoption across the continent's large-scale operations.
- Brazil's Mato Grosso soybean belt:Satellite-guided variable-rate application now dominates commercial row-crop operations, creating concentrated demand pull for telemetry-enabled equipment and cloud-based field analytics platforms.
- LPWAN protocol maturation:Low-power wide-area networks reduce connectivity costs for remote field deployments, enabling sensor density at price points viable for mid-sized grain operations previously priced out of precision agriculture.
Market Restraints
- Silicon supply concentration:Edge computing nodes and sensor microcontrollers depend on semiconductor fabrication concentrated in East Asian foundries, exposing equipment manufacturers to input volatility and allocation constraints.
- F-Gas Regulation equipment standards:The EU's phasedown of hydrofluorocarbons forces redesign of climate-controlled greenhouse sensors and actuators, adding compliance costs that compress margins for European market entrants.
- Data sovereignty fragmentation:Divergent national cloud-storage mandates across Germany, France, and India prevent unified platform architectures, forcing vendors to maintain region-specific infrastructure that dilutes scale economies.
Strategic Opportunities
- India's PLI scheme for precision agriculture:Production-linked incentives for domestic manufacturing of IoT sensors and drones create localized supply advantages for equipment providers establishing Indian assembly operations.
- Livestock biometric monitoring:Dairy and poultry operations deploy ear-tag sensors and automated milking analytics to meet processor traceability requirements, opening faster-expanding value pools than saturated row-crop segments.
- Edge-to-cloud hybrid architectures:Convergence of on-field processing nodes with centralized analytics platforms addresses bandwidth constraints in rural Brazil and Australia while satisfying EU data-localization rules.
Industry Challenges
- Agronomic data science talent scarcity:Farm operators lack personnel capable of translating raw sensor outputs into input prescriptions, forcing vendors to bundle managed analytics services that erode hardware margins.
- Interoperability certification delays:Mixed-fleet environments await standardized device communication protocols, prolonging sales cycles as growers hesitate to commit to proprietary platforms that risk strandeding existing equipment investments.
- Legacy machinery integration complexity:Retrofitting decades-old tractors and combines with telemetry modules requires mechanical engineering expertise scarce among software-native IoT vendors, creating service delivery bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Things (IoT) Agriculture Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $67.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Precision Farming, Livestock Monitoring, Greenhouse Automation, Irrigation Management, Supply Chain Optimization Application: Crop Monitoring, Soil Analysis, Weather Forecasting, Pest Control, Yield Prediction End User: Farm Operators, Agricultural Equipment Providers, Food Processors, Research Institutions |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Robert Bosch GmbH, Raven Industries, Inc., Farmers Edge Inc., The Climate Corporation, Topcon Positioning Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Things (IoT) Agriculture Market Strategic Shifts & Innovations
Electrification of field machinery is converging with autonomous navigation systems to redefine capital deployment patterns, while regulatory pressure on emissions documentation accelerates sensor density requirements beyond yield optimization alone.
Autonomous electric tractors with integrated implement control are electrifying the equipment replacement cycle for North American grain operations. Large-scale farm operators in Iowa and Illinois are piloting battery-powered platforms that eliminate diesel logistics while enabling precise torque modulation for variable-rate seeding. This electrification is compressing the traditional 10-year replacement horizon as energy cost arbitrage and carbon credit eligibility create accelerated depreciation schedules.
The EU F-Gas Regulation mandates equipment efficiency standards that reshape sensor and actuator specifications across European farming cooperatives. Greenhouse gas monitoring requirements now extend to refrigerated transport and controlled-environment agriculture, forcing IoT vendors to certify thermal management devices for lower-global-warming-potential refrigerants. Dutch horticulture clusters and Spanish greenhouse belts are retrofitting climate control systems to maintain market access under tightening emissions enforcement.
Processor-driven traceability requirements are transforming procurement from equipment purchase to outcome-based service contracting. North American meat and dairy packers now mandate immutable audit logs from farm-level platforms, pushing growers toward subscription analytics that guarantee compliance documentation. This shift is most visible in Wisconsin dairy corridors and Nebraska feedlot regions, where biometric monitoring contracts are displacing capital-intensive sensor ownership models.
Global Internet of Things (IoT) Agriculture Market Segmentation
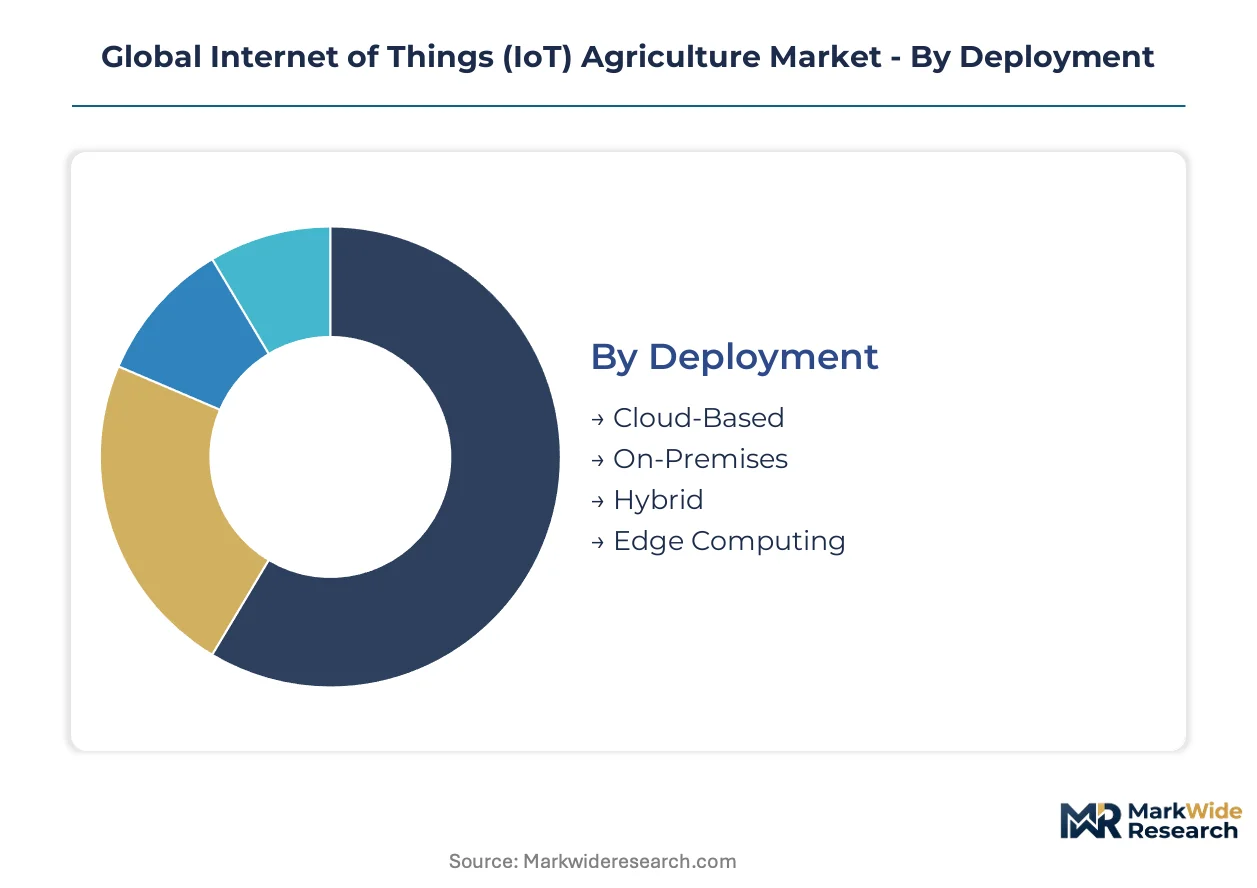
IoT agriculture vendors configure product portfolios around four intersecting dimensions: where data processing occurs, which operational problem gets solved, which farm activity gets instrumented, and who holds procurement authority. These segmentation boundaries determine pricing architecture, sales cycle length, and partnership requirements.
Deployment:
Volume deployments favor centralized processing for cost efficiency, while premium installations distribute intelligence across field nodes to satisfy latency and sovereignty constraints.
- Cloud-Based:Centralized data lakes process telemetry from dispersed sensor networks, with subscription models dominating commercial grain operations in Brazil's Mato Grosso and the US Corn Belt. Latency tolerances under 500 milliseconds for irrigation actuation limit pure-cloud architectures where cellular coverage fragments.
- Edge Computing:On-field processing nodes execute real-time analytics without backhaul dependency, gaining share in Australian broadacre farming and EU jurisdictions with strict data-localization mandates. Hardware margins compress against software subscription attach rates.
- Hybrid:Tiered architectures synchronize critical control loops locally while feeding aggregate datasets to cloud analytics platforms. This configuration addresses bandwidth constraints in rural India and satisfies EU Green Deal traceability requirements without full centralization.
- On-Premises:Fully private infrastructure serves research institutions and defense-adjacent agricultural facilities with classified or export-controlled data. Capital intensity restricts adoption to government-funded demonstration projects and seed-breeding operations.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Solution Type:
Application maturity varies sharply: row-crop optimization commands established budgets while livestock and controlled-environment segments unlock faster expansion rates.
- Precision Farming:Satellite-guided variable-rate application systems dominate commercial expenditure, integrating GNSS correction services with soil moisture telemetry and canopy sensors. Large-scale farm operators in Iowa and Illinois anchor procurement volumes through multi-year platform contracts.
- Livestock Monitoring:Biometric ear tags and automated milking analytics expand most quickly as dairy processors mandate immutable health records. Wisconsin dairy corridors and Dutch livestock cooperatives drive equipment refresh cycles.
- Greenhouse Automation:Climate control systems retrofit for F-Gas Regulation compliance across Spanish Almería and Dutch Westland clusters, with sensor density increasing to document emissions for EU market access.
- Irrigation Management:LPWAN-enabled soil moisture networks reduce water waste in water-stressed regions, with Israeli precision-drip vendors and Australian broadacre operators representing contrasting deployment scales.
- Supply Chain Optimization:Blockchain-anchored logistics tracking extends from farm gate to processor, with FDA food safety rules and EU deforestation regulations forcing data-retention investments backward through supplier tiers.
Precision Farming captures current procurement budgets. Livestock Monitoring climbs the fastest as processor compliance requirements harden.
Application:
Functional use cases segment by data fusion complexity: single-source sensing dominates installed base while multi-variate prediction commands premium pricing.
- Crop Monitoring:Multispectral and thermal imaging from drones or fixed-wing platforms tracks canopy health, with NDVI-derived prescriptions now standard in Brazilian soybean operations and Ukrainian grain belts.
- Soil Analysis:Electromagnetic conductivity mapping and in-situ nutrient probes enable zone-specific fertilization, with subscription soil-sampling services displacing capital equipment ownership among mid-sized US farm operators.
- Weather Forecasting:Microclimate stations augment satellite precipitation data, with edge-deployed models gaining traction where cellular connectivity fails during critical planting windows.
- Pest Control:Pheromone trap sensors and computer-vision detection systems trigger targeted pesticide release, with EPA documentation requirements forcing IoT integration for compliance audit trails.
- Yield Prediction:Machine-learning models fuse multiple sensor streams to forecast harvest volumes, with grain elevators and commodity traders purchasing prediction services directly from platform vendors.
Crop Monitoring holds installed base dominance. Yield Prediction emerges as the highest-value analytics layer.
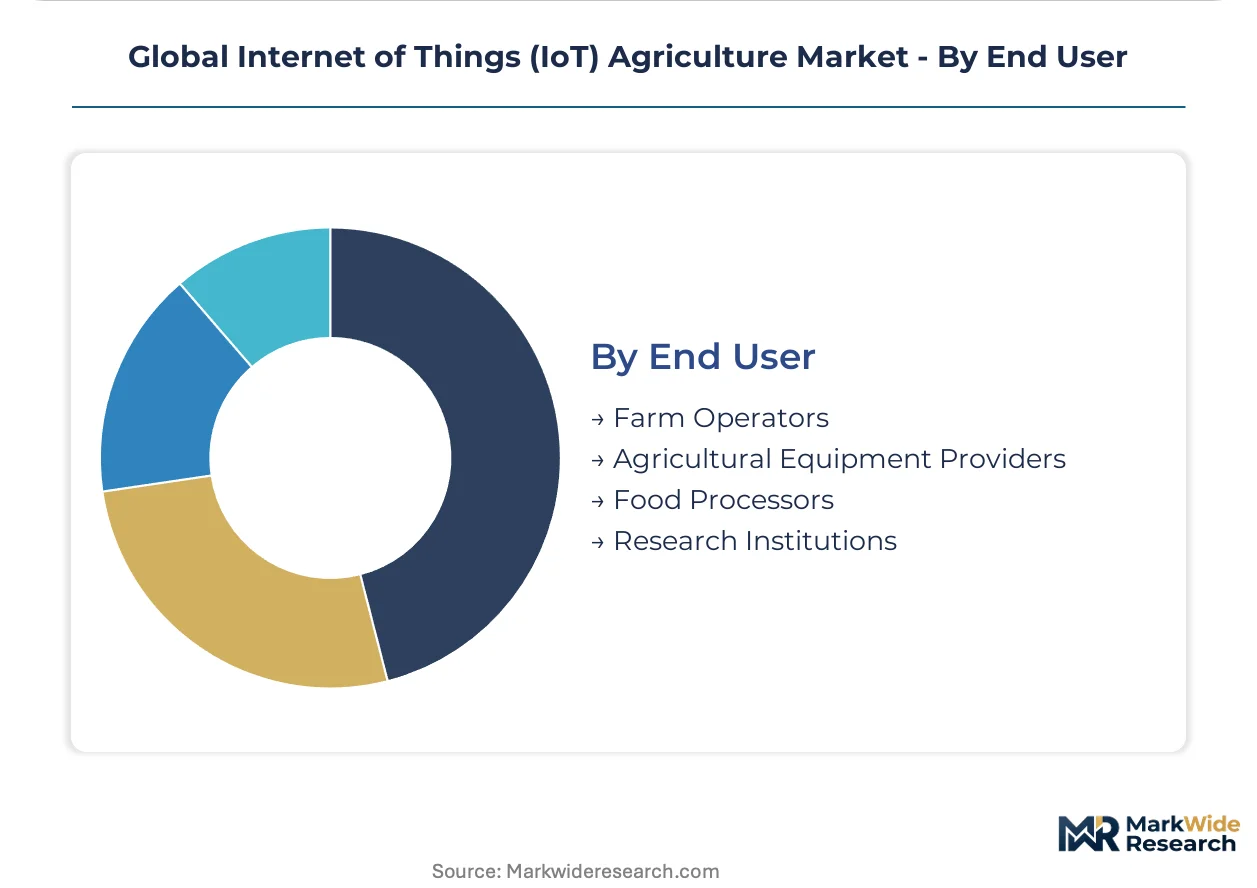
End User:
Procurement authority concentrates with farm operators for field equipment, while food processors increasingly dictate upstream IoT specifications through supply chain contracting.
- Farm Operators:Individual growers and farming cooperatives hold direct purchasing authority for telemetry-enabled machinery and sensor networks, with financing structures shifting from capital expenditure to subscription services.
- Food Processors:Meat packers and dairy processors mandate farm-level platform specifications to satisfy FDA traceability rules and EU deforestation due diligence requirements, converting equipment markets into compliance service contracts.
- Agricultural Equipment Providers:OEMs bundle IoT platforms with machinery sales, using proprietary data architectures to lock in aftermarket service revenue and parts replacement cycles.
- Research Institutions:Universities and government agricultural stations pilot emerging sensor modalities, with public funding cycles creating demand volatility distinct from commercial procurement patterns.
Farm Operators retain volume leadership. Food Processors are displacing traditional procurement authority fastest through supply chain mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture first achieved commercial scale in the United States during the 1990s, when GPS-guided tractors and yield monitors transformed Midwest grain operations into data-driven enterprises. That technological lineage now diffuses across divergent regulatory and agronomic contexts worldwide.
United States
Large-scale farm operators in Iowa and Illinois anchor global procurement volumes for telemetry-enabled machinery and subscription analytics platforms. EPA pesticide documentation requirements force IoT integration for compliance audit trails, reshaping equipment specifications. The Corn Belt corridor from Nebraska to Indiana concentrates deployment of autonomous electric tractors with integrated implement control.
Brazil
Satellite-guided variable-rate application now dominates commercial row-crop operations across Mato Grosso's soybean belt, creating concentrated demand pull for cloud-based field analytics. ANVISA agrochemical regulations intersect with processor traceability mandates to accelerate platform adoption. The Cerrado frontier regions exhibit fastest sensor density growth as LPWAN protocols reduce connectivity costs for remote deployments.
Germany
EU Green Deal digital agriculture mandates and F-Gas Regulation equipment standards reshape sensor specifications across farming cooperatives in Lower Saxony and Bavaria. REACH compliance requirements for chemical monitoring extend IoT obligations into precision spraying systems. The Rhine-Ruhr industrial corridor hosts equipment retrofitting operations for emissions-certified greenhouse automation.
China
Dual carbon goals and MIIT smart agriculture directives accelerate domestic manufacturing of IoT sensors and drones for the North China Plain wheat belt. GB standards for agricultural equipment interoperability create procurement specifications that favor locally assembled platforms. Shandong Province's horticulture clusters deploy climate control systems with edge-computing nodes to satisfy data-sovereignty constraints.
Australia
Broadacre farming operations across New South Wales and Victoria adopt edge computing architectures where cellular coverage fragments during critical planting windows. TGA-equivalent agricultural chemical regulations and processor traceability rules extend data-retention requirements to farm-level platforms. The Murray-Darling Basin concentrates irrigation management deployments as water allocation constraints intensify.
Global Internet of Things (IoT) Agriculture Market Key Industry Players
The competitive structure tilts toward equipment manufacturers with captive distribution networks and proprietary data architectures. Consolidation pressure intensifies as subscription service models raise switching costs and compress hardware margins. Three archetypes dominate: legacy machinery OEMs bundling IoT platforms with equipment sales, independent precision-agriculture specialists selling modular correction services, and software-native vendors offering outcome-based compliance contracts. Geographic expansion through regional assembly partnerships and technology licensing for localized sensor manufacturing represent the dominant competitive moves.
Among North American machinery OEMs, Deere & Company and AGCO Corporation exemplify the platform-bundling archetype, anchoring long-term service relationships through proprietary data architectures. Trimble Inc. occupies a distinct position as an independent precision-technology specialist, competing through modular services that enable operators to scale GNSS precision without full fleet replacement. These three entities collectively illustrate the tension between integrated platform control and interoperability openness that defines vendor strategy across commercial grain operations.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Robert Bosch GmbH |
| Raven Industries, Inc. |
| Farmers Edge Inc. |
| The Climate Corporation |
| Topcon Positioning Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Equipment manufacturers with captive distribution networks anchor supply-side ownership patterns, translating vertical control into pricing discipline through multi-year service contracts that reshape buyer switching costs across commercial grain operations.
Pricing Analysis
Subscription-based platform bundling dominates procurement economics, with hardware sensors sold alongside recurring analytics fees that extend revenue capture beyond initial equipment deployment. Price differentiation rests on GNSS correction accuracy tiers and after-sales service bundling, where premium contracts guarantee sub-inch precision with dedicated support channels. Cost compression in mid-tier sensor modules is intensifying because semiconductor allocation constraints force vendors to prioritize high-margin enterprise accounts. Mid-sized farm operators in water-stressed regions exhibit greatest price sensitivity, while large-scale cooperatives in Brazil's Mato Grosso accept premium positioning for guaranteed uptime commitments.
Supply Chain Analysis
Semiconductor fabrication for edge computing nodes and sensor microcontrollers rests on concentrated East Asian foundry capacity, with Taiwan, South Korea, and China anchoring wafer supply for agricultural IoT equipment. Critical inputs include LoRaWAN chipsets, multispectral imaging sensors, and lithium-ion power management systems. Single-source vulnerability in advanced node production exposes equipment manufacturers to allocation disruptions during demand surges. Distribution runs through authorized dealer networks controlled by legacy machinery OEMs, limiting direct channel access for independent platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in agricultural IoT hinges on software attach rates climbing as hardware commoditization forces vendors to capture value through recurring analytics subscriptions rather than upfront equipment sales.
For Market Incumbents: Deepen proprietary data architecture investments to lock in aftermarket service revenue and extend replacement cycles for telemetry-enabled machinery. Defend against modular correction-service competitors by embedding GNSS precision into bundled platform contracts that raise switching costs. Prioritize certification for EU F-Gas Regulation compliance to maintain access to Dutch and Spanish greenhouse automation markets. For New Entrants and Emerging Players: Mid-sized grain operators in India's wheat belt represent an underserved buyer archetype with limited precision agriculture penetration and growing PLI scheme support for domestic sensor manufacturing. White-space targets include livestock biometric monitoring in Southeast Asian poultry operations and edge-computing nodes for Australian broadacre bandwidth constraints. A channel partnership with regional equipment distributors bypasses incumbent dealer network control. For Investors and Strategic Acquirers: Valuations sit cheapest among independent precision-agriculture specialists lacking captive machinery distribution, presenting consolidation targets for OEMs seeking software capabilities. Long-term viability favors vendors with hybrid edge-cloud architectures that satisfy divergent data sovereignty mandates without duplicating infrastructure. Watch LPWAN protocol standardization progress as an inflection signal for mid-market sensor density acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Fuse Smart Farming's open architecture demonstrates third-party device absorption into mixed-fleet environments. |
| Backward Integration into Sensor Manufacturing | India's PLI scheme incentivizes domestic assembly operations that reduce import dependency for critical components. |
| Geographic Expansion | Regional assembly partnerships in Brazil's Cerrado frontier address ANVISA compliance and logistics cost structures. |
| Strategic Partnership | Dairy processor mandates in Wisconsin corridors convert equipment markets into outcome-based compliance service contracts. |
| Acquisition of Specialist Firm | Modular correction-service providers offer GNSS precision without full fleet replacement, threatening bundled platform incumbents. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary research incorporated interviews with precision agriculture platform engineers, farm cooperative procurement managers, OEM aftermarket service directors, and dairy processor compliance officers. Secondary sources included EPA pesticide documentation requirements, EU Green Deal implementation guidance, ANVISA agrochemical regulations, and customs records for agricultural equipment trade flows. Bottom-up sensor deployment estimates triangulated against top-down platform revenue disclosures.
Rate-of-change decomposition across the analysis window isolated volume expansion from price-mix effects and replacement-cycle acceleration. Segmentation dimensions modeled encompassed deployment architecture, solution type, functional application, and procurement authority concentration. CAGRs derived from fitted growth curves incorporating LPWAN protocol adoption rates, F-Gas Regulation compliance deadlines, and processor traceability mandate rollouts. Industry-specific inputs included satellite-guided variable-rate application penetration in Brazilian soybean operations and autonomous electric tractor pilot deployments across Iowa and Illinois.
Underlying measurement precision varies by segment; cloud-based deployment estimates carry tighter precision than edge computing given greater vendor disclosure transparency. Forecasts reflect documented assumptions regarding regulatory enforcement timing and semiconductor supply normalization. Agricultural commodity price volatility, trade policy shifts affecting equipment tariffs, and data sovereignty mandate fragmentation represent specific risk factors that could revise projections. A small set of named triggers—LPWAN coverage expansion, livestock processor mandate acceleration, and greenhouse emissions enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market