
 Commercial Grain Mill Market | 2026-2036
Commercial Grain Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Grain Mill Market Outlook
CE marking under the EU Machinery Directive is reorganizing competitive access for European-bound equipment, forcing retrofit investments from non-compliant suppliers. Bühler AG leverages its integrated manufacturing footprint across Switzerland and China to sustain premium positioning in roller mill systems. Satake Corporation anchors its Asian market presence through rice-specific milling expertise, while Alapala Machine Industry & Trade Inc. competes on turnkey project delivery across Black Sea grain corridors.
A commercial grain mill is an industrial machine that reduces cereal grains into flour, meal, or grits through mechanical grinding, sifting, and separation processes operating at throughput rates from 500 kg to over 100 tonnes per hour; its primary commercial purpose is producing standardized particle-size distributions for food manufacturing, feed formulation, and ethanol production. Roller mill configurations command the dominant installed base due to their energy efficiency in wheat and corn processing, while hammer mill demand accelerates in animal feed applications where fiber-rich ingredient flexibility matters. Advanced milling technology with real-time particle analysis captures expanding margin pools as processors pursue yield optimization and reduced waste.
The FDA enforces Current Good Manufacturing Practice and preventive controls under FSMA, compelling mill fabricators to redesign contact surfaces and validate clean-in-place protocols. OSHA's grain handling facility standards govern dust explosion prevention, shaping fan and filtration specifications in North American installations. The EU Machinery Directive plus ATEX directives for explosive atmospheres create dual compliance burdens for exporters. Stakeholders must monitor evolving mycotoxin thresholds and carbon accounting rules to anticipate equipment replacement cycles and certification investments.
Market Dynamics
Specialty flour processors are consolidating milling capacity to secure supply chain control against volatile commodity flows, while FSMA sanitation mandates force equipment redesign cycles that favor integrated system suppliers over component vendors.
Growth Catalysts
- Preventive Controls Regulation:FDA's FSMA rules compel bakeries and flour processors to validate clean-in-place protocols, accelerating replacement of legacy mills with sanitary-design equipment.
- Artisanal Bakery Expansion:Independent bakeries across the United States Corn Belt are installing mid-scale roller mills to control flour quality and reduce dependency on toll milling.
- Ethanol Feedstock Flexibility:Dry-grind ethanol producers are retrofitting hammer mill lines to handle variable corn moisture profiles, sustaining equipment refresh demand.
Market Restraints
- Stainless Steel Input Volatility:Food-grade 304 and 316 stainless steel price swings compress fabrication margins, forcing mill builders to index contracts or absorb cost spikes.
- Component Supply Concentration:Precision roller bearings and variable-frequency drives concentrate production in German and Japanese suppliers, creating lead time vulnerability for North American fabricators.
- ATEX Compliance Burden:EU Machinery Directive plus ATEX explosive atmosphere directives impose dual certification costs that lock smaller exporters out of European procurement channels.
Strategic Opportunities
- Black Sea Corridor Infrastructure:Turnkey milling projects in Turkey, Romania, and Ukraine offer expansion paths as grain export hubs modernize handling capacity.
- Rice Milling Technology Transfer:Asian rice-specific cleaning and whitening systems are adapting for quinoa and ancient grain processors in North American health food channels.
- Carbon Accounting Integration:EU CSRD disclosure requirements create service revenue pools for mill suppliers offering energy monitoring and Scope 3 footprint verification.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of real-time particle sensors with automated roll gap adjustment requires controls engineers with combined mechanical and software expertise, a skill set concentrated at agricultural universities in Switzerland and the Netherlands.
- Legacy Control System Migration:Facilities operating 1990s-era programmable logic controllers face expensive rip-and-replace cycles to achieve FDA 21 CFR Part 11 electronic record compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Grain Mill Market |
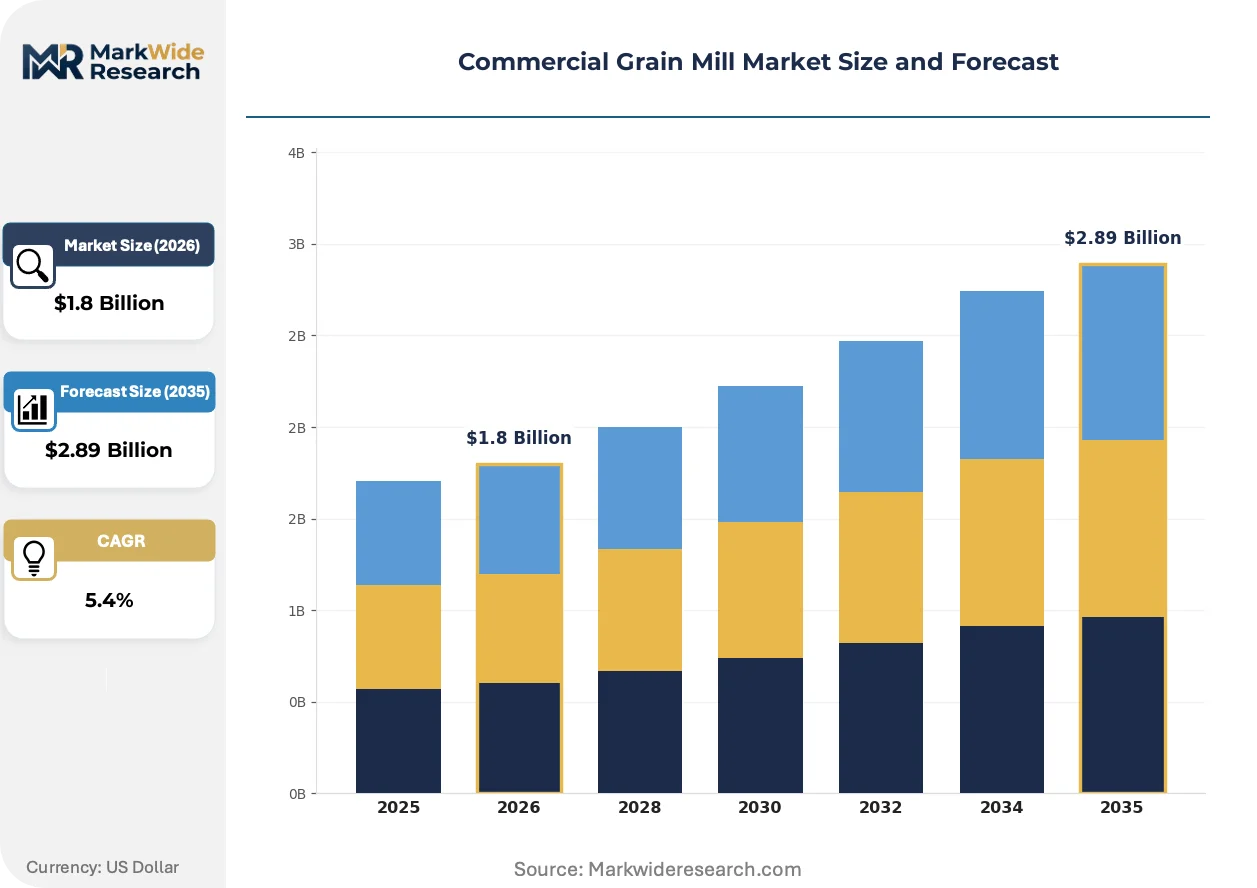
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammer Mill, Roller Mill, Stone Mill, Pin Mill End User: Food Processing, Animal Feed, Brewery, Biofuel Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale Technology: Conventional Milling, Advanced Milling, Hybrid Milling, Eco-friendly Milling |
| Companies Covered | Bühler AG, Satake Corporation, Alapala Machine Industry & Trade Inc., Ardent Mills, Archer Daniels Midland Company, Cargill Incorporated, General Mills Inc., Peterson Pacific Corporation, Grain Millers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Grain Mill Market Strategic Shifts
Real-time process analytics and modular equipment architectures are compressing the traditional ten-year mill replacement cycle, forcing suppliers to pivot from capital sales toward performance-based service relationships.
Inline NIR spectroscopy for moisture and protein measurement is miniaturizing from laboratory bench units to mill-integrated sensors. Artisanal and specialty flour processors in Vermont and California are adopting these systems fastest, enabling continuous blend adjustment that was previously reserved for industrial-scale operations. This capability compression is eroding the quality-assurance advantage that large cooperatives historically held over independent mills.
REACH restrictions on chromium plating are forcing roller manufacturers to shift toward tungsten carbide thermal spray coatings. European mill fabricators face the steepest compliance timeline, with surface treatment suppliers in Italy and Germany scrambling to qualify alternatives before 2026 sunset dates. The transition is compressing roller reconditioning economics and accelerating interest in ceramic composite roll materials.
Flour procurement by craft bakeries is fragmenting from commodity bulk purchasing toward direct relationships with regional mills specifying heritage wheat varieties. This channel disintermediation is visible strongest in the Pacific Northwest, where Portland and Seattle bakeries now specify exact protein content and ash specifications rather than accepting standard patent flour grades. Mill suppliers are responding with smaller-batch cleaning and tempering systems designed for identity-preserved grain flows.
Commercial Grain Mill Market Segmentation
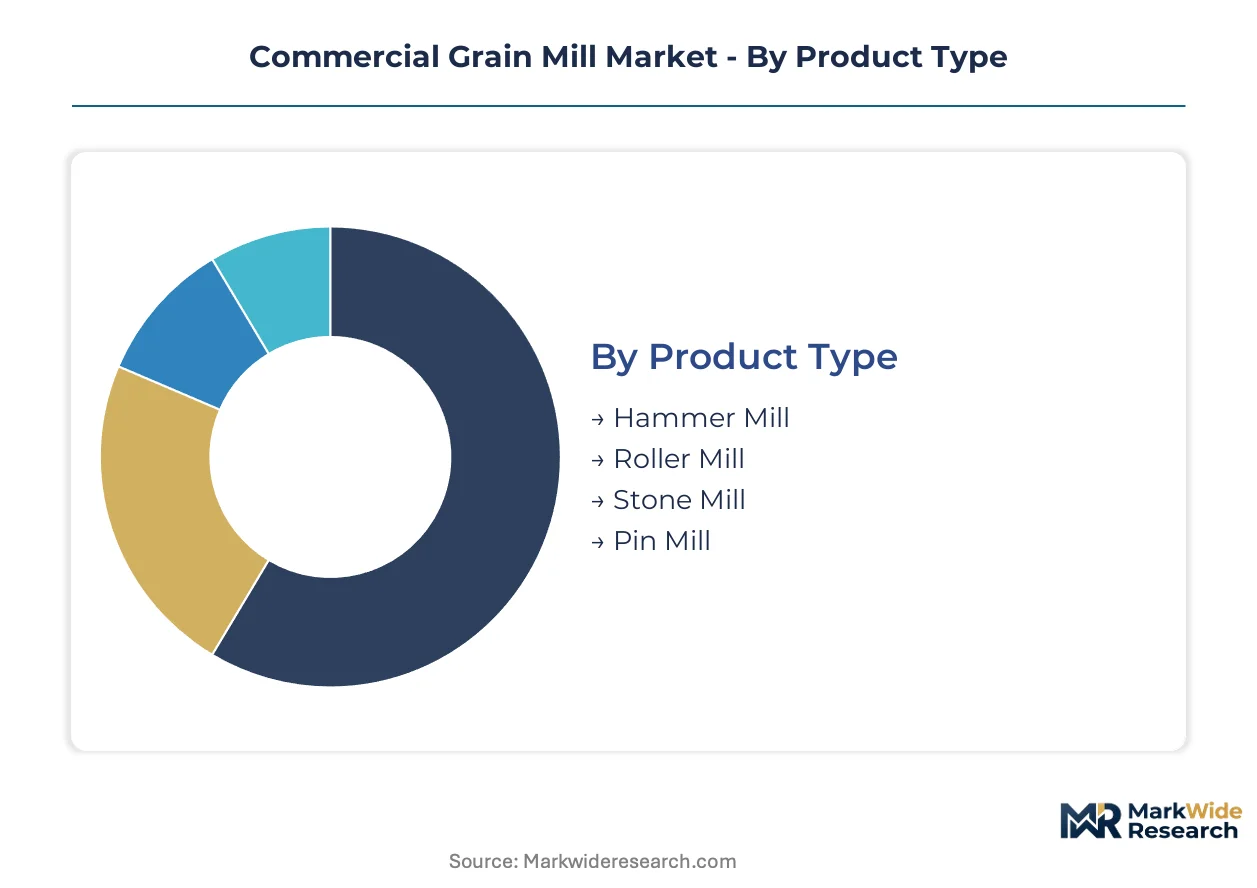
Equipment segmentation in the commercial grain mill market reveals distinct technology-to-application matching patterns, where substitution pressures from alternative processing methods reshape investment priorities across milling configurations.
Product Type:
Roller mill systems face intensifying substitution pressure from hammer mill alternatives in fiber-heavy applications, while stone mill configurations compete against modern precision grinding in specialty flour channels.
- Roller Mill:Multi-roll configurations achieve particle size reduction through compression and shear forces between corrugated steel cylinders, delivering uniform flour extraction rates critical for standardized baking applications. Demand concentrates in wheat and corn processing facilities across the United States Corn Belt, where large cooperatives modernize legacy installations to meet FSMA preventive control mandates for sanitary design and clean-in-place validation.
- Hammer Mill:Rotating hammers mounted on a central shaft pulverize grains through impact forces, accommodating variable moisture content and fiber-rich ingredients without roll gap adjustment complexity. Ethanol producers in Iowa and Illinois are retrofitting hammer mill lines to handle variable corn moisture profiles, sustaining equipment refresh demand as dry-grind facilities seek feedstock flexibility.
- Stone Mill:Corundum or natural stone grinding surfaces preserve enzymatic activity and germ integrity, producing whole grain flours with elevated ash content prized by heritage wheat processors.
- Pin Mill:High-speed rotating pins create turbulent particle collisions for ultra-fine grinding, serving spice and ancient grain applications requiring sub-100 micron distributions.
Roller mill configurations anchor the volume base while hammer mill demand gains share at the steepest rate in biofuel and animal feed channels.
End User:
Cost tier stratification separates capital-intensive integrated systems serving high-volume processors from modular equipment purchased by independent specialty operators.
- Food Processing:Industrial bakeries and flour blenders require continuous-duty equipment with real-time particle analysis integration to maintain tight protein and ash specifications across high-throughput operations. Artisanal bakeries in Vermont and California are installing mid-scale systems with inline NIR spectroscopy, enabling continuous blend adjustment that compresses the quality-assurance gap with large cooperatives.
- Animal Feed:Compound feed manufacturers prioritize hammer mill flexibility for processing diverse ingredient matrices including dried distillers grains, soybean meal, and forage products with varying fiber content. Regional feed mills in Nebraska and Kansas are consolidating toward fewer, larger facilities with automated batching and grinding lines to capture scale economies.
- Brewery:Craft maltsters and commercial breweries demand precise grist particle distributions for optimal mash conversion efficiency, favoring two-roller or four-roller configurations with adjustable gap settings.
- Biofuel:Dry-grind ethanol plants require robust size reduction equipment capable of processing high-tonnage corn streams with minimal downtime during harvest surge periods.
Food processing applications anchor the volume base while brewery installations expand most quickly in craft maltster channels.
Capacity:
Volume-based procurement patterns concentrate large-scale investments among cooperative processors while small-scale demand fragments across independent specialty millers.
- Large Scale:Systems processing 50-100 tonnes per hour serve central grain elevators and export terminals requiring continuous operation during harvest windows. Facilities along the Mississippi River corridor in Minnesota and Wisconsin are replacing 1980s-era equipment with automated tempering and grinding trains to handle identity-preserved soybean and specialty corn contracts.
- Industrial Scale:Installations exceeding 100 tonnes per hour integrate into multinational food manufacturing campuses with dedicated utility infrastructure and 24/7 operational requirements. Archer Daniels Midland and Cargill processing complexes in Decatur, Illinois maintain captive maintenance teams for these installations.
- Medium Scale:Equipment in the 10-50 tonne per hour range serves regional flour mills and independent feed compounders balancing throughput against capital constraints.
- Small Scale:Units below 10 tonnes per hour support farm-scale operations, research facilities, and specialty grain processors requiring batch flexibility.
Large scale systems anchor the volume base while medium scale configurations climb the fastest in regional specialty flour channels.
Technology:
Margin stratification separates premium-priced advanced milling systems with integrated analytics from conventional equipment competing on initial capital cost.
- Advanced Milling:Real-time particle size analyzers, automated roll gap adjustment, and predictive maintenance algorithms enable yield optimization and reduced waste in high-volume operations. Bühler AG and Satake Corporation are deploying these systems across Asian rice milling corridors and European wheat processing facilities to capture service revenue from performance-based contracts.
- Conventional Milling:Mechanical grinding and sifting without sensor integration maintains lowest capital cost for price-sensitive processors in developing markets and legacy facility upgrades. Black Sea grain corridor projects in Romania and Turkey often specify conventional configurations to minimize foreign exchange exposure on equipment imports.
- Hybrid Milling:Combinations of roller and impact grinding stages optimize specific energy consumption across multi-product facilities processing both wheat and coarse grains.
- Eco-friendly Milling:Regenerative braking, heat recovery systems, and biodegradable lubricant specifications address EU CSRD disclosure requirements and corporate Scope 3 reduction targets.
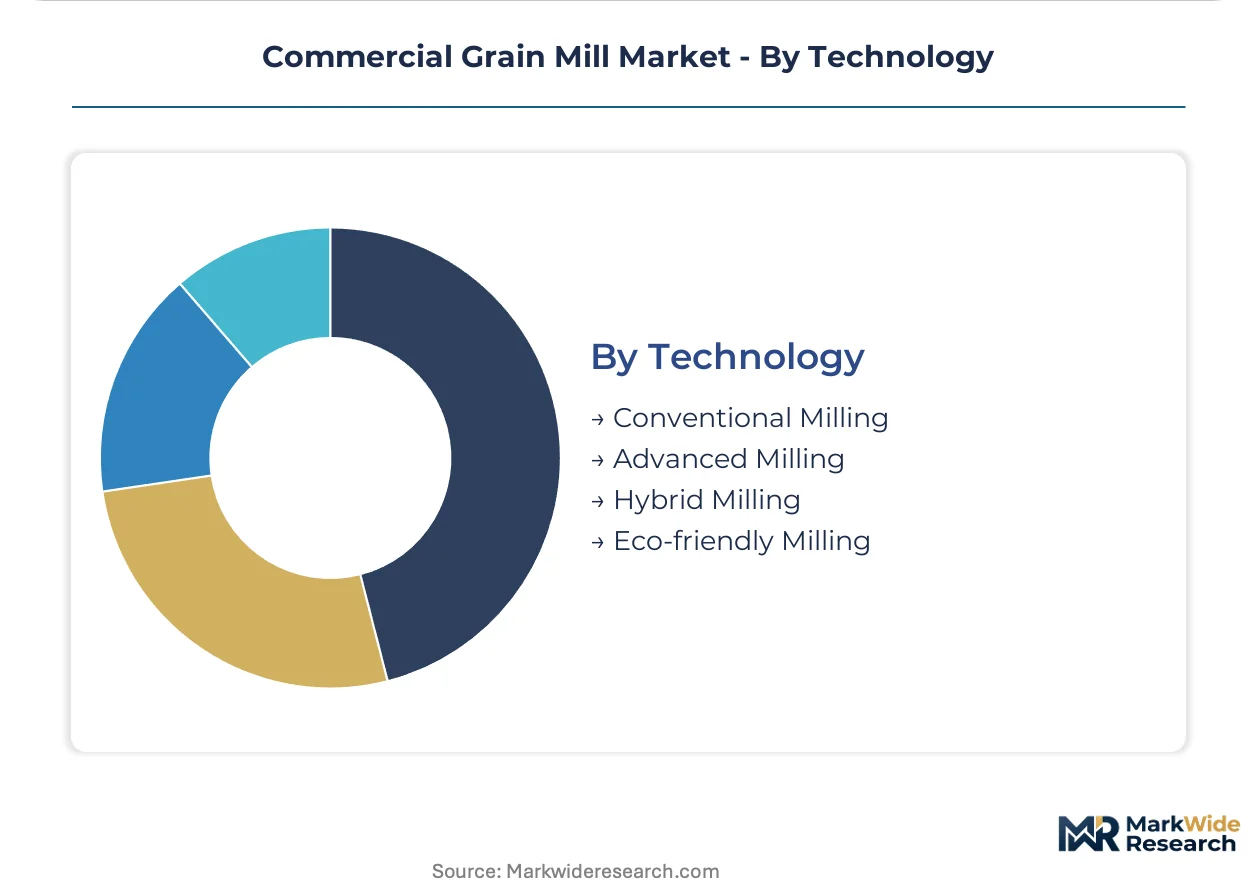
Conventional milling anchors the volume base while advanced milling systems gain share at the steepest rate in premium flour and export-oriented installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale cooperatives and specialty flour processors concentrate equipment procurement in agricultural belts with established grain handling infrastructure, while regulatory divergence across major economies fragments supplier compliance requirements.
United States
Artisanal bakeries across the Corn Belt are installing mid-scale roller mills to secure supply chain control over heritage wheat varieties. FDA enforcement of FSMA preventive controls compels equipment redesign for sanitary validation and clean-in-place protocols. Minneapolis-St. Paul anchors milling technology demand as regional cooperatives modernize 1980s-era facilities along the Mississippi River corridor.
Germany
Precision component suppliers for roller bearings and variable-frequency drives face lead time pressures from compound feed manufacturers prioritizing hammer mill flexibility. REACH restrictions on chromium plating force roller manufacturers toward tungsten carbide thermal spray coatings before 2026 sunset dates. Stuttgart and Munich industrial clusters concentrate surface treatment suppliers scrambling to qualify REACH-compliant alternatives.
China
Integrated manufacturing footprints sustain premium positioning in roller mill systems serving domestic wheat processing expansion. Dual carbon goals under MEE oversight accelerate interest in regenerative braking and heat recovery specifications for new installations. Yangtze River Delta grain processors are retrofitting conventional milling lines with energy monitoring systems to address emerging Scope 3 disclosure requirements.
Turkey
Turnkey milling projects across Black Sea grain corridors drive demand for conventional configurations minimizing foreign exchange exposure on equipment imports. EU Machinery Directive compliance burdens reshape competitive access for European-bound equipment from Turkish fabricators. Istanbul and Izmir serve as procurement hubs for Romanian and Ukrainian export terminal modernization.
Japan
Rice-specific cleaning and whitening systems adapt for quinoa and ancient grain processors targeting North American health food channels. METI standards govern mechatronics integration for real-time particle sensors with automated roll gap adjustment. Osaka-based engineering talent concentrates controls expertise combining mechanical and software disciplines for advanced milling deployments.
Commercial Grain Mill Market Competitive Environment
Player mix skews toward integrated system suppliers with captive manufacturing footprints and component vendors serving price-sensitive regional markets. Structure consolidates around premium-tier roller mill specialists and mid-market hammer mill fabricators competing on delivery speed. Strategic archetypes separate turnkey project integrators from precision component specialists and regional service providers. Dominant competitive moves include geographic footprint expansion through manufacturing co-location and portfolio diversification into adjacent grain handling equipment.
Among Swiss and Chinese integrated manufacturers, Bühler AG occupies a position exemplifying premium-tier roller mill system supply with cross-border manufacturing coordination. Satake Corporation represents rice-specific milling expertise adapted for broader grain applications across Asian corridors. Alapala Machine Industry & Trade Inc. anchors turnkey project delivery capabilities concentrated on Black Sea infrastructure modernization.
| Leading Market Players |
|---|
| Bühler AG |
| Satake Corporation |
| Alapala Machine Industry & Trade Inc. |
| Ardent Mills |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| General Mills Inc. |
| Peterson Pacific Corporation |
| Grain Millers Inc. |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for precision roller bearings from German and Japanese suppliers concentrate procurement power among integrated mill fabricators, compressing margins for North American assemblers while amplifying pricing leverage for captive-manufacturing specialists.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange stainless steel pricing dominate equipment procurement, with food-grade 304 and 316 grades driving quarterly price adjustments. Price differentiation separates FSMA-validated sanitary-design systems from conventional configurations, while volume-scale discounts anchor large cooperative negotiations. Pricing pressure stems from REACH-compliant surface treatment transitions as tungsten carbide coatings displace chromium plating. Regional feed mills in Nebraska and Kansas exhibit highest price sensitivity, whereas artisanal bakeries in Vermont and California prioritize specification compliance over capital cost.
Supply Chain Analysis
Strategic stockpiling of roller bearings and variable-frequency drives prevails over just-in-time approaches, reflecting eighteen-month qualification cycles for precision components. Manufacturing concentrates in Switzerland, China, and Turkey, with component sourcing drawing from German bearing specialists and Japanese drive manufacturers. Raw material dependencies center on food-grade stainless steel, tungsten carbide thermal spray feedstock, and ceramic composite roll substrates. Single-source vulnerability concentrates in precision bearing supply, with distribution running through OEM-direct channels and regional service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FSMA validation protocols and ATEX certification timelines create structural barriers that compound incumbent advantages over multi-year replacement cycles.
For Market Incumbents: Compound certification entrenchment by accelerating CE marking compliance ahead of EU Machinery Directive enforcement windows, while deepening captive supply of precision roller bearings through backward integration into German component partnerships. Threats from Asian rice-milling technology transfer into quinoa and ancient grain channels demand preemptive channel control in Pacific Northwest specialty flour corridors. For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track validation for electronic record compliance offers entry leverage into legacy facility upgrade cycles, particularly targeting 1990s-era PLC migrations in Midwestern cooperatives. White-space concentrates in medium-scale identity-preserved grain systems for heritage wheat processors, with go-to-market traction achievable through performance-based service contracts displacing capital-sales incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FSMA and ATEX compliance burdens accelerate consolidation toward turnkey-integrated suppliers with captive manufacturing footprints. Acquisition targets should display vertical integration into precision component supply or established Black Sea corridor project pipelines. Watch for stainless steel price volatility crossing thresholds that trigger contract renegotiation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Sanitary-Design Certification Investment | FSMA validation protocols lock out component vendors lacking integrated clean-in-place engineering. |
| Precision Component Backward Integration | Captive roller bearing supply secures margin protection against German and Japanese supplier concentration. |
| Black Sea Turnkey Project Expansion | Romanian and Ukrainian export terminal modernization channels foreign exchange-minimized procurement. |
| Real-Time Analytics Service Pivot | Inline NIR spectroscopy integration captures recurring revenue from yield-optimization contracts. |
| REACH-Compliant Surface Treatment Transition | Tungsten carbide thermal spray qualification ahead of chromium plating sunset dates defends European access. |
Study Parameters
Desk research of trade customs data, FDA enforcement records, and EU Machinery Directive guidance documents preceded structured interviews with plant engineers at regional flour mills, procurement leads at ethanol processing facilities, aftermarket service heads at OEM distributors, and maintenance directors at compound feed manufacturers. Primary fieldwork combined with secondary validation from SEC filings of integrated food processors, Bühler AG technical documentation, and Satake Corporation patent filings. Bottom-up equipment shipment analysis triangulated against top-down grain processing capacity expansion announcements.
Variance decomposition across product type, end-use application, capacity tier, and technology sophistication levels shaped the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory compliance-driven upgrade timelines, and grain export infrastructure investment pipelines. Modeled inputs included FSMA enforcement intensity indices, stainless steel price volatility bands, and Black Sea grain corridor modernization project pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA preventive control enforcement and stable German-Japanese component supply relationships; material deviation would warrant model refresh. Revision becomes warranted when REACH alternative coating qualification delays or stainless steel price spike duration crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Global Precision Harvesting Market