
 Brazil Forage Seed Market | 2026-2036
Brazil Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Forage Seed Market Outlook
Certified seed tiers is bifurcating the competitive landscape as producers trade up from farm-saved material. Corteva Agriscience leverages its breeding pipeline to dominate proprietary tropical grass varieties. DLF Seeds and Science anchors its position through deep distribution partnerships with southern Brazilian cooperatives. Barenbrug do Brasil specializes in rhizomatous perennial grasses tailored to Cerrado soil conditions.
Forage seed comprises botanically verified germplasm selected for germination rate, nutritional value, and persistence under grazing pressure, produced through controlled pollination and conditioning to establish productive pastures. Grasses occupy the volume core due to their role in beef cattle finishing systems across the Pantanal and Cerrado biomes. Legumes capture expanding margin pools as dairy operators seek nitrogen-fixing companions to reduce synthetic fertilizer dependency. Mixed varieties gain traction in crop-livestock integration zones where rotation complexity demands multi-species swards.
MAPA enforces cultivar registration and seed quality standards that determine commercial eligibility, while ANVISA monitors pesticide residues on treated seed lots entering the food chain. These frameworks elevate compliance costs for smaller suppliers but reinforce barriers that favor certified operations with laboratory and field-testing infrastructure. Stakeholders must track pending revisions to Brazil's Seed Law that could reshape royalty collection on protected varieties.
Market Dynamics
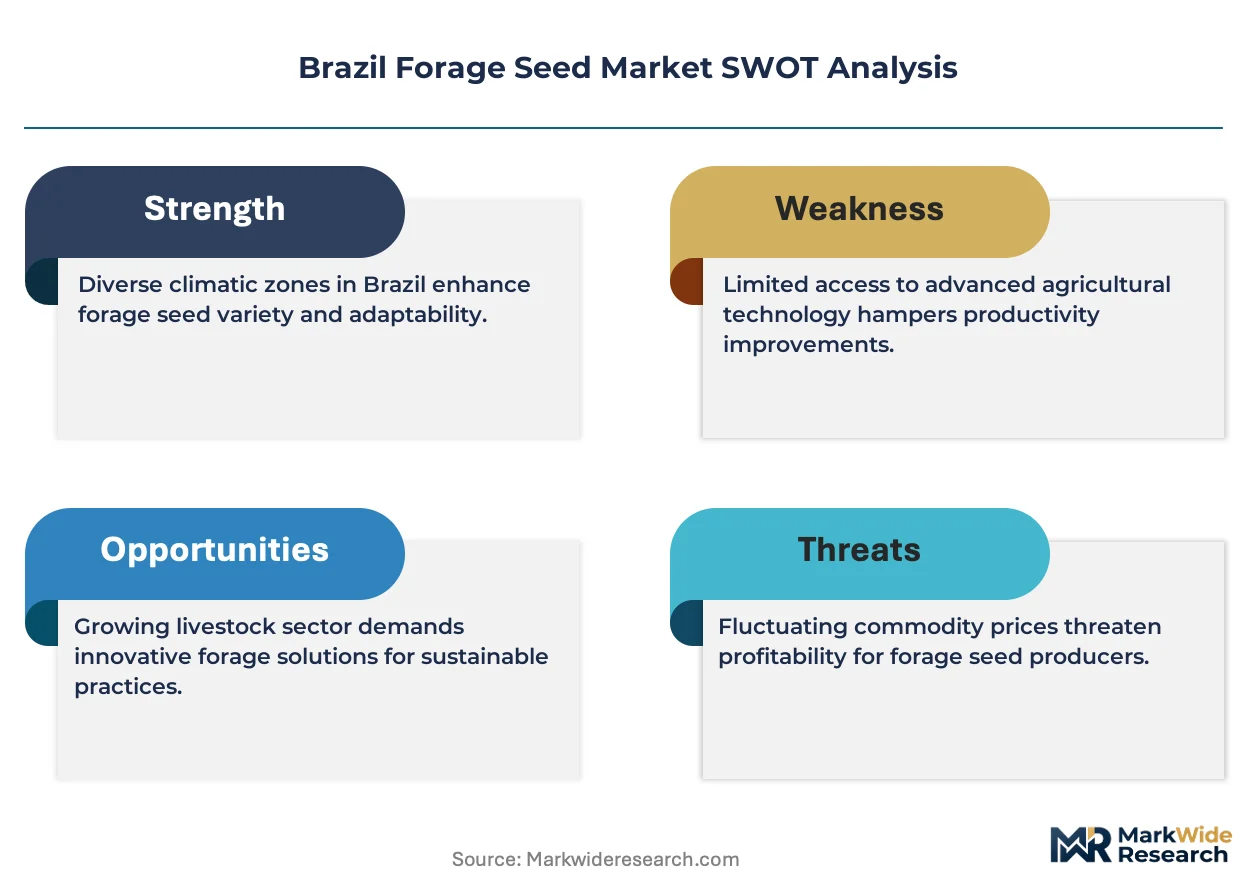
Certified seed adoption is compressing farm-saved germplasm cycles across Brazil's pasture renewal corridors. MAPA's cultivar registration requirements and ANVISA's residue monitoring protocols are elevating compliance thresholds that favor laboratory-equipped suppliers over informal operators.
Growth Catalysts
- MAPA Seed Certification:Mandatory cultivar registration and quality standards are phasing out uncertified germplasm, creating structured upgrade pathways for commercial operators.
- Dairy Intensification:Beef-dairy integration corridors in Mato Grosso do Sul are driving accelerated pasture renovation cycles with higher-value certified varieties.
- Nitrogen-Fixing Legumes:Synthetic fertilizer cost pressures are expanding companion planting of nitrogen-fixing legumes alongside tropical grasses.
Market Restraints
- Input Cost Volatility:Phosphorus and potassium fertilizer price swings compress margins for pasture establishment requiring nutrient amendments.
- Biome-Specific Adaptation:Cerrado soil acidity and aluminum toxicity limit direct cultivar transferability from temperate breeding programs.
- Seed Treatment Regulation:ANVISA's tightening residue thresholds on chemically treated seed lots extend compliance timelines for commercial release.
Strategic Opportunities
- Pantanal Restoration:Seasonal flooding tolerance in rhizomatous perennial grasses opens premium positioning for specialized germplasm in wetland-adjacent zones.
- Cooperative Distribution:Southern Brazilian agricultural cooperatives present underutilized channels for certified seed penetration beyond traditional retail.
- Crop-Livestock Integration:Rotation complexity in integrated systems is creating demand for multi-species sward mixtures with defined seasonal performance windows.
Industry Challenges
- Field Testing Infrastructure:Multi-location cultivar performance trials require sustained capital deployment across contrasting Cerrado and Pantanal conditions.
- Protected Variety Enforcement:Pending Seed Law revisions threaten to complicate royalty collection mechanisms for proprietary tropical grass breeding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Forage Seed Market |
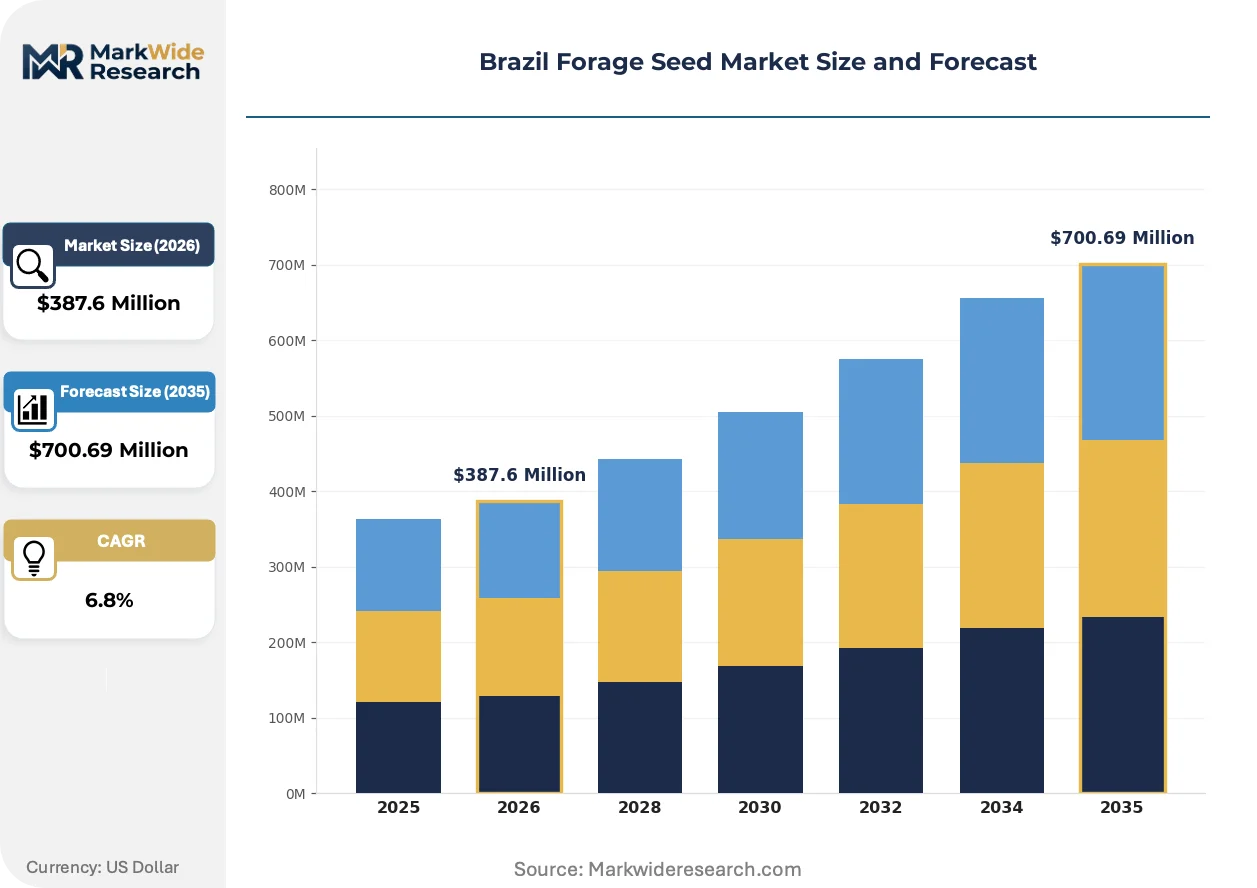
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grasses, Legumes, Mixed Varieties, Native Species End User: Dairy Farmers, Livestock Producers, Agronomists, Research Institutions Application: Pasture Establishment, Crop Rotation, Erosion Control, Soil Restoration Distribution Channel: Online Retailers, Agricultural Cooperatives, Nurseries, Direct Sales |
| Companies Covered | Corteva Agriscience, DLF Seeds and Science, Deutsche Saatveredelung AG, Advanta Seeds (UPL), Barenbrug do Brasil, Agria Corporation, Germisul Seeds Ltd, Wolf Sementes, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Forage Seed Market Strategic Shifts
Digital phenotyping and accelerated breeding pipelines are compressing cultivar development cycles. Germplasm verification technologies and precision conditioning equipment are reshaping quality assurance protocols.
Molecular marker-assisted selection is fragmenting traditional pedigree-based breeding timelines. Large-scale seed producers in São Paulo and Paraná are deploying genomic screening to compress generational advancement. This compression is fragmenting competitive moats between established breeders and agile regional programs with laboratory partnerships.
MAPA's pending Seed Law revision is recalibrating intellectual property enforcement for protected tropical varieties. Royalty collection mechanisms face restructuring that may favor vertically integrated breeding-to-conditioning operations. Southern Brazilian cooperatives are mobilizing compliance infrastructure in anticipation of stricter cultivar documentation requirements.
Direct procurement relationships between seed conditioners and large integrated livestock operations are displacing traditional distributor intermediaries. Volume commitments from beef-dairy integration zones in Mato Grosso do Sul are consolidating purchase authority with fewer buyers. This concentration is most visible in the Cerrado fringe where thousand-hectare pasture blocks dominate renewal schedules.
Brazil Forage Seed Market Segmentation
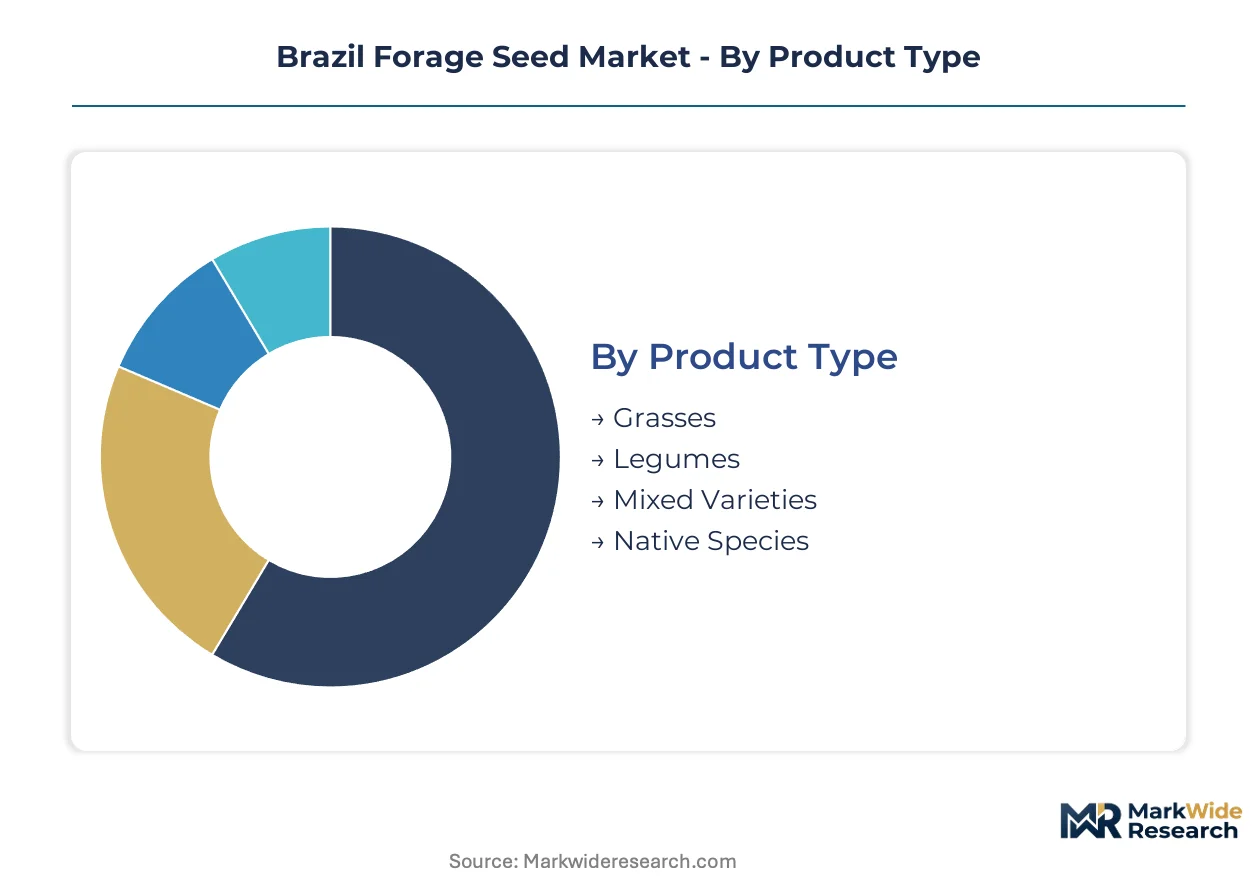
Forage seed purchasing patterns in Brazil diverge sharply between domestic pasture renewal cycles and export-oriented germplasm development. MAPA certification requirements reshape demand composition across every segment tier. Understanding these splits reveals where certified varieties command premium positioning versus where farm-saved material persists.
Product Type:
Grasses dominate domestic volume through beef-dairy integration corridors, while legume development attracts export-oriented breeding investment. Native species recovery programs concentrate in Pantanal restoration zones with distinct procurement channels.
- Grasses:Tropical and temperate grass species selected for germination rate, nutritional density, and persistence under intensive grazing pressure. Demand concentrates in Mato Grosso do Sul's beef-dairy integration corridor where accelerated pasture renovation cycles favor certified Brachiaria and Panicum varieties with proven aluminum tolerance.
- Legumes:Nitrogen-fixing species including Stylosanthes and Arachis pintoi developed for companion planting with tropical grasses. Dairy operators in Paraná and Minas Gerais drive adoption as synthetic fertilizer cost pressures intensify, creating margin pools for proprietary cultivars with verified nodulation performance.
- Mixed Varieties:Multi-species sward formulations designed for crop-livestock integration zones where rotation complexity demands defined seasonal performance windows. Agronomists in São Paulo's sugarcane-beef transition belt specify these blends for soil structure maintenance between cash crop cycles.
- Native Species:Cerrado and Pantanal-adapted germplasm recovered for conservation grazing and wetland restoration. Public procurement through MAPA-supported rehabilitation programs anchors demand, with limited commercial scale outside government conservation contracts.
Grasses hold the largest share; momentum sits with legumes as nitrogen-fixing companions gain traction in dairy intensification zones.
End User:
Livestock producers split between thousand-hectare integrated operations with direct conditioner relationships and fragmented smallholders relying on cooperative channels. Research institutions anchor germplasm verification but represent minimal commercial volume.
- Dairy Farmers:Operators running crossbred herds in Minas Gerais and Paraná with specialized nutritional requirements driving certified seed premiums. These buyers prioritize cultivars with documented milk yield response and persistency under rotational grazing.
- Livestock Producers:Beef-focused operations spanning cow-calf through finishing systems across Pantanal and Cerrado biomes. Thousand-hectare pasture blocks in Mato Grosso do Sul consolidate purchase authority with direct procurement from major conditioners.
- Agronomists:Technical consultants specifying cultivar selections for integrated crop-livestock clients. Their recommendations bridge certified commercial varieties and experimental lines from regional breeding programs.
- Research Institutions:EMBRAPA and state agricultural research units managing cultivar performance trials and germplasm banks. These entities influence commercial eligibility through MAPA registration support but consume negligible certified seed volume directly.
Livestock producers command the volume base; agronomists are expanding most quickly as technical specification authority concentrates in consultant hands.
Application:
Pasture establishment absorbs the certified seed premium as MAPA registration becomes mandatory for commercial eligibility. Soil restoration applications remain fragmented across public conservation programs with irregular procurement cycles.
- Pasture Establishment:Primary commercial application involving complete sward renovation on degraded grazing lands. Beef-dairy integration zones in Mato Grosso do Sul drive the steepest expansion trajectory as operators compress renewal cycles from seven to four years.
- Crop Rotation:Forage integration into cash crop sequences for soil structure maintenance and livestock feed security. São Paulo's sugarcane regions and southern soybean belts specify cover crop-forage hybrids with dual harvest windows.
- Erosion Control:Sloped Cerrado fringe plantings targeting ground cover establishment ahead of seasonal rains. State environmental compliance requirements in Goiás and Mato Grosso create sporadic demand spikes tied to licensing enforcement.
- Soil Restoration:Degraded land rehabilitation using deep-rooted perennials for organic matter accumulation and aluminum toxicity mitigation. MAPA-supported programs in western Bahia anchor demand, with limited private commercial traction.
Pasture establishment holds the largest share; crop rotation gains share fastest as integrated systems proliferate.
Distribution Channel:
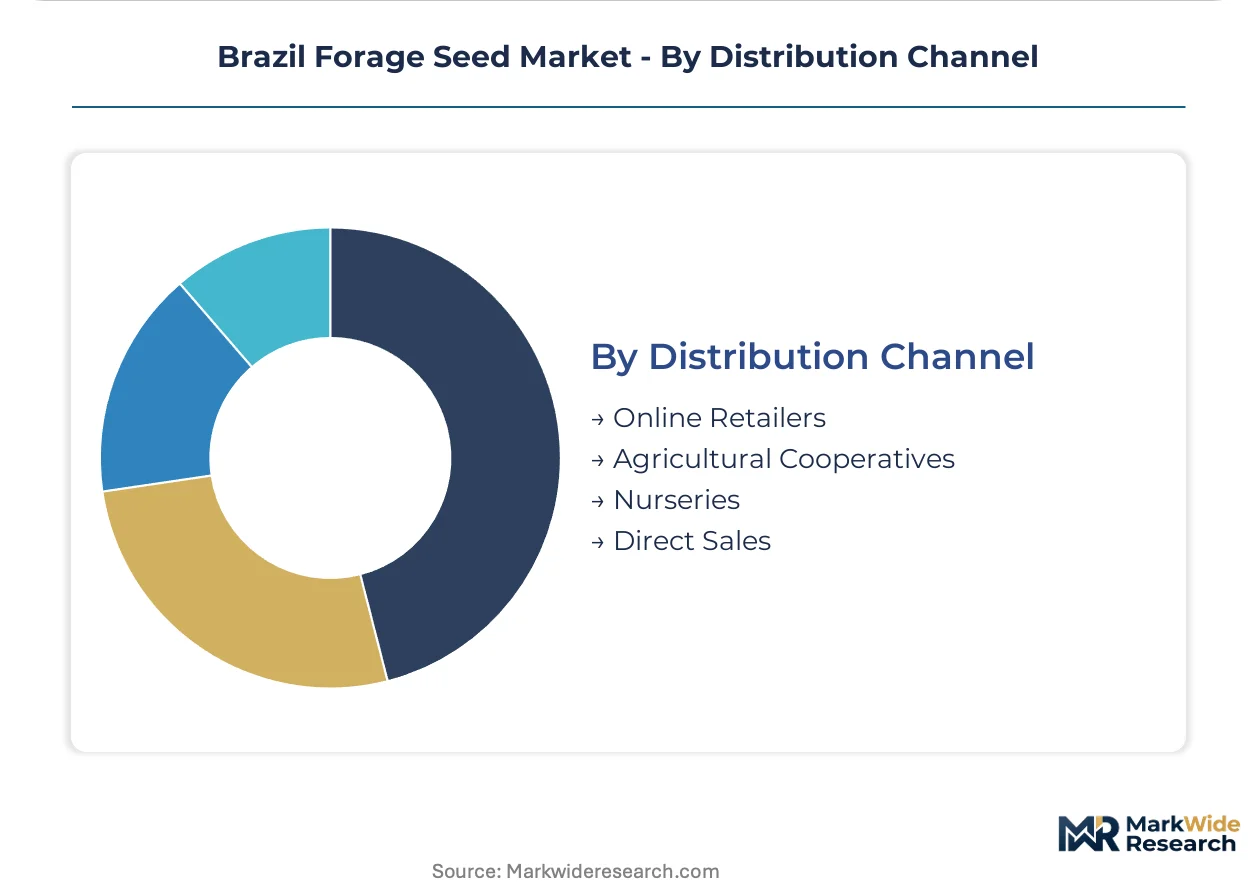
Agricultural cooperatives concentrate southern Brazilian volume while direct sales capture integrated livestock operations. Online retail remains marginal given germplasm verification requirements and bulk logistics constraints.
- Agricultural Cooperatives:Member-owned distributors dominating Paraná, Rio Grande do Sul, and southern São Paulo. These channels leverage embedded agronomic advisory services to push certified varieties against farm-saved alternatives.
- Direct Sales:Conditioner-to-producer relationships bypassing traditional retail for large integrated operations. Mato Grosso do Sul's thousand-hectare pasture blocks consolidate purchase authority through volume commitments with breeding-to-conditioning operations.
- Nurseries:Regional plant propagation specialists serving smallholder segments with pre-germinated plug trays and technical support. These operators concentrate in Minas Gerais dairy belts where establishment failure risks deter direct seeding.
- Online Retailers:E-commerce platforms offering catalog convenience for standard cultivars with established performance records. ANVISA documentation requirements and bulk shipment economics limit penetration to hobby farmers and specialty seed seekers.
Agricultural cooperatives hold the largest share; direct sales are climbing the fastest as buyer concentration proceeds in major integration zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seed conditioning infrastructure clusters in São Paulo and Paraná, with breeding trials dispersed across Cerrado and Pantanal biome boundaries. MAPA's cultivar registration requirements create compliance thresholds that favor laboratory-equipped suppliers in southern states over informal operators in frontier zones.
Mato Grosso do Sul
Beef-dairy integration corridors drive accelerated pasture renovation cycles, compressing renewal intervals from seven to four years. MAPA certification mandates phase out farm-saved germplasm in commercial operations. Thousand-hectare pasture blocks around Campo Grande consolidate purchase authority through direct procurement relationships with major conditioners.
São Paulo
Sugarcane-beef transition belts generate demand for multi-species sward mixtures supporting crop-livestock rotation. State environmental compliance requirements create sporadic demand spikes for erosion control seedings on sloped terrain. Piracicaba-based research clusters anchor EMBRAPA cultivar performance trials influencing commercial eligibility.
Paraná
Dairy intensification zones around Londrina and Maringá prioritize nitrogen-fixing legume companions to reduce synthetic fertilizer dependency. Agricultural cooperatives dominate distribution channels, leveraging embedded agronomic advisory to push certified varieties. DLF Seeds and Science anchors position through deep partnerships with these member-owned distributors.
Minas Gerais
Crossbred dairy herds in the Triângulo Mineiro and Zona da Mata drive certified seed premiums based on documented milk yield response. Nursery channels concentrate in dairy belts where establishment failure risks deter direct seeding. Corteva Agriscience leverages breeding pipeline dominance to supply proprietary tropical grass varieties.
Goiás
Cerrado fringe plantings target ground cover establishment ahead of seasonal rains on degraded grazing lands. State environmental licensing enforcement creates irregular demand for erosion control applications. Barenbrug do Brasil specializes in rhizomatous perennial grasses tailored to aluminum-toxic soil conditions prevalent in western production zones.
Brazil Forage Seed Market Competitive Environment
Concentration sits with integrated breeding-to-conditioning operations possessing laboratory and field-testing infrastructure. Three tiers structure competitive positioning: multinational breeders with proprietary tropical varieties, regional specialists with biome-adapted germplasm, and cooperative-linked distributors with embedded advisory capacity. Strategic moves center on backward integration into captive seed production and direct procurement relationships displacing traditional retail intermediaries.
Among multinational breeders, Corteva Agriscience and Bayer AG exemplify archetypes leveraging global breeding pipelines for proprietary tropical grass development. DLF Seeds and Science occupies a position within the cooperative-linked tier, anchoring distribution through southern Brazilian agricultural partnerships. Barenbrug do Brasil represents the regional specialist archetype, concentrating on rhizomatous perennial varieties adapted to specific Cerrado soil constraints. Deutsche Saatveredelung AG and Advanta Seeds (UPL) sit within mid-scale breeding operations competing on cultivar registration speed and MAPA compliance infrastructure.
| Leading Market Players |
|---|
| Corteva Agriscience |
| DLF Seeds and Science |
| Deutsche Saatveredelung AG |
| Advanta Seeds (UPL) |
| Barenbrug do Brasil |
| Agria Corporation |
| Germisul Seeds Ltd |
| Wolf Sementes |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between thousand-hectare integrated livestock operations and major seed conditioners lock in supply access while anchoring price visibility across MAPA-mandated certification tiers. These contracts compress spot market liquidity and concentrate pricing power with laboratory-equipped suppliers capable of meeting ANVISA residue documentation requirements.
Pricing Analysis
MAPA's cultivar registration protocols dictate the pricing tier structure across the Brazilian market. Pricing stratifies across certified proprietary varieties, registered commercial standards, and residual farm-saved germplasm. Certification grade and volume scale drive price differentiation, with thousand-hectare pasture blocks commanding preferential rates through direct procurement relationships. Cost compression in mid-tier certified varieties is intensifying because phosphorus and potassium fertilizer price volatility erodes pasture establishment margins. Smallholder dairy operators in Minas Gerais exhibit the highest price sensitivity, while integrated beef-dairy corridors in Mato Grosso do Sul prioritize performance documentation over unit cost.
Supply Chain Analysis
Seed inventory cycles stretch from conditioning facilities in São Paulo and Paraná to Pantanal fringe planting windows, creating compressed lead times during seasonal demand surges. Supply concentrates in Brazil's southern states, with germplasm development anchored in EMBRAPA research clusters and captive breeding programs. The chain draws from controlled pollination operations, laboratory verification infrastructure, and rhizomatous perennial multiplication fields. Single-source vulnerability sits with proprietary tropical grass breeding lines where pending Seed Law revisions threaten royalty collection mechanisms. Distribution runs through agricultural cooperatives in southern zones and direct conditioner relationships in Mato Grosso do Sul integration corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farm-saved germplasm persistence threatens incumbent revenue streams as MAPA enforcement gaps allow informal seed exchange in frontier zones. Defending certified seed premiums requires structural moves that embed suppliers irreplaceably into pasture renewal workflows.
For Market Incumbents: Compound laboratory and field-testing infrastructure investments to compress cultivar registration timelines against agile regional competitors. Deepen backward integration into captive seed production in Cerrado-adapted germplasm to secure supply continuity against aluminum toxicity breeding failures. ANVISA documentation requirements favor incumbents with existing compliance infrastructure.
For New Entrants and Emerging Players: MAPA fast-track cultivar registration for nitrogen-fixing legume companions offers the most penetrable entry point. Target dairy intensification zones in Paraná where synthetic fertilizer cost pressures drive rapid adoption of Stylosanthes and Arachis pintoi varieties. Partner with southern Brazilian cooperatives to leverage embedded agronomic advisory channels for certified seed penetration.
For Investors and Strategic Acquirers: Regional specialists with biome-adapted rhizomatous perennial germplasm and existing MAPA registration portfolios represent the most compelling acquisition targets. Long-term viability hinges on intellectual property enforcement clarity under pending Seed Law revisions. Watch for EMBRAPA cultivar performance trial outcomes as inflection indicators for commercial eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Breeding | Secures proprietary tropical grass germplasm control against royalty collection uncertainty. |
| Cooperative Distribution Partnership | Embeds certified seed access through member-owned channels with agronomic advisory capacity. |
| MAPA Certification Infrastructure Investment | Accelerates cultivar registration timelines and elevates barriers against informal operators. |
| Direct Procurement Relationship Development | Consolidates purchase authority with thousand-hectare integrated livestock operations. |
| Legume Companion Portfolio Expansion | Captures nitrogen-fixing demand from dairy operators reducing synthetic fertilizer dependency. |
Study Parameters
A spread of perspectives from seed conditioning facility managers, cooperative agronomic advisors, EMBRAPA research directors, and integrated livestock procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across São Paulo, Paraná, and Mato Grosso do Sul with secondary validation against MAPA cultivar registration databases, ANVISA residue monitoring protocols, and southern Brazilian cooperative financial disclosures. Bottom-up volume estimates from pasture renewal cycle data triangulated against top-down market sizing from certified seed distribution records.
Segmentation dimensions modeled include product type stratification across grasses, legumes, mixed varieties, and native species; end-user classification spanning dairy farmers, livestock producers, agronomists, and research institutions; application split between pasture establishment, crop rotation, erosion control, and soil restoration; and distribution channel differentiation across cooperatives, direct sales, nurseries, and online retail. CAGRs were derived from trend extrapolation of certified adoption rates and renewal cycle compression patterns, with nitrogen-fixing legume penetration and MAPA enforcement intensity as key forecast inputs across the projection horizon.
Decision-makers should treat outputs as directional under assumptions of continued MAPA certification mandate expansion and stable EMBRAPA cultivar trial throughput; material deviation in Seed Law revision outcomes or fertilizer cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Alfalfa Seed Market
Seeds
Global Seed Market
Seeds
Agricultural Seeder Market
Seeds
North America Forage Seed Market
Seeds
United States Forage Seed Market
Seeds
Indonesia Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Bangladesh Seed Market
Seeds
Watermelon Seeds Market
Seeds
North America Vegetable Seed Market
Seeds
Buckwheat Market
Seeds
India Vegetable Seed Market
Seeds
Guar Market
Seeds
Pumpkin Seeds Market
Seeds
South America Chia Seeds Market