
 Europe Precision Farming Market | 2026-2036
Europe Precision Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Precision Farming Market Foresight
Subscription-based software-defined agronomy is realigning how European farmers procure precision farming capabilities, shifting capital expenditure toward recurring operational models. Deere & Company leverages its integrated operations platform to anchor recurring revenue streams across major European markets. Trimble Inc. competes through specialized correction services and GNSS infrastructure. Hexagon Agriculture differentiates via autonomous steering and implement control systems.
Precision farming encompasses site-specific crop management using variable-rate technology, remote sensing, and automated guidance to optimize inputs and maximize yield per hectare. GPS Technology and IoT Solutions represent the structural core, with real-time kinematic positioning and sensor networks enabling sub-inch accuracy in field operations. Yield Monitoring and Soil Monitoring command the largest installed bases, while Data Analytics applications capture expanding margin pools as cooperatives seek predictive agronomic intelligence.
The EU Green Deal and F-Gas Regulation constrain equipment refrigerant profiles and mandate sustainability disclosures, directly shaping product design and procurement criteria. EMA and national agricultural ministries enforce machinery safety standards through CE marking requirements under the Machinery Directive. Stakeholders must monitor evolving carbon accounting rules and digital farm data sovereignty frameworks to anticipate compliance costs and platform interoperability demands.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing equipment refresh cycles across European arable operations, forcing cooperatives to retire legacy machinery ahead of depreciation schedules while recalibrating procurement criteria toward refrigerant-compliant platforms and carbon-accounting transparency.
Growth Catalysts
- Variable-rate application technology:German and French cooperatives deploy GPS-guided spreaders to reduce nitrogen runoff while meeting EFSA sustainability benchmarks. Sub-inch accuracy cuts input waste by double-digit percentages.
- CSRD disclosure mandates:Large farming operations face granular sustainability reporting requirements from 2024 onward. Digital farm management platforms automate data capture for Scope 3 emissions tracking.
- Netherlands cluster concentration:Wageningen University's ag-tech corridor accelerates field-to-market validation. Dutch arable giants pilot autonomous implement control before continental rollout.
Market Restraints
- RTK-GNSS infrastructure dependency:Correction service subscriptions from Trimble and Hexagon lock operators into recurring cost structures that erode margin at sub-500 hectare scale.
- Lithium-ion cell supply concentration:Battery packs for electric autonomous tractors rely on Asian cell manufacturers, exposing European OEMs to raw material volatility and export control friction.
- CE marking complexity under Machinery Directive:EMA and national ministries enforce divergent safety interpretations, stretching certification timelines for sensor-integrated implements.
Strategic Opportunities
- Poland and Romania underpenetration:Fragmented land ownership in Eastern Europe creates whitespace for equipment-as-a-service models. Local cooperatives lack capital for outright platform purchases.
- Carbon credit monetization:The EU Green Deal's carbon farming initiative rewards verifiable sequestration. Data analytics layers that audit soil carbon stocks capture new revenue pools.
- 5G private network deployment:Telecommunications infrastructure convergence with edge computing enables real-time machine-to-machine coordination in remote field environments.
Industry Challenges
- Agronomic data science talent scarcity:Cooperatives compete with fintech and logistics for Python-literate analysts who can operationalize satellite imagery into prescription maps.
- Interoperability fragmentation:Deere's proprietary data formats resist third-party platform integration, forcing mid-scale operators into single-vendor dependency or manual data translation.
- Retrofit kit engineering complexity:Legacy tractor fleets require CAN bus adapters and hydraulic interface redesigns to accept autonomous steering retrofits, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Precision Farming Market |
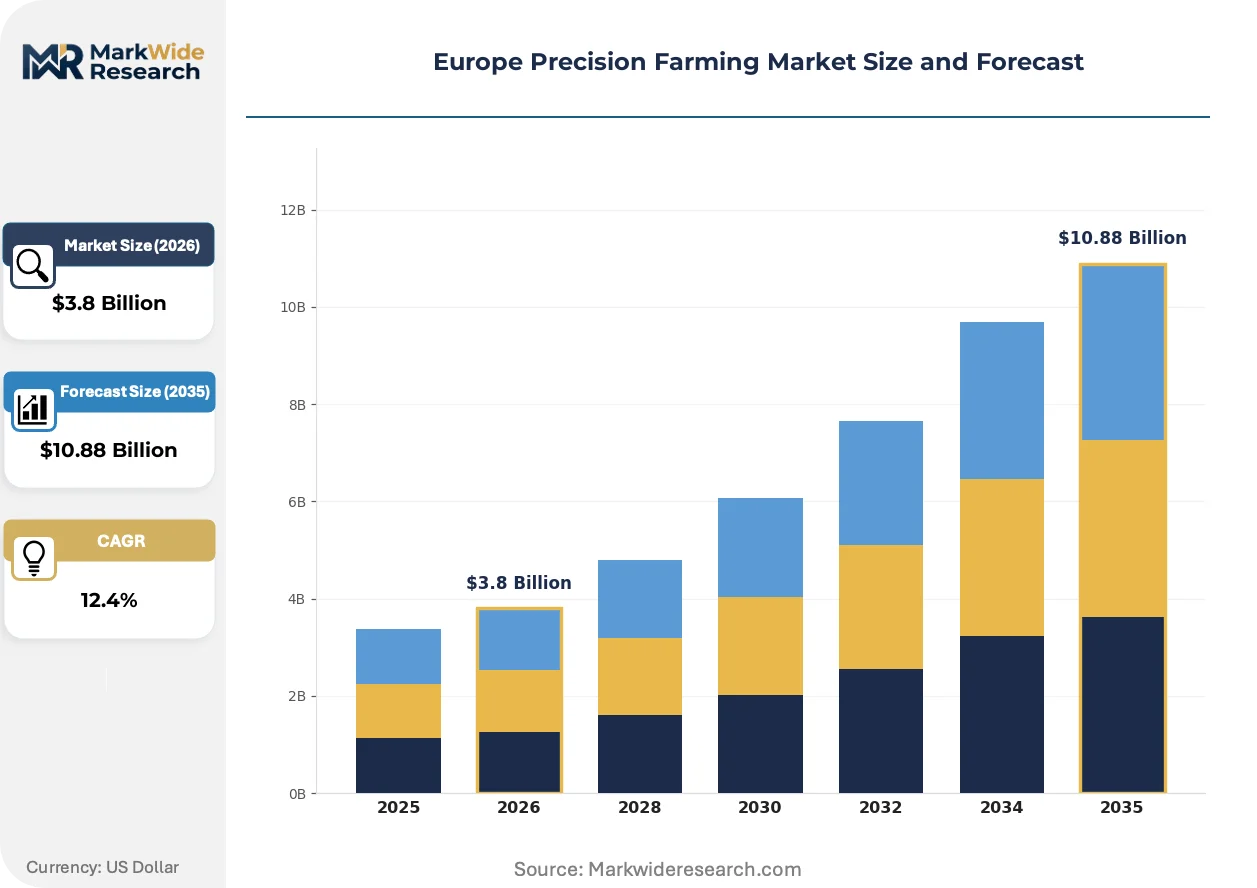
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yield Monitoring, Soil Monitoring, Weather Tracking, Crop Management Technology: GPS Technology, IoT Solutions, Drones, Automation Systems End User: Farmers, Agricultural Cooperatives, Agribusinesses, Research Institutions Application: Precision Irrigation, Crop Health Monitoring, Data Analytics, Resource Management |
| Companies Covered | CLAAS KGaA mbH, Topcon Positioning Systems, Deere & Company, Kverneland Group, Hexagon Agriculture, CNH Industrial N.V., Trimble Inc., Amazone Werke, AGCO Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Precision Farming Market Shifts & Advancements
Machine learning inference at the edge is displacing cloud-dependent agronomic models, compressing decision latency from hours to seconds while reducing connectivity costs for remote field operations. Three developments dominate the innovation landscape.
Real-time kinematic positioning is converging with computer vision-based weed recognition. Danish and Dutch arable operators deploy camera-guided spot sprayers that geolocate individual weed plants, cutting herbicide volumes by over 90 percent compared to broadcast application. The structural compression falls on agrochemical distributors whose volume-based margins erode as site-specific treatment displaces blanket coverage.
The F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants in tractor and harvester climate systems. Equipment manufacturers redesign thermal management around CO2 and hydrocarbon alternatives, adding engineering cost that concentrates procurement power with large cooperatives able to absorb premium pricing. German and French fleets face the steepest compliance cliffs given their larger installed base of high-horsepower machinery.
Cooperative buying consortia are consolidating equipment procurement across multi-farm memberships. The Netherlands' largest arable collectives negotiate fleet-wide software subscriptions and shared RTK base stations, displacing individual farm capital expenditure with pooled operational budgets. This behavior is most visible in Flevoland and Gelderland where land concentration enables scale-matched contract structures.
Europe Precision Farming Market Segmentation
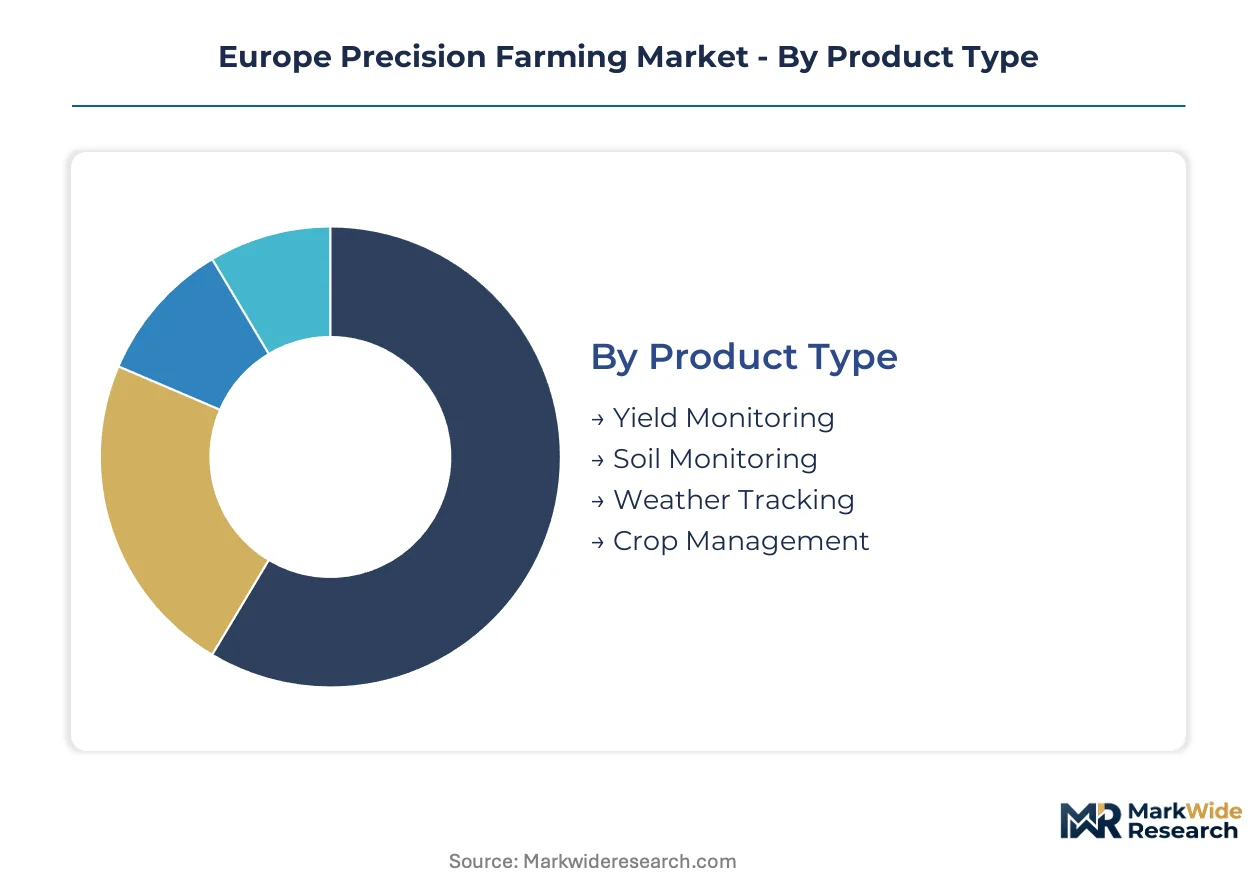
European precision farming procurement splits across equipment functionality, data infrastructure, and operational scale. Cooperatives prioritize segments that satisfy CSRD disclosure mandates and EFSA sustainability benchmarks while minimizing capital lock-up.
Product Type:
Farmers select precision farming products based on immediate yield impact versus long-term soil intelligence value.
- Yield Monitoring:Combines mass flow sensors, moisture detectors, and GPS tagging to generate hectare-level productivity maps. German and French cooperatives deploy these systems to satisfy EU Green Deal nitrogen efficiency reporting requirements. The installed base concentrates in large arable operations seeking granular input-output accountability.
- Soil Monitoring:Electrochemical and spectroscopic sensors measure pH, organic matter, and macronutrient profiles at variable depth intervals. Dutch operators in Flevoland integrate these probes with variable-rate spreaders to cut phosphate runoff into waterways. Carbon credit verification protocols are accelerating demand for soil carbon stock baselining.
- Weather Tracking:On-farm weather stations and hyperlocal forecast APIs enable spray timing optimization.
- Crop Management:Digital platforms consolidate scouting records, pest alerts, and prescription workflows.
Yield Monitoring leads on scale; Soil Monitoring leads on momentum.
Technology:
Technology selection hinges on accuracy requirements versus connectivity infrastructure availability across European farmland.
- GPS Technology:Real-time kinematic positioning delivers sub-inch accuracy for autosteering and boundary mapping. Trimble and Hexagon correction services dominate subscription revenue in Germany and France. The F-Gas Regulation's equipment refresh cycles are bundling upgraded GNSS receivers with new machinery purchases.
- IoT Solutions:LoRaWAN and cellular sensor networks transmit soil moisture, equipment telemetry, and environmental conditions to cloud platforms. Polish and Romanian cooperatives pilot these networks where RTK infrastructure remains sparse. Edge computing migration is reducing latency for time-critical irrigation decisions.
- Drones:Multispectral and RGB imaging platforms generate vegetation index maps for targeted intervention.
- Automation Systems:Autonomous implement control and robotic weeding reduce labor dependency in seasonal windows.
GPS Technology commands the largest installed base; IoT Solutions are climbing the fastest as connectivity costs fall.
End User:
Capital availability and reporting complexity determine end-user segment penetration across European agriculture.
- Farmers:Individual operators below 200 hectares favor retrofit kits and subscription software to avoid machinery replacement. French cereal producers in Beauce adopt yield monitors through dealer financing programs. CSRD thresholds exclude most sole operators from mandatory disclosure, slowing platform investment.
- Agricultural Cooperatives:Multi-farm entities pool procurement and share RTK base stations across membership hectares. Netherlands collectives in Gelderland negotiate fleet-wide software licenses displacing individual capital expenditure. These structures concentrate demand for data analytics layers that aggregate field-level intelligence.
- Agribusinesses:Vertically integrated operators deploy precision systems across owned and contracted acreage.
- Research Institutions:Wageningen University and INRAE facilities validate agronomic models before commercial transfer.
Agricultural Cooperatives concentrate procurement volume; Research Institutions concentrate innovation pipeline access.
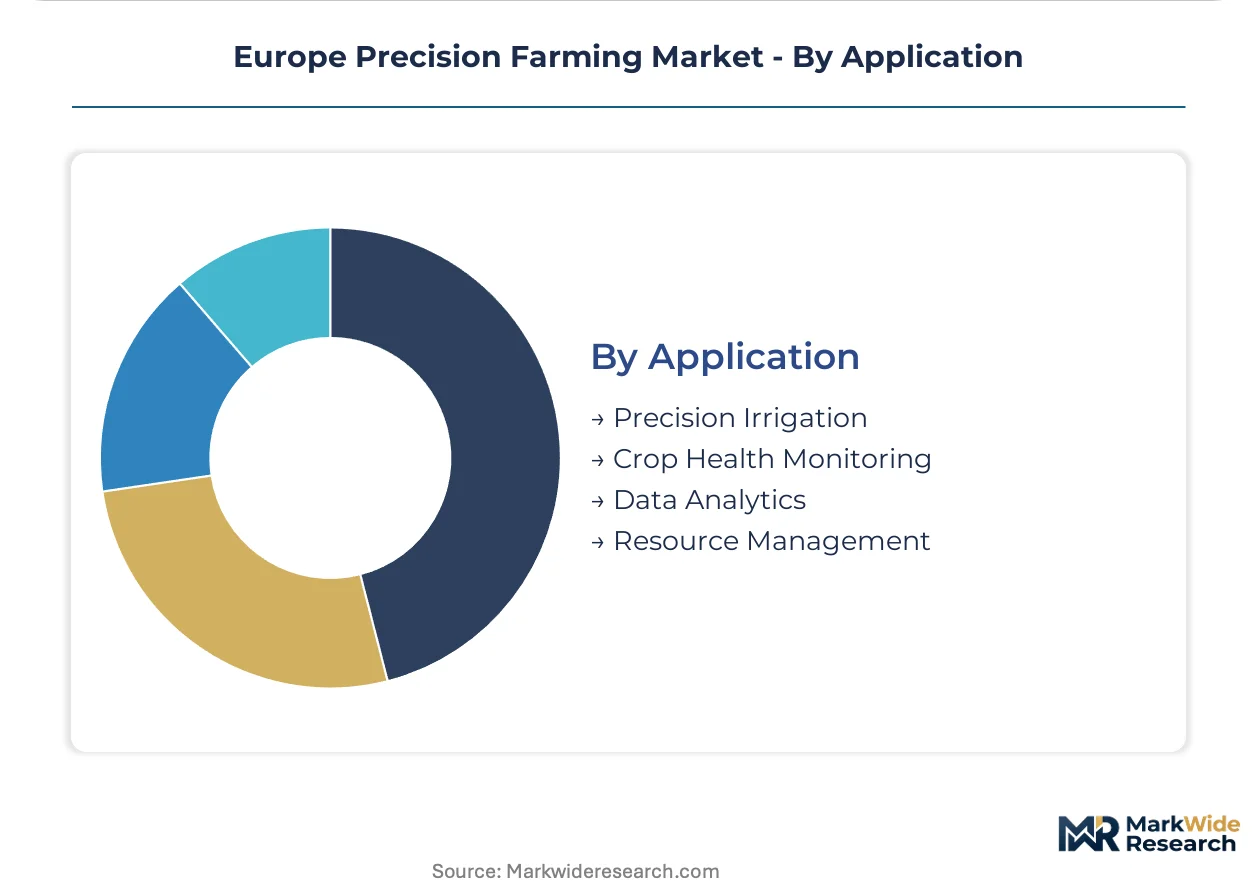
Application:
Application prioritization follows water stress geography and chemical input regulatory pressure.
- Precision Irrigation:Soil moisture sensing and variable-rate nozzle control cut water application by double-digit percentages. Spanish and Italian operators in water-stressed regions deploy these systems under national drought contingency plans. Subsurface drip integration with automation systems enables overnight scheduling without labor presence.
- Crop Health Monitoring:Satellite and drone imagery detect nutrient stress, disease pressure, and weed infestations before visual symptoms. Danish spot-spraying deployments cut herbicide volumes by over ninety percent compared to broadcast application. Computer vision inference at the edge is displacing cloud-dependent processing.
- Data Analytics:Prescription map generation and predictive yield modeling convert raw sensor feeds into actionable agronomy.
- Resource Management:Fleet tracking, fuel monitoring, and carbon accounting tools satisfy operational and regulatory reporting.
Precision Irrigation leads on water-stress geography penetration; Crop Health Monitoring leads on chemical reduction momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing equipment procurement timelines as German and French cooperatives accelerate machinery refresh cycles ahead of F-Gas Regulation deadlines, while Polish and Romanian operators delay capital deployment pending subsidy clarity.
Germany
Kverneland Group and CLAAS KGaA mbH anchor equipment supply to large arable collectives in Lower Saxony and Schleswig-Holstein. The F-Gas Regulation forces premature retirement of high-horsepower tractors with hydrofluorocarbon climate systems. Bavarian machinery rings pool RTK-GNSS subscriptions across membership hectares to dilute correction service costs.
France
Cereal cooperatives in Beauce and Picardy deploy variable-rate spreaders to satisfy EFSA nitrogen efficiency benchmarks. INRAE research stations validate prescription agronomy models before commercial transfer to farm management platforms. The CSRD disclosure mandate from 2024 onward drives adoption of automated data capture systems for Scope 3 emissions tracking.
Netherlands
Wageningen University's ag-tech corridor accelerates field-to-market validation for autonomous implement control. Flevoland and Gelderland collectives negotiate fleet-wide software licenses that displace individual capital expenditure with pooled operational budgets. Dutch phosphate runoff regulations intensify demand for soil monitoring probes integrated with variable-rate application.
Poland
Fragmented land ownership across Masovia and Greater Poland creates whitespace for equipment-as-a-service models. Local cooperatives lack balance sheet capacity for outright platform purchases. EU Common Agricultural Policy direct payments remain the primary financing mechanism for precision technology adoption.
Spain
Water-stressed arable operations in Castile-La Mancha and Andalusia prioritize precision irrigation systems under national drought contingency plans. Subsurface drip integration with automation enables overnight scheduling without labor presence. The country's national agricultural ministry channels recovery funds toward sensor network deployment in water-scarce provinces.
Europe Precision Farming Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding procurement volume in large cooperative accounts while regional fabricators capture retrofit kit demand. The vendor base concentrates around three strategic archetypes: full-stack platform providers bundling hardware and software subscriptions, component specialists selling GNSS correction services and sensor modules, and regional equipment manufacturers with localized dealer networks. Competitive moves center on fleet-wide software licensing negotiations and shared infrastructure pooling through cooperative buying consortia.
Within the integrated platform tier, Deere & Company and CNH Industrial N.V. anchor recurring revenue strategies through operations platforms that lock in large arable accounts. Trimble Inc. and Hexagon Agriculture occupy positions on the precision infrastructure vector, supplying correction services and autonomous steering systems that other OEMs embed. CLAAS KGaA mbH and AGCO Corporation represent the European machinery specialist archetype, competing through harvester-integrated yield monitoring and dealer-financed technology packages. These groupings illustrate how competitive positioning fragments across subscription software, precision hardware, and equipment manufacturing competencies.
| Leading Market Players |
|---|
| CLAAS KGaA mbH |
| Topcon Positioning Systems |
| Deere & Company |
| Kverneland Group |
| Hexagon Agriculture |
| CNH Industrial N.V. |
| Trimble Inc. |
| Amazone Werke |
| AGCO Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between CSRD-compliant data platforms and legacy yield monitors splits procurement budgets across European cooperatives, with premium-tier subscriptions commanding three-to-five-year contractual lock-in while commodity hardware faces margin compression from Asian component sourcing. This bifurcation concentrates supplier power with integrated OEMs bundling compliance-automated software, while standalone sensor vendors absorb logistics cost inflation on thin hardware margins.
Pricing Analysis
Distributor margin layers in precision farming equipment typically absorb 12-18 points between factory gate and cooperative procurement desks, with dealer financing programs extending payment terms to capture sub-500 hectare operators. Three-tier pricing structure across premium, standard, and economy levels tracks RTK correction accuracy tiers and carbon-accounting automation depth. Pricing pressure stems from lithium-ion cell volatility feeding into electric autonomous tractor premiums, eroding OEM margins on battery-electric platforms. Sub-200 hectare farmers exhibit acute price sensitivity, deferring platform upgrades until subsidy windows align, while Netherlands collectives in Flevoland prioritize total-cost-of-ownership metrics over upfront capital outlay.
Supply Chain Analysis
GNSS receiver chip supply rests on Taiwanese semiconductor foundries and Dutch lithography equipment, with correction service infrastructure anchored in German and French ground station networks. Raw material dependencies span lithium carbonate from Chilean brine operations, rare earth magnets for electric drivetrains concentrated in Chinese processing facilities, and high-purity silicon for sensor substrates. Single-source vulnerability in RTK-GNSS module supply exposes European OEMs to export control friction and foundry allocation constraints. Distribution runs through CLAAS and Kverneland dealer networks in Germany, cooperative buying consortia in the Netherlands, and EU Common Agricultural Policy subsidy channels in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European precision farming hinges on subscription revenue displacement of capital equipment sales, with software-defined agronomy platforms capturing recurring value pools as F-Gas Regulation compliance forces machinery refresh cycles.
For Market Incumbents: Cement platform stickiness through mandatory data format interoperability investments that preempt EU digital farm data sovereignty mandates. Deepen backward integration into edge computing hardware to reduce cloud dependency latency for time-critical spraying decisions. Prioritize fleet-wide software licensing negotiations with Netherlands and German cooperative consortia before carbon credit verification protocols standardize.
For New Entrants and Emerging Players: CSRD disclosure mandates in Germany and France open a window for specialized Scope 3 emissions auditing software targeting large arable collectives. Target Poland and Romania with equipment-as-a-service models circumventing fragmented land ownership capital constraints. Pursue white-label integration with established machinery rings rather than direct dealer network buildout.
For Investors and Strategic Acquirers: Consolidation pressure builds where agronomic data science talent scarcity constrains cooperative operationalization of satellite imagery. Position acquisition screening around edge-AI inference startups with field-validated weed recognition models. Watch for inflection where 5G private network deployment in remote arable regions enables real-time machine-to-machine coordination at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Credit Verification Platform | EU Green Deal soil carbon protocols create audit-ready revenue layer for data analytics providers. |
| RTK-GNSS Infrastructure Sharing | Cooperative base station pooling in Gelderland and Lower Saxony dilutes subscription costs across membership hectares. |
| Edge Computing Migration | On-field ML inference reduces latency from hours to seconds for autonomous spot-spraying decisions. |
| Equipment-as-a-Service Rollout | Polish and Romanian cooperatives bypass capital constraints through operational budgeting models. |
| F-Gas Compliant Thermal Redesign | CO2 refrigeration systems in high-horsepower tractors concentrate procurement power with large German and French fleets. |
Research Methodology
Multiple input streams — cooperative procurement managers, precision farming OEM product strategists, RTK-GNSS service engineers, and EU agricultural policy officers — were reconciled against machinery registration databases, CAP subsidy allocation records, and EMA safety certification filings. Secondary validation drew from customs trade data on GNSS receiver imports, SEC 10-K disclosures from listed equipment manufacturers, and INRAE agronomic trial publications. Bottom-up unit economics modeling and top-down market sizing triangulation anchored volume and value estimates.
Historical shipment trajectories were cross-referenced against expert panel assessments of F-Gas Regulation compliance timelines and CSRD adoption curves across the projection horizon. Segmentation dimensions modeled include product functionality tier, technology accuracy class, operational scale bracket, and application water-stress geography. CAGRs were derived from equipment replacement cycle compression and software subscription attach rate assumptions, with sensitivity testing around lithium-ion cost curves and 5G rural coverage expansion.
Revisions become necessary when EU digital farm data sovereignty frameworks materialize with interoperability mandates, carbon credit verification protocols shift measurement baselines, or export controls disrupt GNSS semiconductor supply. A small set of named triggers — subsidy program redesigns, correction service pricing resets, and autonomous weeding regulatory clearance — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Digital Agriculture Solutions Market