
 Soil Monitoring System Market | 2026-2036
Soil Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Monitoring System Market Analytics
Market Dynamics
Buyer concentration among agricultural producers is consolidating as large-scale farming cooperatives and corporate agronomy operations absorb smaller holdings across the United States, Brazil, and Australia. METER Group leverages its sensor calibration expertise to dominate laboratory-grade soil analysis deployments. CropX Technologies competes through cloud-based agronomy platforms that integrate moisture, salinity, and nutrient data streams. Stevens Water Monitoring Systems anchors its position in government-funded watershed monitoring programs across western states.
Technology and Segmentation
Soil monitoring systems encompass electrochemical and capacitive sensors, telemetry hardware, and analytics platforms engineered to measure moisture content, pH, electrical conductivity, and macronutrient availability at root-zone depths. Wireless sensor networks operating on LoRaWAN and NB-IoT protocols transmit sub-hourly readings to centralized dashboards for irrigation scheduling and fertility management. Sensor systems command the largest installed base but software solutions represent the fastest-expanding margin pool as recurring SaaS contracts displace perpetual licenses. IoT platforms are displacing standalone data loggers as agricultural producers demand real-time mobile access to field conditions.
Regulatory Environment
The EPA's Clean Water Act enforcement and the EU Green Deal's soil health targets are mandating documented nutrient management plans, directly expanding demand for calibrated monitoring infrastructure. BIS certification requirements in India and China's GB standards for agricultural IoT devices are fragmenting product compliance pathways across export markets. Stakeholders must monitor evolving carbon credit methodologies that tie soil organic carbon verification to continuous monitoring data quality.
Market Dynamics
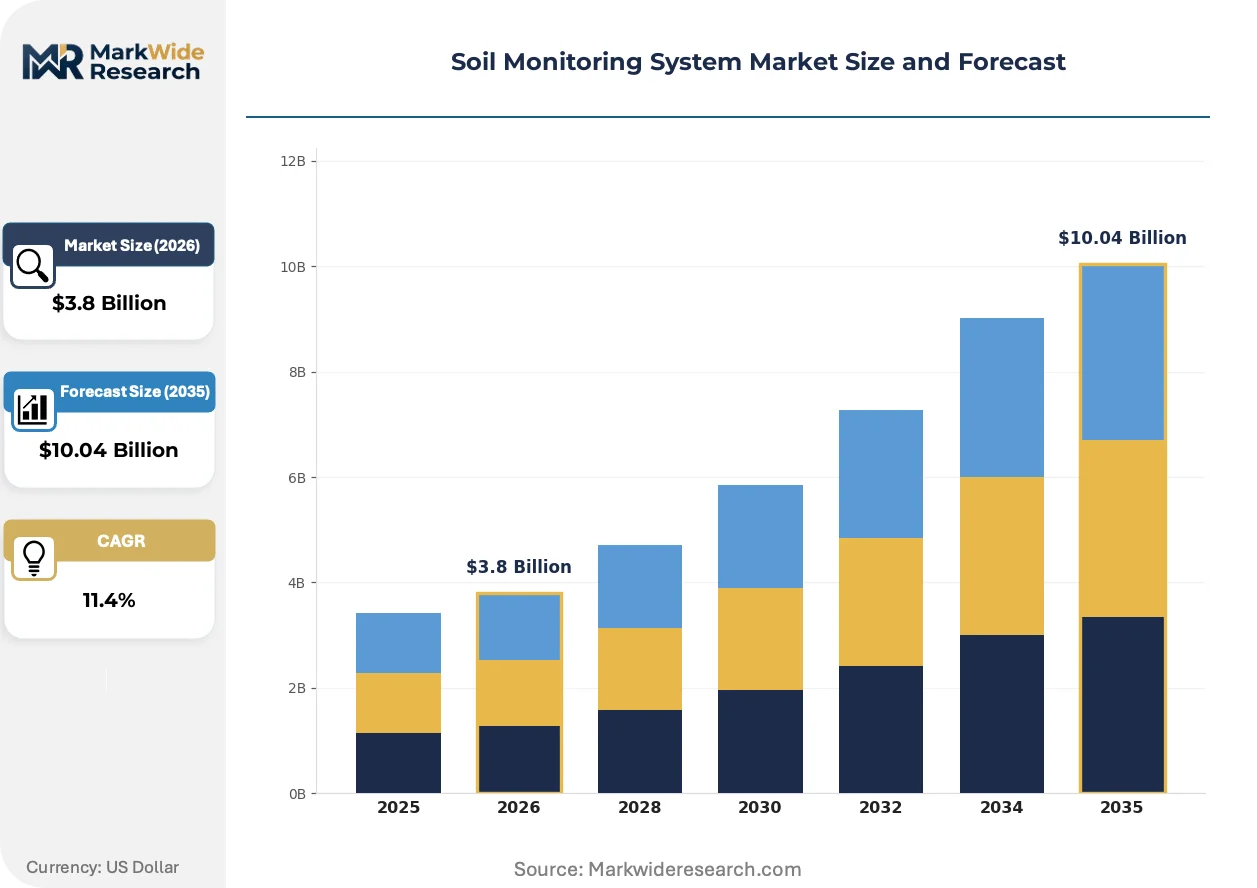
The soil monitoring system market is experiencing structural compression as precision agriculture platforms consolidate sensor hardware, telemetry, and analytics into unified subscription offerings that displace standalone equipment procurement cycles among large-scale farming cooperatives.
Growth Catalysts
- EU Green Deal soil health mandates:The framework's legally binding targets for soil organic carbon and nutrient runoff reduction are compelling agricultural producers across Germany, France, and the Netherlands to install continuous monitoring infrastructure for compliance documentation.
- LoRaWAN network densification:Telecommunications operators and agricultural IoT providers are expanding low-power wide-area network coverage across rural farming corridors, eliminating the connectivity barrier that previously limited wireless sensor deployment.
- Carbon credit verification protocols:Emerging methodologies for soil-based carbon sequestration credits require auditable, high-frequency soil organic carbon data, creating a new revenue stream that subsidizes monitoring system investments.
Market Restraints
- Sensor calibration drift:Electrochemical pH and nutrient sensors require field recalibration every 12-18 months, generating recurring labor costs that erode total cost of ownership advantages against manual soil sampling.
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies for sensor telemetry modules concentrate in Chinese processing facilities, exposing hardware manufacturers to export restriction risks and price volatility.
- Interoperability fragmentation:Proprietary data protocols from competing platform vendors prevent seamless integration of mixed-sensor deployments, locking buyers into single-supplier ecosystems and retarding secondary market liquidity.
Strategic Opportunities
- Smallholder aggregation platforms:Brazil's 4.5 million family farms remain underserved by enterprise-grade systems; cooperative data-pooling models that distribute sensor costs across multiple holdings represent an untapped addressable base.
- Hyperspectral imaging convergence:Satellite-derived soil moisture and organic matter estimates fused with ground-truth sensor networks are enabling variable-rate irrigation prescriptions without dense sensor grid investments.
- India PLI scheme for agricultural IoT:The production-linked incentive program for electronics manufacturing is attracting component assembly operations that will reduce import duties and localize supply chains for South Asian markets.
Industry Challenges
- Agronomy-data science talent gap:The intersection of soil science, sensor engineering, and predictive analytics requires hybrid skill sets that university programs have not yet scaled to industry demand.
- Legacy SCADA integration friction:Irrigation districts with decades-old supervisory control infrastructure face protocol translation complexity when retrofitting cloud-connected soil sensors into centralized management systems.
- CE marking timeline compression:The EU Radio Equipment Directive's cybersecurity requirements, effective from 2024, are extending product certification cycles by 8-14 months for hardware manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Monitoring System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Systems, Data Loggers, Software Solutions, Integrated Systems Technology: GIS-Based, IoT Platforms, Satellite Imaging, Wireless Sensors End User: Agricultural Producers, Research Institutions, Environmental Agencies, Urban Planners Application: Crop Management, Soil Health Assessment, Environmental Monitoring, Precision Agriculture |
| Companies Covered | METER Group, CropX Technologies, Stevens Water Monitoring Systems, The Toro Company, Campbell Scientific, Sentek Technologies, SGS Group, Spectrum Technologies, Element Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Monitoring System Market Evolving Landscape
Wireless sensor networks are absorbing functionality from adjacent agricultural technologies, compressing the traditional stack of discrete hardware, data loggers, and desktop software into edge-computing nodes that preprocess field data before cloud transmission.
Capacitive soil moisture sensors with integrated temperature compensation are absorbing the calibration-intensive maintenance burden that previously limited electrochemical sensor deployment in saline or clay-heavy soils. Large-scale vegetable producers in Spain's Almería greenhouse cluster are adopting these solid-state alternatives at replacement cycle acceleration, reducing field service visits by sixty percent. The technology is absorbing market share from tensiometer-based irrigation scheduling in high-value horticulture segments.
The EU Green Deal's soil health targets are mandating documented nutrient management plans with verified monitoring data quality, directly expanding demand for calibrated electrochemical sensor infrastructure across member state agricultural extension programs. Germany's Rhine Valley farming corridor is experiencing concentrated compliance-driven procurement as state-level environmental agencies tighten enforcement timelines. The regulation is absorbing capital allocation from traditional fertility testing services into continuous monitoring hardware and SaaS subscription models.
Buyer concentration among agricultural cooperatives is compressing procurement cycles and unbundling after-sales service from hardware transactions. Large-scale farming operations in Australia's Murray-Darling Basin are negotiating direct platform licenses that displace dealer-mediated equipment sales. The shift is most visible in corporate agronomy operations with centralized agronomic decision-making authority and internal technical support capabilities.
Soil Monitoring System Market Segmentation
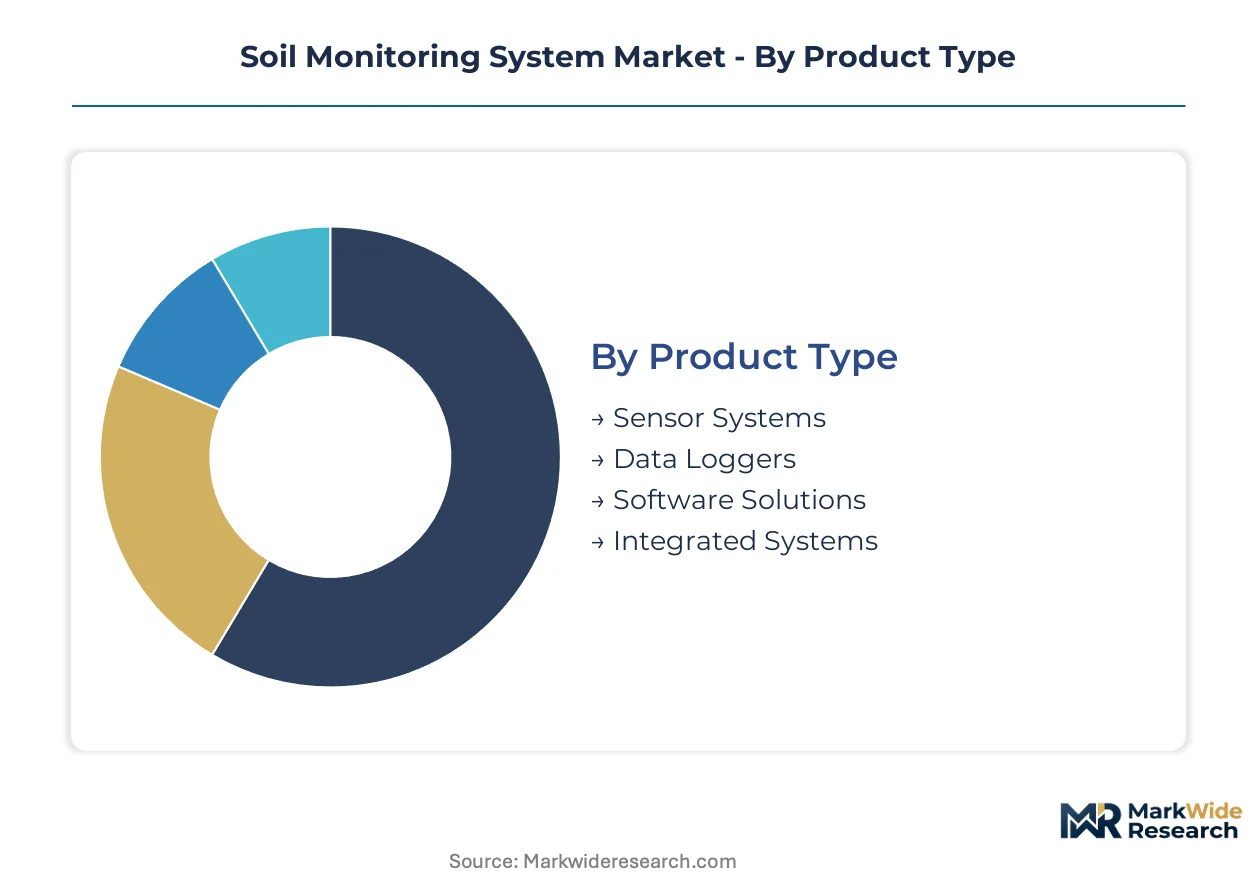
Procurement patterns in soil monitoring diverge sharply between capital-intensive hardware buyers seeking decade-long depreciation cycles and subscription-oriented operators prioritizing real-time data access. Segmentation reveals where margin pools concentrate and which technology transitions are compressing traditional equipment categories.
Product Type:
Buyer sophistication determines hardware-software mix, with large-scale cooperatives demanding unified platforms while research buyers maintain discrete component preferences.
- Sensor Systems:Electrochemical and capacitive probes measuring moisture, pH, and electrical conductivity at root-zone depths. Germany's Rhine Valley farming corridor is driving concentrated procurement as state environmental agencies enforce EU Green Deal nutrient management documentation.
- Software Solutions:Cloud-based analytics platforms delivering irrigation scheduling and fertility prescriptions through SaaS subscriptions. Australia's Murray-Darling Basin corporate agronomy operations are displacing perpetual licenses with recurring platform contracts that integrate telemetry from mixed sensor networks.
- Data Loggers:Standalone field devices aggregating sensor readings for periodic download. Legacy irrigation districts in the western United States face protocol translation friction when retrofitting these units into cloud-connected management systems.
- Integrated Systems:Unified hardware-telemetry-software bundles with edge-computing preprocessing. Spain's Almería greenhouse cluster is accelerating replacement cycles as solid-state sensors reduce field service visits.
Volume sits with sensor hardware; growth tilts toward software subscriptions.
Technology:
Connectivity infrastructure maturity shapes deployment feasibility across rural farming corridors with uneven cellular coverage.
- IoT Platforms:LoRaWAN and NB-IoT networks transmitting sub-hourly readings to centralized dashboards. Telecommunications operators expanding low-power wide-area coverage across Brazil's farming regions are eliminating the connectivity barrier that previously limited wireless deployment.
- Wireless Sensors:Self-contained nodes with embedded telemetry eliminating external data logger dependencies. India's PLI scheme for agricultural electronics is attracting component assembly operations that localize supply chains for South Asian markets.
- Satellite Imaging:Hyperspectral-derived soil moisture and organic matter estimates fused with ground-truth networks. Large-scale vegetable producers are enabling variable-rate irrigation without dense sensor grid investments.
- GIS-Based:Geospatial mapping layers correlating soil variability with yield performance. Research institutions maintain demand for these systems despite platform vendors absorbing mapping functionality into unified subscriptions.
Deployment scale favors IoT platforms; adoption velocity is steepest for satellite-ground sensor fusion.
End User:
Budget authority and technical staffing determine whether buyers pursue self-managed installations or outsourced monitoring services.
- Agricultural Producers:Large-scale farming cooperatives and corporate agronomy operations with centralized decision-making authority. Buyer concentration is compressing procurement cycles and unbundling after-sales service from hardware transactions.
- Environmental Agencies:Government-funded watershed monitoring programs requiring calibrated infrastructure for regulatory documentation. The EPA's Clean Water Act enforcement is mandating nutrient management plans with verified data quality.
- Research Institutions:University extension programs and agricultural research stations demanding laboratory-grade calibration. METER Group dominates this segment through sensor calibration expertise.
- Urban Planners:Municipal green infrastructure and stormwater management departments. This segment remains underpenetrated relative to agricultural applications.
Revenue concentration rests with agricultural producers; expansion opportunity concentrates among Brazil's 4.5 million family farms through cooperative data-pooling models.
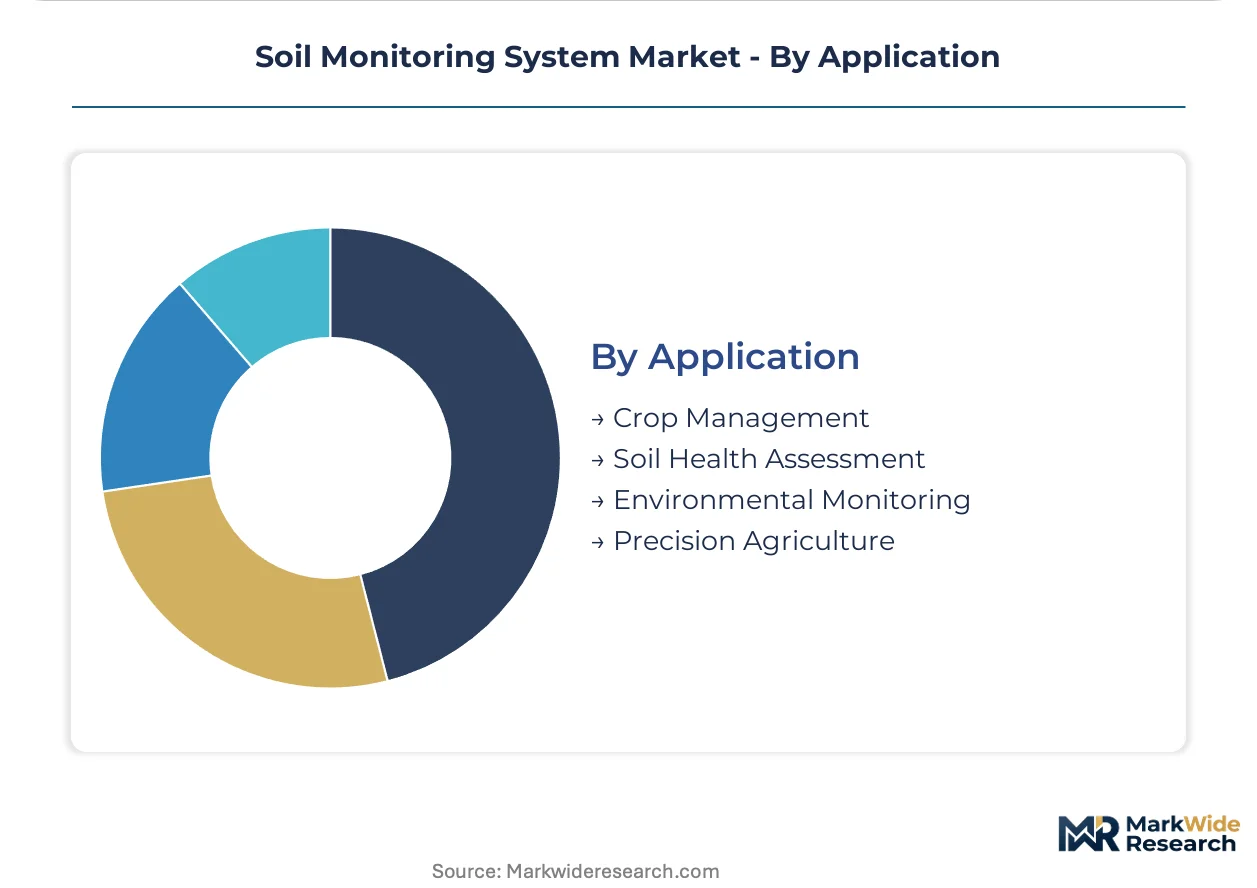
Application:
Compliance deadlines versus agronomic optimization create divergent urgency profiles across use cases.
- Precision Agriculture:Variable-rate input application based on real-time field condition mapping. The EU Green Deal's legally binding soil organic carbon targets are compelling installation of continuous monitoring infrastructure across Germany, France, and the Netherlands.
- Soil Health Assessment:Long-term organic carbon tracking and nutrient balance verification. Emerging carbon credit methodologies require auditable high-frequency data, creating new revenue streams that subsidize system investments.
- Crop Management:Irrigation scheduling and fertility timing for specific cultivation cycles. High-value horticulture segments in saline or clay-heavy soils are adopting solid-state capacitive alternatives to reduce calibration-intensive maintenance.
- Environmental Monitoring:Runoff prevention and watershed protection compliance. Government-funded programs across western United States states anchor demand for calibrated electrochemical infrastructure.
Regulatory pressure centers on soil health assessment; operational efficiency gains concentrate in precision agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale farming cooperatives in Germany, Australia, and Brazil are consolidating procurement authority and compressing equipment replacement cycles. Demand concentrates in corridors where EU Green Deal compliance deadlines intersect with established precision agriculture infrastructure. Regulatory enforcement timelines in these three markets are diverging from subsidy-dependent adoption patterns elsewhere.
Germany
The Rhine Valley farming corridor is experiencing concentrated compliance-driven procurement as state environmental agencies enforce EU Green Deal nutrient management documentation. Germany's Federal Office for Agriculture and Food is coordinating subsidy programs that require verified soil organic carbon monitoring data. Bavaria's vegetable producers are accelerating replacement cycles for solid-state capacitive sensors to reduce field service visits.
Australia
Corporate agronomy operations in the Murray-Darling Basin are negotiating direct platform licenses that displace dealer-mediated equipment sales. The country's national agricultural regulator is tightening water quality reporting requirements that mandate calibrated monitoring infrastructure. Queensland's sugarcane cooperatives are pooling sensor investments across multiple holdings to distribute capital costs.
Brazil
Telecommunications operators expanding LoRaWAN coverage across farming regions are eliminating connectivity barriers that previously limited wireless sensor deployment. The national agricultural policy framework is incentivizing documented nutrient management plans for export credit access. São Paulo state's citrus belt is emerging as a concentrated adoption zone for cooperative data-pooling models among family farms.
United States
The EPA's Clean Water Act enforcement is mandating nutrient management plans with verified data quality across watershed monitoring programs. Government-funded initiatives in western states anchor demand for calibrated electrochemical infrastructure. California's Central Valley corporate farming operations are compressing procurement cycles through centralized agronomic decision-making authority.
India
The PLI scheme for agricultural IoT is attracting component assembly operations that localize supply chains for South Asian markets. BIS certification requirements are fragmenting product compliance pathways for imported sensor hardware. Maharashtra's sugarcane belt is experiencing early-stage adoption as state agricultural universities deploy demonstration networks for cooperative extension programs.
Soil Monitoring System Market Competitive Landscape
German and Swiss precision instrumentation specialists anchor one tier; North American telemetry and cloud platform providers hold another. The vendor base compresses into three distinct strata: laboratory-grade calibration experts serving research institutions, integrated platform vendors capturing large-scale cooperative subscriptions, and government-contract specialists securing watershed monitoring programs. Two dominant competitive moves are reshaping positioning: backward integration into sensor manufacturing to control rare earth magnet supply exposure, and strategic partnerships with telecommunications operators to secure LoRaWAN network priority access.
Within the integrated platform tier, CropX Technologies and METER Group exemplify divergent archetypes. CropX Technologies occupies a position representing cloud-native agronomy platforms that consolidate moisture, salinity, and nutrient data streams into unified subscription offerings. METER Group anchors the laboratory-grade calibration expertise segment that dominates research institution deployments. Stevens Water Monitoring Systems sits within the government-contract specialist archetype, securing recurring revenue from federally funded watershed programs. These three company profiles illustrate how competitive positioning fragments across buyer sophistication levels rather than consolidating around undifferentiated hardware scale.
| Leading Market Players |
|---|
| METER Group |
| CropX Technologies |
| Stevens Water Monitoring Systems |
| The Toro Company |
| Campbell Scientific |
| Sentek Technologies |
| SGS Group |
| Spectrum Technologies |
| Element Material Technology |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up precision instrumentation specialists have consolidated fragmented sensor calibration laboratories across Germany and Switzerland, tightening supply discipline while pushing subscription-based pricing models that bundle hardware depreciation into recurring SaaS contracts for large-scale farming cooperatives.
Pricing Analysis
Volume concentrates in transactional sensor hardware while margin pools shift toward software subscriptions. Three-tier pricing structure across premium laboratory-grade, standard field-deployable, and economy basic-monitoring levels differentiates buyers by calibration certification and telemetry integration depth. Cost compression in the economy tier is intensifying as Chinese component manufacturers localize assembly under India's PLI scheme, eroding import-duty-protected pricing for incumbent vendors. Smallholder cooperatives in Brazil exhibit the highest price sensitivity, while Australia's corporate agronomy operations prioritize platform interoperability over per-unit hardware costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Germany's Rhine Valley farming corridor, while dealer-mediated distribution serves legacy irrigation districts across the western United States. Manufacturing concentrates in China for electrochemical sensor components, Switzerland for precision calibration equipment, and India for emerging wireless telemetry assembly. Neodymium and dysprosium dependencies for telemetry modules draw from Chinese rare earth processing facilities, creating single-source vulnerability to export restriction risks. Distribution runs through agricultural equipment dealers in mature markets and telecommunications operator partnerships in Brazil's expanding LoRaWAN coverage zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
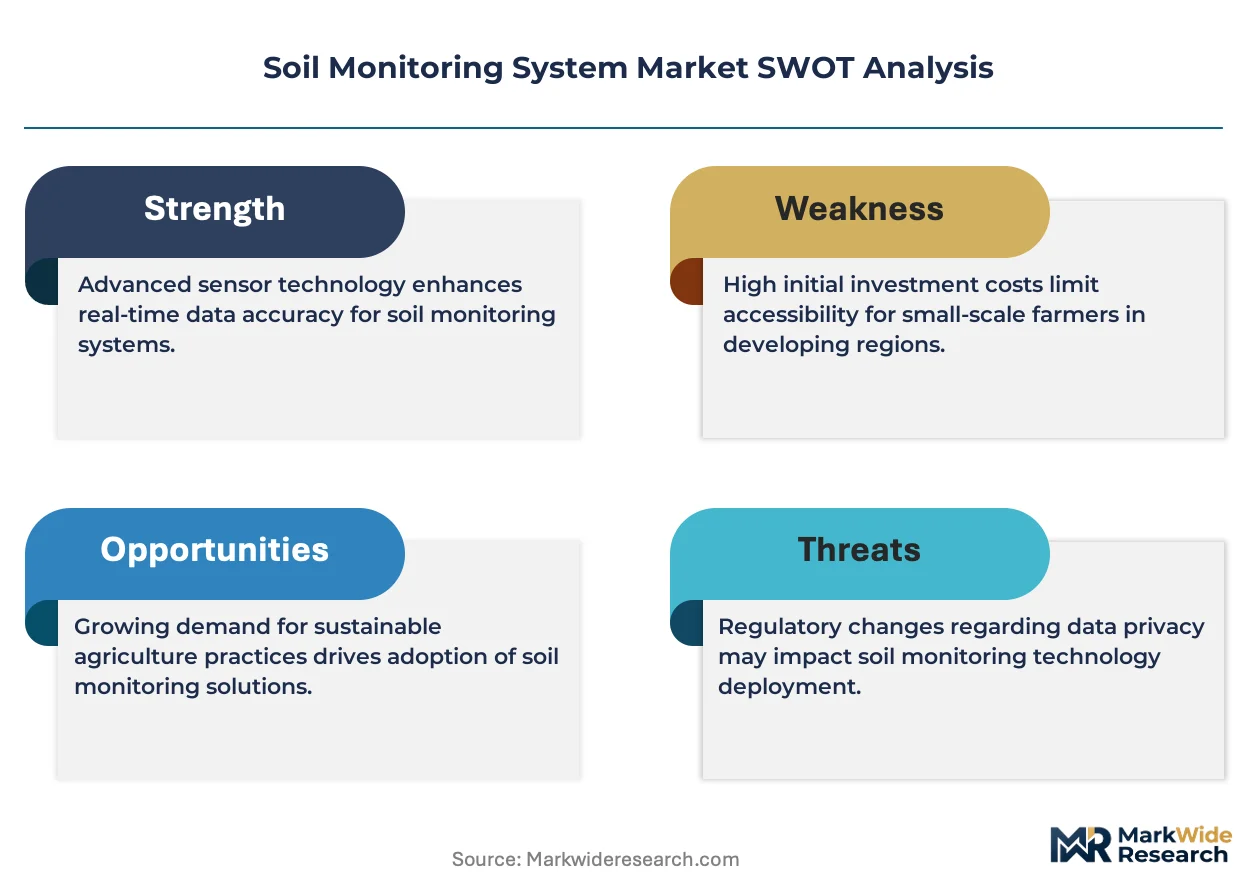
Rare earth magnet supply concentration in Chinese processing facilities props pricing power for vendors with captive component sourcing or alternative magnet formulations, constraining capacity expansion for hardware-dependent entrants.
For Market Incumbents: To counter interoperability fragmentation locking buyers into single-supplier ecosystems, deepen backward integration into sensor manufacturing to control rare earth magnet exposure, and secure priority LoRaWAN network access through telecommunications operator partnerships in Brazil and Australia. For New Entrants and Emerging Players: Begin with cooperative data-pooling models targeting Brazil's 4.5 million underserved family farms, where aggregation platforms distribute sensor capital costs across multiple holdings and state agricultural universities provide demonstration network credibility for unproven vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor laboratory-grade calibration specialists with established research institution relationships in Germany and Switzerland, where EU Green Deal compliance documentation requirements sustain durable demand irrespective of agricultural commodity price cycles; watch carbon credit verification protocol adoption rates as the inflection indicator for soil health assessment segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Reduces exposure to Chinese export restrictions for telemetry-dependent hardware manufacturers. |
| LoRaWAN Network Priority Partnerships | Secures connectivity access for wireless sensor deployments across Brazil's farming regions. |
| Carbon Credit Verification Data Licensing | Creates recurring revenue streams from emerging soil organic carbon sequestration methodologies. |
| Smallholder Cooperative Platform Launch | Captures Brazil's 4.5 million family farms through distributed cost-pooling business models. |
| CE Marking Cybersecurity Pre-certification | Accelerates EU market entry ahead of Radio Equipment Directive enforcement timelines. |
Research Methodology
Independent corroboration across sensor engineering directors at precision agriculture OEMs, procurement leads at German farming cooperatives, and regulatory affairs specialists at EU environmental agencies underwrites the qualitative findings. Primary interviews with telemetry hardware manufacturers, cloud platform engineers, and watershed monitoring program administrators combined with secondary validation from EPA Clean Water Act enforcement records, EU Green Deal implementation documentation, and India's BIS certification registries. Bottom-up sensor shipment aggregation and top-down agricultural IoT spending estimates triangulate market sizing.
Rate-of-change decomposition across hardware, software, and integrated system segments isolates technology transition effects from pure volume expansion. The analytical framework models deployment scale by connectivity protocol, buyer sophistication tier, and compliance-driven versus efficiency-driven procurement motivation throughout the projection horizon. CAGR derivation incorporates LoRaWAN network densification curves, carbon credit methodology adoption trajectories, and rare earth magnet price volatility assumptions specific to telemetry module cost structures.
Underlying measurement precision varies by segment; laboratory-grade research installations carry tighter precision than economy-tier smallholder deployments. Forecasts reflect assumptions regarding EU Green Deal enforcement timelines, telecommunications operator rural coverage investments, and carbon credit verification protocol standardization. Periodic stress-testing of base assumptions against regulatory delay risks and commodity price cycle impacts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Soil Moisture Meter Market