
 Connected Agriculture Software Market | 2026-2036
Connected Agriculture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Agriculture Software Market Insights
North American cloud infrastructure expansion is fragmenting the competitive landscape for farm management platforms. Cropin Technology Solutions leverages its AI-driven crop intelligence stack to anchor presence across emerging markets. Bosch Connected Agriculture sustains hardware-software integration advantages through its sensor-to-cloud pipeline for equipment telemetry. AGRIVI differentiates via white-label deployments serving agricultural cooperatives across Central and Eastern Europe.
Connected agriculture software denotes platforms that integrate IoT sensor feeds, satellite imagery, and predictive algorithms to automate decision support for planting, irrigation, fertilization, and harvest logistics. These systems typically process field-level data at sub-meter resolution through edge gateways before cloud-based analytics generate prescriptive recommendations. Farm Management Software captures the dominant margin pool as growers consolidate disparate tools into unified operating systems. Crop Monitoring Tools represent the fastest-expanding category, driven by satellite imagery price declines and API accessibility for yield prediction models. Supply Chain Software remains comparatively mature, with incumbent ERP vendors controlling traceability modules for commodity exporters.
The EPA regulates agricultural runoff reporting that drives adoption of nutrient management modules within farm software suites. USDA conservation programs incentivize precision agriculture investments, while the EU Green Deal mandates farm-level sustainability metrics that cloud platforms must certify. Stakeholders should monitor evolving data portability requirements between competing platforms as growers resist vendor lock-in across multi-season contracts.
Market Dynamics
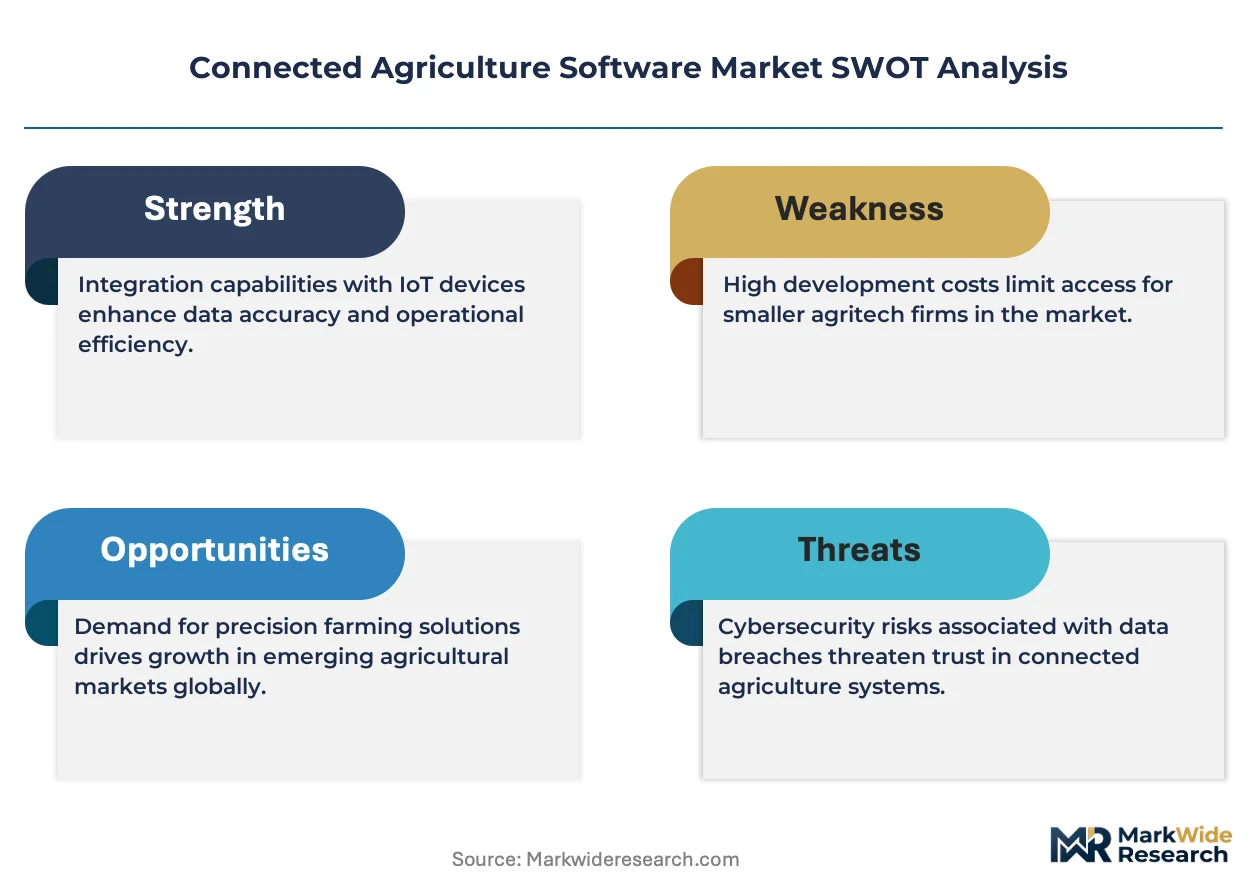
Large-scale commercial farming operations are consolidating software procurement around unified farm management platforms that subsume point solutions for irrigation, fertilization, and harvest logistics into single operating systems.
Growth Catalysts
- EU Green Deal:Mandatory farm-level sustainability metrics under the Farm to Fork Strategy are forcing agricultural producers to adopt cloud-based certification modules for nutrient runoff and carbon footprint tracking.
- Edge computing:Field-level data processing at sub-meter resolution through IoT gateways is enabling real-time prescription generation without latency penalties from cloud-only architectures.
- Row-crop concentration:United States precision agriculture adoption among corn and soybean producers is driving subscription volume for satellite imagery and yield prediction APIs.
Market Restraints
- Data portability friction:Growers resist multi-season vendor lock-in where competing platforms lack interoperable field history formats, extending sales cycles.
- Satellite imagery cost volatility:Launch schedule delays and constellation failures create input price uncertainty for crop monitoring tool providers.
- Rural connectivity gaps:Broadband infrastructure deficits in agricultural regions of Brazil and India limit edge gateway deployment density.
Strategic Opportunities
- USDA conservation incentives:Cost-share programs for precision agriculture equipment are reducing customer acquisition friction for software vendors targeting mid-size operations.
- Cooperative white-labeling:Agricultural cooperatives across Central and Eastern Europe seek branded farm management portals, creating channel partnerships without direct enterprise sales.
- API convergence:Standardized yield prediction models are enabling third-party developers to build specialized modules atop core farm management platforms.
Industry Challenges
- Agronomic data science talent:Shortage of professionals combining crop science expertise with machine learning implementation is constraining model refinement velocity.
- Legacy equipment integration:Proprietary telemetry protocols from incumbent machinery manufacturers complicate sensor-to-cloud pipeline standardization.
- EPA reporting compliance:Evolving agricultural runoff documentation requirements demand continuous software updates to nutrient management modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Agriculture Software Market |
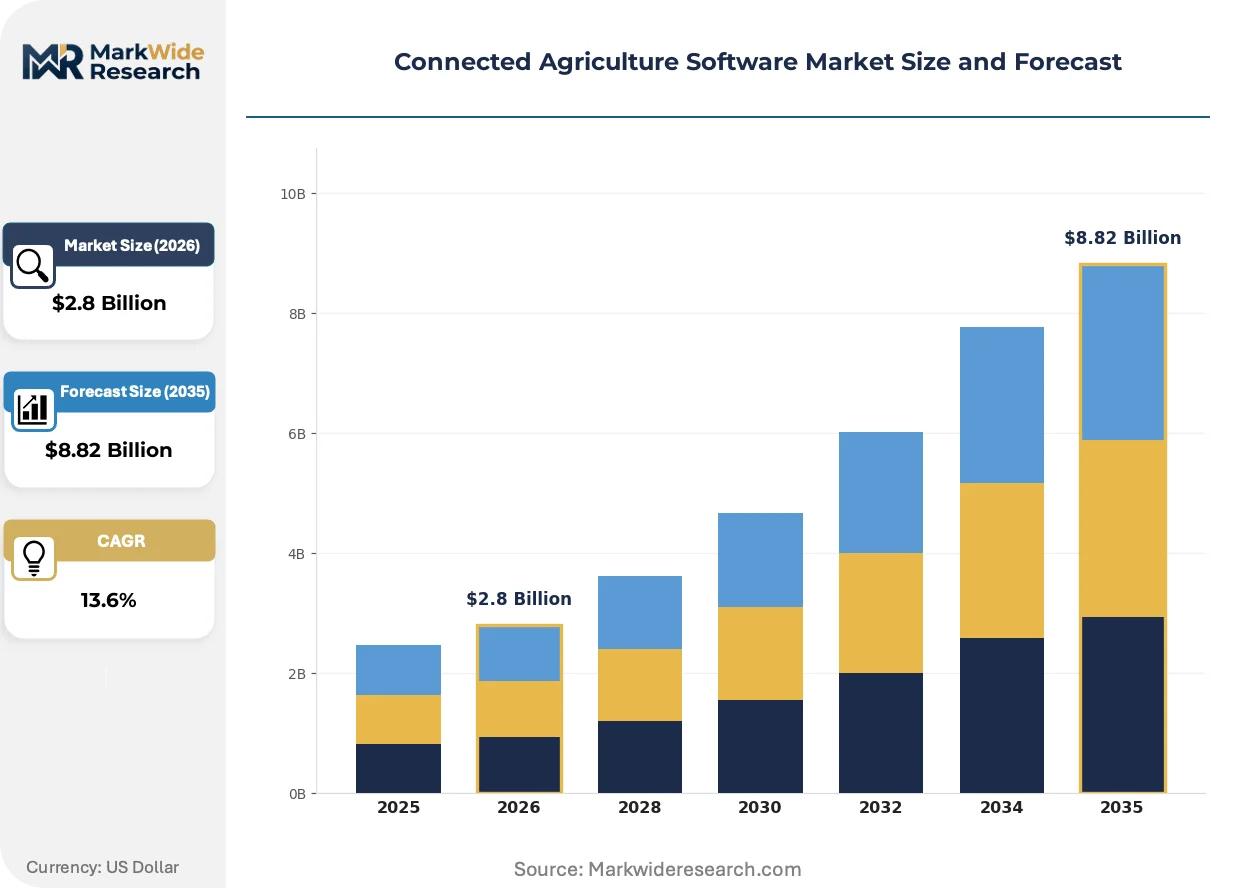
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farm Management Software, Crop Monitoring Tools, Livestock Management Solutions, Supply Chain Software Application: Precision Agriculture, Crop Management, Soil Health Monitoring, Farm Analytics Technology: IOT Solutions, Cloud Computing, Big Data Analytics, Mobile Applications End User: Farmers, Agricultural Cooperatives, AgTech Companies, Enterprises |
| Companies Covered | Plantix, Instacrops, Cropin Technology Solutions, Bluewhite, FarmERP, AGRIVI, Agrosmart, Bosch Connected Agriculture, OneSoil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Agriculture Software Market Trends and Innovations
Cloud infrastructure expansion across North American agricultural regions is fragmenting competitive positioning as hyperscale providers enable new entrants to bypass capital-intensive data center builds.
Edge-native AI inference engines deployed directly on irrigation controllers and drone flight computers are rendering obsolete centralized cloud-only analytics architectures that suffer from field connectivity interruptions. Mid-size vegetable producers in California's Central Valley are piloting these systems for sub-hour irrigation adjustments. The shift compresses hardware margins while elevating software licensing value.
CSRD disclosure mandates in Europe are compelling agricultural software vendors to embed emissions calculation engines that automatically generate Scope 3 reporting for downstream food processors. German dairy cooperatives now require these modules in procurement specifications. Vendors without certified carbon accounting functionality are losing RFP eligibility.
Subscription unbundling is accelerating as growers reject comprehensive platform fees in favor of à-la-carte API access for specific functions like satellite-derived nitrogen recommendations. This pattern concentrates among cotton producers in Texas and Australia who maintain in-house data science teams. Channel partners are responding with usage-based billing infrastructure.
Connected Agriculture Software Market Segmentation
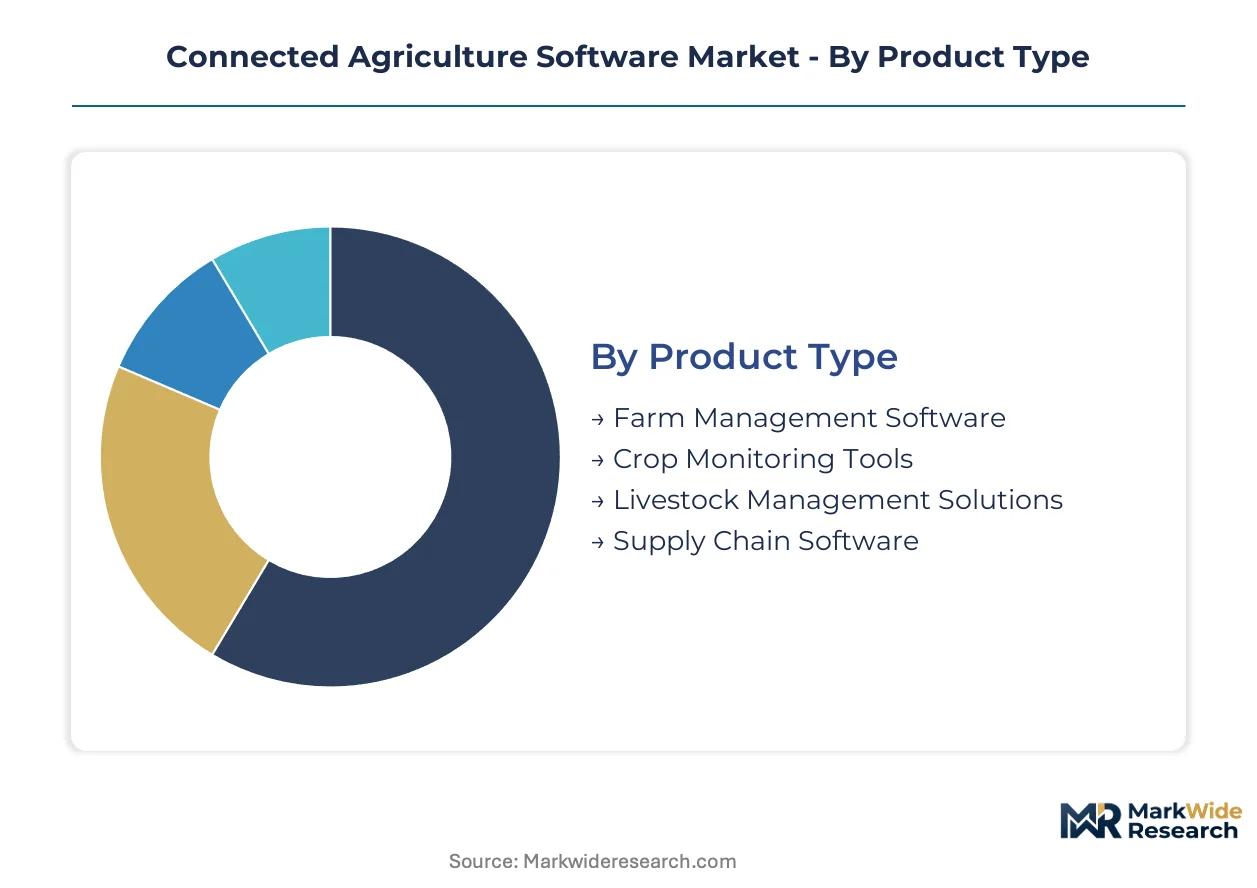
Software segmentation in connected agriculture reflects divergent data processing requirements across farm scales and crop types. Procurement patterns vary sharply between commodity row-crop operations seeking yield optimization and specialty producers prioritizing traceability compliance.
Product Type:
Mature platforms with established deployment footprints dominate procurement budgets, while emerging categories capture vendor R&D concentration.
- Farm Management Software:Unified operating systems consolidate irrigation, fertilization, and harvest logistics modules into single dashboards. Large-scale corn and soybean operations in the United States are standardizing procurement around these platforms to reduce point-solution fragmentation.
- Crop Monitoring Tools:Satellite imagery integration with sub-meter resolution field mapping enables prescription generation for variable-rate application. API accessibility and imagery price declines are accelerating adoption among mid-size vegetable producers in California's Central Valley.
- Livestock Management Solutions:Sensor-based herd health monitoring and automated feeding systems for dairy and cattle operations.
- Supply Chain Software:ERP-integrated traceability modules for commodity exporters managing sustainability documentation.
Farm Management Software handles the majority of throughput; Crop Monitoring Tools is the fastest mover on share.
Application:
Cost tier differentiation separates enterprise-grade integrated suites from modular point solutions serving budget-constrained operators.
- Precision Agriculture:Variable-rate technology execution through automated equipment control systems. Row-crop farmers in the United States drive subscription volume for prescription services tied to planting and nutrient application.
- Crop Management:Field-level activity tracking from planting through harvest with integrated weather and pest alerts.
- Soil Health Monitoring:Sensor networks and laboratory integration for nutrient mapping and carbon sequestration verification. EU Green Deal compliance requirements are mandating adoption among German and French cereal producers.
- Farm Analytics:Yield prediction models and financial performance benchmarking tools.
Precision Agriculture commands the largest implementation spend; Soil Health Monitoring is climbing the fastest on regulatory compulsion.
Technology:
Volume concentration follows infrastructure deployment density, with cloud architectures scaling faster than edge-native alternatives in connectivity-served regions.
- IOT Solutions:Edge gateways and field sensor networks processing telemetry at sub-meter resolution. Equipment manufacturers are embedding these modules directly into tractors and irrigation controllers to bypass standalone hardware procurement.
- Cloud Computing:Centralized data lakes and API infrastructure enabling multi-farm consolidation. North American hyperscale expansion is fragmenting vendor competitive positioning by reducing capital barriers to entry.
- Big Data Analytics:Machine learning pipelines for yield prediction and prescription generation.
- Mobile Applications:Field-accessible interfaces for real-time decision support and equipment control.
Cloud Computing supports the broadest user base; IOT Solutions is expanding most quickly on edge-AI deployment.
End User:
Customer type determines contract structure, with cooperatives seeking white-label deployments and enterprises demanding custom integration.
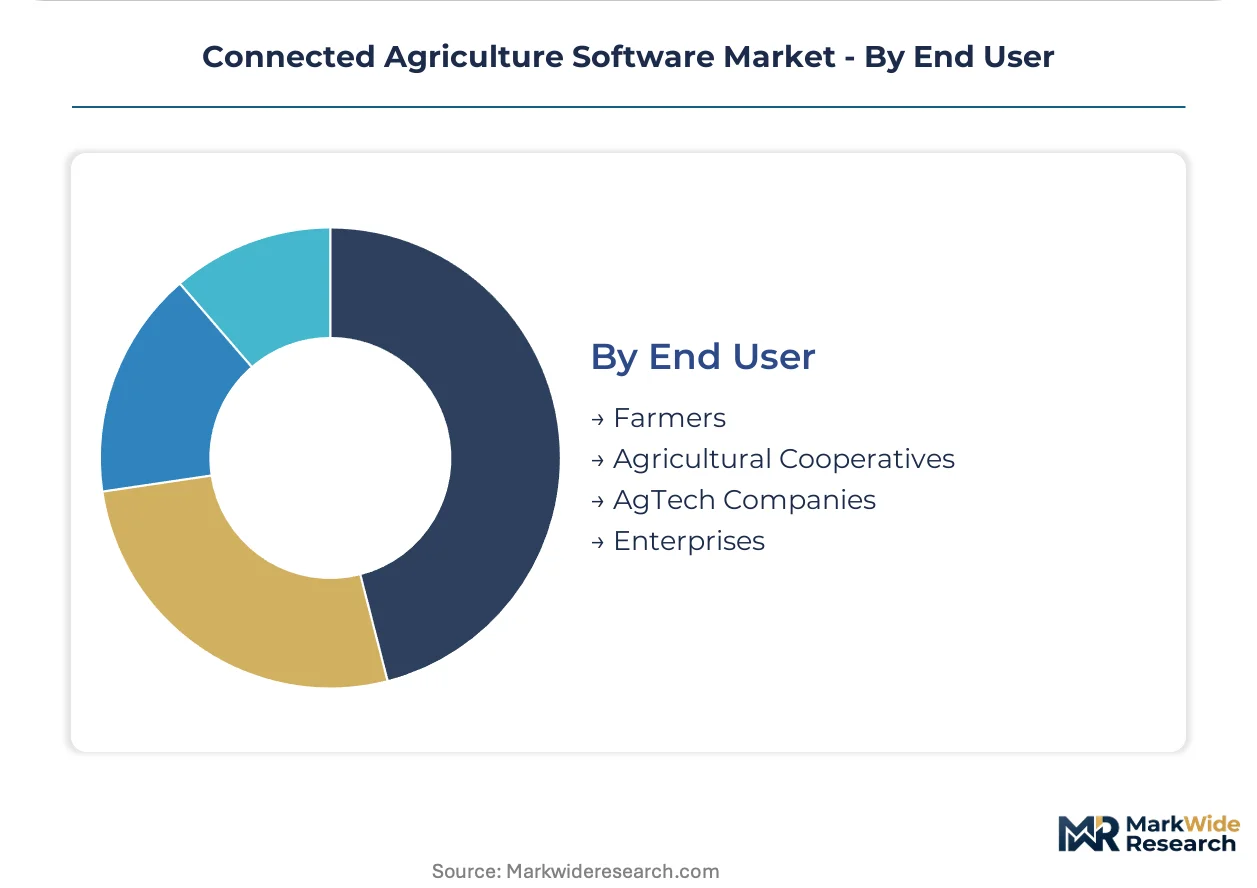
- Farmers:Owner-operators and family farms purchasing subscription-based modules for field-level optimization. USDA conservation program incentives are reducing acquisition friction for precision agriculture investments among mid-size operations.
- Agricultural Cooperatives:Member-owned entities procuring branded portals for collective farm management. Central and Eastern European cooperatives are driving channel partnership demand without direct enterprise sales cycles.
- AgTech Companies:Technology developers and platform integrators building specialized modules atop core infrastructure.
- Enterprises:Large agribusiness conglomerates and food processors requiring supply chain visibility and Scope 3 emissions tracking.
Farmers represent the largest addressable population; Agricultural Cooperatives is gaining share fastest on white-label procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River grain corridor underwrites United States dominance in precision agriculture software adoption, with barge terminals at St. Louis and Memphis enabling data-intensive commodity flows that justify platform investments.
United States
Corn and soybean belt operations drive subscription volume for satellite imagery and yield prediction APIs. USDA conservation programs provide cost-share incentives that reduce customer acquisition friction for precision agriculture vendors. The Central Valley of California hosts pilot deployments of edge-native AI irrigation systems among mid-size vegetable producers.
Germany
German cereal producers face mandatory EU Green Deal sustainability metrics that compel adoption of cloud-based certification modules. The country's national agricultural regulator enforces strict nutrient runoff documentation requirements. Bavarian dairy cooperatives now require emissions calculation engines in procurement specifications for farm management software.
Brazil
Soybean and sugarcane conglomerates in Mato Grosso and São Paulo states seek unified platforms to consolidate irrigation and fertilization point solutions. Rural connectivity gaps in the Cerrado region limit edge gateway deployment density. Campinas anchors agtech startup formation with proximity to research universities and commodity trading infrastructure.
India
Mid-size cotton and rice operations in Maharashtra and Gujarat pilot subscription models for crop monitoring tools as satellite imagery prices decline. The country's central agricultural technology regulator promotes digital infrastructure standards under national precision farming initiatives. The Punjab-Haryana wheat belt concentrates early adoption of soil health monitoring sensor networks.
Australia
Queensland and New South Wales cotton producers with in-house data science teams drive demand for à-la-carte API access rather than comprehensive platform subscriptions. The national agricultural research agency validates yield prediction models for regional calibration. Toowoomba serves as a cluster for farm software integration services targeting broadacre grain operations.
Connected Agriculture Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor telemetry and imagery feeds. The vendor landscape exhibits moderate fragmentation as hyperscale cloud infrastructure reduces capital barriers for new entrants. Three archetypes dominate: equipment-anchored hardware-software integrators, pure-play SaaS farm management platforms, and cooperative-facing white-label portal providers. Competitive moves concentrate on API convergence strategies and cooperative channel partnerships that bypass direct enterprise sales cycles.
Within the equipment-anchored tier, Bosch Connected Agriculture exemplifies sensor-to-cloud pipeline integration, while AGRIVI occupies a position serving agricultural cooperative white-label deployments across Central and Eastern Europe. Cropin Technology Solutions represents the emerging-market platform archetype with AI-driven crop intelligence capabilities.
| Leading Market Players |
|---|
| Plantix |
| Instacrops |
| Cropin Technology Solutions |
| Bluewhite |
| FarmERP |
| AGRIVI |
| Agrosmart |
| Bosch Connected Agriculture |
| OneSoil |
| Others |
Pricing and Supply Chain Analysis
The Mississippi River barge corridor's freight cost volatility directly shapes software pricing power across the Corn Belt, as proximity to St. Louis and Memphis terminals determines platform ROI thresholds for precision agriculture investments. Supply concentration among hyperscale cloud providers in the United States compresses infrastructure margins while enabling tiered subscription models that differentiate commodity row-crop operators from specialty producers seeking traceability compliance.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating enterprise agribusiness suites from mid-size farm management portals and à-la-carte API access for cotton producers with in-house data science teams. Price differentiation rests on integration complexity and after-sales support bundling, where white-label cooperative deployments command premiums over direct subscriptions. Pricing pressure stems from satellite imagery cost volatility and launch schedule delays that squeeze crop monitoring tool margins. Mid-size vegetable producers in California exhibit highest price sensitivity, while German dairy cooperatives prioritize certified carbon accounting functionality over cost.
Supply Chain Analysis
Contract manufacturing concentration among Taiwanese semiconductor foundries and South Korean memory suppliers anchors sensor-to-cloud pipeline production for edge gateway hardware. Component dependencies center on silicon wafers, lithium-ion cells for field sensor power, and optical components for multispectral imaging modules. Single-source vulnerability in satellite constellation operations creates input uncertainty for imagery-dependent prescription services. Distribution runs through agricultural equipment dealerships and cooperative procurement channels rather than direct enterprise sales, with channel partners managing usage-based billing infrastructure for API-centric buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source farm management platforms and generative AI coding tools threaten incumbent pricing power by enabling grower-built substitutes that bypass subscription fees entirely. Incumbents must defend through data network effects and regulatory certification moats that homemade alternatives cannot replicate.
For Market Incumbents: Build data network effect moats by integrating proprietary yield prediction models with EPA-mandated nutrient runoff reporting modules that lock in multi-season contracts. Consolidate point-solution vendors through API convergence strategies that subsume irrigation, fertilization, and harvest logistics into unified operating systems. Channel control through cooperative white-label partnerships in Central and Eastern Europe defends against hyperscale cloud entrants bypassing capital barriers. For New Entrants and Emerging Players: Rural connectivity gaps in Brazil's Cerrado region and India's Maharashtra cotton belt represent addressable white-space where edge-native AI irrigation systems can bypass centralized cloud architectures. Target mid-size operations with USDA conservation program eligibility, leveraging cost-share incentives to reduce customer acquisition friction. Go-to-market through agricultural cooperative channel partnerships avoids direct enterprise sales cycle extension from data portability friction. For Investors and Strategic Acquirers: Carve-out targets emerge from equipment manufacturers seeking to divest non-core software divisions as hardware margins compress under edge-AI deployment shifts. Long-term viability favors platforms with certified EU Green Deal compliance modules and Scope 3 emissions calculation engines embedded for downstream food processor procurement. Watch for inflection when German and French cereal producers mandate carbon accounting functionality as RFP eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| API Convergence Platform | Unifies irrigation, fertilization, and harvest modules into single dashboards for Corn Belt operators. |
| Cooperative White-Label Partnership | Enables branded farm management portals across Central and Eastern Europe without direct sales cycles. |
| Edge-Native AI Certification | Validates sub-hour irrigation adjustment capabilities for California Central Valley vegetable producers. |
| CSRD Compliance Module Development | Embeds Scope 3 emissions engines required by Bavarian dairy cooperative procurement specifications. |
| Satellite Imagery API Integration | Reduces input cost uncertainty for crop monitoring tools through constellation diversification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with farm management software CTOs, agricultural cooperative procurement directors, precision agriculture platform engineers, and channel integration specialists. Secondary validation drew from USDA conservation program filings, EPA agricultural runoff documentation requirements, EU Green Deal regulatory texts, and hyperscaler cloud infrastructure capex disclosures. Bottom-up farm-level adoption modeling and top-down market sizing triangulated volume estimates across deployment models and organization scales.
Calibration against historical subscription growth patterns and regulatory compliance adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include product type, application, technology deployment architecture, and end-user category. CAGRs were derived from fitted growth curves incorporating precision agriculture equipment cost-share incentive uptake and satellite imagery price decline trajectories. Industry-specific inputs included edge gateway deployment density constraints and cooperative white-label procurement velocity.
Practitioners should monitor satellite launch schedule reliability and rural broadband infrastructure buildout pace for early signals of forecast deviation. Assumptions reflect current EPA reporting requirements and EU Green Deal implementation timelines. Quarterly review of constellation failure rates and imagery API pricing volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Global Precision Livestock Farming Market