
 Variable Rate Technology Market | 2026-2036
Variable Rate Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Rate Technology Market Intelligence
The EU Green Deal is repositioning the cost-of-entry calculus for precision agriculture equipment across European farming operations. Deere & Company leverages its integrated hardware-software stack to dominate North American distribution channels. Trimble Inc. specializes in GNSS-guided variable rate controllers that anchor its position in aftermarket retrofit segments. AGCO Corporation navigates regional compliance requirements through modular platform architectures adaptable to local input regulations.
Variable Rate Technology encompasses sensor-driven systems that modulate input application rates across spatially heterogeneous fields, typically integrating GPS positioning, real-time soil sensing, and prescription map execution to optimize seeding density, fertilizer placement, or irrigation volume. Hardware components including variable-rate controllers and actuator interfaces constitute the mature revenue base, while cloud-based deployment architectures represent the fastest-expanding segment as farm operations consolidate data management across dispersed equipment fleets. Edge computing deployments are emerging as a margin-rich niche where latency-sensitive real-time control commands bypass centralized cloud latency.
The EPA regulates agricultural chemical application rates through FIFRA enforcement, while the EU Green Deal's Farm to Fork strategy mandates nutrient reduction targets that directly shape product specification requirements for equipment sold in member states. Brazil's national agricultural regulator enforces input documentation standards that influence software feature development for South American market access. Stakeholders must monitor evolving carbon accounting methodologies that could reclassify precision input reduction as verifiable offset generation, fundamentally altering equipment ROI calculations for climate-conscious farm operators.
Market Dynamics
Cloud-based data architectures are compressing equipment refresh cycles as farm operators consolidate telemetry across dispersed machinery fleets, forcing hardware manufacturers to defend installed bases through software subscription attach rates rather than controller replacement sales.
Growth Catalysts
- EU Green Deal nutrient mandates:The Farm to Fork strategy's reduction targets compel European growers to adopt prescription mapping tools that demonstrate compliance through documented input optimization.
- Brazilian soybean belt consolidation:Large-scale operators in Mato Grosso and Goiás deploy variable-rate controllers to manage fertilizer costs across ten-thousand-hectare blocks where manual calibration becomes economically prohibitive.
- Edge computing latency thresholds:Real-time actuator commands for sub-second nozzle response are absorbing processing power into field-mounted units, bypassing cloud round-trip delays that compromise application accuracy.
Market Restraints
- GNSS correction service concentration:RTK signal infrastructure depends on a limited base station network in rural coverage gaps, creating dead zones where prescription execution accuracy degrades below agronomic thresholds.
- Semiconductor actuator component volatility:Variable-rate valve controllers rely on specialized analog-digital converters whose lead times extend 26-40 weeks during foundry allocation cycles.
- Legacy CAN bus protocol fragmentation:Equipment manufacturers maintain proprietary communication standards that prevent cross-brand controller integration, locking growers into single-vendor fleets.
Strategic Opportunities
- Carbon accounting methodology alignment:Precision input reduction documentation positions VRT systems as verifiable offset generation infrastructure, altering ROI calculations for climate-conscious operators.
- Drone-mounted hyperspectral sensing convergence:Aerial imagery platforms are integrating with ground-based controllers to enable same-day prescription updates without soil probe lag.
- Indian Punjab-Haryana wheat-rice belt penetration:Subsidized precision agriculture equipment under the central government's agricultural mechanization mission targets 2.5 million smallholder transitions.
Industry Challenges
- Agronomic data science talent scarcity:Prescription map development requires hybrid competencies combining soil chemistry, spatial statistics, and equipment calibration that agricultural extension services rarely provide.
- ISO 11783 compliance certification timelines:ISOBUS universal terminal interoperability testing delays product launches 8-14 months as manufacturers validate against multiple implement manufacturer implementations.
- Retrofit installation skill gaps:Aftermarket controller deployment on legacy tractors demands hydraulic plumbing expertise that dealer technician training programs have not systematically addressed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Rate Technology Market |
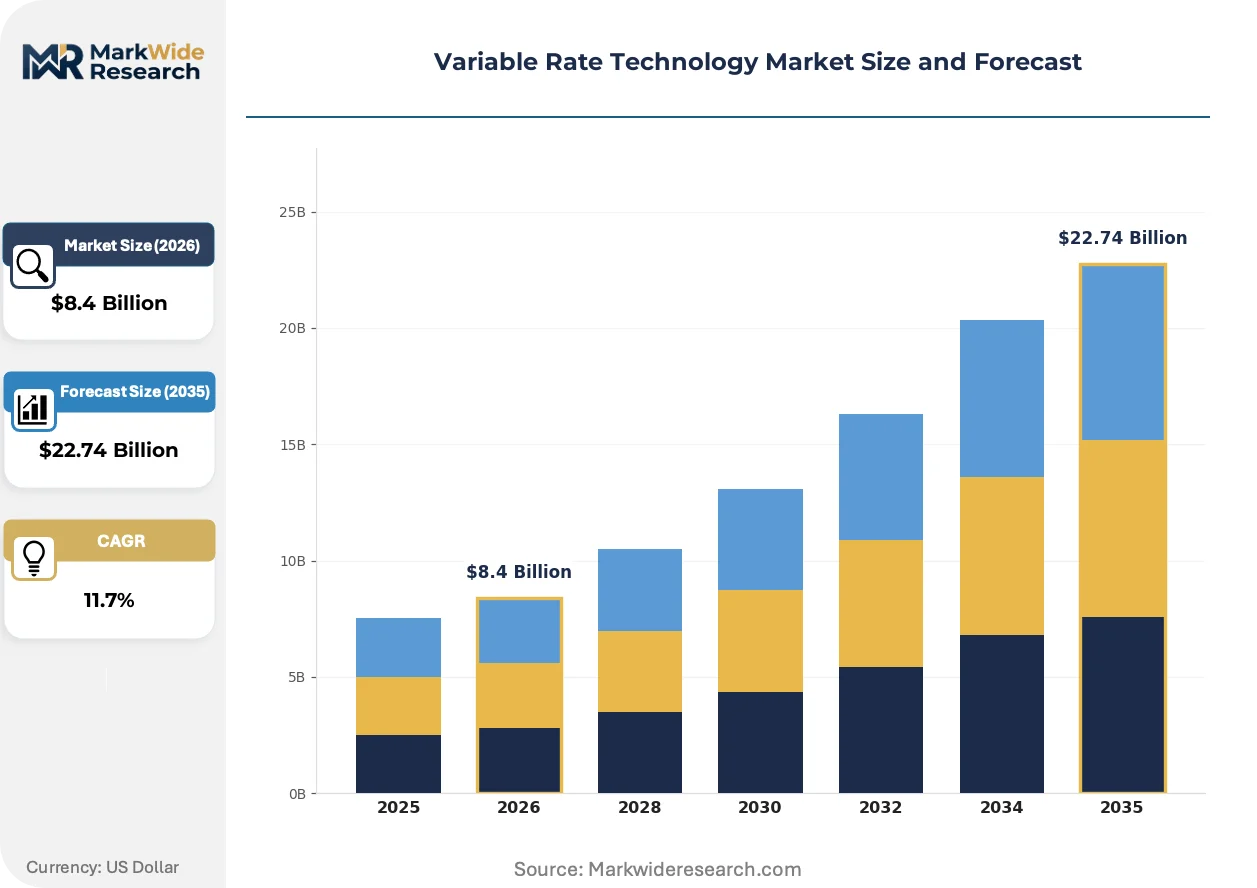
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Controllers, Interfaces Application: Agriculture, Manufacturing, Telecommunications, Energy Management End User: Farmers, Industrial Manufacturers, Service Providers, Energy Companies Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Topcon Corporation, Kubota Corporation, Valmont Industries, Inc., Lindsay Corporation, Yara International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Rate Technology Market Strategic Shifts & Innovations
Real-time kinematic positioning accuracy is commoditizing while prescription algorithm sophistication becomes the primary equipment differentiation vector, compressing margin structures in hardware while expanding software attach-rate economics.
Multi-spectral camera arrays mounted on fertilizer spreaders are absorbing nitrogen sensing functions that previously required separate soil sampling laboratory workflows. Corn and wheat operators in Iowa and Illinois deploy these integrated systems to eliminate the 3-5 day lag between tissue testing and variable-rate urea application. The technology is absorbing mid-season sidedress operations into single-pass equipment configurations that reduce fuel and compaction costs.
EPA FIFRA enforcement priorities are tightening documentation requirements for chemical application rates, mandating timestamped geolocation records for every nozzle activation. Equipment manufacturers respond by embedding immutable audit trails in controller firmware that resist post-hoc data modification. The regulatory pressure is accelerating cloud telemetry adoption as growers seek automated compliance archiving that satisfies inspector subpoena protocols.
Cooperative purchasing arrangements among mid-scale operations are consolidating equipment procurement decisions into multi-farm consortia that negotiate fleet-scale software licensing. These buying pools in Nebraska and Kansas displace individual dealer relationships with direct manufacturer contracts that bundle hardware, prescription services, and seasonal agronomic support. The channel compression is most visible in regions where 2,000-5,000 acre operations lack internal agronomy staff but share equipment utilization across contiguous landholdings.
Variable Rate Technology Market Segmentation
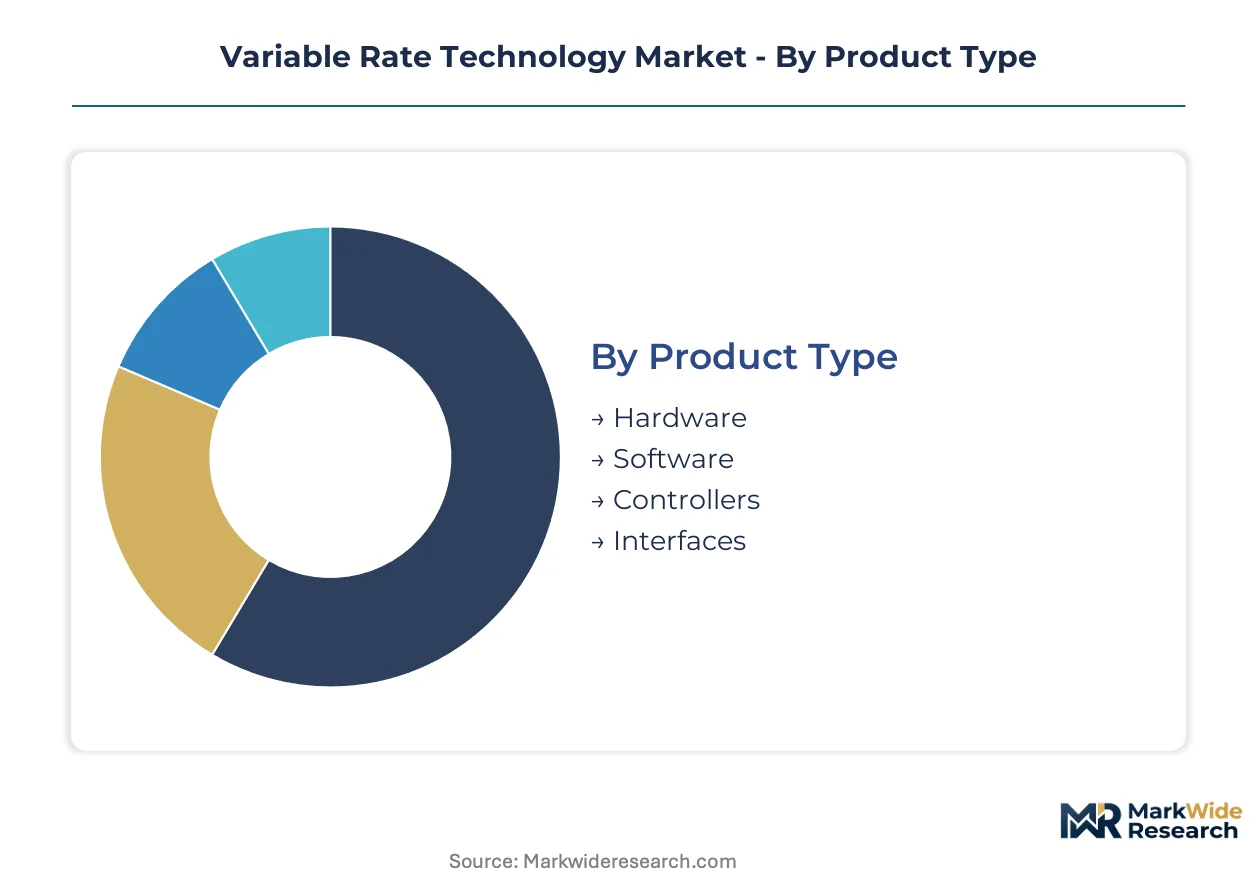
Variable Rate Technology segments along four distinct axes that shape procurement patterns and margin structures. Product type determines whether vendors capture revenue through capital equipment sales or recurring software subscriptions. Application scope separates agricultural precision systems from industrial process control, each with divergent compliance requirements and customer concentration.
Product Type:
Hardware dominates installed value while software commands expanding recurring revenue streams across precision agriculture deployments.
- Hardware:Sensor arrays, GPS receivers, and hydraulic actuators constitute the physical infrastructure for field-variable input modulation. Farmers in Iowa and Mato Grosso prioritize ruggedized enclosures rated for vibration and moisture exposure during extended planting windows.
- Software:Prescription mapping algorithms and telemetry dashboards enable spatial data interpretation and automated compliance documentation. The EU Green Deal's nutrient reduction mandates accelerate adoption of cloud-based platforms that generate audit-ready application records for member state regulators.
- Controllers:Embedded processing units execute real-time rate adjustments based on sensor feedback and pre-loaded prescription maps.
- Interfaces:Operator terminals and mobile applications bridge machine control with human decision-making during field operations.
Today's leader: Hardware. Tomorrow's challenger: Software.
Application:
Agriculture absorbs the dominant share of precision variable-rate deployment, though industrial process control presents higher margin opportunities.
- Agriculture:Crop input optimization across seeding, fertilization, and irrigation commands the primary demand volume. Brazilian soybean operators in Goiás deploy variable-rate controllers across ten-thousand-hectare blocks where manual calibration proves economically prohibitive.
- Manufacturing:Assembly line flow control and adaptive resource allocation drive industrial VRT adoption. Discrete manufacturers prioritize sub-second actuator response times that edge computing architectures deliver more reliably than cloud-dependent alternatives.
- Telecommunications:Dynamic bandwidth allocation and network traffic management utilize rate-adjustment logic originally developed for agricultural prescription mapping.
- Energy Management:Grid load balancing and distributed generation coordination apply variable-rate principles to electricity distribution infrastructure.
Volume concentrates in Agriculture. Margin expansion tracks toward Manufacturing.
End User:
Farmers represent the price-sensitive mass market while energy companies present contract-scale procurement opportunities.
- Farmers:Owner-operators and large-scale agricultural enterprises seek input cost reduction through documented application precision. North American corn belt growers prioritize ISOBUS-compatible systems that integrate across mixed-brand equipment fleets.
- Industrial Manufacturers:Process industries deploy variable-rate systems for raw material optimization and waste minimization. Automotive and chemical sectors demand ISO-certified controllers with predictive maintenance capabilities.
- Service Providers:Custom application businesses and agronomic consulting firms purchase VRT systems as revenue-generating capital equipment.
- Energy Companies:Utilities and independent power producers utilize rate-adjustment technologies for demand response and renewable integration.
Procurement scale peaks with Energy Companies. Deployment velocity runs highest among Farmers.
Deployment:
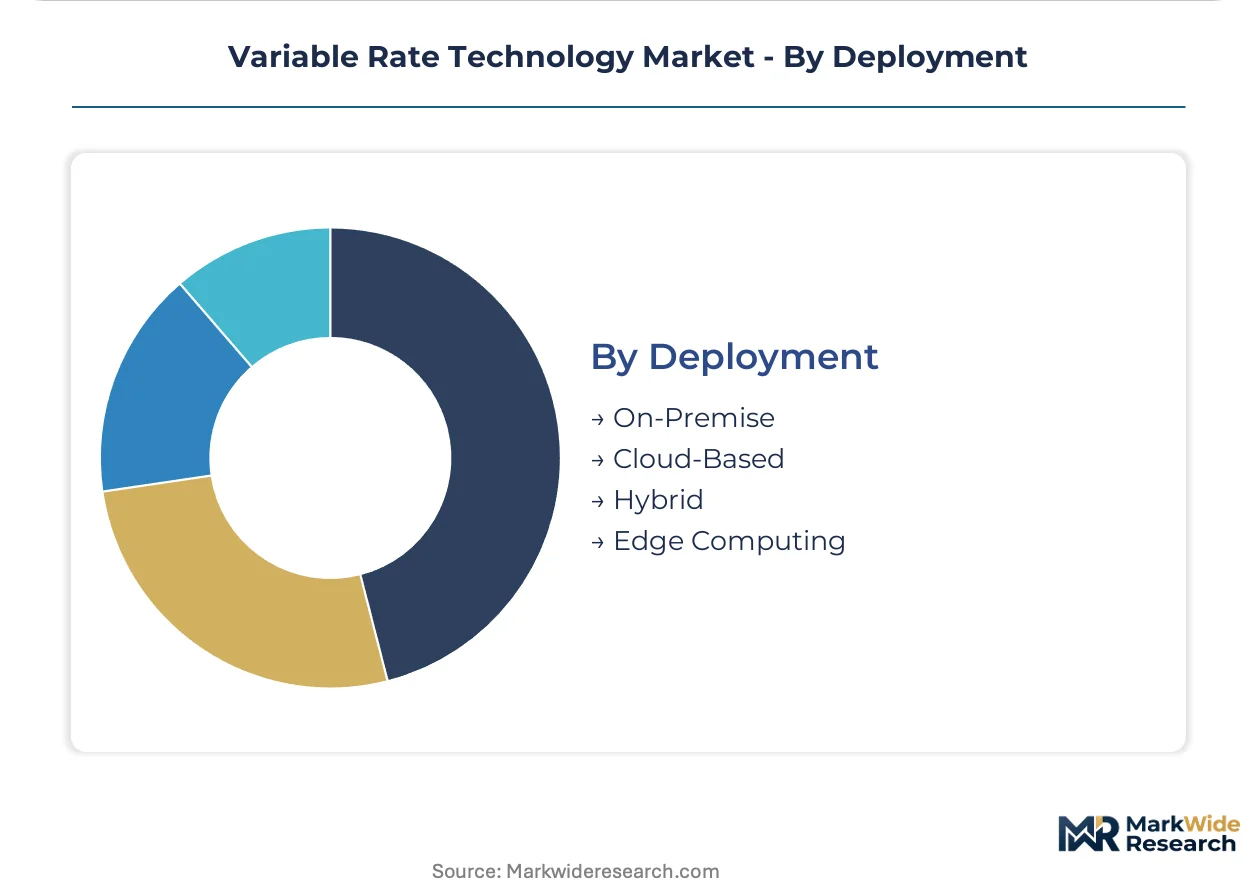
On-premise legacy systems defend installed bases while cloud architectures capture new customer acquisition.
- On-Premise:Local server installations and offline prescription management persist in regions with unreliable cellular coverage. Rural Nebraska and Kansas operations maintain on-premise systems where RTK correction signal dead zones compromise real-time cloud dependency.
- Cloud-Based:Centralized data architectures enable cross-fleet telemetry consolidation and automated software updates. EPA FIFRA enforcement priorities mandating timestamped geolocation records accelerate cloud adoption for compliance archiving.
- Hybrid:Split architectures process latency-sensitive control commands locally while archiving analytics in cloud repositories.
- Edge Computing:Field-mounted processing units execute sub-second actuator commands without cloud round-trip delays. Nitrogen sensing spreaders in Illinois deploy edge architectures for same-pass variable-rate urea application.
Cloud-Based systems claim the steepest expansion trajectory. Edge Computing defends the premium price tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Variable rate technology emerged from GPS-guided farming experiments in the US Midwest during the 1990s, then diffused through Canadian prairie operations and Brazilian commercial soybean estates before reaching European regulatory compliance markets.
United States
Corn belt operators in Iowa and Illinois deploy multi-spectral nitrogen sensing spreaders to compress sidedress application windows. EPA FIFRA enforcement mandates timestamped geolocation records for every nozzle activation, accelerating cloud telemetry adoption for automated compliance archiving. The Nebraska-Kansas cooperative purchasing corridor consolidates procurement decisions into multi-farm consortia negotiating direct manufacturer contracts.
Brazil
Large-scale operators in Mato Grosso and Goiás manage fertilizer costs across ten-thousand-hectare blocks where manual calibration proves economically prohibitive. ANVISA enforces input documentation standards that shape software feature development for South American market access. The Cerrado soybean belt concentrates demand for ruggedized variable-rate controllers rated for extended tropical planting windows.
Germany
Bavarian and Lower Saxon arable farms adopt prescription mapping tools to demonstrate EU Green Deal Farm to Fork nutrient reduction compliance. REACH chemical registration requirements intersect with machinery certification standards for equipment sold across member states. The precision agriculture cluster around Munich anchors development of ISOBUS-compatible modular platforms adaptable to regional input regulations.
Canada
Prairie wheat and canola operations in Saskatchewan and Alberta prioritize RTK-dependent systems where cellular coverage gaps persist. Health Canada PMRA regulates agricultural chemical application rates through parallel enforcement frameworks to US EPA. The Red River Valley consolidation trend drives cooperative equipment utilization across contiguous landholdings lacking internal agronomy staff.
India
Punjab-Haryana wheat-rice belt smallholders transition under the central government's agricultural mechanization mission subsidizing precision equipment adoption. FSSAI traceability requirements intersect with input optimization documentation for export-oriented basmati operations. The Karnal-Ludhiana corridor concentrates dealer technician training programs addressing retrofit installation skill gaps on legacy tractor fleets.
Variable Rate Technology Market Key Industry Players
The competitive structure tilts toward diversified agricultural equipment conglomerates defending installed bases through software subscription attach rates. Tier-one positions concentrate around integrated hardware-software stacks with distribution channel dominance, while specialists occupy aftermarket retrofit segments through GNSS-guided controller expertise. Strategic moves center on ISOBUS interoperability certification investments compressing product launch timelines, and edge computing architecture development bypassing cloud latency for sub-second actuator response.
Within the integrated equipment tier, Deere & Company and CNH Industrial N.V. exemplify conglomerate positioning through captive distribution networks and modular platform architectures. Trimble Inc. occupies the specialist vector with GNSS-centric aftermarket positioning. AGCO Corporation represents adaptive compliance navigation through regional specification flexibility. Kubota Corporation and Topcon Corporation sit within the Asia-Pacific origin tier competing on manufacturing scale and precision optics heritage respectively.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Topcon Corporation |
| Kubota Corporation |
| Valmont Industries, Inc. |
| Lindsay Corporation |
| Yara International |
| Others |
Cost & Logistics Intelligence
EU Green Deal nutrient reduction mandates gate access to premium-tier variable rate technology pricing by qualifying only ISOBUS-certified controllers and cloud-compliant telemetry architectures for member state procurement. This environmental compliance filter concentrates qualified supply among manufacturers with modular platform investments, while locking uncertified competitors into economy-tier retrofit segments with compressed margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates variable rate technology procurement. Premium tiers attach software subscription bundling and automated compliance documentation for EU and EPA regulatory environments; standard tiers compete on ISOBUS interoperability alone; economy tiers serve aftermarket retrofit demand with hardware-only configurations. Cost compression in the economy tier intensifies because semiconductor lead time volatility forces inventory carrying cost absorption onto distributors. Large-scale Brazilian soybean operators exhibit lowest price sensitivity due to ten-thousand-hectare scale efficiencies, while Indian smallholders under mechanization mission subsidies remain most price-constrained.
Supply Chain Analysis
ISOBUS certification and EPA FIFRA compliance documentation gate upstream component sourcing for variable rate controller manufacturers. Supply concentrates in Germany for precision optics and embedded processing units, Taiwan for specialized analog-digital converters, and the United States for RTK correction service infrastructure. Controller production draws from agricultural-grade sensor arrays, hydraulic actuator valves, and GNSS receiver modules. Single-source vulnerability runs through foundry allocation cycles for automotive-qualified semiconductors. Distribution runs through captive dealer networks for integrated equipment conglomerates and independent precision agriculture specialists for aftermarket retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable rate technology functions as a stable compounder where regulatory compliance mandates generate replacement demand with predictable cadence. Equipment refresh cycles compress as cloud telemetry consolidation forces software subscription economics over hardware replacement revenue.
For Market Incumbents: Extend software subscription attach rates through prescription algorithm licensing that locks growers into telemetry ecosystems. Defend against emerging edge computing specialists by embedding sub-second actuator response capabilities in field-mounted controller units. Prioritize ISOBUS interoperability certification investments that compress product launch timelines against modular platform competitors. For New Entrants and Emerging Players: Agronomic consulting firms represent the most penetrable channel partner type for white-space entry into variable rate technology deployment. Target Indian Punjab-Haryana wheat-rice belt retrofit installation demand where subsidized mechanization mission programs lower customer acquisition costs. Pursue drone-mounted hyperspectral sensing convergence as a go-to-market angle that bypasses established ground-based controller incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional precision agriculture specialists because agronomic data science talent scarcity prevents rapid organic capability building. Five-to-ten year viability hinges on carbon accounting methodology alignment that reclassifies precision input reduction as verifiable offset generation infrastructure. Watch for EPA FIFRA enforcement priority shifts toward immutable audit trail mandates as the inflection signal for cloud telemetry adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISOBUS Interoperability Certification | Compresses product launch timelines against modular platform competitors in EU member states. |
| Edge Computing Architecture Development | Enables sub-second actuator response that bypasses cloud latency for nitrogen sensing spreaders. |
| Carbon Accounting Methodology Alignment | Positions precision input reduction as verifiable offset generation infrastructure for climate-conscious operators. |
| Cooperative Purchasing Consortium Engagement | Captures multi-farm procurement decisions in Nebraska-Kansas corridor lacking internal agronomy staff. |
| Drone-Mounted Hyperspectral Sensing Integration | Enables same-day prescription updates without soil probe lag for corn belt sidedress operations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both equipment shipment volumes and procurement decision dynamics. Primary engagement spanned precision agriculture product managers at equipment manufacturers, agronomic consultants developing prescription maps, dealer technicians performing retrofit installations, and farm operators managing ten-thousand-hectare blocks in Mato Grosso. Secondary validation drew from EPA FIFRA enforcement documentation, EU Green Deal Farm to Fork strategy filings, ANVISA input registration databases, and ISOBUS certification test records. Bottom-up equipment deployment tracking triangulated against top-down input optimization spend estimates across major agricultural regions.
Historical reference periods anchored the projection horizon to documented adoption curves from GPS-guided farming diffusion in the 1990s through present cloud telemetry consolidation. Segmentation modeling spanned product type, application scope, end user archetype, and deployment architecture across the analysis window. CAGRs derived from equipment replacement cycle compression rates and software subscription attach rate trajectories. Forecast inputs incorporated RTK correction signal coverage expansion timelines and semiconductor foundry allocation cycle assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon accounting methodology standardization and EPA enforcement priority shifts. Model assumptions reflect documented input optimization economics and regulatory compliance cost structures. A model refresh is warranted upon material change in EU Green Deal nutrient mandate implementation timelines or ANVISA input documentation standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market