
 Corn Milling Machine Market | 2026-2036
Corn Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Milling Machine Market Outlook
Brazil is reshaping regional supply dynamics as new corn ethanol plants in Mato Grosso and Goiás drive demand for continuous processing equipment. Buhler Group leverages its Swiss engineering heritage to dominate high-capacity roller mill installations across South American facilities. Satake Corporation anchors Asian supply chains through specialized pin mill technology for precision grit production. Archer Daniels Midland Company sustains North American market presence through backward integration into equipment specification and captive maintenance networks.
A corn milling machine is a mechanical processing unit designed to reduce dried corn kernels into fractions including grits, meal, flour, and germ through abrasive, compressive, or impact forces at throughput rates ranging from 500 kg/hr to over 50 tons/hr. Its primary purpose is to transform raw grain into standardized intermediate products for food manufacturing, fuel ethanol fermentation, and compound feed formulation. Roller mill configurations occupy the premium tier of the product type landscape due to their gentler shear profiles and superior germ recovery rates in wet milling circuits. Automated systems within the technology dimension represent the fastest-growing segment as labor costs climb and food safety traceability requirements tighten across regulated jurisdictions. Small scale capacity equipment retains stubborn price competition from Asian fabricators, compressing margin pools for standardized hammer mill offerings.
The EPA enforces Renewable Fuel Standard blending mandates that directly sustain ethanol plant capacity utilization and associated milling equipment replacement cycles. FDA food safety modernization rules and OSHA grain handling standards jointly elevate capital requirements for dust control and sanitary design in domestic installations. Equipment buyers must monitor how the IRA's clean fuel production credits redirect investment toward carbon capture retrofits that alter mill sizing and utility integration specifications.
Market Dynamics
Wet milling capacity expansion across Brazil is forcing equipment suppliers to reconfigure their service architectures. The EPA's Renewable Fuel Standard mandates sustain ethanol plant utilization rates that drive replacement cycles for high-throughput processing lines.
Growth Catalysts
- EPA Renewable Fuel Standard:Blending mandates enforce minimum ethanol volumes that sustain corn processing infrastructure investment across the American Midwest. Equipment replacement cycles compress as facilities chase efficiency gains.
- Biofuel sector demand:Corn ethanol plants in Mato Grosso and Goiás require continuous processing equipment rated for tropical humidity conditions. Brazilian processors prioritize roller mill configurations with enhanced corrosion resistance.
- Automated systems technology:Labor cost escalation and food safety traceability requirements accelerate adoption of sensor-integrated milling circuits. Regulated jurisdictions mandate lot-level tracking that manual operations cannot satisfy.
Market Restraints
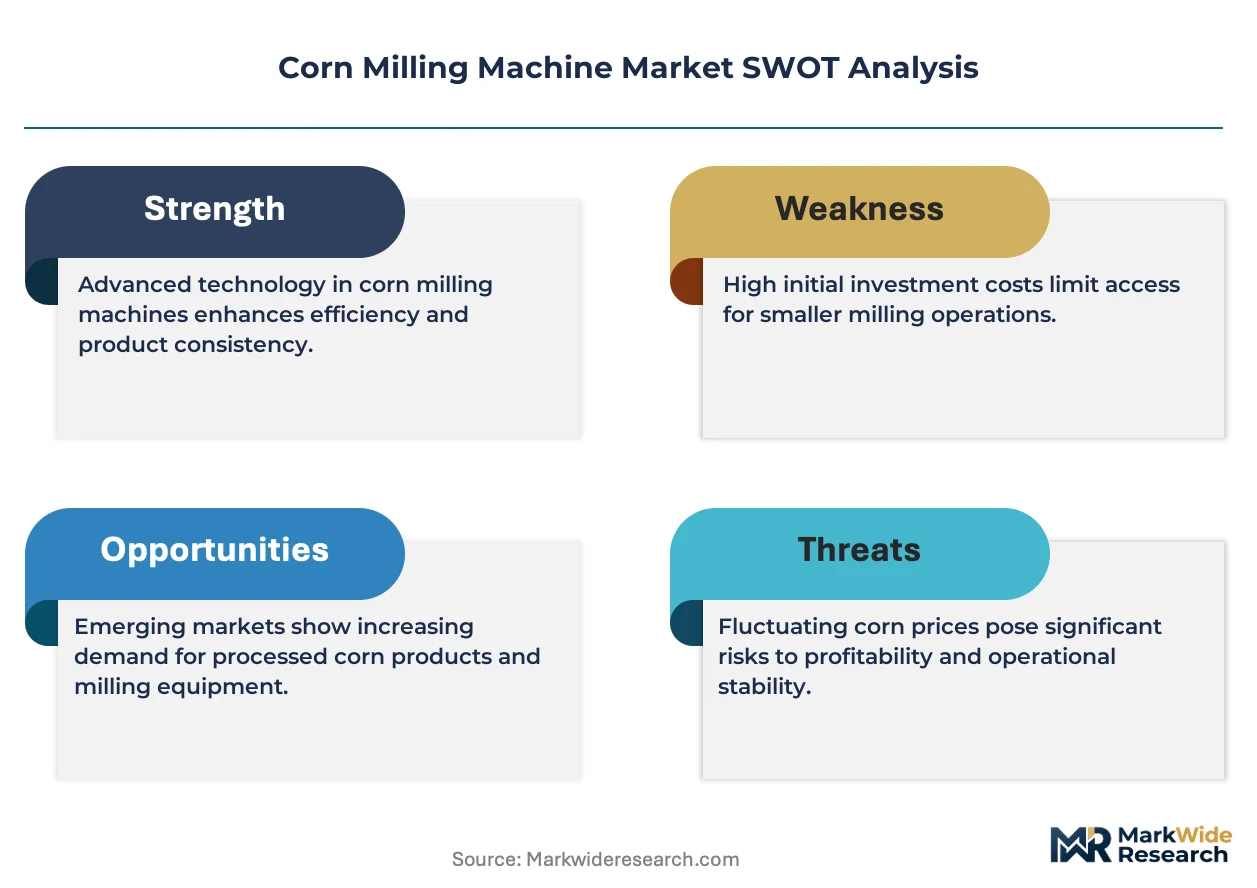
- Stainless steel input volatility:Sanitary-grade alloy prices swing with nickel and chromium commodity markets. Equipment fabricators absorb margin compression or pass costs to capital-constrained small-scale buyers.
- Asian fabricator concentration:Standardized hammer mill supply concentrates in Chinese and Indian manufacturing clusters. Premium European suppliers face price competition that limits volume expansion in economy-tier segments.
- Dual carbon goals technical ceiling:China's MEE standards enforce energy intensity limits that cap throughput-per-kilowatt ratios. Older mill designs face retrofit costs that extend payback periods beyond acceptable thresholds.
Strategic Opportunities
- IRA clean fuel production credits:Carbon capture retrofits alter mill sizing and utility integration specifications. Equipment suppliers can bundle capture-ready designs with processing hardware.
- Precision grit applications:Brewery and snack food segments demand tighter particle size distributions than commodity flour markets. Pin mill technology from Japanese engineering houses captures premium positioning.
- Aftermarket service unbundling:Predictive maintenance contracts separate from equipment sales create recurring revenue streams. Remote diagnostics via IoT sensors reduce field technician dispatch costs.
Industry Challenges
- Mechatronics skill scarcity:Automated milling systems require technicians versed in both mechanical alignment and PLC programming. Rural processing facility locations struggle to attract qualified candidates.
- FDA food safety modernization compliance:Sanitary design validation and documentation timelines extend project delivery schedules. Equipment buyers face delayed revenue recognition from extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Milling Machine Market |
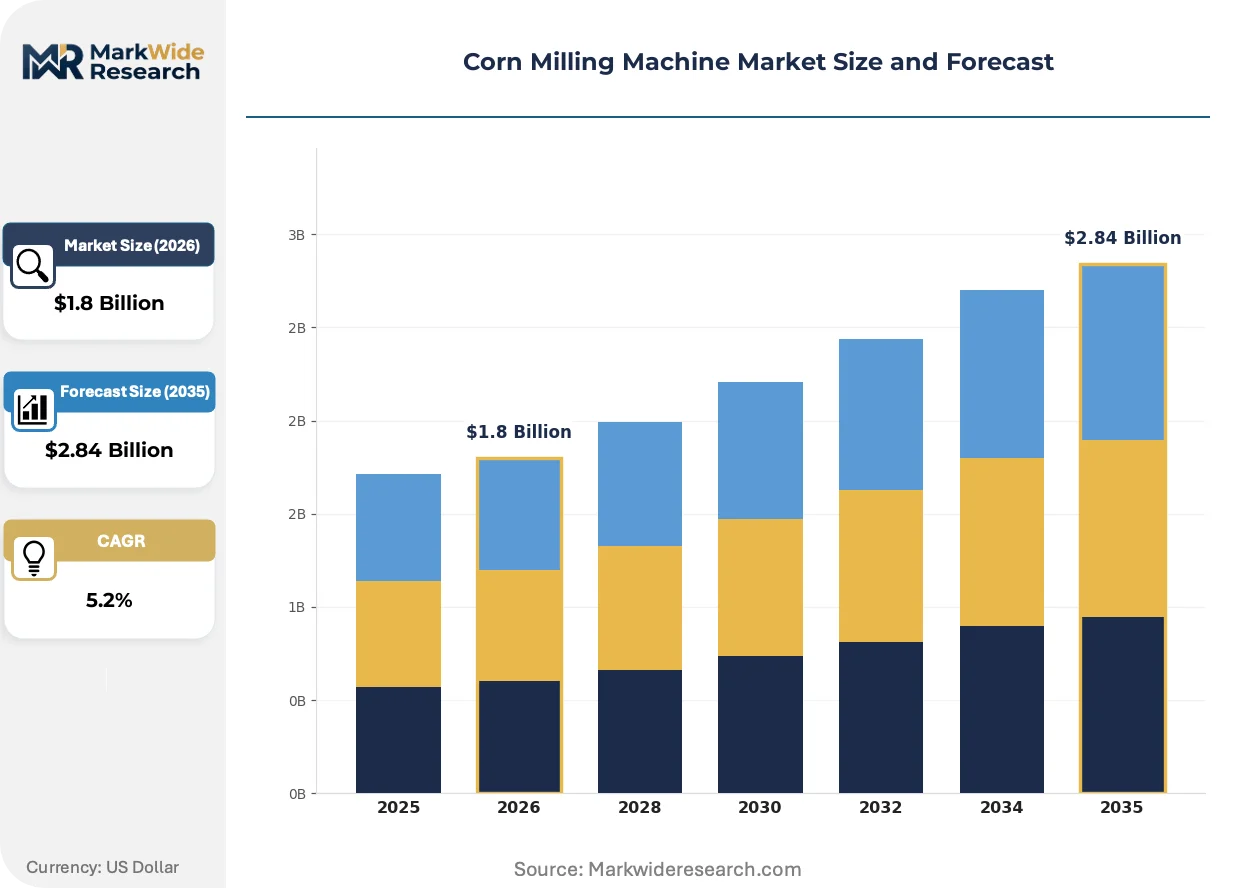
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammer Mill, Roller Mill, Stone Mill, Pin Mill End User: Agriculture, Food Processing, Biofuel Production, Animal Feed Capacity: Small Scale, Medium Scale, Large Scale, Industrial Technology: Batch Processing, Continuous Processing, Automated Systems, Manual |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Tate and Lyle PLC, Agrana Beteiligungs-AG, Roquette Frères, Buhler Group, Satake Corporation, Tehold International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Milling Machine Market Strategic Shifts
Digital twin architectures are compressing equipment commissioning timelines and reshaping how buyers evaluate total cost of ownership. Virtualization of process optimization reduces physical prototyping requirements.
Sensor-integrated roller mill platforms are virtualizing traditional mechanical adjustment protocols. Large integrated grain processors deploy these systems to enable remote gap-setting and real-time throughput modulation. The technology is virtualizing the role of on-site millwrights, compressing labor requirements while elevating capital intensity.
REACH chemical registration requirements in Europe are elevating material traceability standards for food-contact surfaces. Equipment suppliers must document alloy composition and surface treatment chemistry through the supply chain. Wet milling circuits serving export markets face the strictest documentation burdens, driving specification divergence between EU-bound and domestic-only installations.
Buyer consolidation among integrated grain processors is compressing vendor negotiation cycles and elevating specification complexity. Large Midwestern facilities now bundle milling equipment with carbon capture and utility integration in single tender packages. This pattern concentrates most visibly in Iowa and Illinois, where processor scale permits dedicated engineering staff to manage multi-year capital programs.
Corn Milling Machine Market Segmentation
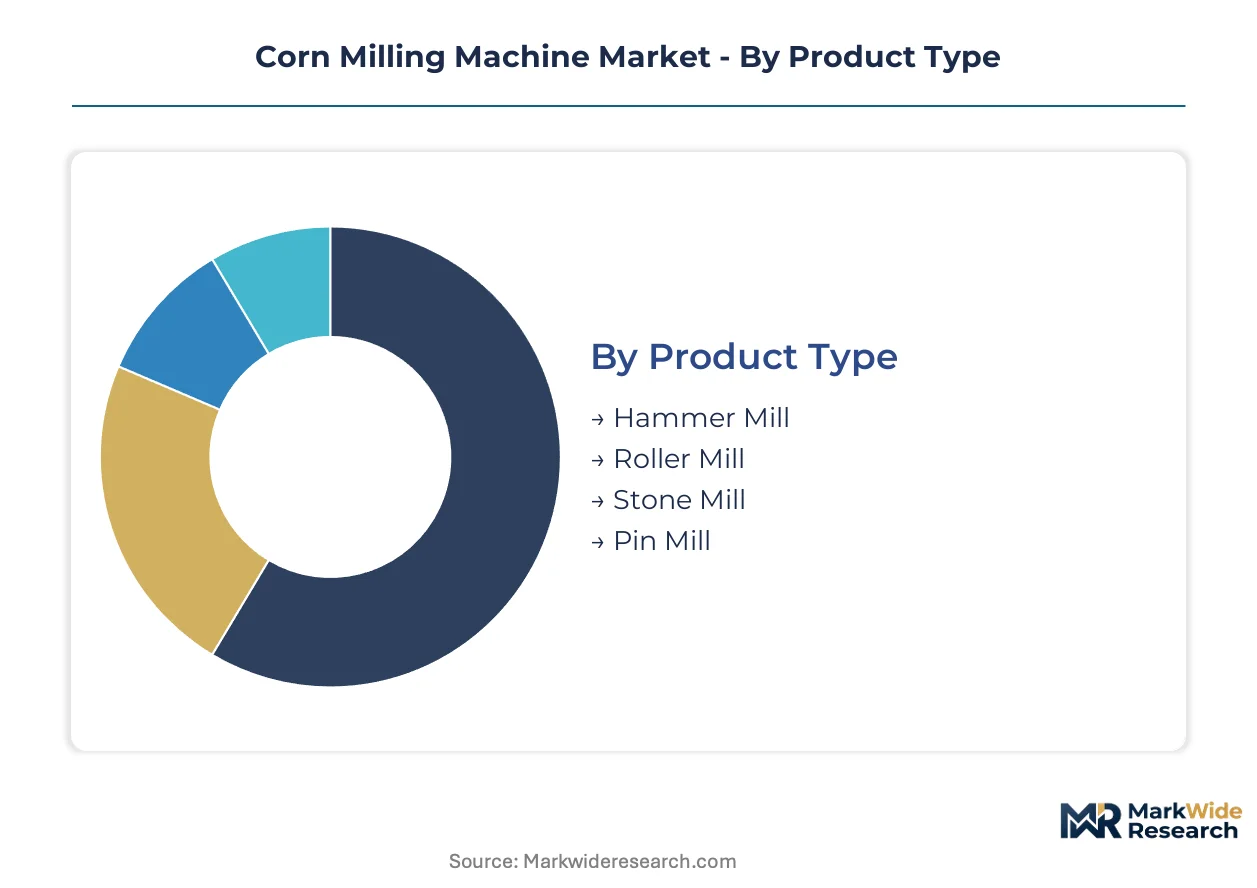
Corn milling equipment segments diverge sharply in replacement cycles and capital intensity. Roller mill installations in wet ethanol circuits turn over every 12-15 years while small-scale hammer mills in rural feed operations cycle faster due to abrasive wear and limited maintenance access.
Product Type:
Roller mill configurations command the longest replacement cycles due to precision bearing assemblies and hardened roll surfaces, while hammer mills in high-abrasion applications require more frequent rebuilds.
- Roller Mill:Precision-machined cast iron or steel rolls apply compressive shear forces between rotating cylinders at adjustable gap settings. Wet milling facilities in Iowa and Illinois specify these units for superior germ recovery rates and lower heat generation during starch extraction.
- Hammer Mill:High-speed rotating hammers mounted on a central shaft impact kernels against breaker plates and screen grates. Dry milling operations serving animal feed compounders across Nebraska and Kansas favor these units for coarse grinding flexibility and lower capital entry points.
- Stone Mill:Corundum or natural stone grinding surfaces operate at lower speeds to preserve heat-sensitive nutrients. Artisanal food processors in Vermont and North Carolina specify these units for heirloom corn varieties and specialty masa production.
- Pin Mill:Counter-rotating pin discs generate impact forces through high-velocity particle-on-particle collisions. Snack food manufacturers in Texas and brewery malt processors demand these systems for precise particle size distributions in premium grit applications.
Roller mill technology dominates installed base in large integrated facilities. Pin mill configurations are where expansion concentrates among precision food applications.
End User:
Capital allocation patterns separate continuous-process biofuel operators from batch-oriented food manufacturers, with ethanol plants commanding the highest per-site equipment values.
- Biofuel Production:Corn ethanol fermentation facilities require continuous milling circuits rated for 24-hour operation with minimal downtime. EPA Renewable Fuel Standard mandates sustain capacity utilization rates above 90% at facilities across Minnesota and South Dakota, compressing maintenance windows and accelerating wear component replacement schedules.
- Food Processing:Masa flour, cornmeal, and grits manufacturers operate batch or semi-continuous systems with frequent product changeovers. FDA food safety modernization rules extend commissioning timelines for sanitary design validation at facilities supplying retail grocery channels.
- Animal Feed:Compound feed mills grind dried distillers grains and corn fractions for poultry and livestock rations. Regional cooperatives in Missouri and Indiana prioritize hammer mill flexibility to handle variable moisture content and kernel damage rates.
- Agriculture:On-farm grinding operations for direct livestock feeding utilize portable or stationary small-scale units. Producer-owned equipment in Ohio and Wisconsin faces seasonal utilization patterns that limit capital recovery compared to commercial processing facilities.
Food processing applications dominate installed base across diversified milling operations. Biofuel production is where capacity expansion concentrates under federal blending mandates.
Capacity:
Equipment scale determines service architecture requirements, with industrial installations demanding dedicated field engineering support unavailable to small-scale buyers.
- Industrial:Systems rated above 50 tons per hour integrate with utility infrastructure and carbon capture equipment at major processing complexes. IRA clean fuel production credits are redirecting investment toward capture-ready mill specifications at facilities in Illinois.
- Large Scale:Units between 10-50 tons per hour serve regional ethanol plants and integrated grain processors. Brazilian facilities in Mato Grosso specify corrosion-resistant roller mill configurations for tropical humidity conditions.
- Medium Scale:Equipment in the 2-10 ton per hour range supports independent feed mills and food processing cooperatives. OSHA grain handling standards elevate dust control capital requirements for these mid-tier installations.
- Small Scale:Portable or stationary units below 2 tons per hour serve on-farm and artisanal applications. Asian fabricators in China and India concentrate supply of standardized hammer mills at price points that compress margin pools for premium European suppliers.
Large scale configurations dominate revenue concentration in North American ethanol infrastructure. Industrial capacity is where new build activity concentrates under decarbonization incentives.
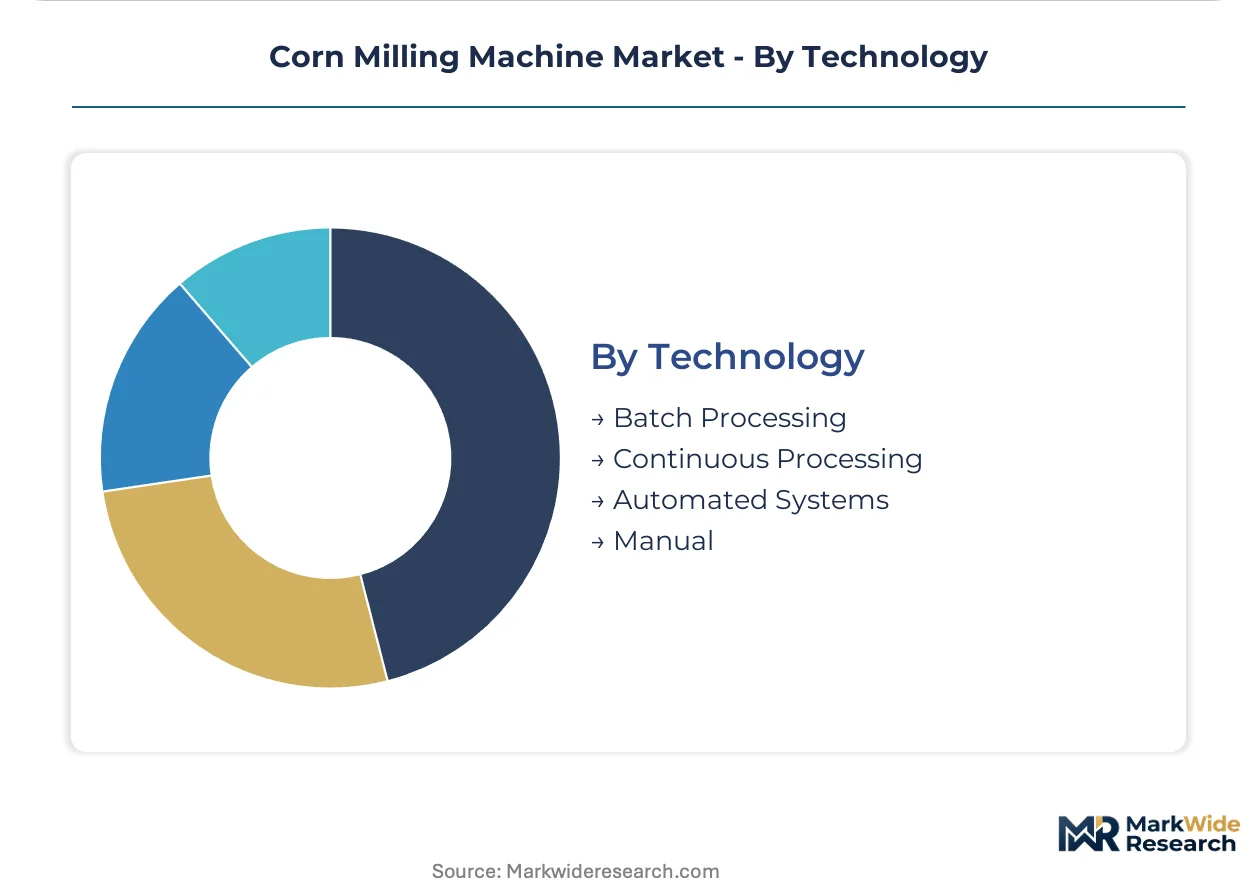
Technology:
Automation intensity separates regulated food safety environments from commodity processing operations with less stringent traceability requirements.
- Automated Systems:Sensor-integrated milling circuits enable remote gap-setting, real-time throughput modulation, and lot-level tracking. FDA food safety modernization rules mandate traceability that manual operations cannot satisfy, accelerating adoption at facilities supplying retail and export channels.
- Continuous Processing:Uninterrupted material flow designs minimize product residence time and temperature buildup. Biofuel plants in Brazil and the American Midwest specify these systems for ethanol fermentation feedstock preparation.
- Batch Processing:Intermittent operation permits product changeovers and equipment cleaning between runs. Specialty food manufacturers leverage batch flexibility for organic certification and allergen control protocols.
- Manual:Operator-dependent adjustment and monitoring persists in developing markets and legacy installations. Rural facility locations struggle to attract mechatronics technicians qualified for automated system maintenance.
Batch processing technology dominates legacy installed base in diversified food operations. Automated systems are where capital deployment concentrates fastest under labor cost escalation and regulatory traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA blending mandates anchor North American demand, while Brazilian biofuel expansion and Asian food processing modernization reshape regional equipment procurement patterns across distinct regulatory environments.
United States
Iowa and Illinois processing complexes drive industrial-scale roller mill demand under Renewable Fuel Standard enforcement. IRA clean fuel production credits redirect capital toward carbon capture-ready mill specifications. Minneapolis-St. Paul corridor facilities bundle utility integration with milling equipment in consolidated tender packages.
Brazil
Mato Grosso and Goiás corn ethanol plants require continuous processing equipment rated for tropical humidity conditions. ANVISA sanitary regulations elevate documentation burdens for export-bound wet milling circuits. São Paulo-based engineering houses coordinate corrosion-resistant roller mill deployments across the Cerrado production belt.
Germany
REACH chemical registration mandates enforce alloy composition traceability for food-contact surfaces. Bavarian precision engineering clusters supply high-capacity roller mill installations to EU biofuel processors. Stuttgart-area fabricators dominate premium-tier equipment specification for sanitary design validation.
China
Dual carbon goals and MEE energy intensity standards cap throughput-per-kilowatt ratios for domestic mill designs. Shandong Peninsula fabricators concentrate standardized hammer mill supply at compressed price points. Yangtze River Delta food processors accelerate automated system adoption under tightening labor cost pressures.
India
FSSAI food safety modernization extends commissioning timelines for sanitary design validation at retail-facing facilities. Gujarat and Maharashtra cooperative feed mills prioritize hammer mill flexibility for variable moisture handling. Punjab agricultural belt sustains small-scale equipment demand through producer-owned grinding operations.
Corn Milling Machine Market Competitive Environment
Integrated grain processors and specialized engineering houses split the market between captive specification authority and third-party equipment supply. Consolidation among Midwestern biofuel operators compresses vendor negotiation cycles. Three archetypes dominate: Swiss-German precision engineering conglomerates, Asian standardized fabricators, and backward-integrated agricultural processors. Competitive moves concentrate on geographic service architecture reconfiguration and predictive maintenance contract unbundling.
Within the precision engineering tier, Buhler Group and Satake Corporation exemplify divergent regional anchoring strategies. Archer Daniels Midland Company occupies a position representing backward-integrated processor authority over equipment specification. Chinese and Indian fabricators sit within the economy-tier supply concentration, compressing margin pools for premium European suppliers through standardized hammer mill offerings at aggressive price points.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Tate and Lyle PLC |
| Agrana Beteiligungs-AG |
| Roquette Frères |
| Buhler Group |
| Satake Corporation |
| Tehold International |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors transmit stainless steel alloy cost volatility into roller mill price spreads between Swiss-German precision suppliers and Asian fabricators. Brazilian ethanol processors absorb elevated landed costs for corrosion-resistant configurations while Midwestern biofuel operators leverage proximity to Chicago rail hubs for standard equipment procurement.
Pricing Analysis
Geographic price spreads between European precision engineering and Asian standardized supply compress margin pools at the economy tier. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification requirements and after-sales bundling intensity. Cost compression in hammer mill segments intensifies because Chinese and Indian fabricators concentrate standardized supply. Small-scale agricultural buyers exhibit highest price sensitivity while integrated biofuel processors prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Extended payment terms from São Paulo-based engineering houses anchor supplier financing arrangements for Brazilian wet milling expansions. Manufacturing concentrates in Germany, Switzerland, China, and India. Equipment fabrication draws from nickel-chromium alloy feedstocks, hardened bearing assemblies, and precision-machined roll castings. Single-source vulnerability in sanitary-grade steel supply elevates risk exposure for export-bound installations. Distribution runs through OEM direct sales for industrial-scale buyers and regional distributor networks for mid-tier feed mill operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity constrains automated system deployment timelines across rural processing locations. Equipment suppliers who internalize training infrastructure or embed remote diagnostics capabilities capture sustainable differentiation.
For Market Incumbents: Build predictive maintenance service moats through IoT-enabled remote diagnostics platforms and multi-year aftermarket contracts. Defensive consolidation should prioritize captive maintenance network expansion in Iowa and Illinois to preempt third-party service unbundling. Capacity addition in Mato Grosso addresses Brazilian biofuel demand while insulating against Asian fabricator price competition in economy-tier segments. For New Entrants and Emerging Players: Artisanal food processing clusters in Vermont and North Carolina present underpenetration opportunities for stone mill and specialty pin mill configurations. Precision grit applications for brewery and snack food segments offer white-space entry with lower capital intensity than industrial ethanol circuits. Go-to-market execution should leverage regional food safety consultant partnerships to accelerate FDA sanitary design validation timelines. For Investors and Strategic Acquirers: Engineering-intensive mid-tier specialists with automated system integration capabilities represent attractive acquisition targets. Long-term viability over the next decade hinges on carbon capture-ready design portfolios and IRA credit capture expertise. Watch EPA Renewable Fuel Standard blending mandate modifications as the critical inflection signal for ethanol plant capacity utilization and associated equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture-Ready Mill Design | IRA clean fuel production credits redirect capital toward integrated utility specifications at Illinois facilities. |
| Predictive Maintenance Contract Unbundling | Recurring revenue streams from IoT-enabled remote diagnostics reduce field technician dispatch costs. |
| Corrosion-Resistant Configuration Development | ANVISA export requirements and tropical humidity conditions in Mato Grosso drive specification divergence. |
| Sanitary Design Validation Investment | FDA food safety modernization rules extend commissioning timelines for retail-facing food processors. |
| Regional Service Architecture Reconfiguration | Brazilian wet milling expansion forces equipment suppliers to localize technical support capabilities. |
Study Parameters
Cross-validation between equipment procurement databases and regulatory filing records anchors the qualitative findings in documented capital allocation patterns. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combine with secondary validation from EPA enforcement data, FDA facility registration records, SEC 10-K capital expenditure disclosures, and customs trade statistics. Bottom-up and top-down triangulation reconciles segment-level equipment shipments with aggregate processing capacity expansion.
Calibration against historical replacement cycle data and documented capacity utilization rates validates projection assumptions across the analysis window. Segmentation dimensions modeled include product type configuration, end-use application, capacity tier, and technology automation intensity. CAGRs derive from equipment shipment trajectories and processing capacity buildout correlations. Industry-specific forecast inputs incorporate EPA blending mandate enforcement patterns and Brazilian ethanol plant commissioning schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian fabricators into precision roller mill segments would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Cassava Processing Market