
 Australia Forage Seed Market | 2026-2036
Australia Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Forage Seed Market Outlook
Agronomist and plant-breeding specialist shortages across rural Australia is redrawing competitive dynamics among seed suppliers. DLF Seeds leverages its Danish breeding heritage to sustain premium perennial ryegrass lines suited to temperate dairy zones. Heritage Seeds anchors southern Australian market presence through region-specific lucerne and clover portfolios. Selected Seeds competes on price-accessible pasture blends tailored to mixed farming operations in Queensland and northern New South Wales.
Australia forage seed comprises genetically improved propagules of grasses, legumes, cereals, and herbs selected for germination vigor, nutritive value, and persistence under grazing pressure. These seeds undergo certified multiplication through foundation seed programs governed by seed certification schemes to ensure genetic purity and weed-seed limits before commercial sale. Grass seeds occupy the largest product category share, reflecting entrenched dairy pasture systems reliant on perennial ryegrass and fescue establishment. Legume seeds represent the fastest-expanding product type as producers pursue nitrogen-fixing lucerne and clover rotations to reduce synthetic fertilizer dependency. Application through pasture renovation dominates volume flows, while cover crop adoption grows fastest among broadacre farmers integrating multispecies blends for soil carbon accrual.
TGA and APVMA frameworks govern veterinary chemical and agricultural compound standards, though seed quality falls primarily under state-based seed certification aligned with OECD seed schemes and Plant Breeder's Rights protections. Australia's national drought resilience policies and Murray-Darling Basin water planning rules directly influence which forage species gain farmer preference and research funding priority. Stakeholders must monitor evolving carbon farming methodology approvals and water allocation volatility to align seed portfolio development with producer risk profiles.
Market Dynamics
Murray-Darling Basin water allocation volatility is compressing farmer planting windows and forcing seed suppliers to accelerate varietal development cycles. Breeders now face simultaneous pressure from drought resilience mandates and irrigation access uncertainty.
Growth Catalysts
- Carbon Farming Initiative methodologies:Approved soil carbon measurement protocols under Australia's Emissions Reduction Fund incentivize multispecies pasture blends that sequester carbon and qualify for credit generation.
- Dairy processor feed cost pressures:Major milk processors in Victoria and Tasmania are prescribing specific ryegrass-lucerne rotations to reduce purchased grain dependency among supplier farms.
- Plant Breeder's Rights Act modernization:Streamlined varietal registration timelines are accelerating commercial release of drought-tolerant fescue and cocksfoot lines developed through public-private breeding consortia.
Market Restraints
- Foundation seed supply concentration:Certified multiplication programs rely on a narrow eastern Australian seed production belt, exposing commercial flows to localized frost and hail events.
- Synthetic nitrogen price volatility:Global urea and ammonium nitrate cost swings diminish the relative economic advantage of nitrogen-fixing legume rotations during price troughs.
- Seed certification timeline rigidity:OECD-aligned field inspection protocols impose fixed seasonal windows that delay commercialization of biotech-enhanced varieties by 18-24 months.
Strategic Opportunities
- Queensland northern expansion zones:Mixed grazing operations from Darling Downs to Central Highlands show underpenetrated demand for subtropical grass seed blends adapted to lower frost risk.
- Cover crop integration in broadacre wheat systems:South Australian and Western Australian grain farmers are experimenting with multispecies winter cover mixes ahead of summer fallows.
- Water trading market maturation:Permanent water entitlement sales in the southern Murray-Darling are concentrating irrigation access among larger dairy operations capable of premium perennial pasture investment.
Industry Challenges
- Rural agronomist workforce gaps:Regional extension services struggle to recruit pasture specialists capable of prescribing complex rotation schedules across diverse soil types.
- Genetic purity verification costs:PCR-based trait confirmation and field isolation distances for certified seed production require capital-intensive infrastructure upgrades.
- Climate adaptation breeding lag:Conventional selection cycles for perennial species outpace the velocity of rainfall pattern shifts in Mediterranean climate zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Forage Seed Market |
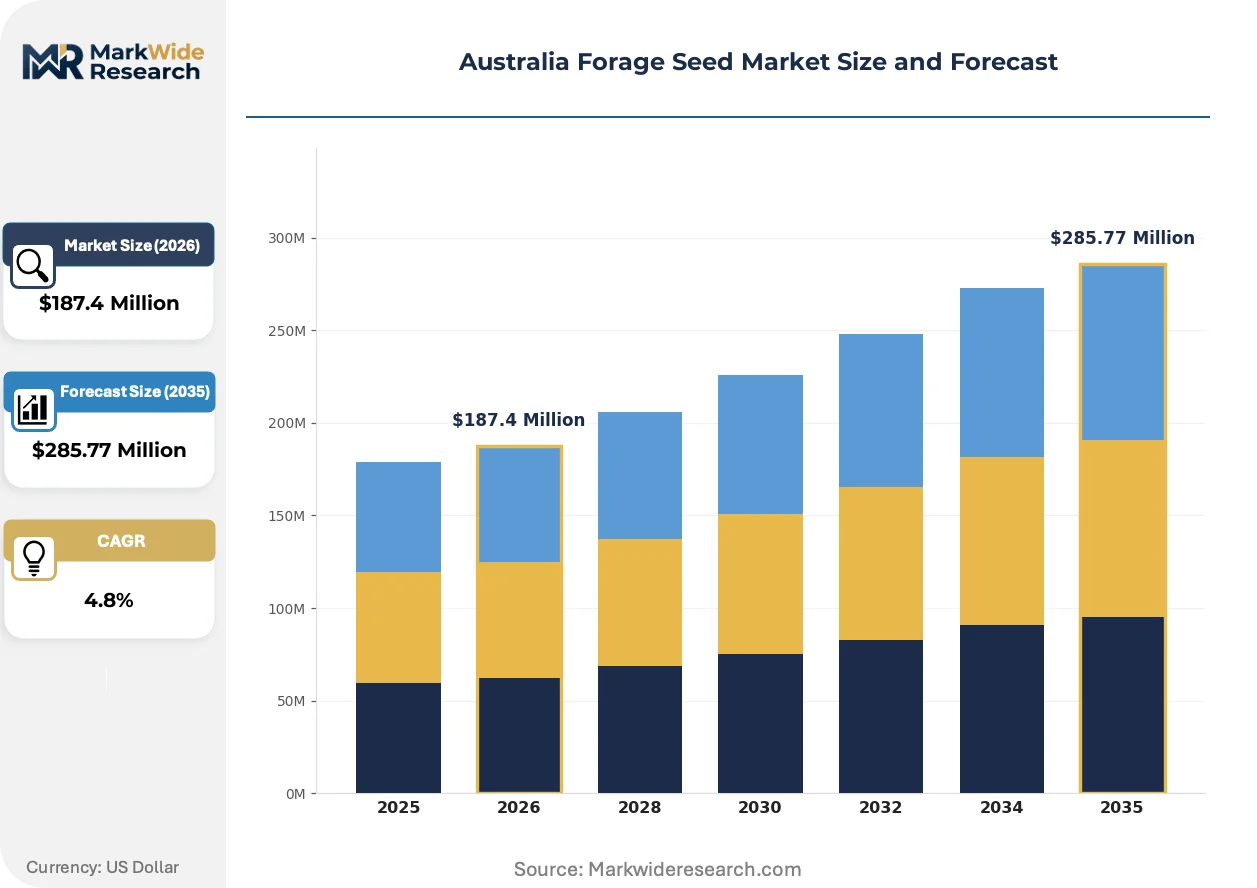
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grass Seeds, Legume Seeds, Cereal Seeds, Herb Seeds Application: Pasture, Green Manure, Cover Crop, Erosion Control End User: Farmers, Agricultural Cooperatives, Lawn Care Companies, Government Agencies Distribution Channel: Online Retail, Agricultural Supply Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | DLF Seeds, Selected Seeds, Corteva Agriscience, KWS SAAT SE & Co. KGaA, RAGT, Barenbrug, Heritage Seeds, Valley Seeds Pty Ltd, S&W Seed Company Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Forage Seed Market Strategic Shifts
Genomic selection tools and on-farm sensor networks are collapsing the feedback loop between breeding trials and commercial performance data. These technologies are redrawing how varietal recommendations reach end-users.
Genomic prediction platforms are decomposing traditional multi-year field trial requirements by enabling early-generation selection based on marker-trait associations. Dairy cooperatives in Gippsland and southwest Victoria are piloting these tools to match ryegrass cultivars to specific farm microclimates. The technology is decomposing the historical reliance on broad regional adaptation ratings in favor of precision-matched varietal prescriptions.
Australia's national drought resilience framework and associated research funding pools are redirecting public breeding investment toward deep-rooted perennial species. State agriculture departments in New South Wales and Victoria are reallocating variety evaluation resources to prioritize water-use efficiency metrics over raw yield benchmarks. This policy pivot most affects lucerne and phalaris breeding programs targeting marginal rainfall zones.
Direct seed procurement relationships between large pastoral companies and breeding houses are displacing traditional merchant distribution layers. Corporate beef operations in northern Australia and dairy aggregators in Tasmania are negotiating multi-year varietal development agreements that bypass regional seed retailers. This channel compression is most visible in high-volume perennial ryegrass contracts where volume certainty justifies dedicated production runs.
Australia Forage Seed Market Segmentation
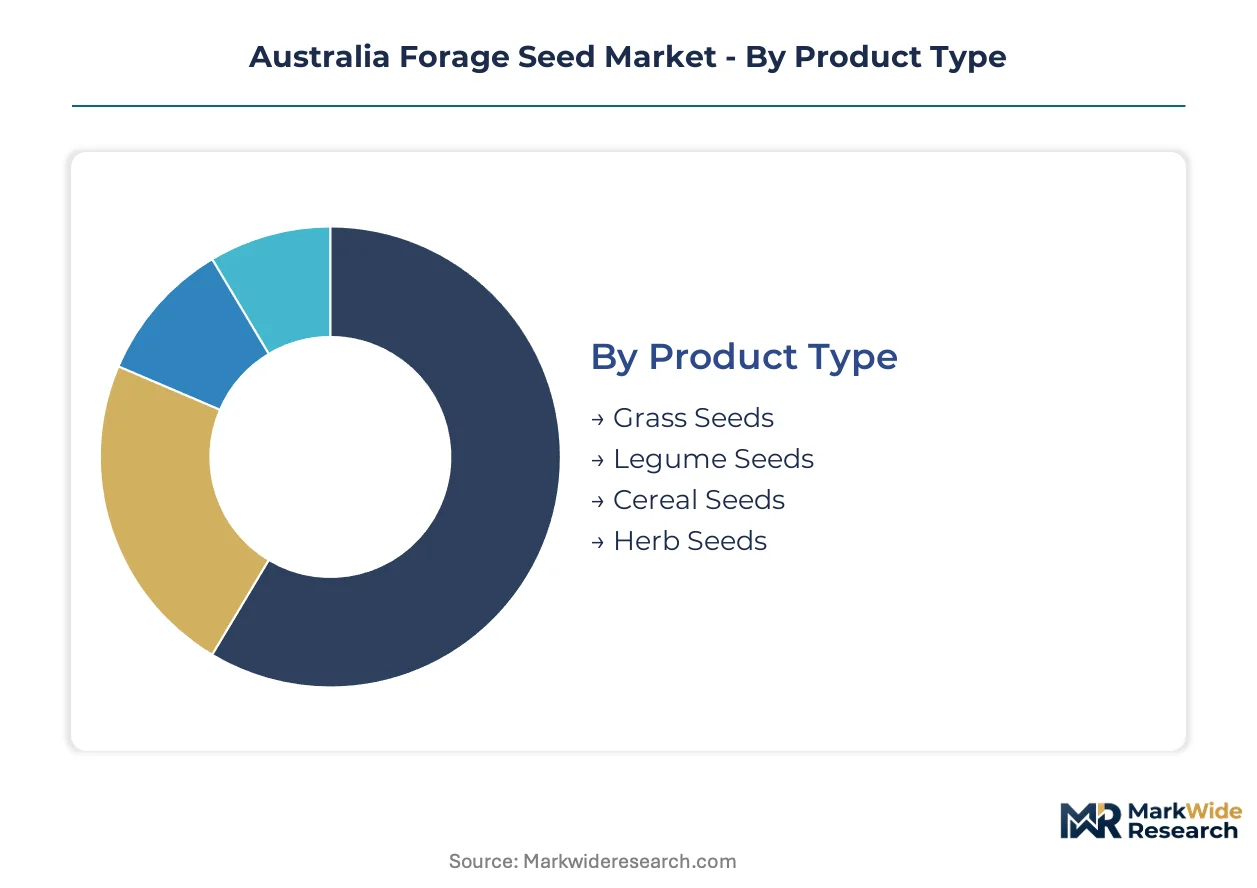
Segmentation in the Australia forage seed market reveals how producer priorities diverge across climate zones and enterprise scales. Product portfolios must align with Murray-Darling water variability and carbon farming incentive structures to capture margin.
Product Type:
Margin pools concentrate in perennial species commanding multi-year stand persistence premiums from dairy and beef operators.
- Grass Seeds:Perennial ryegrass and tall fescue dominate certified seed multiplication programs, with germination vigor standards exceeding 85% under OECD protocols. Victorian and Tasmanian dairy zones drive premium pricing for endophyte-enhanced cultivars that reduce heat stress livestock disorders. Grass seeds hold installed capacity.
- Legume Seeds:Lucerne and clover varieties deliver nitrogen fixation valued at synthetic fertilizer replacement rates, with stand longevity spanning 3-5 years in rotational systems. Southern New South Wales irrigation districts show strongest uptake as water entitlement trading concentrates access among larger operations. Legume seeds are rotating up the share rankings.
- Cereal Seeds:Oats and annual ryegrass serve dual-purpose grain-forage systems across mixed farming enterprises from Wagga Wagga to Dubbo.
- Herb Seeds:Chicory and plantain feature in multispecies pasture blends targeting soil carbon accrual under Emissions Reduction Fund methodologies.
Cereal and herb varieties expand most quickly as broadacre farmers integrate cover crop rotations ahead of summer fallows.
Application:
Application choice tracks water security and enterprise type across Australia's agricultural zones.
- Pasture:Permanent and rotational pasture establishment consumes the majority of certified seed volume, with renovation cycles triggered by stand decline thresholds of 60% ground cover. Gippsland and southwest Victorian dairy regions specify ryegrass-lucerne rotations in processor supply agreements. Pasture holds installed capacity.
- Green Manure:Vetch and field pea biomass crops precede cash grain plantings in South Australian Mallee districts, with termination timing critical for moisture conservation. Green manure is rotating up the share rankings.
- Cover Crop:Multispecies winter blends combining brassicas, legumes, and cereals gain traction in Western Australian wheatbelt systems seeking soil biology enhancement.
- Erosion Control:Phalaris and native grass revegetation programs align with Murray-Darling Basin environmental water recovery targets on riparian corridors.
Cover crop adoption climbs the fastest as carbon farming methodology approvals validate soil carbon measurement protocols.
End User:
Customer scale determines procurement channel preference and technical service intensity requirements.
- Farmers:Individual grazing enterprises from 200 to 2,000 hectares dominate volume consumption, with seed selection decisions influenced by regional agronomist recommendations and processor feed cost reduction programs. Farmers hold installed capacity.
- Agricultural Cooperatives:Member-owned buying groups aggregate demand across 50-150 farm operations, negotiating varietal development agreements that bypass traditional merchant distribution. Agricultural cooperatives are rotating up the share rankings.
- Lawn Care Companies:Turf establishment contractors source certified tall fescue and Kentucky bluegrass for sports field and amenity plantings in metropolitan Melbourne and Sydney corridors.
- Government Agencies:State agriculture departments and catchment management authorities procure native grass and legume seed for public land rehabilitation and biodiversity offset programs.
Government procurement expands most quickly as national drought resilience policies redirect public breeding investment toward marginal rainfall zone adaptation.
Distribution Channel:
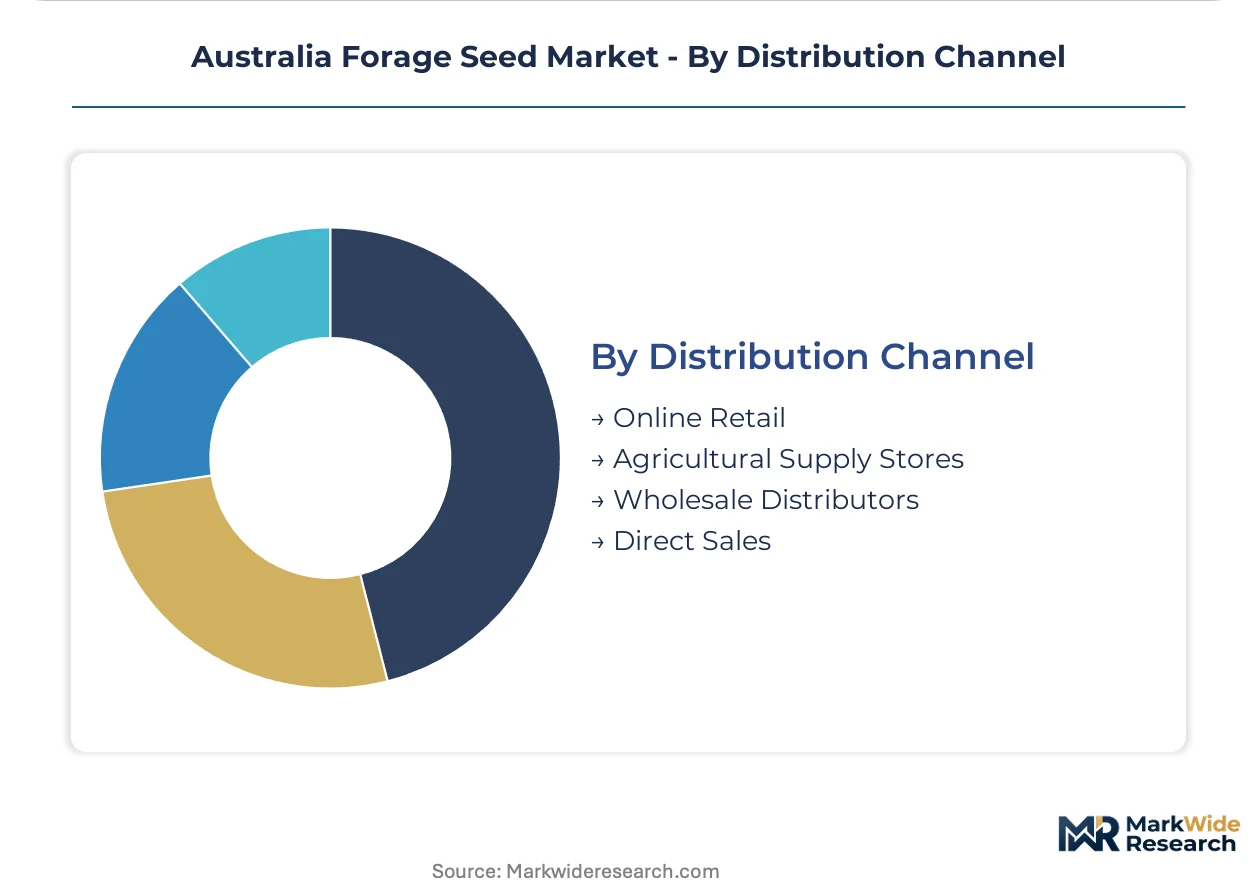
Channel structure reflects seed certification requirements and the technical complexity of varietal matching to soil and climate conditions.
- Agricultural Supply Stores:Regional merchandisers in Wagga Wagra, Tamworth, and Shepparton maintain certified seed inventories with foundation seed documentation traceable to OECD field inspection records. Agricultural supply stores hold installed capacity.
- Direct Sales:Large pastoral companies and dairy aggregators negotiate multi-year supply contracts with breeding houses, compressing traditional distribution layers for high-volume perennial ryegrass agreements. Direct sales are rotating up the share rankings.
- Wholesale Distributors:State-level aggregators manage certified seed logistics from eastern Australian multiplication zones to regional retail networks.
- Online Retail:E-commerce platforms serve small-scale lifestyle block owners and hobby farmers with packaged pasture blends, though certified seed documentation requirements limit penetration in commercial segments.
Online retail gains share fastest among non-commercial producers seeking convenience over technical advisory services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA and state-based seed certification schemes anchor regulatory oversight across Australia's southeastern seed production belt, where Murray-Darling water allocations determine planting economics.
New South Wales
Irrigation-dependent dairy operations along the Murray and Murrumbidgee rivers drive lucerne and perennial ryegrass uptake. NSW Department of Primary Industries administers variety evaluation trials aligned with Plant Breeder's Rights protocols. The Riverina region around Wagga Wagga hosts foundation seed multiplication programs supplying certified propagules to southeastern markets.
Victoria
Gippsland and southwest dairy processors prescribe specific pasture rotations to reduce supplier grain dependency. Agriculture Victoria oversees drought-tolerance breeding consortia targeting Mediterranean rainfall zones. The Wimmera and Western Districts concentrate perennial ryegrass certified seed production under OECD field inspection standards.
Queensland
Mixed grazing enterprises from Darling Downs to Central Highlands show expanding demand for subtropical grass blends adapted to lower frost risk. Queensland Department of Agriculture and Fisheries directs research funding toward summer-active species for northern expansion zones. The Burnett region anchors certified seed multiplication for tropical and subtropical legume varieties.
South Australia
Broadacre wheat farmers in the Mallee and Eyre Peninsula integrate multispecies cover crop mixes ahead of summer fallows. Primary Industries and Regions SA supports soil carbon methodology validation under Emissions Reduction Fund guidelines. The Adelaide Plains maintain limited but strategic lucerne seed production for local dairy and hay markets.
Western Australia
Grainbelt farmers experiment with winter cover crop blends combining brassicas, legumes, and cereals for soil biology enhancement. Department of Primary Industries and Regional Development manages variety adaptation trials for low-rainfall Mediterranean conditions. The Great Southern region hosts emerging perennial pasture seed demand from expanding sheep and beef operations.
Australia Forage Seed Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Australian forage seed market. International breeding houses with multi-decade germplasm libraries command premium positioning in certified perennial lines, while regional distributors compete on price-accessible blends for mixed farming operations. The market structure stratifies into three archetypes: multinational breeders with proprietary cultivars, national distributors with region-specific portfolios, and direct-contract specialists serving corporate pastoral aggregators. Competitive moves center on varietal development agreements that compress traditional merchant channels and state-level seed certification infrastructure investments that lock in multiplication capacity.
Among multinational breeders, DLF Seeds and Corteva Agriscience occupy positions representing premium-tier technology access, while Heritage Seeds and Selected Seeds exemplify national distributors with state-level adaptation focus. Valley Seeds Pty Ltd represents the direct-contract specialist archetype serving large-scale pastoral operations.
| Leading Market Players |
|---|
| DLF Seeds |
| Selected Seeds |
| Corteva Agriscience |
| KWS SAAT SE & Co. KGaA |
| RAGT |
| Barenbrug |
| Heritage Seeds |
| Valley Seeds Pty Ltd |
| S&W Seed Company Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
OECD-aligned seed certification schemes gate both supply qualification and price differentiation simultaneously in Australian forage seed markets. TGA and state-based protocols enforce genetic purity standards that stratify commercial tiers, while Plant Breeder's Rights protections enable endophyte-enhanced cultivars to command persistence premiums from Victorian dairy operators.
Pricing Analysis
Price spreads between Riverina foundation seed and Queensland retail channels exceed transport and certification cost differentials alone. Three-tier pricing structure across premium, standard, and economy levels reflects germination vigor thresholds and endophyte status, with certified perennial ryegrass lines from Wimmera multiplication zones capturing brand premiums. Cost compression in economy pasture blends is intensifying because northern mixed farmers substitute uncertified farm-saved seed during drought recovery periods. Small-scale lifestyle block owners exhibit highest price sensitivity, while Tasmanian dairy aggregators prioritize stand longevity over per-kilogram seed costs.
Supply Chain Analysis
Australia anchors certified seed multiplication for temperate perennial species, with foundation seed production concentrated across New South Wales Riverina, Victorian Wimmera, and Tasmanian irrigation districts. Commercial flows draw from narrow eastern Australian multiplication belts, exposing volumes to localized frost and hail events. Single-source vulnerability concentrates in lucerne seed cleaning and PCR-based trait verification infrastructure. Distribution runs through agricultural supply stores in regional hubs, with direct sales channels compressing traditional wholesale layers for corporate pastoral contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon farming methodology approvals are transforming forage seed procurement into an ecosystem-coordination platform, where seed suppliers must integrate with soil carbon auditors and processor feed programs to capture margin.
For Market Incumbents: Shield certified seed market share by deepening backward integration into foundation seed multiplication capacity across multiple eastern Australian climate zones. Accelerate varietal development agreements with dairy cooperatives that prescribe specific rotation schedules, insulating premium perennial lines from price-accessible blend competition. Prioritize PCR-based genetic purity infrastructure investments that lock in OECD certification capacity.
For New Entrants and Emerging Players: Lead with subtropical grass seed portfolios targeting Queensland's Darling Downs-to-Central Highlands corridor, where frost-risk adaptation creates white-space demand unmet by temperate-focused incumbents. Pursue cover crop blend development for South Australian and Western Australian broadacre wheat systems, positioning multispecies mixes ahead of carbon methodology validation cycles. Build go-to-market relationships directly with agricultural cooperatives that aggregate demand across member farms.
For Investors and Strategic Acquirers: Plant Breeder's Rights Act modernization reshapes the acquisition landscape by accelerating commercial release timelines for drought-tolerant varieties. Target breeding houses with established public-private consortia relationships and deep-rooted perennial germplasm libraries positioned for Murray-Darling water volatility. Watch for inflection signals in permanent water entitlement trading volumes that concentrate irrigation access among premium pasture investors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundation Seed Multiplication | Captures OECD certification capacity in Riverina and Wimmera production zones. |
| Varietal Development Agreement with Dairy Cooperatives | Locks in multi-year perennial ryegrass demand from Gippsland processor supply chains. |
| Carbon Farming Methodology Alignment | Qualifies multispecies blends for Emissions Reduction Fund credit generation. |
| Subtropical Portfolio Expansion | Addresses underpenetrated Queensland mixed grazing demand with lower frost-risk cultivars. |
| Direct Channel Compression | Bypasses agricultural supply store layers for high-volume corporate pastoral contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed certification officers, plant breeding program directors, dairy processor agronomists, agricultural cooperative procurement managers, and broadacre farm advisors. Secondary validation drew from OECD seed scheme documentation, APVMA agricultural compound registers, Murray-Darling Basin water trading data, and state agriculture department variety evaluation trial records. Bottom-up acreage and seeding rate estimates were triangulated against top-down certified seed production volumes.
Across the analysis window, forecasts were constructed through segmented modeling across product type, application, end user scale, and distribution channel dimensions. CAGRs were derived from historical certified seed multiplication trends, irrigation access projections, and carbon farming adoption curve assumptions. Industry-specific inputs included Plant Breeder's Rights registration timelines, drought resilience policy funding allocations, and processor feed cost reduction program specifications.
The analysis sits within stated boundaries; outcomes outside sustained Murray-Darling water allocation volatility or accelerated carbon methodology approval would require recalibration. Forecasts reflect assumptions regarding varietal development cycle compression and agronomist workforce availability. Recalibration cycles align with material shifts in national drought resilience policy frameworks and water entitlement trading market structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Vietnam Seed Market
Seeds
China Forage Seed Market
Seeds
United States Forage Seed Market
Seeds
Africa Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Rapeseed Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Americas Seeds Market
Seeds
Grass Seed Market
Seeds
Ghana Seeds Market
Seeds
Garden Seeds Market
Seeds
Australia Oilseed Market
Seeds
Mustard Seeds Market
Seeds
Helianthus Annuus (Sunflower) Market