
 Global Intelligent Steering System Market | 2026-2036
Global Intelligent Steering System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Steering System Market Intelligence
The substitution of complex mechanical linkages with software-defined control logic is repositioning the value chain for intelligent steering systems. Robert Bosch GmbH leverages its deep expertise in automotive electronics and software to deliver highly integrated system solutions. ZF Friedrichshafen AG competes strongly in the commercial vehicle space with its robust electro-hydraulic power steering products. Nexteer Automotive specializes in advanced electric power steering for a diverse range of passenger vehicles, anchoring its position through R&D in torque sensor technology.
An intelligent steering system automates or assists vehicle directional control using electronic control units, sensors, and actuators. These systems process inputs from torque sensors and vehicle dynamics data to execute precise steering adjustments via adaptive control algorithms. Electric Power Steering represents the dominant component type due to its energy efficiency and seamless integration with ADAS functions. While passenger cars constitute the largest vehicle type segment, heavy-duty trucks are showing the fastest uptake for these advanced systems.
Safety mandates from bodies like the NHTSA in the United States and under the EU's General Safety Regulation drive the integration of steer-by-wire functionalities. Concurrently, technical standards from China's MIIT influence component design and interoperability for the world's largest automotive market. Suppliers must now decide whether to compete as full-system integrators or as specialized providers of high-value sensor and software modules.
Market Dynamics
The fundamental replacement of mechanical steering linkages with software-defined control logic is the central force shaping the market. This technological pivot shifts value from traditional hardware manufacturing to expertise in systems integration, sensor fusion, and adaptive control algorithms.
Growth Catalysts
- Regulatory Mandates:Safety requirements under the EU's General Safety Regulation and from the NHTSA in the US compel the integration of ADAS features like lane-keeping assist, directly driving the adoption of intelligent steering systems that enable these functions.
- Commercial Vehicle Efficiency:The heavy-duty truck segment shows rapid uptake, driven by the need for improved fuel economy through optimized steering control and advanced driver assistance to reduce operator fatigue on long-haul routes.
- Electric Power Steering Dominance:As the foundational component, Electric Power Steering (EPS) offers superior energy efficiency over hydraulic systems and provides the necessary electronic interface for seamless integration with modern ADAS sensor suites and control units.
Market Restraints
- High System Complexity and Cost:The integration of redundant sensors, powerful electronic control units, and fail-operational actuators significantly increases the bill of materials and development costs, posing a barrier for adoption in cost-sensitive vehicle segments.
- Cybersecurity and Functional Safety:Steer-by-wire systems, which lack a direct mechanical link, face immense scrutiny regarding their vulnerability to cyber-attacks and the challenge of guaranteeing functional safety under all fault conditions, slowing deployment.
- Semiconductor Supply Constraints:The market's dependency on a concentrated group of suppliers for automotive-grade microcontrollers and specialized torque sensors creates supply chain vulnerabilities and potential production bottlenecks for steering system manufacturers.
Strategic Opportunities
- Software-Defined Vehicles:The shift toward software-defined vehicle architectures creates an opportunity for suppliers to offer scalable steering platforms where functionality, such as enhanced parking assists or performance modes, can be activated post-sale via over-the-air updates.
- Off-Highway Automation:Significant white space exists in applying intelligent steering to agricultural and construction vehicles, where precision guidance can yield major improvements in operational efficiency, resource usage, and automation capabilities.
- Vehicle Dynamics Integration:There is a growing opportunity to merge intelligent steering control with active suspension and braking systems, creating a unified vehicle dynamics control module that can deliver superior handling, stability, and safety performance.
Industry Challenges
- Legacy System Integration:Integrating advanced intelligent steering systems into existing vehicle platforms with legacy electrical and electronic architectures often requires costly and time-consuming redesigns, delaying widespread implementation across all models.
- Specialized Engineering Talent:A persistent shortage of software and systems engineers with dual expertise in mechatronics and functional safety standards, such as ISO 26262, hampers development and validation timelines for safety-critical steering applications.
- Interoperability Standardization:The absence of a universal standard for communication protocols between steering ECUs, sensors, and other vehicle domain controllers from different vendors complicates system integration for automakers and limits component interchangeability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Steering System Market |
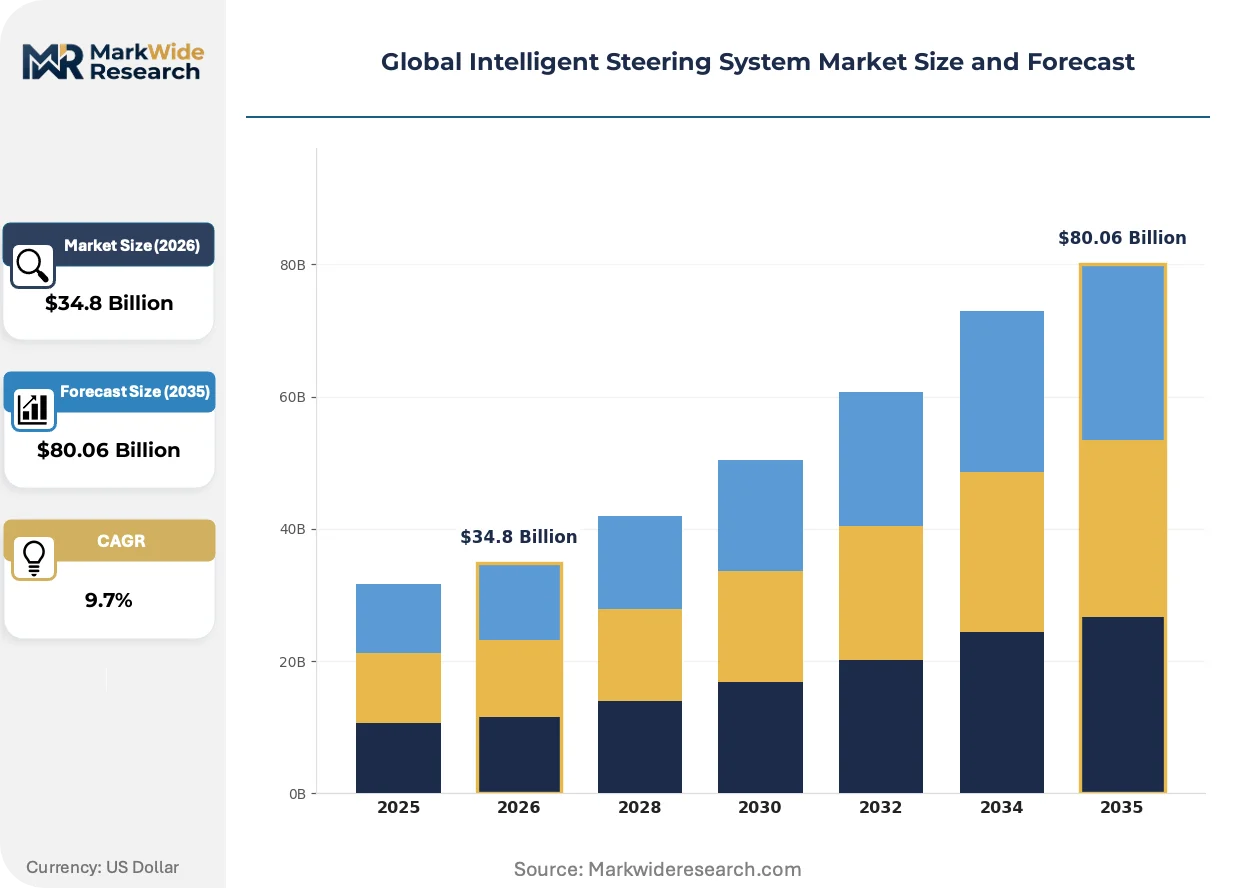
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $80.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Electric Power Steering, Hydraulic Power Steering, Electro-Hydraulic Power Steering, Active Steering, Variable Gear Ratio Steering Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, Buses, Construction Equipment Technology: Sensor Integration, Torque Feedback, Autonomous Steering, Real-Time Data Processing, Adaptive Control Algorithms End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Manufacturers, Fleet Operators |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, Robert Bosch GmbH, ZF Friedrichshafen AG, NSK Ltd, Mando Corporation, Showa Corporation, Hyundai Mobis, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Steering System Market Strategic Shifts & Innovations
The competitive landscape is being reshaped by the elevation of software as the primary differentiator. Value is migrating from the mechanical precision of hardware to the sophistication of the control algorithms and the system's ability to integrate with the vehicle's broader digital ecosystem.
Adaptive control algorithms, the software brain of the system, process a continuous stream of data from torque sensors and vehicle dynamics inputs. While first proven in luxury passenger cars, adoption is accelerating in heavy-duty trucks and mid-range vehicle segments. This software capability is expanding into new business models, enabling feature-on-demand subscriptions for advanced driver-assistance functions.
Regulations from China's MIIT are establishing specific technical standards for the performance and data security of intelligent vehicle components. This action directly influences system design, compelling global suppliers to ensure their steering modules meet stringent GB standards for interoperability and cybersecurity. The passenger car segment is most impacted, as compliance is a prerequisite for access to the world's largest automotive market.
Automaker purchasing criteria now prioritize a steering system's capacity for over-the-air (OTA) software updates and its potential for future feature enhancement. This change disrupts the traditional one-time hardware sale, shifting focus to the supplier's software roadmap and ability to support the vehicle's digital lifecycle. This trend is particularly pronounced in the electric vehicle sector, where software-enabled features are a key competitive battleground.
Global Intelligent Steering System Market Segmentation
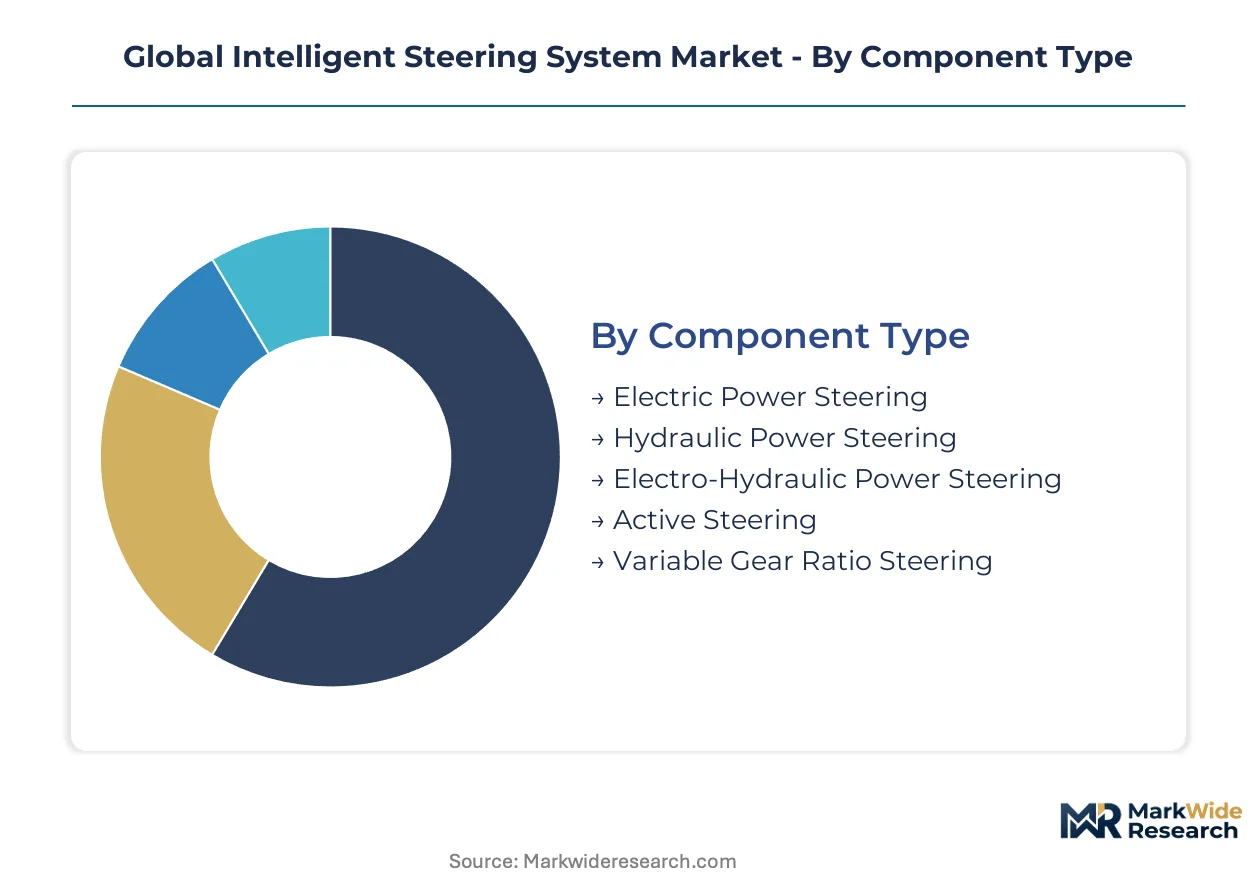
The intelligent steering system market dissects into distinct segments, reflecting varied technological sophistication, vehicle applications, and end-user requirements. Understanding these segmentations reveals where value accumulates and how different system architectures cater to specific operational demands across the automotive landscape.
Component Type:
This category highlights how integration depth influences system design, differentiating between standalone mechanical components and deeply embedded electronic control units.
- Electric Power Steering:This dominant component type replaces hydraulic pumps with an electric motor, offering superior energy efficiency, reduced parasitic losses, and seamless electronic integration with advanced driver-assistance systems. Demand concentrates in passenger cars and light commercial vehicles, driven by fuel economy mandates and ADAS proliferation.
- Active Steering:This advanced system dynamically adjusts the steering ratio based on vehicle speed and driver input, enhancing maneuverability at low speeds and stability at high speeds through a planetary gearset. Luxury passenger vehicles in Germany and South Korea primarily drive demand for this performance-oriented technology.
- Hydraulic Power Steering:This traditional system uses hydraulic fluid pressurized by an engine-driven pump to assist steering, providing robust operation but with lower energy efficiency and limited electronic integration capabilities.
- Electro-Hydraulic Power Steering:Combining hydraulic assistance with an electric pump, this system offers a compromise between traditional hydraulics and full EPS, improving efficiency over HPS while retaining some hydraulic benefits.
- Variable Gear Ratio Steering:This mechanical system alters the steering ratio non-linearly, providing quicker steering response at low speeds and more relaxed control at high speeds, often found in performance-oriented vehicles.
Electric Power Steering leads volumes today; Active Steering is gaining share fastest.
Vehicle Type:
This segmentation illustrates how intelligent steering systems are adapted for different operational environments and performance expectations across various vehicle platforms.
- Passenger Cars:This segment represents the largest volume market for intelligent steering systems, driven by consumer demand for comfort, safety features, and the widespread integration of ADAS functionalities. Global automotive manufacturing centers, including Germany and South Korea, show high adoption rates.
- Heavy-Duty Trucks:Intelligent steering systems in this segment focus on reducing driver fatigue, enhancing stability for large loads, and improving fuel efficiency through optimized steering control. The need for operational cost reduction drives demand in long-haul logistics fleets.
- Light Commercial Vehicles:These vehicles benefit from improved maneuverability in urban environments and enhanced driver comfort during frequent stops and starts, making intelligent steering a valuable upgrade for delivery and service fleets.
- Buses:Intelligent steering systems in buses contribute to improved handling, reduced driver effort, and enhanced safety for passenger transport, particularly in urban and intercity routes.
- Construction Equipment:Precision guidance and improved operator control for heavy machinery, such as excavators and loaders, represent a growth area for intelligent steering, enhancing efficiency on job sites.
Passenger Cars command the largest market share; Heavy-Duty Trucks are expanding most quickly.
Technology:
This category delineates the core technological underpinnings that enable intelligent steering functionality, from data acquisition to dynamic control execution.
- Adaptive Control Algorithms:These software components represent the brain of intelligent steering systems, processing real-time data to dynamically adjust steering parameters for optimal vehicle response, stability, and driver assistance. Their sophistication is a key differentiator for premium systems.
- Sensor Integration:This foundational technology involves incorporating various sensors, such as torque, speed, and yaw rate sensors, to provide the electronic control unit with comprehensive data on vehicle dynamics and driver input. The quality and redundancy of sensor integration are critical for functional safety.
- Torque Feedback:This technology provides tactile information to the driver about road conditions and vehicle behavior through the steering wheel, enhancing driver feel and control, especially in electric power steering systems.
- Real-Time Data Processing:The ability of the electronic control unit to instantaneously analyze inputs from multiple sensors and execute steering commands is crucial for the responsiveness and safety of intelligent steering systems.
- Autonomous Steering:This advanced capability allows the vehicle to execute steering maneuvers without direct driver input, forming a core component of higher-level autonomous driving systems.
Sensor Integration provides the foundational data; Adaptive Control Algorithms define system performance.
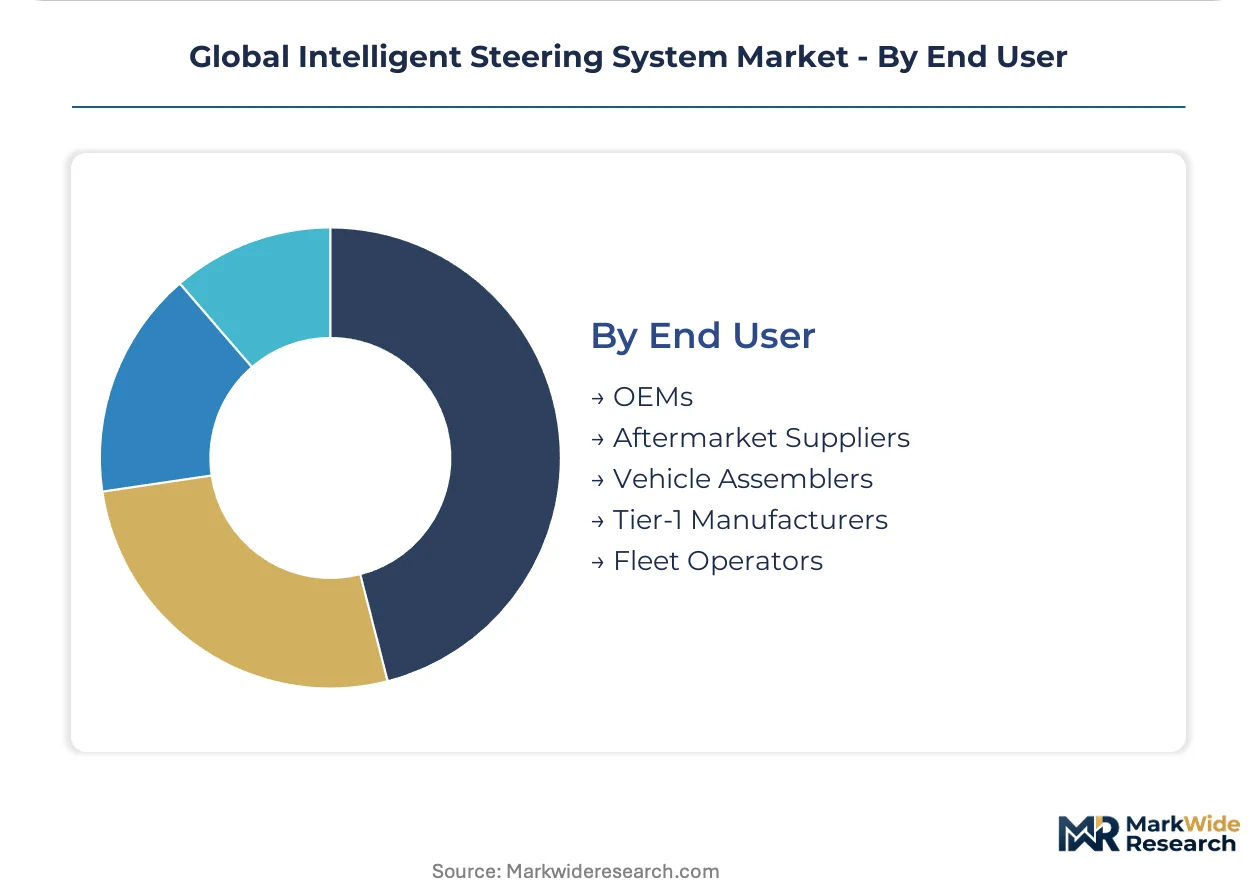
End User:
This segmentation highlights the primary stakeholders procuring and integrating intelligent steering systems, from original equipment manufacturers to fleet operators.
- OEMs:Original Equipment Manufacturers integrate intelligent steering systems directly into new vehicle production lines, often working closely with Tier-1 suppliers to develop customized solutions that meet specific vehicle platform requirements. These include major automakers in Germany and South Korea.
- Tier-1 Manufacturers:These companies design, develop, and supply complete intelligent steering system modules or major sub-assemblies to OEMs, often holding significant intellectual property in core technologies like electric power steering and torque sensors. Robert Bosch GmbH and Nexteer Automotive exemplify this segment.
- Aftermarket Suppliers:These entities provide replacement parts, upgrades, or specialized intelligent steering components for vehicles already in operation, catering to repair, customization, or performance enhancement needs.
- Vehicle Assemblers:These companies focus on the final assembly of vehicles, integrating various components supplied by OEMs and Tier-1 manufacturers to produce finished automobiles.
- Fleet Operators:Businesses managing large fleets of vehicles, particularly in commercial transport, procure intelligent steering systems for their benefits in fuel efficiency, driver comfort, and safety across their operational vehicle base.
OEMs represent the largest procurement channel; Fleet Operators are expanding their adoption footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturing centers concentrate demand for intelligent steering systems, driving innovation and adoption across the global market. These advanced systems are crucial for enhancing vehicle safety, improving fuel efficiency, and enabling advanced driver-assistance features. The regional landscape reflects varied regulatory pressures and distinct market needs, influencing technology deployment.
Germany
German automakers prioritize intelligent steering systems for luxury passenger vehicles and high-performance cars, driven by consumer expectations for advanced ADAS. The EU's General Safety Regulation mandates features like lane-keeping assist, directly integrating these systems into new models. Stuttgart, a prominent automotive hub, sees significant research and development investments in sophisticated steering control algorithms.
South Korea
Seoul-based manufacturers focus on integrating intelligent steering into both passenger cars and electric vehicles, aiming for enhanced driving comfort and efficiency. National automotive safety standards and government initiatives promote the adoption of advanced vehicle technologies. The Gyeonggi Province, surrounding Seoul, serves as a key cluster for automotive component suppliers and R&D centers.
United States
The National Highway Traffic Safety Administration (NHTSA) mandates ADAS features, compelling the integration of intelligent steering systems in passenger cars and heavy-duty trucks. Demand for improved fuel efficiency and reduced driver fatigue drives uptake in commercial fleets. Detroit, Michigan, remains a pivotal automotive hub, with major OEMs and Tier-1 suppliers advancing steering system development.
China
China's Ministry of Industry and Information Technology (MIIT) influences component design and interoperability through stringent technical standards for intelligent vehicle components. The world's largest automotive market sees rapid adoption across passenger cars and electric vehicles. Shanghai, a major manufacturing and innovation center, leads in the production and integration of advanced steering solutions.
Global Intelligent Steering System Market Key Industry Players
Strategic partnerships dominate the current landscape, as companies seek to combine expertise in hardware, software, and systems integration. The market exhibits a tiered structure, with established automotive suppliers alongside specialized technology firms. Key archetypes include full-system integrators, specialized software and sensor providers, and traditional mechanical component manufacturers adapting to electronic systems. Portfolio diversification and technology licensing are prevalent competitive moves.
Within the full-system integrator archetype, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify companies leveraging extensive automotive electronics and software capabilities to deliver highly integrated solutions. Nexteer Automotive, a specialist in advanced electric power steering, anchors its position through focused research and development in torque sensor technology. These companies represent the shift toward software-defined control logic, repositioning the value chain in intelligent steering systems.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Mando Corporation |
| Showa Corporation |
| Hyundai Mobis |
| Hitachi Astemo |
| Others |
Cost & Logistics Intelligence
Automotive-grade microcontroller costs directly influence the pricing tiers for intelligent steering systems, impacting downstream OEM procurement. This upstream cost component shapes the overall value proposition from Tier-1 suppliers to vehicle manufacturers.
Pricing Analysis
The pass-through of semiconductor and sensor input costs significantly influences intelligent steering system pricing. Contract-based long-term off-take agreements with major OEMs define the dominant pricing model. Price differentiation stems from the level of ADAS integration and functional safety certification, such as ISO 26262 compliance. Pricing softness reflects intense competition among Tier-1 suppliers and OEM demands for cost optimization. Commercial vehicle fleets exhibit the highest price sensitivity due to their operational expenditure focus, while luxury passenger car manufacturers prioritize performance and feature sets.
Supply Chain Analysis
Single-source vulnerability sits with specialized microcontroller and torque sensor manufacturers, leading to potential production bottlenecks. Geographic supply concentration centers on Taiwan for advanced semiconductors, South Korea for automotive electronics, and Germany for complex mechatronic components. The supply chain relies heavily on automotive-grade microcontrollers, specialized torque sensors, and rare earth elements for electric motors. Geopolitical instability affecting key manufacturing regions represents a critical structural risk. Distribution runs primarily through Tier-1 suppliers delivering integrated modules directly to Original Equipment Manufacturers (OEMs).
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent steering market is transitioning into a late-cycle quality story, with demand shifting toward premium specifications for enhanced driver experience and safety. This evolution requires strategic adjustments across the value chain.
For Market Incumbents:Hedge against the threat of software-centric new entrants by acquiring specialized AI and control algorithm firms. Standardize steering platform architectures to reduce development costs and accelerate integration with diverse vehicle models. Invest heavily in functional safety certification for steer-by-wire systems to maintain a competitive edge. This strategy mitigates margin pressure from OEM cost-cutting and defends market share against agile technology providers.
For New Entrants and Emerging Players:Off-highway vehicle manufacturers represent an underserved buyer archetype for intelligent steering solutions, offering significant white space for innovation. Target construction equipment and agricultural machinery in North America for precision guidance systems. Focus on developing modular, scalable software platforms that can integrate easily with existing vehicle architectures. A value-added software subscription model for advanced functionalities presents a compelling go-to-market angle for these specialized applications.
For Investors and Strategic Acquirers:Consolidation pressure builds where software integration capabilities become the primary value driver, favoring firms with robust intellectual property in adaptive control algorithms. The long-term viability of intelligent steering systems, spanning the next 5-10 years, depends on successful mass adoption of steer-by-wire. Target specialized software IP holders and advanced sensor manufacturers for acquisition. A successful mass production launch of Level 3 autonomous driving features serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | This enhances system flexibility and enables over-the-air updates for new features and performance improvements. |
| Platform Standardization | Streamlining component interfaces reduces integration complexity for OEMs and accelerates time-to-market. |
| Strategic Partnership with Semiconductor Firms | Securing long-term supply of critical automotive-grade microcontrollers mitigates supply chain risks. |
| Acquisition of Specialist Sensor Technology Firms | Integrating advanced torque and vehicle dynamics sensors improves system precision and functional safety. |
| Geographic Manufacturing Footprint Expansion in China | Ensuring compliance with MIIT standards enables access to the world's largest automotive market. |
Research Approach
Multiple input streams — primary interviews, secondary market intelligence, and regulatory filings — were reconciled to construct a comprehensive market view. This involved engaging OEM platform engineers, Tier-1 R&D directors, commercial fleet managers, and ADAS software architects. Secondary data sources included vehicle production databases, automotive component supplier reports, and regulatory body publications from NHTSA and the EU. Both bottom-up and top-down triangulation approaches were applied to validate market sizing and growth projections.
Historical market performance was cross-referenced against expert panel input to establish a robust forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including component type, vehicle type, technology, end-user, and regional adoption patterns. Compound annual growth rates were derived by assessing these factors against anticipated technological advancements and regulatory shifts. Key industry-specific forecast inputs included ADAS penetration rates and electric vehicle production forecasts.
Underlying measurement precision varies by segment; established passenger car and heavy-duty truck segments carry tighter precision than off-highway applications. Forecasts reflect assumptions regarding semiconductor supply chain stability, evolving regulatory mandates, and cybersecurity threat mitigation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Air Springs Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market