
 Automotive Chassis Electronics Market | 2026-2036
Automotive Chassis Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chassis Electronics Market Analysis
German Tier-1 suppliers is decoupling from legacy mechanical chassis production. Bosch Mobility Solutions leverages embedded systems expertise to anchor its position in electronic control units. Continental AG sustains R&D intensity across CAN Bus and LIN Bus architectures. ZF Friedrichshafen AG dominates integrated chassis platforms that merge software with electromechanical actuation.
Automotive chassis electronics encompass the electronic control systems governing vehicle dynamics, stability, and ride management, typically operating across voltage ranges from 12V to 48V with signal processing latencies below 10 milliseconds. These systems translate sensor inputs into real-time actuator commands for braking, steering, and suspension functions, serving the primary purpose of enhancing vehicle safety, handling precision, and energy efficiency. Electronic control units command the largest margin pools as OEMs consolidate multiple chassis functions into domain controllers, while sensors represent the fastest-expanding category due to proliferating axle-load and road-condition monitoring requirements. Embedded systems architecture leads technology adoption, though diagnostic protocols are gaining traction as over-the-air update capabilities become standard.
NHTSA mandates electronic stability control and advanced driver-assistance interoperability, while EPA regulations pressure powertrain control modules to optimize energy recovery. The EU Green Deal and REACH chemical restrictions further shape material selection for wiring harnesses and connectors. Stakeholders must monitor how functional safety standards ISO 26262 and cybersecurity regulations interact with chassis software architectures.
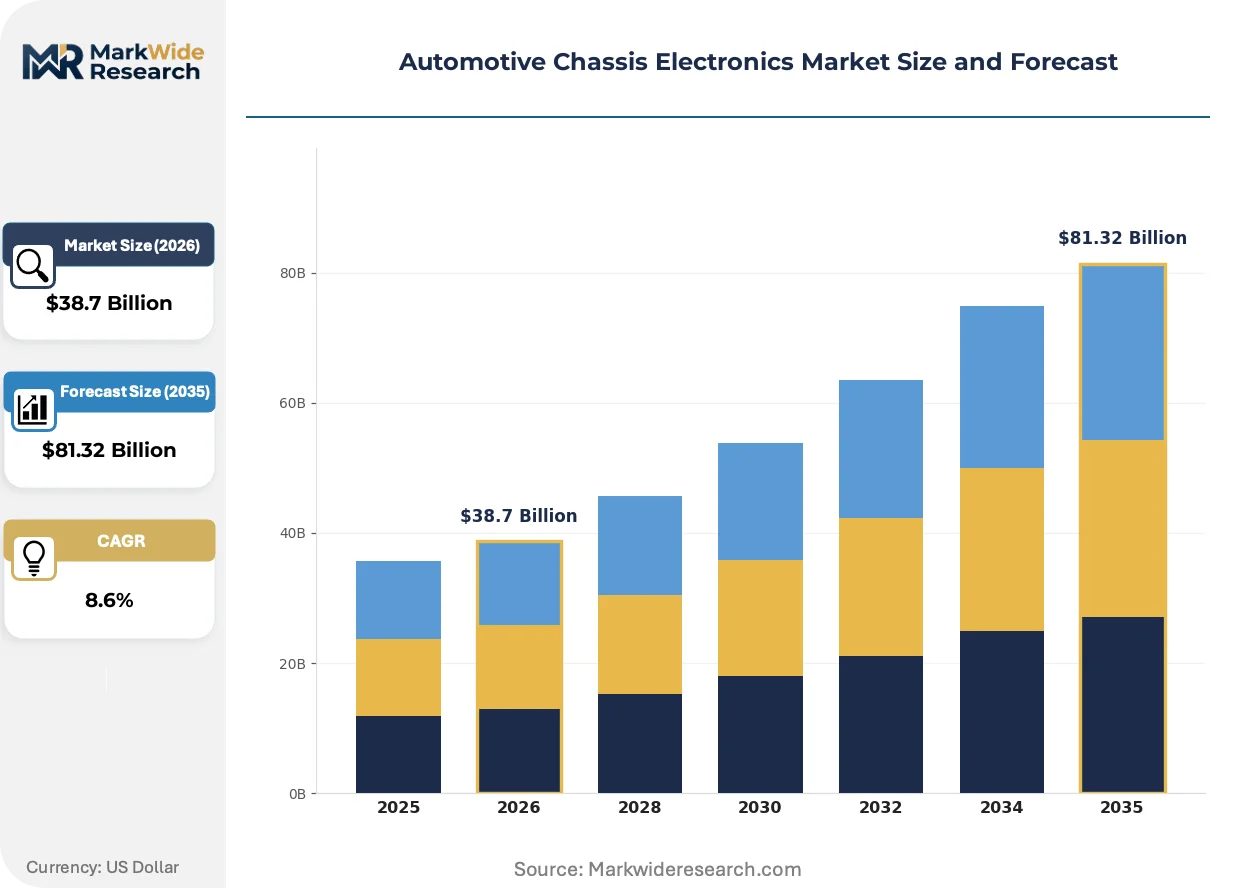
Market Dynamics
OEM consolidation of braking, steering, and suspension functions into centralized domain controllers is compressing supplier tiers and rewriting procurement specifications for chassis electronics.
Growth Catalysts
- EPA emissions standards:Powertrain control modules must optimize regenerative braking energy recovery, mandating sophisticated chassis-integrated electronics across US vehicle platforms.
- 48V electrical architecture:Mild-hybrid platforms require upgraded chassis control systems capable of handling higher voltage loads for electromechanical actuation.
- German OEM R&D clusters:BMW, Mercedes-Benz, and Volkswagen anchor advanced chassis development in Stuttgart, Munich, and Wolfsburg, concentrating supplier engineering resources.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate automotive-grade microcontroller production, creating vulnerability in ECU manufacturing pipelines.
- ISO 26262 compliance costs:Functional safety certification for ASIL-D rated chassis systems demands extensive validation testing that extends development timelines.
- Copper and rare earth price volatility:Wiring harnesses and permanent magnet actuators face input cost instability that compresses component margins.
Strategic Opportunities
- India automotive production:Maruti Suzuki, Tata Motors, and Mahindra are expanding domestic chassis electronics sourcing as PLI scheme incentives localize supply chains.
- Over-the-air update infrastructure:Chassis software architectures that support remote calibration create recurring service revenue streams disconnected from hardware sales cycles.
- China NEV platform standardization:MIIT mandates for unified vehicle operating systems enable chassis electronics suppliers to design once for multiple domestic OEMs.
Industry Challenges
- Embedded cybersecurity engineering:UN R155 vehicle cybersecurity regulations require chassis ECU architects to build intrusion detection and secure boot protocols from silicon level.
- Legacy LIN Bus integration:Cost-sensitive vehicle segments still deploy 20-year-old communication architectures that resist migration to Ethernet-based backbone networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chassis Electronics Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Control Units, Sensors, Wiring Harnesses, Connectors Technology: Embedded Systems, CAN Bus, LIN Bus, Diagnostic Protocols End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Manufacturers Application: Safety Systems, Comfort Features, Infotainment Systems, Powertrain Control |
| Companies Covered | Bosch Mobility Solutions, Denso Corporation, Continental AG, Magna International, ZF Friedrichshafen AG, Aptiv PLC, Hyundai Mobis, Delphi Technologies, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chassis Electronics Market Emerging Trajectories
Software-defined vehicle architectures are dissolving the boundary between chassis hardware and digital control layers, enabling functional upgrades through firmware rather than component replacement.
Steer-by-wire systems eliminate mechanical steering columns entirely, replacing them with electronic signal paths and redundant actuator motors. Premium OEMs in Germany and Japan are deploying these architectures on dedicated EV platforms first. This technology is integrating chassis and ADAS domains into unified motion control stacks that reduce part count while expanding feature flexibility.
NHTSA's updated FMVSS 126 stability control mandates now require interoperability with automatic emergency braking systems, forcing chassis ECU suppliers to open proprietary communication protocols. The regulation compresses development cycles as OEMs must certify integrated systems rather than standalone components. Heavy-duty truck segments face the steepest compliance burden due to payload-variable dynamics algorithms.
Fleet operators now specify chassis electronics by total cost of ownership metrics rather than unit procurement price, weighting predictive maintenance and energy efficiency in selection criteria. Tier-1 suppliers are responding with sensor-rich platforms that feed telematics data directly to fleet management systems. This pattern is most pronounced in North American long-haul trucking and European last-mile delivery vehicle categories.
Automotive Chassis Electronics Market Segmentation
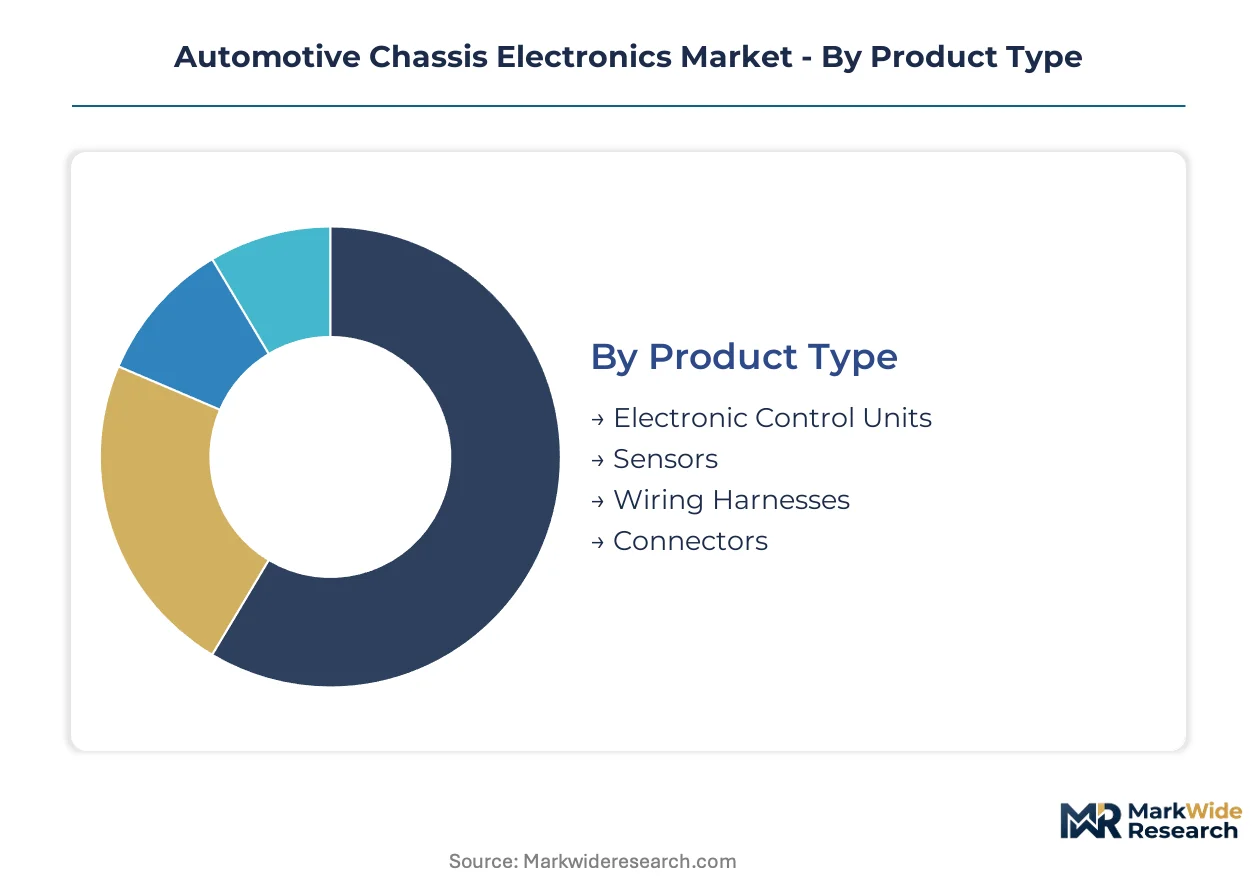
Chassis electronics procurement diverges sharply between platforms undergoing full electrical architecture redesigns and those running legacy 12V systems. Upgrade cycles for domain controllers and sensor arrays now determine supplier contract timing more than traditional vehicle model refreshes.
Product Type:
Replacement intensity varies by component durability, with semiconductor-based modules demanding more frequent updates than passive interconnect hardware.
- Electronic Control Units:Domain controllers consolidate braking, steering, and suspension logic onto single boards with ASIL-D safety ratings. Demand clusters with German OEMs integrating 48V mild-hybrid platforms requiring upgraded power handling.
- Sensors:Axle-load detection, road-condition monitoring, and steering-angle measurement devices proliferate across ADAS-enabled vehicles. Fleet operators in North American long-haul trucking specify predictive maintenance capabilities that feed telematics systems.
- Wiring Harnesses:Copper-intensive cable assemblies face REACH chemical compliance pressures in European supply chains.
- Connectors:Sealed interconnects for underbody chassis zones must endure thermal cycling and corrosion exposure.
Volume placements concentrate in Electronic Control Units; the faster expansion belongs to Sensors.
Technology:
Cost tier separates legacy architectures from next-generation backbone networks, with LIN Bus retaining position in economy segments while Ethernet-derivative protocols penetrate premium platforms.
- Embedded Systems:Real-time operating systems execute chassis control algorithms with sub-10 millisecond latency requirements. ISO 26262 functional safety certification drives software validation costs upward for ASIL-rated implementations.
- CAN Bus:Controller Area Network protocols remain dominant for powertrain and chassis module communication despite bandwidth limitations. Cost-sensitive vehicle segments in India and Southeast Asia sustain demand for this mature standard.
- LIN Bus:Low-cost single-wire networks serve door modules and seat controls where data rates remain minimal.
- Diagnostic Protocols:Unified Diagnostic Services and OBD-II interfaces enable over-the-air calibration updates.
CAN Bus captures current volume leadership; Embedded Systems are climbing the fastest as software-defined vehicle architectures mature.
End User:
Customer type determines specification authority, with OEMs consolidating purchasing power while Tier-1 manufacturers retain design influence.
- OEMs:Vehicle manufacturers specify domain controller integration levels and mandate open communication protocols for ADAS interoperability. NHTSA stability control regulations force direct OEM accountability for system-level certification.
- Tier-1 Manufacturers:Bosch Mobility Solutions, Continental AG, and ZF Friedrichshafen AG translate OEM requirements into electromechanical subsystem designs. These suppliers anchor engineering resources in Stuttgart, Munich, and Wolfsburg to serve German OEM clusters.
- Vehicle Assemblers:Contract manufacturers execute hardware integration without design ownership.
- Aftermarket Suppliers:Independent distributors serve repair networks with replacement sensors and control modules.
Revenue concentration sits with OEMs; Tier-1 Manufacturers show the steepest expansion trajectory as outsourcing deepens.
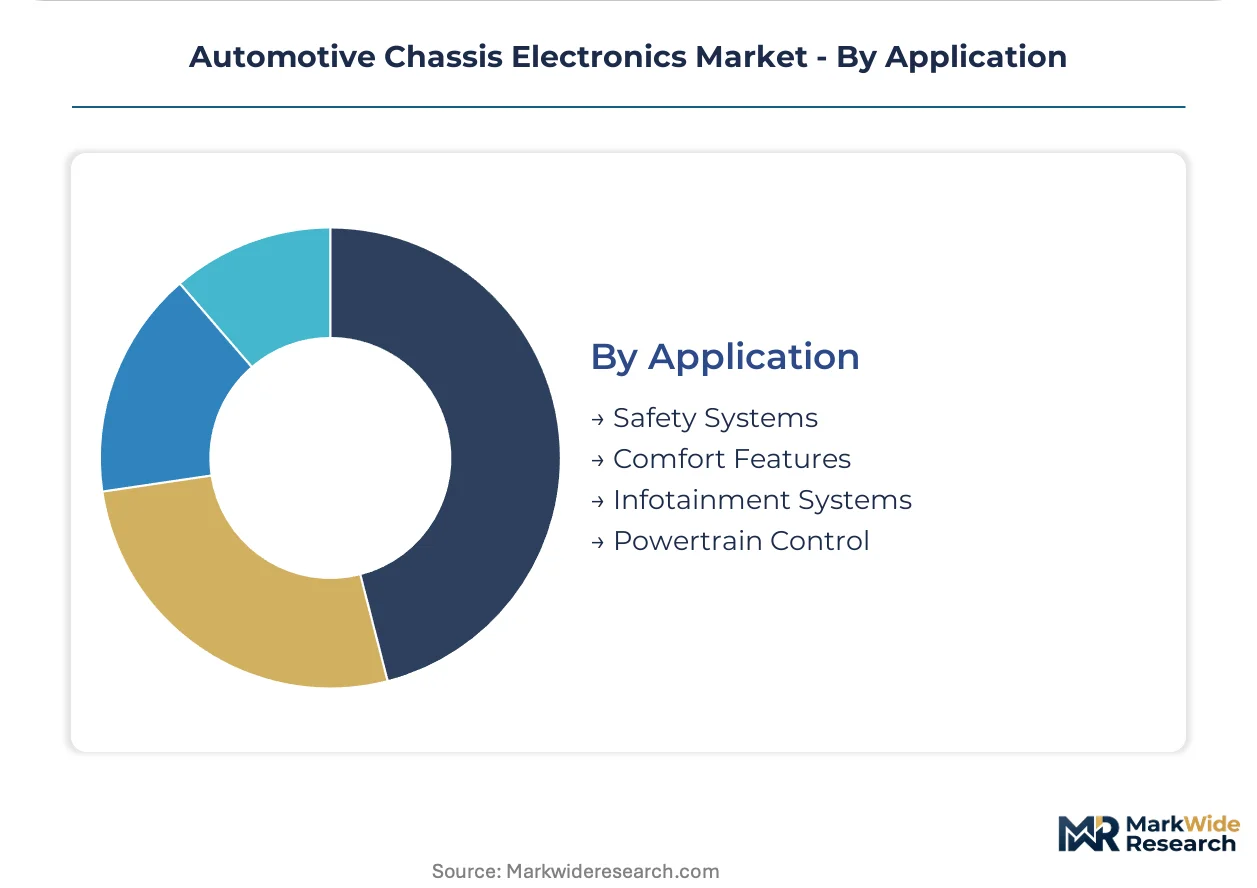
Application:
Application priority shifts with regulatory pressure, where safety mandates now override comfort feature development cycles.
- Safety Systems:Electronic stability control, anti-lock braking, and traction management systems face mandatory fitment under NHTSA FMVSS 126 and equivalent regulations. Heavy-duty truck segments encounter the steepest compliance burden due to payload-variable dynamics algorithms.
- Powertrain Control:Regenerative braking coordination and torque vectoring integration demand chassis-electronics synchronization with battery management systems. EPA emissions standards pressure optimization of energy recovery across US vehicle platforms.
- Comfort Features:Adaptive suspension and active damping systems differentiate premium vehicle positioning.
- Infotainment Systems:Chassis-mounted accelerometers and gyroscopes supply vehicle motion data to navigation and augmented reality displays.
Procurement volume tilts toward Safety Systems; Powertrain Control gains share fastest as electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rare earth processing and Taiwanese semiconductor foundries anchor the geographic distribution of chassis electronics supply chains. Raw material concentration in these localities shapes component availability and pricing volatility across automotive manufacturing clusters.
United States
NHTSA mandates electronic stability control and ADAS interoperability across light-duty and heavy-duty vehicle segments. EPA emissions standards pressure powertrain control modules to optimize regenerative braking energy recovery. Detroit anchors OEM engineering centers where Ford, General Motors, and Stellantis consolidate chassis domain controller procurement.
Germany
BMW, Mercedes-Benz, and Volkswagen drive demand for integrated chassis platforms merging software with electromechanical actuation. EU Green Deal and REACH chemical restrictions shape material selection for wiring harnesses and connectors. Stuttgart, Munich, and Wolfsburg concentrate supplier engineering resources from Bosch Mobility Solutions, Continental AG, and ZF Friedrichshafen AG.
China
MIIT mandates for unified vehicle operating systems enable chassis electronics suppliers to design once for multiple domestic NEV OEMs. Dual carbon goals accelerate 48V mild-hybrid platform adoption requiring upgraded chassis control systems. Yangtze River Delta and Pearl River Delta clusters host BYD, NIO, and Xpeng engineering centers specifying domain controller integration.
Japan
Toyota, Honda, and Nissan anchor advanced chassis development for steer-by-wire architectures on dedicated EV platforms. METI industrial policy supports automotive-grade microcontroller production to reduce import dependency. Nagoya and Tokyo metropolitan areas concentrate Denso Corporation and other Tier-1 supplier R&D facilities.
India
Maruti Suzuki, Tata Motors, and Mahindra expand domestic chassis electronics sourcing as PLI scheme incentives localize supply chains. BIS certification requirements shape component specifications for cost-sensitive vehicle segments. Tamil Nadu and Maharashtra manufacturing corridors attract supplier investments for sensor and ECU assembly operations.
Automotive Chassis Electronics Market Vendor Landscape
Global majors compete with regional champions across technology integration depth and geographic proximity to OEM engineering centers. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with embedded systems expertise, specialized chassis platform integrators, and electronics-focused component suppliers. Consolidation pressure intensifies as OEMs reduce supplier tiers through domain controller consolidation. M&A activity targets software capabilities and cybersecurity certification assets.
Among diversified industrial conglomerates, Bosch Mobility Solutions and Continental AG exemplify the integrated technology provider archetype, spanning sensor hardware through embedded software stacks. ZF Friedrichshafen AG occupies a distinct position as a chassis platform specialist with electromechanical actuation heritage. These German-based entities anchor engineering resources in proximity to Stuttgart and Munich OEM clusters, representing the premium-tier competitive vector where functional safety certification and ISO 26262 compliance create qualification barriers.
| Leading Market Players |
|---|
| Bosch Mobility Solutions |
| Denso Corporation |
| Continental AG |
| Magna International |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Hyundai Mobis |
| Delphi Technologies |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap wiring harness specialists in Southern Germany anchor regional supply networks while exercising pricing discipline through long-term OEM frame contracts. Their ownership structure insulates margin targets from quarterly earnings pressure, creating stability in component pricing even as copper and rare earth volatility feeds through to actuator costs.
Pricing Analysis
Warranty bundling separates chassis electronics procurement into service-inclusive frame contracts and unbundled spot purchases for aftermarket replacement. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and volume scale commitments. Pricing pressure stems from semiconductor supply concentration in Taiwan and South Korea compressing ECU margins. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while cost-sensitive vehicle segments in India drive hardest unit-price negotiations.
Supply Chain Analysis
Container freight rates from Taiwanese semiconductor foundries to German assembly plants directly influence landed costs for microcontroller-dependent ECUs. Supply concentrates in Germany for rare earth processing, Taiwan for automotive-grade semiconductors, and China for magnet and connector manufacturing. Copper wire, neodymium magnets, and silicon wafers constitute critical input dependencies. Single-source vulnerability in 300mm wafer fabrication creates structural risk. Distribution runs through Tier-1 integrators delivering sequenced parts to OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive chassis electronics market functions as a vertical-integration race where control over semiconductor sourcing and embedded software stacks determines margin capture. Players are pursuing backward integration into automotive-grade microcontroller supply to reduce Taiwan foundry dependency.
For Market Incumbents: Extend domain controller consolidation roadmaps to capture braking-steering-suspension integration contracts before platform standardization freezes supplier tiers. Secure ASIL-D certification assets through targeted capability acquisition to defend against emerging Chinese NEV platform specialists. Prioritize captive semiconductor supply arrangements with South Korean foundries to mitigate single-source exposure. For New Entrants and Emerging Players: The price-point gap between German premium chassis platforms and Indian cost-optimized segments creates white-space opportunity for mid-tier sensor suppliers. Target domestic OEM sourcing mandates under India's PLI scheme where engineering localization requirements disadvantage distant incumbents. Pursue fleet telematics integration partnerships as the primary go-to-market angle, bypassing entrenched Tier-1 supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined vehicle specialists with ISO 26262 certification capabilities in Stuttgart and Munich corridors. Long-term viability hinges on chassis-ADAS domain convergence over a multi-year electrification transition. Monitor MIIT standardization mandates for unified vehicle operating systems as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Firmware-upgradable chassis architectures unlock recurring revenue streams disconnected from hardware replacement cycles. |
| Battery Supply Agreement | Regenerative braking coordination with BMS suppliers secures powertrain control module positioning under EPA standards. |
| Geographic Manufacturing Footprint | Tamil Nadu and Maharashtra assembly operations capture PLI incentives while satisfying BIS certification requirements. |
| Platform Standardization | MIIT-mandated unified operating systems enable single-design multi-OEM supply relationships across Yangtze River Delta clusters. |
| Charging Infrastructure Partnership | 48V mild-hybrid platform penetration accelerates through charging network interoperability specifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive chassis electronics assessment. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations specialists validated demand-side assumptions. NHTSA rulemaking dockets, EPA emissions compliance reports, EU REACH substance registrations, and MIIT standardization notices provided regulatory trajectory inputs. Bottom-up vehicle production forecasts and top-down electronics content-per-vehicle estimates underwent cross-triangulation.
Reconciliation of vehicle registration databases against supplier shipment disclosures established baseline volume estimates across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to technology adoption S-cycles for steer-by-wire and domain controller penetration. Semiconductor supply constraints and copper price volatility scenarios bounded forecast sensitivity ranges.
Inputs from Taiwan foundry utilization reports and German Tier-1 financial disclosures were available through the study window; gaps in Chinese NEV platform specification data introduce uncertainty bands around MIIT standardization timing assumptions. Forecasts reflect documented assumptions about electrification adoption curves and regulatory compliance deadlines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market