
 Automotive Coolant Pump Market | 2026-2036
Automotive Coolant Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coolant Pump Market Insights
Project finance for dedicated EV thermal component facilities is narrowing the competitive field to capital-rich suppliers. Robert Bosch GmbH leverages its integrated electronics division to control electric pump module development. Continental AG anchors its position through in-house semiconductor partnerships for motor controllers. Mahle GmbH specializes in compact high-flow designs that serve hybrid architectures.
An automotive coolant pump is a fluid circulation device, typically rated for flow rates between 50 and 400 liters per minute and operating temperatures from minus 40 to 150 degrees Celsius, that maintains optimal thermal equilibrium in internal combustion and electrified powertrains. Electric pumps now lead technology adoption as engine bays lose belt-driven accessories and thermal zones multiply. Passenger vehicle applications command the largest volume share, while commercial vehicle segments present higher per-unit margins due to durability specifications and fleet uptime requirements.
EPA tailpipe rules, EU F-Gas Regulation on refrigerant containment, and Japan METI energy efficiency benchmarks collectively mandate tighter thermal management across vehicle classes. These frameworks force redesign cycles that favor suppliers with certified testing infrastructure and multi-region homologation experience. Stakeholders must weigh electrification pace against mechanical pump aftermarket longevity when allocating R&D budgets.
Market Dynamics
Powertrain electrification is eliminating belt-driven accessories while multiplying thermal zones per vehicle, forcing pump architecture from single mechanical units toward distributed electric modules with embedded motor controllers.
Growth Catalysts
- EPA tailpipe regulations:Tightening emissions standards in the United States mandate precise thermal control across hybrid and electric platforms, accelerating electric pump adoption in Detroit's electrified truck programs.
- EU Green Deal decarbonization:The European framework forces OEMs to redesign thermal systems for efficiency, creating certified demand for suppliers with multi-region homologation infrastructure.
- Japan METI energy benchmarks:These efficiency mandates compress thermal management tolerances, driving compact high-flow pump specifications for domestic kei-car electrification.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings disrupt electric pump motor economics, squeezing margins for suppliers without long-term offtake agreements.
- Semiconductor supply concentration:Motor controller chip fabrication concentrates in Taiwan and South Korea, exposing pump module production to single-point geopolitical risk.
- Mechanical pump aftermarket longevity:Durable belt-driven units in existing ICE fleets delay replacement cycles, compressing near-term revenue for electric-focused product lines.
Strategic Opportunities
- Commercial vehicle fleet electrification:Heavy-duty uptime requirements in Germany and the United States favor premium electric pump durability specifications with higher per-unit margins.
- ISO 26262 functional safety certification:This automotive standard creates a barrier that rewards early-compliant suppliers with locked-in OEM platform wins.
- Thermal management-as-a-service:Subscription-based pump monitoring and predictive maintenance contracts open recurring revenue streams beyond hardware sales.
Industry Challenges
- Embedded software talent scarcity:Motor control algorithm development and functional safety verification require specialized engineers that pump suppliers struggle to recruit against semiconductor and Tier 1 competitors.
- Multi-zone integration complexity:Battery, inverter, and cabin thermal loops demand synchronized pump control that legacy suppliers lack the systems architecture experience to deliver.
- Homologation timeline compression:Simultaneous EPA, EU F-Gas, and Japan METI certification cycles strain testing infrastructure and delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coolant Pump Market |
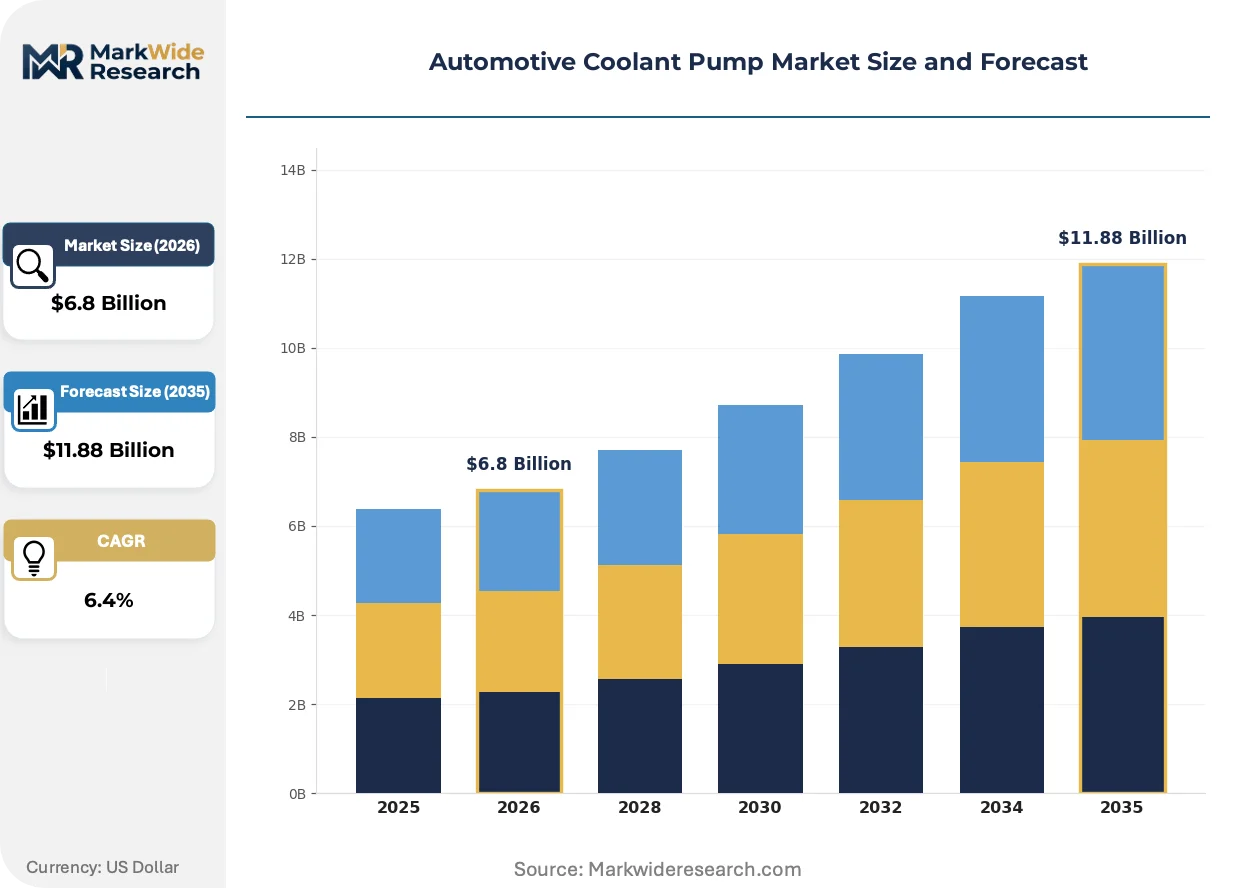
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pump, Gear Pump, Electric Pump, Mechanical Pump End User: OEMs, Aftermarket Providers, Repair Shops, Vehicle Assemblers Technology: Electric Drive, Hydraulic Drive, Pneumatic Drive, Mechanical Drive Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Race Cars |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Aisin Seiki Co., Ltd., Mahle GmbH, Valeo SA, Rheinmetall AG, Schaeffler AG, Davies Craig Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coolant Pump Market Trends and Innovations
Digital twin technology and predictive thermal modeling are compressing development cycles while enabling real-time pump optimization across variable driving profiles.
Brushless DC motor architecture with integrated power electronics is virtualizing the traditional separation between pump mechanics and engine control modules. Tier 1 suppliers in Germany and Japan are adopting these smart pump units at program-launch scale. This convergence is virtualizing discrete component procurement into subsystem sourcing decisions that favor integrated electronics capabilities.
EU F-Gas Regulation refrigerant containment mandates are forcing coolant circuit redesigns that eliminate leak-prone mechanical seals. The regulation drives hermetic electric pump specifications across passenger and commercial vehicle classes. French and German OEMs are responding with platform-standardized thermal architectures that consolidate supplier pools.
Fleet operators in the United States are unbundling after-sales service from hardware procurement, demanding outcome-based uptime guarantees rather than component warranties. This purchasing shift compresses supplier margins while transferring operational risk to pump manufacturers. The pattern is most visible in California and Texas heavy-duty electrification programs where total cost of ownership dominates acquisition decisions.
Automotive Coolant Pump Market Segmentation
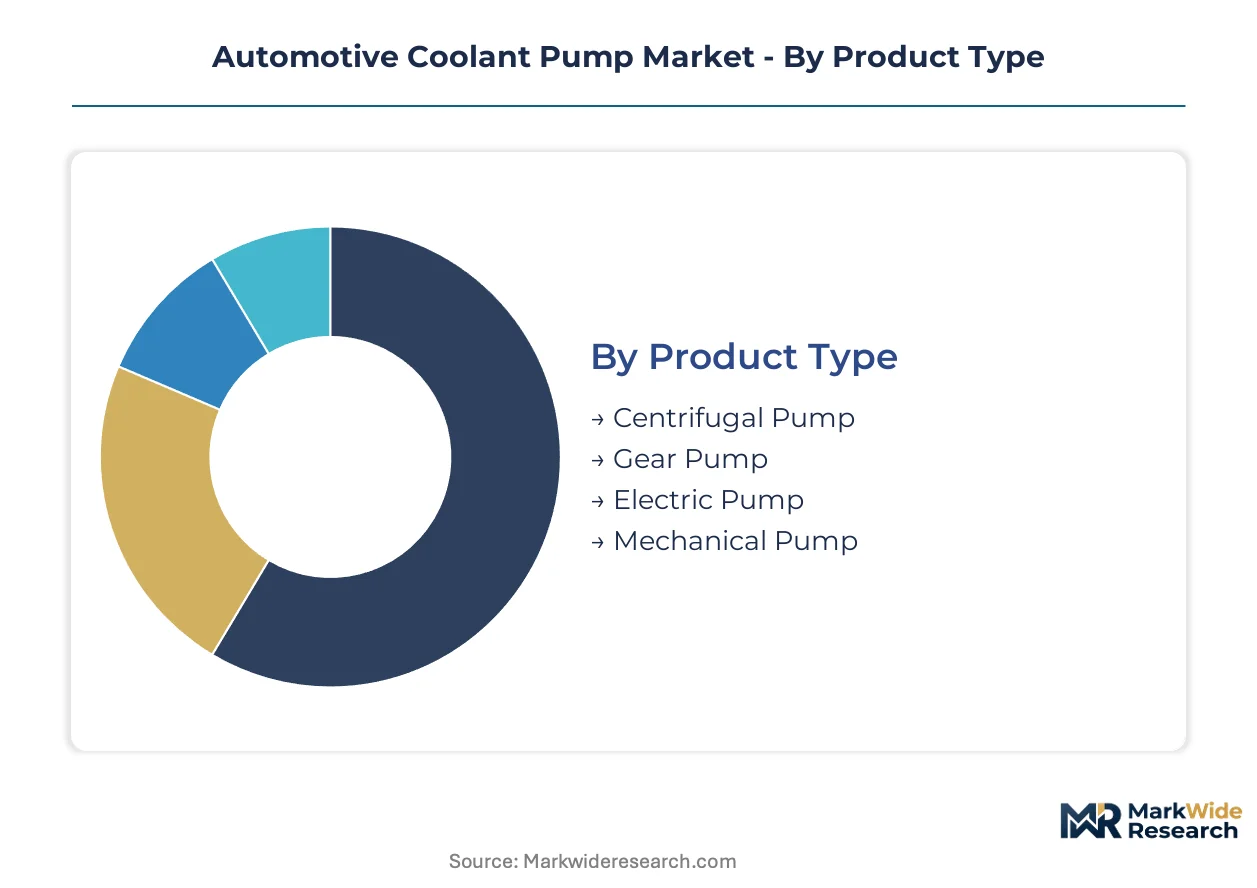
Segmentation in the automotive coolant pump market reveals divergent margin structures and service intensity profiles across product architectures and customer channels. Suppliers must calibrate production footprints and inventory strategies to the distinct technical requirements and purchasing behaviors of each segment cluster.
Product Type:
After-sales-service intensity varies sharply across pump architectures, with electric modules requiring software diagnostics and mechanical units demanding seal replacement protocols.
- Electric Pump:Brushless DC motor architecture with embedded power electronics eliminates belt-drive dependencies while enabling precise flow modulation across battery, inverter, and cabin thermal zones. Demand concentrates in Germany and Japan where OEMs scale dedicated EV platforms under EU Green Deal and METI efficiency mandates.
- Mechanical Pump:Belt-driven centrifugal designs with stamped housings and graphite seals maintain cost advantages in ICE-dominant vehicle classes. The United States pickup and SUV segments sustain volume demand despite electrification headwinds, though replacement cycles extend due to aftermarket durability.
- Centrifugal Pump:Radial flow impeller designs dominate coolant circulation duty across both electric and mechanical implementations.
- Gear Pump:Positive displacement architecture serves high-viscosity thermal fluid applications in commercial vehicle auxiliary circuits.
Mechanical pumps hold the largest share; momentum sits with electric pumps.
End User:
Cost tier stratification separates capital-intensive OEM contracts from fragmented aftermarket channels with diverging margin profiles.
- OEMs:Platform-scale procurement contracts demand ISO 26262 functional safety certification and multi-region homologation capability, locking in Tier 1 suppliers with integrated electronics divisions. Specifications tighten under simultaneous EPA tailpipe, EU F-Gas, and Japan METI compliance cycles.
- Aftermarket Providers:Independent distributors and private-label suppliers source replacement units for aging ICE fleets, with revenue durability tied to mechanical pump longevity in existing vehicle parc. Germany and the United States present the deepest replacement demand pools.
- Repair Shops:Direct installation channels capture urgent failure replacement demand with limited brand loyalty.
- Vehicle Assemblers:Contract manufacturers and kit builders procure pumps as part of powertrain module sourcing agreements.
OEMs command the highest per-unit margins; aftermarket providers deliver volume stability.
Technology:
Application-specific duty cycles determine drive technology selection across passenger comfort and powertrain thermal management functions.
- Electric Drive:Variable-speed motor control enables precise thermal zone management with energy recovery potential, displacing hydraulic and pneumatic alternatives in electrified architectures. Adoption accelerates in Japan kei-car electrification and German premium EV platforms.
- Mechanical Drive:Crankshaft or accessory belt power takeoff maintains cost efficiency in conventional powertrains with single-zone cooling requirements.
- Hydraulic Drive:Auxiliary power unit coupling serves commercial vehicle applications with existing hydraulic infrastructure.
- Pneumatic Drive:Compressed air actuation persists in specialty vehicle classes with pneumatic system integration.
Mechanical drive retains installed base dominance; electric drive is climbing the fastest.
Application:
Volume concentration in passenger vehicles contrasts with margin premium availability in commercial and specialty segments.
- Passenger Vehicles:High-volume production scales across compact through luxury segments drive platform-standardized pump specifications, with electrification multiplying thermal zone count per vehicle. EU F-Gas refrigerant containment mandates force hermetic electric pump adoption across French and German OEM lineups.
- Commercial Vehicles:Heavy-duty uptime requirements and fleet total-cost-of-ownership calculations favor premium durability specifications with extended service intervals. California and Texas heavy-duty electrification programs are unbundling service contracts from hardware procurement.
- Heavy-Duty Trucks:Long-haul thermal loads demand high-flow capacity with redundant cooling circuit architectures.
- Race Cars:Extreme performance specifications prioritize weight reduction and rapid thermal transient response.
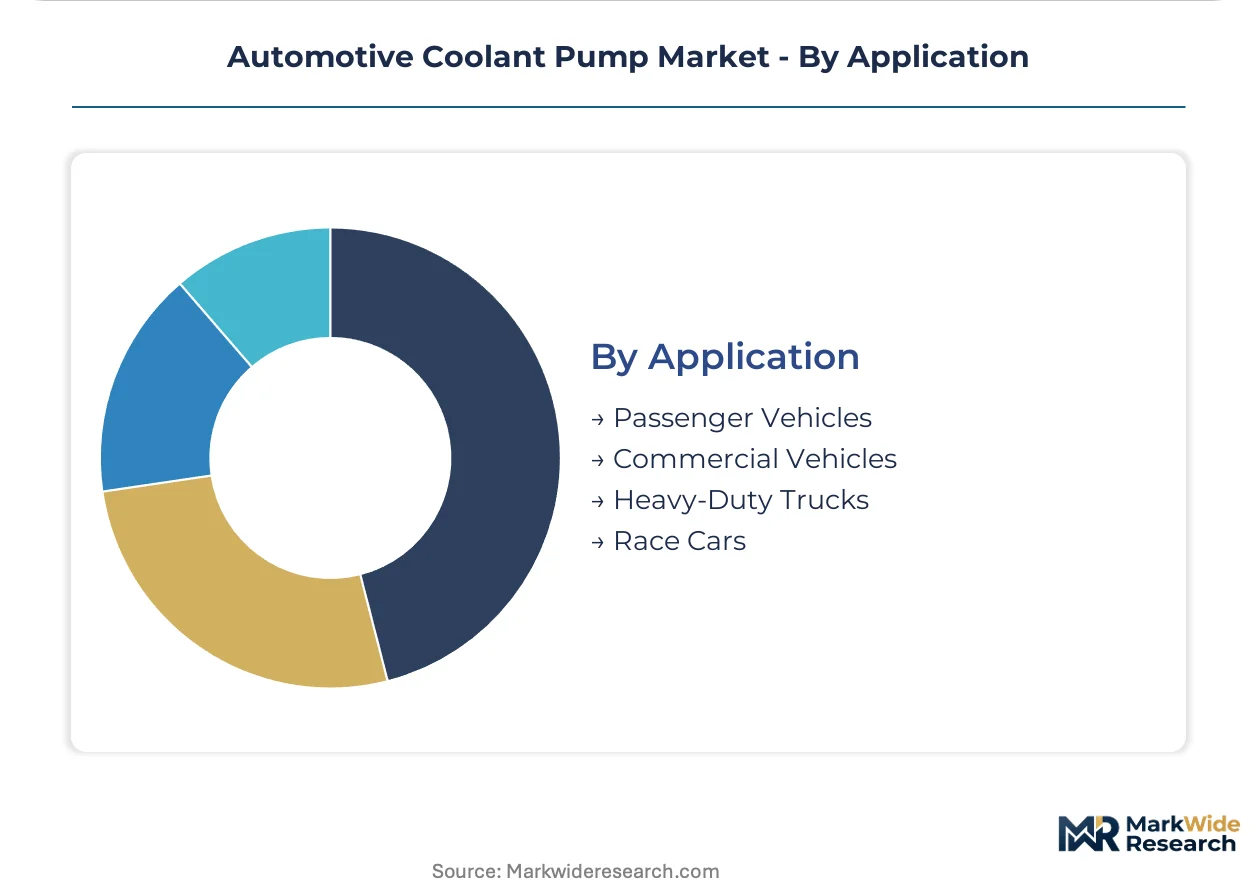
Passenger vehicles generate the highest absolute revenue; commercial vehicles offer the steepest expansion trajectory in per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers extract premium pricing for ISO 26262-certified electric pump modules, while Chinese manufacturers compete on unit cost for mechanical replacements. This asymmetry shapes procurement patterns across OEM and aftermarket channels.
United States
Detroit's electrified truck programs and California heavy-duty fleet mandates drive electric pump demand. EPA tailpipe regulations tighten thermal control requirements across hybrid platforms. Michigan and Texas industrial corridors host Tier 1 supplier engineering centers serving domestic OEM platform launches.
Germany
French and German OEM platform-standardized thermal architectures consolidate supplier pools under EU F-Gas refrigerant containment mandates. EU Green Deal decarbonization timelines compress homologation cycles. Stuttgart and Munich engineering clusters specialize in brushless DC motor controller integration for premium EV lineups.
Japan
Domestic kei-car electrification and METI energy efficiency benchmarks drive compact high-flow pump specifications. METI efficiency mandates compress thermal management tolerances. Nagoya and Tokyo supplier networks anchor motor controller semiconductor partnerships for integrated pump modules.
China
Domestic EV platform scaling and local supply chain localization policies reshape component sourcing. Dual carbon goals accelerate thermal system efficiency requirements. Yangtze River Delta manufacturing bases concentrate electric pump motor production for regional OEM electrification programs.
South Korea
Battery thermal management integration and domestic EV platform development multiply pump specifications per vehicle. National semiconductor self-sufficiency initiatives target motor controller chip fabrication. Seoul Capital Area R&D centers specialize in multi-zone thermal loop synchronization algorithms.
Automotive Coolant Pump Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mechanical and motor sub-assembly supply. The market structure concentrates around Tier 1 suppliers with certified testing infrastructure and multi-region homologation capability. Three archetypes dominate: integrated electronics divisions, in-house semiconductor partners, and compact high-flow design specialists. Competitive moves center on strategic partnerships for motor controller supply and capacity expansion for EV-dedicated production lines.
Among Germany-based diversified industrial groups, Robert Bosch GmbH and Continental AG exemplify platform integrators with embedded electronics capabilities. Mahle GmbH represents the compact high-flow specialization archetype serving hybrid architectures. These three occupy positions that reflect the market's trajectory toward distributed electric modules with integrated motor controllers.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Aisin Seiki Co., Ltd. |
| Mahle GmbH |
| Valeo SA |
| Rheinmetall AG |
| Schaeffler AG |
| Davies Craig Pty Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese electric motor manufacturing is compressing supplier margins while simultaneously enabling aggressive pricing postures for volume contracts. German and Japanese pump module producers respond by anchoring premium positioning through ISO 26262 certification and embedded software capabilities that commodity competitors cannot replicate.
Pricing Analysis
Configured-to-order pricing for electric pump modules with integrated motor controllers commands spreads of 40-60 percent above standard mechanical pump catalogs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified suppliers from regional homologation-only competitors from cost-focused mechanical replacement producers. Cost compression in standard mechanical tiers is intensifying because Chinese manufacturers are flooding aftermarket channels with stamped-housing units. Fleet procurement officers in California heavy-duty electrification programs exhibit the lowest price sensitivity due to total-cost-of-ownership calculations, while independent aftermarket distributors in the United States remain the most price-sensitive buyer segment.
Supply Chain Analysis
Extended payment terms from German OEMs now stretch to 90-120 days, forcing Tier 1 suppliers to deploy supply-chain finance facilities or absorb working capital strain. Motor controller chip fabrication concentrates in Taiwan and South Korea, while rare earth magnet processing for brushless DC motors is anchored in China. Neodymium and dysprosium price volatility, copper winding stock, and semiconductor wafer supply constitute the critical input dependencies. Single-source vulnerability around Taiwan Semiconductor fabrication exposes pump module production to geopolitical disruption. Distribution runs through OEM platform-scale procurement contracts and fragmented aftermarket distributor networks with diverging margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by the replacement wave of aging ICE fleet thermal components and simultaneous EV platform scaling. The recovery trajectory hinges on rare earth price stabilization and semiconductor capacity expansion.
For Market Incumbents: Build certification moats by accelerating ISO 26262 functional safety investment ahead of competitor compliance timelines. Secure long-term offtake agreements with rare earth processors to insulate electric pump motor economics from neodymium price volatility. Deepen backward integration into motor controller semiconductor sourcing through partnerships with South Korean fabrication facilities. Channel control through exclusive aftermarket distribution agreements protects margin position against Chinese mechanical pump imports.
For New Entrants and Emerging Players: Pursue white-space opportunities in commercial vehicle fleet electrification service contracts, where outcome-based uptime guarantees transfer operational risk from fleet operators to pump manufacturers. Target the United States heavy-duty aftermarket channel in Texas and California, where electrification mandates are outpacing incumbent service infrastructure. Penetration is highest among independent distributors serving aging ICE fleets with price-competitive mechanical replacements. A software-defined thermal management-as-a-service go-to-market angle bypasses capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with embedded software diagnostics and predictive maintenance contracts rather than pure hardware manufacturers. Long-term viability over the five-to-ten year window favors platform integrators with multi-region homologation capability and captive semiconductor partnerships. Acquisition targets should display integrated electronics divisions with brushless DC motor controller development expertise. The signal to watch is EPA tailpipe rule acceleration or relaxation, which would respectively compress or extend mechanical pump aftermarket longevity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | French and German OEMs consolidate supplier pools under EU F-Gas refrigerant containment mandates. |
| Battery Supply Agreement | Thermal loop integration with cell manufacturers secures multi-zone pump specifications per vehicle. |
| Software-Defined Vehicle Investment | Embedded motor control algorithms virtualize discrete component procurement into subsystem sourcing. |
| Geographic Manufacturing Footprint | Yangtze River Delta localization serves Chinese EV platform scaling under dual carbon goals. |
| Charging Infrastructure Partnership | Heavy-duty fleet electrification in Texas and California demands thermal management uptime guarantees. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution channel managers, and fleet operations officers provided ongoing calibration against market developments. Primary interview data combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA regulatory filings, and EU F-Gas compliance records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around rare earth price volatility and semiconductor supply disruption produced bounded forecast ranges without deterministic point estimates. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from production volume projections weighted by pump specification intensity per thermal zone count. Industry-specific forecast inputs incorporated METI energy efficiency benchmark trajectories and EU Green Deal decarbonization timeline compression.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, rare earth commodity prices, or Taiwan semiconductor fabrication capacity would shift the trajectory. Forecasts reflect documented assumptions regarding electrification pace and regulatory enforcement stringency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
VVT and Start-Stop Systems Market