
 Automotive Screenwash Products Market | 2026-2036
Automotive Screenwash Products Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Screenwash Products Market Analysis
Fleet operator procurement is expanding as logistics uptime requirements tighten across commercial vehicle segments. Prestone Products Corporation leverages its winter-formulation expertise to anchor supply contracts with North American fleet managers. ITW Global Brands competes through automotive retail channel control, while Sasol Chemicals sustains feedstock cost advantages in surfactant chemistry.
Automotive screenwash products are aqueous cleaning formulations containing surfactants, solvents, and antifreeze agents designed to remove road grime, insect residue, and ice from vehicle windshields without damaging wiper blades or painted surfaces. Concentrated formulations dominate volume sales due to freight efficiency and retailer shelf-space economics, while ready-to-use products capture convenience-driven individual consumers through gas station and supermarket channels. Winter formula variants command premium positioning in cold-climate regions where methanol and ethylene glycol content must meet freeze-protection specifications.
The EPA regulates volatile organic compound content under Clean Air Act provisions, while REACH in Europe restricts methanol concentrations in consumer-facing formulations. China's GB standards through SAMR mandate labeling and safety data sheet compliance for chemical mixtures sold through automotive aftermarket channels. Stakeholders must monitor evolving state-level VOC restrictions in California and New York alongside the EU Green Deal's chemical sustainability targets.
Market Dynamics
Fleet uptime mandates and tightening VOC regulations are compressing formulation cycles and procurement patterns across the automotive screenwash sector. Chemical suppliers face simultaneous pressure to reduce methanol content while maintaining freeze-protection performance in winter-grade products.
Growth Catalysts
- Commercial Fleet Expansion:Logistics operators in Germany and the United States are extending replacement cycles and consolidating supplier contracts to minimize vehicle downtime during winter months.
- REACH Compliance Deadlines:ECHA restrictions on methanol concentrations in consumer formulations are accelerating R&D investment in glycol-based and bio-derived antifreeze alternatives.
- Concentrate Economics:Freight cost differentials favor concentrated screenwash formulations, driving retailer shelf-space reallocation toward dilutable products in automotive aftermarket channels.
Market Restraints
- Feedstock Volatility:Ethylene glycol and surfactant precursor prices fluctuate with crude oil derivatives, squeezing margin stability for mid-tier blenders.
- Supplier Concentration:Specialty surfactant production clusters in Germany and the Netherlands create geographic vulnerability for formulators dependent on European chemical feedstock.
- Substitution Pressure:All-season wiper fluid systems and heated windshield technologies reduce per-vehicle screenwash consumption in premium automotive segments.
Strategic Opportunities
- India Aftermarket Penetration:SAMR-aligned GB standard adoption in China's automotive supply chain creates template compliance pathways for Indian distributors entering organized retail.
- EU Green Deal Alignment:Chemical sustainability targets and bio-based content mandates open formulation partnerships with agricultural waste-derived solvent producers.
- Direct Fleet E-Commerce:B2B platform procurement bypasses traditional distributor markups, enabling volume pricing transparency for multi-thousand vehicle operators.
Industry Challenges
- Formulation Chemistry Talent:Shortage of surfactant chemists with low-temperature fluid dynamics expertise delays winter-grade product development cycles.
- Multi-Jurisdiction Labeling:Divergent EPA Safer Choice, REACH Annex XVII, and SAMR GB standard requirements force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Screenwash Products Market |
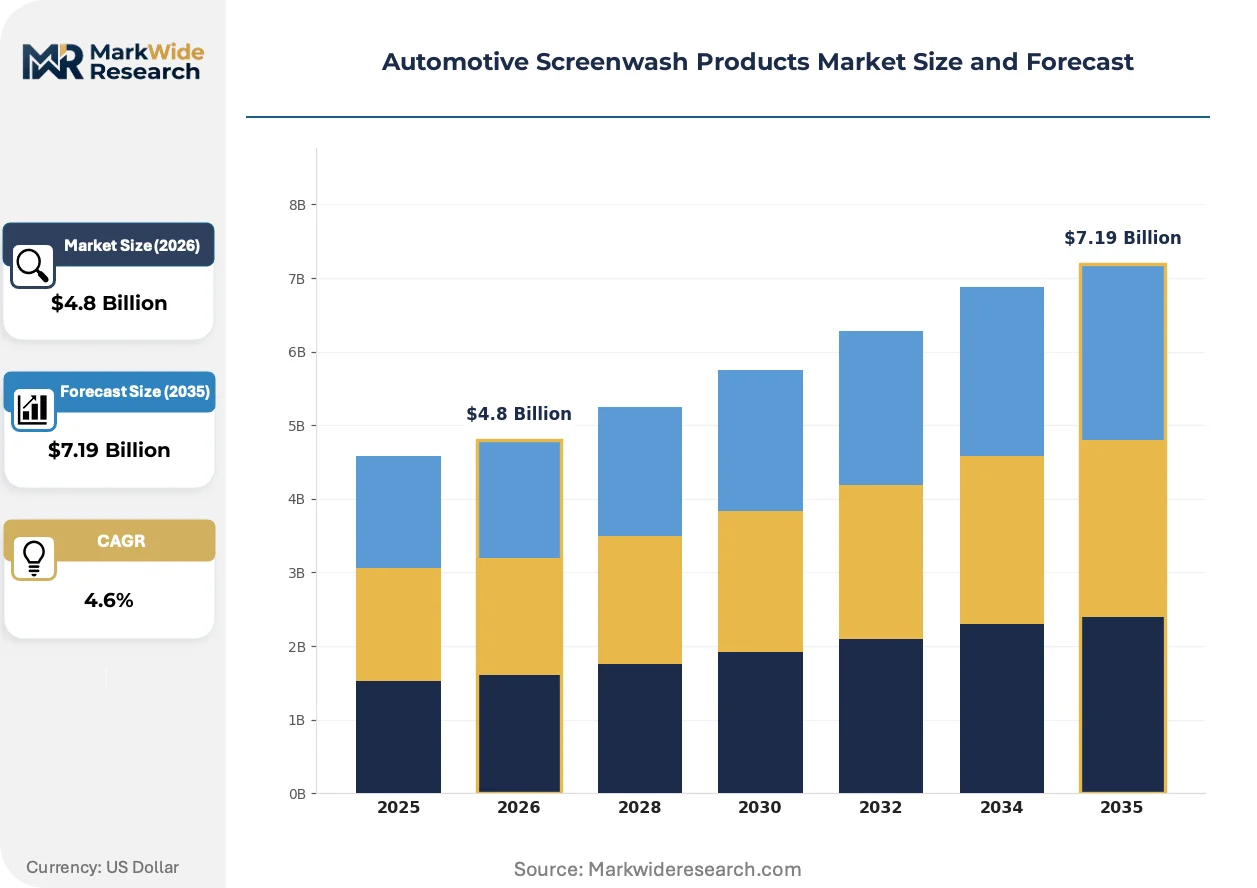
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Ready-to-Use, Winter Formula, Summer Formula Packaging Type: Plastic Bottles, Jugs, Pouches, Bulk Containers Distribution Channel: Online Retail, Automotive Stores, Supermarkets, Gas Stations End User: Individual Consumers, Fleet Operators, Automotive Workshops, Dealerships |
| Companies Covered | 3M, Prestone Products Corporation, Henkel AG & Co. KGaA, Turtle Wax, Inc., SONAX GmbH, ITW Global Brands, Meguiar's, Sasol Chemicals, Recochem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Screenwash Products Market Emerging Trajectories
Formulation chemistry and distribution logistics are converging around sustainability compliance and procurement efficiency. Three distinct vectors are restructuring competitive advantage in screenwash supply.
Biobased surfactant platforms derived from agricultural byproducts are unifying performance and regulatory compliance objectives for European formulators. Sasol Chemicals and specialty chemical divisions of major oil companies are piloting rapeseed and corn-derived alternatives to petroleum-based alkylbenzene sulfonates. The technology is unifying cost parity with conventional surfactants in high-volume production runs, compressing the premium positioning historically commanded by bio-derived formulations.
REACH Annex XVII methanol restrictions are forcing reformulation of consumer-facing winter products across EU member states. Industrial consequence includes accelerated glycol substitution and elevated raw material costs for freeze-protection compliance. Germany's KBA type-approval requirements for automotive fluids are extending testing protocols to screenwash formulations, affecting importers and private-label suppliers most acutely.
Direct procurement platforms are consolidating fleet operator purchasing into annual volume contracts with formula customization clauses. Traditional automotive aftermarket distributors in the United States face margin compression as large logistics operators negotiate direct supply relationships with chemical blenders. This pattern is most visible in the Great Lakes and Northeast corridor states where winter-grade consumption concentrates and fleet density supports dedicated tanker delivery economics.
Automotive Screenwash Products Market Segmentation
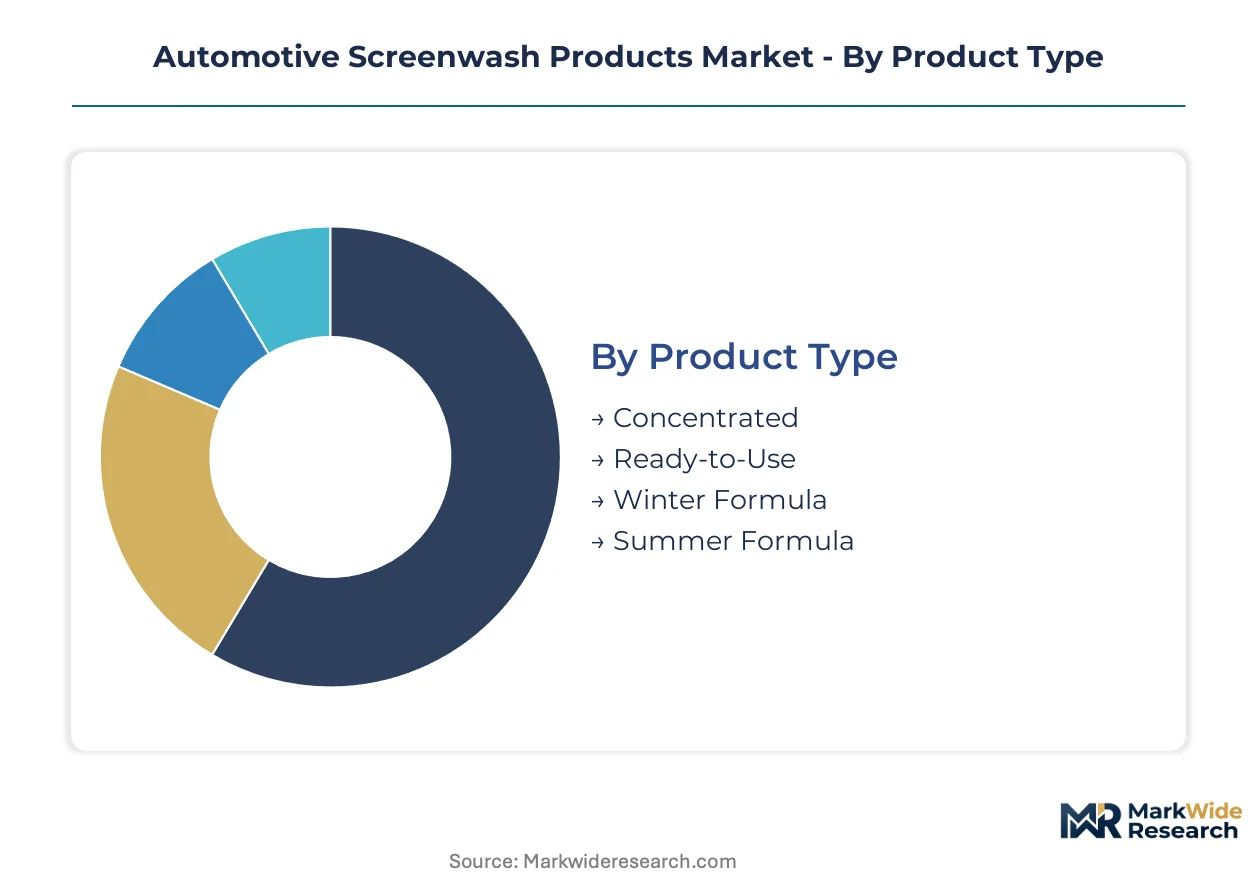
Automotive screenwash segmentation reflects divergent procurement economics between bulk fleet buyers and convenience-driven retail consumers. Formulation chemistry and packaging logistics create distinct margin profiles across each category.
Product Type:
Concentrated formulations dominate freight economics while winter variants command freeze-protection premiums.
- Concentrated:High-active surfactant solutions requiring dilution before application reduce per-unit shipping costs by 60-70% versus ready-to-use equivalents. Fleet operators in Germany and the United States specify concentrate procurement to minimize tanker delivery frequency during high-consumption winter months.
- Winter Formula:Methanol or ethylene glycol-enhanced formulations meeting freeze-protection specifications down to -20°C and below. REACH Annex XVII methanol restrictions are accelerating glycol substitution in EU consumer channels while industrial fleet contracts retain methanol tolerance.
- Ready-to-Use:Pre-diluted solutions targeting impulse purchases at gas stations and supermarkets where consumer convenience overrides unit economics.
- Summer Formula:Reduced antifreeze content formulations optimized for insect residue removal and road grime cleaning in temperate climates.
Mature deployment sits with Concentrated formulations in commercial channels. Newer deployment is concentrated in bio-derived surfactant variants across EU sustainability mandates.
Packaging Type:
Container selection tracks channel economics and refill infrastructure maturity across retail versus institutional buyers.
- Bulk Containers:Intermediate bulk containers and dedicated tanker systems serve fleet operators with captive dilution equipment. Logistics operators in the Great Lakes corridor negotiate annual volume contracts with direct tanker delivery clauses.
- Plastic Bottles:Standard 1-5 liter polyethylene terephthalate containers dominate supermarket and automotive retail shelf presence. Shelf-space economics favor square-base designs maximizing pallet density.
- Jugs:High-density polyethylene containers in 2-4 gallon formats target cost-conscious individual consumers with multi-vehicle households.
- Pouches:Flexible film packaging for concentrated refills reduces plastic intensity by 80% versus rigid containers but requires consumer access to reusable dilution bottles.
Volume concentrates in Plastic Bottles across mass retail. Pouch formats are expanding fastest in EU markets with extended producer responsibility packaging mandates.
Distribution Channel:
Channel control determines margin capture between chemical blenders and end consumers.
- Automotive Stores:Specialized retailers including AutoZone and O'Reilly Auto Parts maintain year-round screenwash inventory with seasonal SKU rotation. Staff expertise drives winter-grade upselling in cold-climate states.
- Online Retail:Amazon and direct-to-fleet e-commerce platforms bypass traditional distributor markups. Large logistics operators negotiate transparent volume pricing through B2B procurement portals.
- Supermarkets:Mass merchandisers capture convenience-driven individual consumers through seasonal promotional placement adjacent to automotive accessories.
- Gas Stations:Impulse purchase locations with highest per-liter pricing but limited SKU depth, typically stocking ready-to-use winter and summer variants only.
Established volume flows through Automotive Stores. Online Retail is climbing the fastest as fleet procurement digitizes.
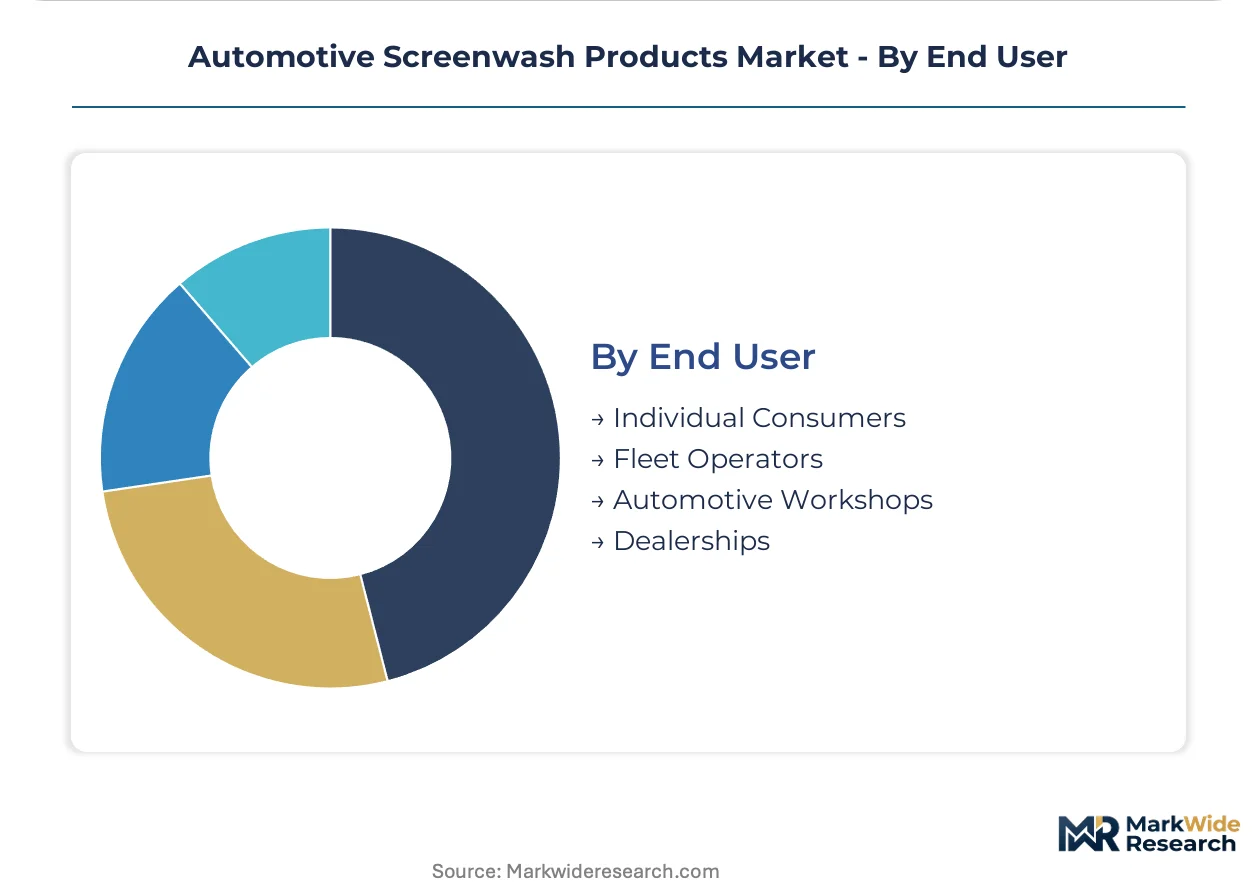
End User:
User type dictates formulation specification complexity and contract structure.
- Fleet Operators:Commercial vehicle operators with 500+ unit fleets negotiate direct supply contracts with formula customization and dedicated delivery scheduling. Uptime requirements mandate winter-grade inventory buffers.
- Individual Consumers:Price-sensitive retail purchasers with seasonal consumption spikes and minimal brand loyalty beyond Prestone and Rain-X recognition.
- Automotive Workshops:Service bay operations requiring rapid-dispense packaging and bulk concentrate systems for vehicle detailing and maintenance services.
- Dealerships:New vehicle delivery preparation and service lane operations with captive brand requirements from OEM fluid specifications.
Contract maturity sits with Fleet Operators. Dealership specification compliance is expanding most quickly as OEMs tighten approved fluid lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States while consumption gravity shifts toward China's expanding vehicle fleet. Formulation chemistry expertise clusters in European industrial centers, but regulatory divergence is fragmenting product specifications across jurisdictions.
United States
Fleet operators in the Great Lakes and Northeast corridors drive bulk concentrate procurement through direct tanker contracts. EPA Safer Choice program requirements on volatile organic compound content force reformulation of retail-facing products. Chicago and Detroit anchor winter-grade production capacity serving commercial logistics networks.
Germany
KBA type-approval protocols for automotive fluids extend testing burdens to screenwash importers and private-label suppliers. REACH Annex XVII methanol restrictions accelerate glycol substitution in consumer channels. The Ruhr industrial region maintains surfactant precursor production critical to European formulation supply.
China
SAMR GB standards mandate labeling and safety data sheet compliance for aftermarket chemical mixtures. Domestic vehicle production exceeding twenty-five million units annually sustains massive screenwash consumption. Yangtze River Delta chemical clusters supply surfactant feedstock to regional blenders.
India
Organized automotive retail expansion creates distribution infrastructure for concentrated formulations. Central Pollution Control Board oversight of chemical mixtures intensifies compliance requirements for imported products. Maharashtra and Gujarat host emerging blending capacity serving western India vehicle density.
Japan
METI energy efficiency guidelines influence automotive chemical product lifecycle assessments. Premium vehicle segment concentration sustains demand for high-performance windshield cleaning systems. Kanto region distribution networks integrate screenwash into comprehensive vehicle maintenance supply chains.
Automotive Screenwash Products Market Vendor Landscape
Top-tier vendors anchor formulation chemistry and fleet contract execution, while mid-tier blenders compete on regional distribution speed and private-label flexibility. The market exhibits moderate consolidation around chemical conglomerates with surfactant production capabilities. Three archetypes dominate: integrated chemical suppliers with captive feedstock, specialized automotive aftermarket brands with retail channel control, and regional blenders serving fleet direct procurement. Competitive moves center on backward integration into surfactant production and B2B platform development for fleet volume contracting.
Among North American specialists, Prestone Products Corporation and ITW Global Brands occupy positions at the premium-brand and retail-channel vectors respectively. Sasol Chemicals anchors the integrated chemical supplier archetype with upstream surfactant capabilities. These three exemplify the strategic divergence between formulation ownership, distribution control, and feedstock security that defines competitive positioning in this sector.
| Leading Market Players |
|---|
| 3M |
| Prestone Products Corporation |
| Henkel AG & Co. KGaA |
| Turtle Wax, Inc. |
| SONAX GmbH |
| ITW Global Brands |
| Meguiar's |
| Sasol Chemicals |
| Recochem Corporation |
| Others |
Supply Flow & Price Mechanics
Ethylene glycol spot price volatility cascades through automotive screenwash supply chains into three distinct pricing tiers. Feedstock cost swings compress margins for mid-tier blenders while integrated chemical suppliers capture buffer capacity through captive surfactant production.
Pricing Analysis
Margin tightening in retail-facing tiers reflects REACH Annex XVII methanol restriction compliance costs. Three-tier pricing structure across premium glycol-based, standard methanol-tolerant, and economy dilutable concentrates separates fleet contract volumes from convenience-channel impulse purchases. Price differentiation hinges on freeze-protection certification grade and volume scale. Individual consumers at gas stations exhibit highest price sensitivity while logistics operators with direct tanker contracts prioritize uptime over unit cost.
Supply Chain Analysis
Return flows of intermediate bulk containers from fleet operators to regional blenders reduce packaging cost intensity by enabling refill economics. Surfactant precursor production clusters in Germany, the Netherlands, and the United States anchor upstream supply. Formulation chemistry draws from ethylene glycol, methanol, and petroleum-derived alkylbenzene sulfonate feedstocks. Single-source vulnerability concentrates in European specialty surfactant manufacturing. Distribution runs through automotive retail chains, direct fleet procurement portals, and mass merchandiser seasonal promotions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive screenwash markets are becoming a vertical-integration race as chemical suppliers pursue backward control over surfactant feedstock to defend formulation margin.
For Market Incumbents: Anchor fleet contract renewal cycles through dedicated tanker delivery infrastructure in the Great Lakes and Northeast corridors. Defend against heated windshield substitution threats by embedding screenwash into bundled vehicle uptime service agreements. Prioritize in-house production of glycol-based antifreeze alternatives to offset REACH-driven methanol reformulation costs.
For New Entrants and Emerging Players: Begin with bio-derived surfactant formulations targeting EU Green Deal compliance premiums in German automotive retail channels. White-space exists in Indian organized aftermarket penetration following SAMR-aligned GB standard templates. Pursue direct-to-fleet e-commerce platforms bypassing traditional distributor markups for logistics operators with 500-plus vehicle counts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier blenders with private-label flexibility in North American automotive retail channels. Five-to-ten year viability hinges on surfactant chemistry talent acquisition and multi-jurisdiction labeling capability buildout. Monitor ECHA methanol restriction enforcement intensity as inflection indicator for glycol substitution investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Captive alkylbenzene sulfonate supply insulates margin from crude derivative volatility. |
| Direct Fleet E-Commerce Platform Launch | B2B procurement portals bypass AutoZone and O'Reilly markup for logistics operators. |
| Bio-Derived Formulation Partnership | Rapeseed and corn-derived surfactants unify EU Green Deal compliance with cost parity. |
| Multi-Jurisdiction Labeling Infrastructure | EPA Safer Choice, REACH Annex XVII, and SAMR GB standard SKU consolidation reduces inventory complexity. |
| Winter-Grade Concentrate Capacity Expansion | Dedicated tanker delivery economics in cold-climate corridors anchor fleet contract renewals. |
Methodological Framework
Trade databases, chemical industry association publications, and automotive aftermarket channel audits formed the secondary backbone of this study. Primary interviews with formulation chemists, fleet procurement managers, automotive retail category buyers, and surfactant plant engineers validated demand assumptions. Bottom-up triangulation across concentrate volume flows and top-down reconciliation against vehicle fleet data anchored market sizing.
Historical trendline analysis of replacement cycle intensity and regulatory compliance cost trajectories informed projection modeling. Segmentation dimensions span product type, packaging format, distribution channel, and end-user archetype across the analysis window. CAGRs derived from elasticity-adjusted consumption patterns incorporate winter severity indices and fleet uptime mandate evolution as screenwash-specific forecast inputs.
Underlying measurement precision varies by segment; fleet operator procurement data carries tighter precision than individual consumer channel estimates. Forecasts reflect assumptions about REACH enforcement timelines and EPA state-level VOC restriction adoption. Practitioners should monitor ECHA methanol concentration rulings and heated windshield technology penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
South America Gear Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market