
 Automotive Electric Drive Axle Market | 2026-2036
Automotive Electric Drive Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Drive Axle Market Analysis
Chinese electric axle foundries is broadening output capacity to serve European and North American OEM programs. Dana Incorporated leverages in-house motor manufacturing to control bill-of-material costs across integrated drive programs. ZF Friedrichshafen AG anchors its position through torque-vectoring axle architectures developed for premium passenger vehicle platforms. Magna International Inc. competes by sustaining dual-source production footprints in Austria and China.
An automotive electric drive axle integrates an electric motor, reduction gearing, and differential into a single axle assembly, typically delivering peak power densities above 3.5 kW per kilogram for passenger vehicle applications. The unit converts battery DC power into mechanical torque at the wheels, eliminating the mechanical driveline and enabling packaging flexibility for skateboard chassis platforms. Integrated Drive configurations command margin premiums due to their consolidated thermal management and reduced assembly steps, while Dual Axle systems lead volume in all-wheel-drive electric SUVs and light trucks. Gear Drive technology dominates commercial vehicle applications where sustained torque loads exceed direct-drive motor efficiency curves, and OEM end users represent the primary demand pool as captive production lines displace tiered supplier arrangements.
EPA tailpipe standards and the EU Green Deal fleet CO2 targets are mandating zero-emission powertrains, which forces axle suppliers to certify electromagnetic compatibility under ECE R10 and thermal endurance under ISO 26262 functional safety grades. China's MIIT new energy vehicle catalog ties subsidy eligibility to domestic motor and axle content thresholds, reshaping supplier qualification pathways. Stakeholders must monitor how NHTSA battery safety proposals and evolving UN ECE axle load regulations alter validation timelines and capital deployment priorities for integrated drive programs.
Market Dynamics
Integrated drive axle architectures are compressing tiered supplier hierarchies as OEMs consolidate motor, gearbox, and differential sourcing into single-source programs, forcing component specialists to defend position through captive manufacturing or exclusive thermal management IP.
Growth Catalysts
- EPA tailpipe standards:Zero-emission mandates under US federal rules are accelerating powertrain electrification timelines across light-duty and medium-duty vehicle fleets, expanding qualified supplier pools for integrated axle systems.
- Battery-electric passenger vehicle platforms:Skateboard chassis designs from premium and mass-market OEMs are standardizing on compact axle-integrated motor layouts to maximize interior packaging efficiency.
- China's dual carbon goals:National carbon neutrality targets are tightening domestic motor power density requirements and redirecting foundry capacity toward high-efficiency axle components.
Market Restraints
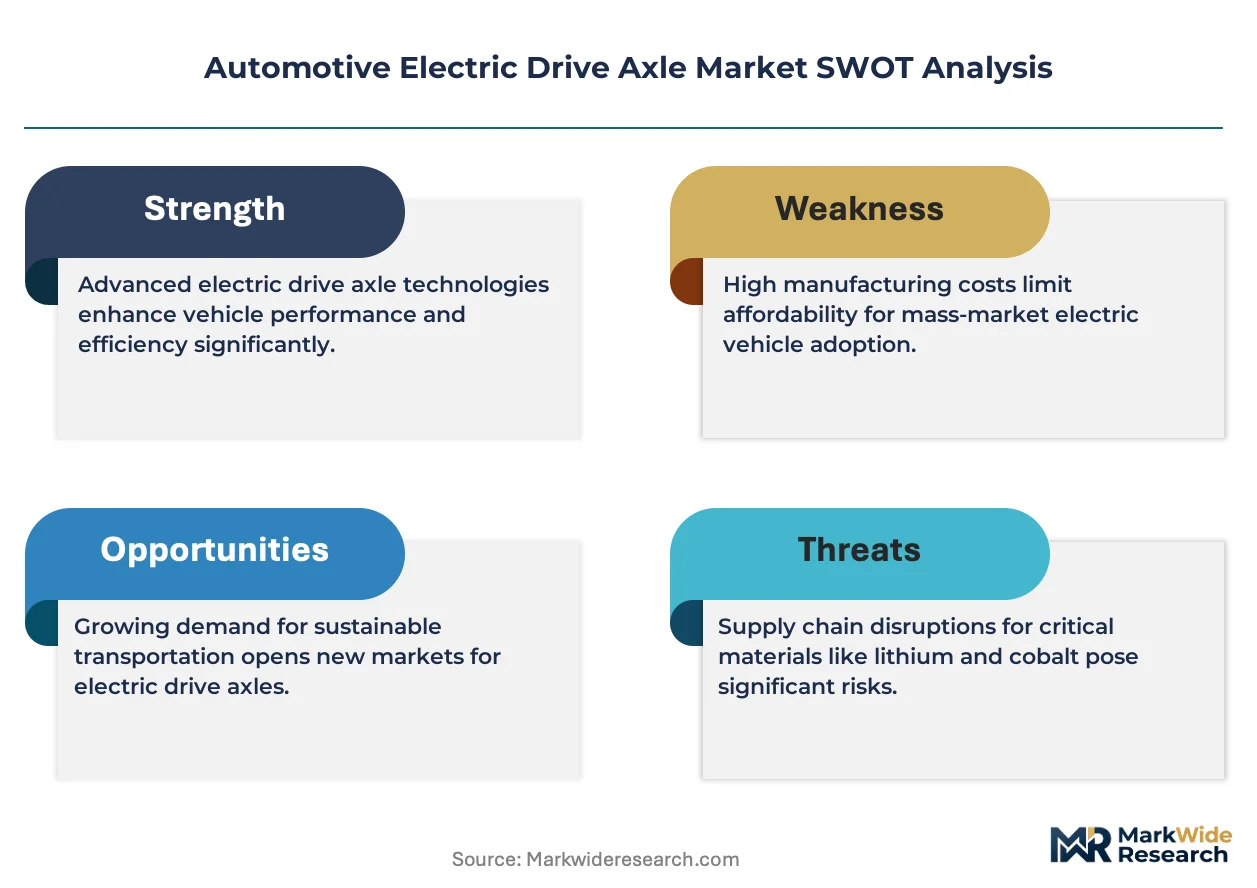
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings are compressing motor manufacturing margins and complicating long-term axle assembly quoting.
- Single-source semiconductor dependency:Concentrated silicon carbide substrate supply from East Asian foundries is creating vulnerability in inverter-integrated axle programs.
- ECE R10 electromagnetic compatibility certification:Extended validation timelines for integrated power electronics are delaying program launches and freezing engineering resources.
Strategic Opportunities
- Commercial vehicle retrofit demand:Urban freight electrification programs in Germany and the Netherlands are creating aftermarket axle replacement markets for existing diesel chassis.
- Torque-vectoring convergence with steer-by-wire:Premium platforms are unifying axle control with four-wheel steering architectures, opening software-defined differentiation.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive technology are attracting axle assembly investments to Pune and Chennai manufacturing corridors.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise is concentrated among a limited pool of suppliers, inflating recruitment costs and program risk.
- Legacy thermal management integration:Existing vehicle cooling circuits require redesign to handle axle-integrated motor heat rejection, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Drive Axle Market |
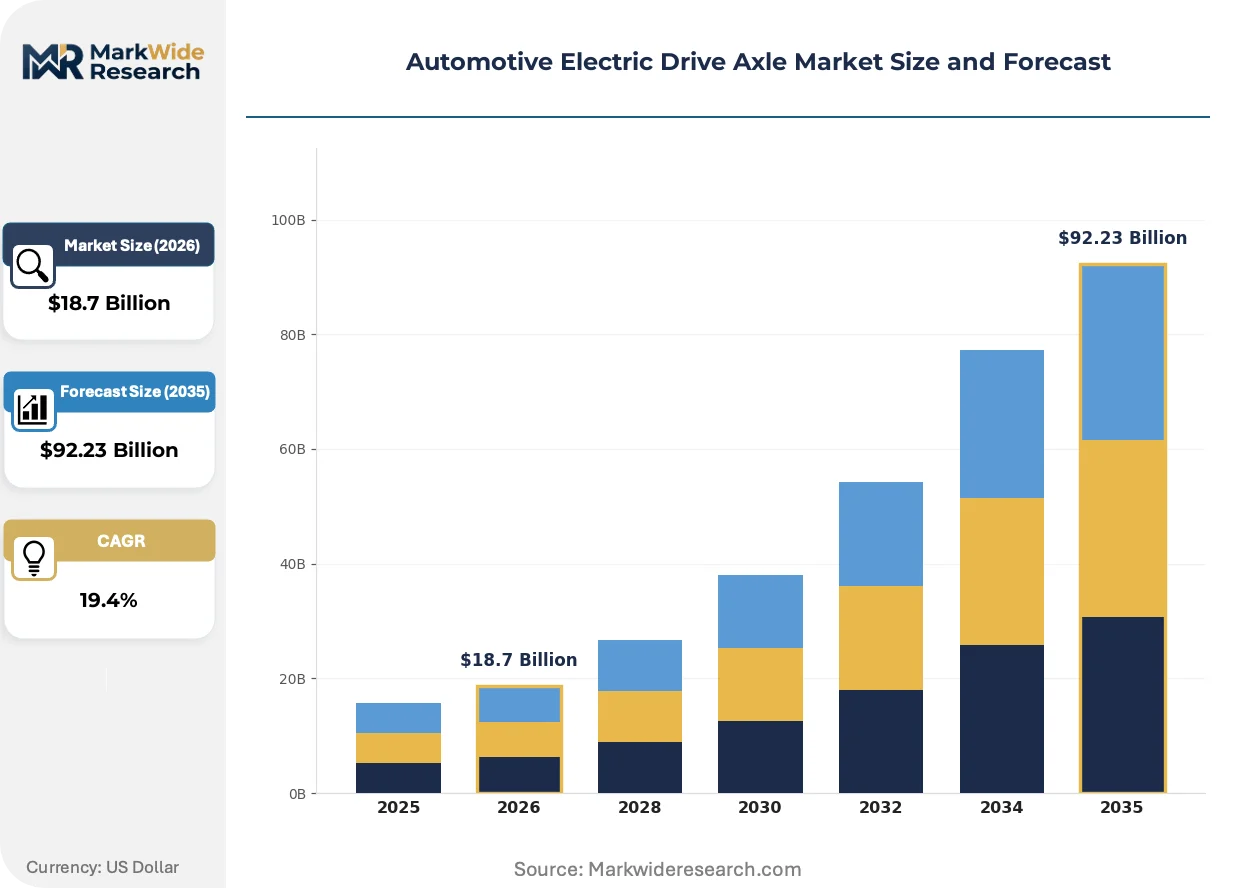
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axle, Dual Axle, Multi-Axle, Integrated Drive Application: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy-Duty Vehicles Technology: Active Torque Distribution, Regenerative Braking, Direct Drive, Gear Drive End User: OEMs, Aftermarket Suppliers, Fleet Operators, R&D Institutions |
| Companies Covered | Dana Incorporated, Nidec Corporation, ZF Friedrichshafen AG, Magna International Inc., Continental AG, Robert Bosch GmbH, Schaeffler AG, American Axle & Manufacturing, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Drive Axle Market Emerging Trajectories
Axle system architecture is pivoting from mechanical consolidation toward electromechanical integration, with thermal management and software control emerging as the primary axes of supplier differentiation rather than gearing design alone.
Silicon carbide power electronics is expanding into integrated drive axle inverters, enabling higher switching frequencies that reduce motor size and improve efficiency at highway speeds. European premium OEMs are specifying SiC-based axle programs for next-generation electric SUVs. This semiconductor transition is expanding into mid-size vehicle segments previously served by silicon IGBT systems.
The EU Green Deal fleet CO2 targets are mandating binding zero-emission sales quotas that force axle suppliers to pre-certify electromagnetic compatibility and thermal endurance before platform nomination. German engineering corridors around Stuttgart are experiencing accelerated validation lab construction. Tier-one suppliers are responding by co-locating test facilities with OEM engineering centers to compress approval timelines.
Fleet procurement departments are consolidating axle sourcing decisions at the holding-company level rather than delegating to individual brand engineering teams, compressing supplier negotiation cycles and favoring dual-source production footprints. This concentration is displacing traditional tier-two component relationships in favor of direct OEM-axle manufacturer contracts. The shift is most visible in North American light-truck electrification programs where fleet operators specify standardized axle specifications across multiple nameplates.
Automotive Electric Drive Axle Market Segmentation
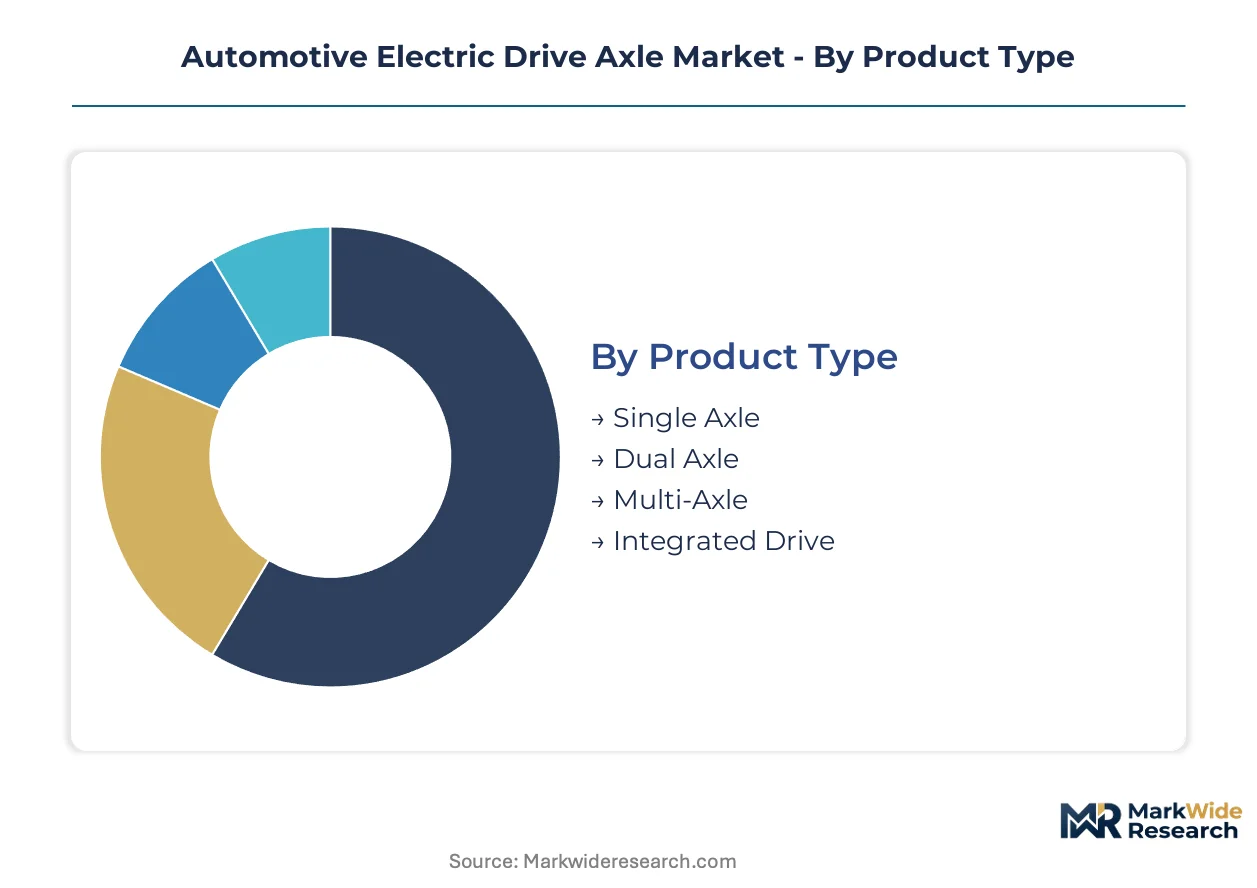
Axle architecture choices determine thermal management complexity, supplier consolidation patterns, and OEM platform standardization strategies. Segmentation reveals where engineering resources concentrate and which configurations command procurement priority in electrification programs.
Product Type:
Supply concentration in integrated axle manufacturing is compressing tiered supplier hierarchies as motor, gearbox, and differential sourcing collapses into single-source programs.
- Integrated Drive:Consolidates electric motor, reduction gearing, and differential into a single assembly with peak power densities above 3.5 kW per kilogram. Battery-electric passenger vehicle platforms in Germany's Stuttgart corridor are standardizing on this configuration to maximize interior packaging efficiency. Integrated Drive absorbs the bulk of installed capacity; Dual Axle is expanding most quickly.
- Dual Axle:Deploys independent drive units at both axles for all-wheel-drive capability without mechanical driveline connections. Demand concentrates in electric SUVs and light trucks where torque biasing improves traction performance. China's MIIT new energy vehicle catalog is tightening domestic content thresholds for these systems.
- Single Axle:Powers one axle pair through a centralized motor and differential, remaining cost-competitive for front-wheel-drive urban passenger vehicles with moderate range requirements.
- Multi-Axle:Configures three or more driven axles for heavy freight and specialty applications where distributed torque improves load handling on uneven terrain.
Integrated Drive captures the majority of engineering investment; Dual Axle configurations are gaining share fastest in premium platform nominations.
Application:
Cost tier differentiation separates high-volume passenger programs from specialized commercial vehicle requirements with divergent thermal and durability specifications.
- Passenger Vehicles:Prioritizes packaging density and NVH performance over absolute torque capacity. Skateboard chassis designs from European and North American OEMs are standardizing compact axle-integrated motor layouts. Passenger Vehicles dominate current production volumes; Light Trucks are climbing the fastest.
- Commercial Vehicles:Demands sustained torque output for urban freight duty cycles with regenerative braking integration for stop-and-go routes. Germany and the Netherlands are electrifying existing diesel chassis through retrofit axle programs.
- Light Trucks:Combines passenger vehicle packaging constraints with commercial-grade towing capacity, requiring dual-axle or torque-vectoring architectures. Fleet procurement departments are consolidating sourcing decisions at holding-company level across multiple nameplates.
- Heavy-Duty Vehicles:Requires multi-axle configurations with gear drive technology to manage sustained loads exceeding direct-drive motor efficiency curves.
Passenger Vehicles anchor current manufacturing capacity; Light Trucks are scaling most rapidly in North American electrification programs.
Technology:
Volume concentration in gear drive systems for commercial applications contrasts with direct drive adoption in passenger segments where motor speed range suffices.
- Gear Drive:Employs reduction gearing to match motor efficiency zones with wheel speed requirements under sustained torque loads. Dominates commercial vehicle applications where EPA tailpipe standards are accelerating medium-duty fleet electrification timelines. Gear Drive maintains the largest installed base; Active Torque Distribution is expanding most quickly.
- Direct Drive:Eliminates mechanical reduction through high-speed motor design, reducing component count and maintenance points for passenger vehicle duty cycles.
- Active Torque Distribution:Varies torque split between axles or wheels in real-time through software-controlled inverters. Premium platforms are unifying this capability with steer-by-wire architectures for software-defined differentiation.
- Regenerative Braking:Recaptures kinetic energy through axle-integrated motor operation, with efficiency gains dependent on inverter semiconductor selection and battery thermal state.
Gear Drive retains the majority of commercial vehicle installations; Active Torque Distribution is gaining share fastest in premium SUV nominations.
End User:
Customer type fragmentation separates captive OEM production from aftermarket retrofit demand with divergent certification and validation requirements.
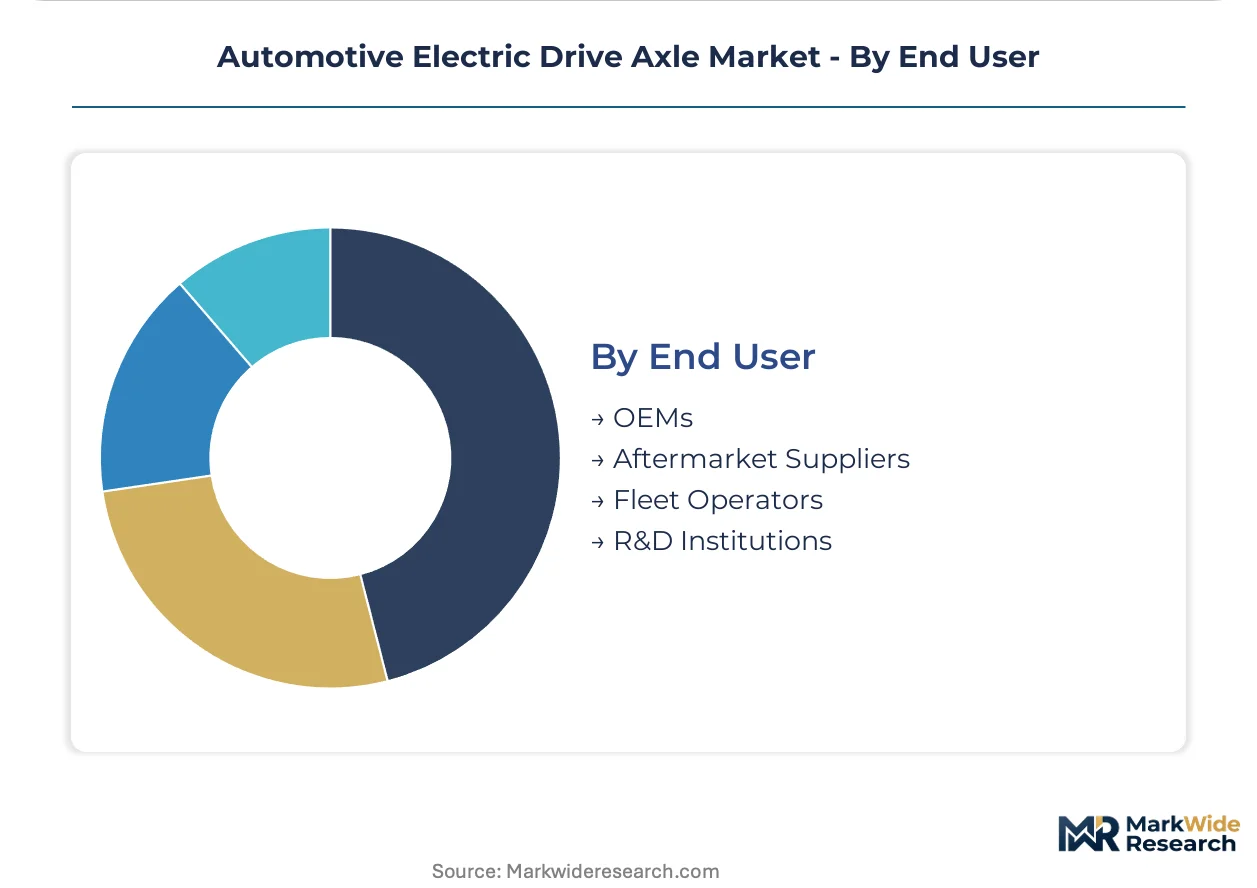
- OEMs:Specify axle systems at platform conception with integrated thermal management and ECE R10 electromagnetic compatibility certification. Tier-one suppliers are co-locating test facilities with OEM engineering centers to compress approval timelines. OEMs command the dominant procurement volume; Fleet Operators are scaling fastest.
- Fleet Operators:Consolidate specifications across holding-company vehicle portfolios, favoring standardized axle configurations with dual-source production footprints for supply security.
- Aftermarket Suppliers:Serve retrofit demand for existing diesel chassis in urban freight electrification programs, requiring compatibility with legacy cooling circuits and suspension geometries.
- R&D Institutions:Validate next-generation silicon carbide inverter integration and torque-vectoring algorithms ahead of commercial platform adoption.
OEMs absorb the bulk of qualified production capacity; Fleet Operators are expanding procurement most quickly as electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing capacity in Inner Mongolia anchors axle motor supply chains for export programs. China's dual carbon goals and MIIT efficiency mandates redirect foundry investment toward high-density motor architectures. European and North American OEM procurement teams now qualify Chinese axle assemblies for platform integration.
China
Battery-electric passenger vehicle platforms from BYD and NIO accelerate integrated drive axle procurement. MIIT new energy vehicle catalog ties subsidy eligibility to domestic motor and axle content thresholds above 60 percent. Foundry capacity concentrates in Ningbo and Suzhou manufacturing corridors serving European OEM nomination programs.
Germany
Premium OEM skateboard chassis programs standardize torque-vectoring axle architectures for electric SUV lineups. EU Green Deal fleet CO2 targets mandate binding zero-emission sales quotas from 2035. Engineering validation labs cluster around Stuttgart and Munich as tier-one suppliers co-locate test facilities with OEM centers.
United States
Fleet operators consolidate axle sourcing decisions at holding-company level across light-truck electrification programs. EPA tailpipe standards accelerate medium-duty fleet electrification timelines through 2030. Manufacturing investment concentrates in Michigan and Ohio corridors where American Axle & Manufacturing anchors production.
Japan
Direct-drive motor architectures gain traction in compact passenger vehicle segments where packaging efficiency outweighs absolute torque capacity. METI carbon neutrality roadmaps tighten motor efficiency standards for export-bound axle systems. Industrial concentration persists in Nagoya and Toyota City engineering clusters.
India
Urban freight electrification programs in Delhi and Mumbai create aftermarket axle replacement demand for existing diesel chassis. PLI scheme for auto components attracts assembly investment to Pune and Chennai manufacturing corridors. Domestic OEMs source gear drive axles for medium-duty commercial vehicle platforms.
Automotive Electric Drive Axle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon carbide inverter integration and torque-vectoring software stacks. The vendor base compresses around integrated system suppliers capable of certifying electromagnetic compatibility under ECE R10 and thermal endurance under ISO 26262. Three archetypes dominate: diversified automotive suppliers with captive motor manufacturing, pure-play axle specialists defending position through thermal management IP, and semiconductor-forward entrants leveraging SiC substrate relationships. Consolidation pressure intensifies through single-source program nominations and co-located validation facility investments.
Among German-based engineering conglomerates, ZF Friedrichshafen AG and Schaeffler AG exemplify the diversified supplier archetype with integrated powertrain portfolios. Dana Incorporated represents North American fabrication scale with in-house motor manufacturing capabilities. These three anchors illustrate how geographic production footprints and captive supply chains determine qualification pathways for OEM platform nominations.
| Leading Market Players |
|---|
| Dana Incorporated |
| Nidec Corporation |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Continental AG |
| Robert Bosch GmbH |
| Schaeffler AG |
| American Axle & Manufacturing |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Captive motor manufacturing anchors supply position and pricing power for integrated axle suppliers, compressing tiered hierarchies as OEMs consolidate sourcing into single-source programs with bundled thermal management and certification warranties.
Pricing Analysis
Warranty bundling separates integrated axle suppliers from component vendors, with ECE R10 electromagnetic compatibility and ISO 26262 thermal endurance certifications commanding premium positioning against unbundled motor-gearbox combinations. Three-tier pricing structure across premium torque-vectoring, standard integrated drive, and economy single-axle configurations reflects certification grade and volume scale differentials. Cost compression in standard integrated drive tiers is intensifying because rare-earth magnet price volatility feeds directly into motor manufacturing margins. Fleet operators exhibit highest price sensitivity through holding-company consolidated sourcing, while premium OEM platform engineering teams prioritize thermal management IP over unit cost.
Supply Chain Analysis
China's MIIT domestic content thresholds above 60 percent are redirecting foundry investment toward Ningbo and Suzhou manufacturing corridors serving export programs. Rare-earth magnet processing in Inner Mongolia, silicon carbide substrate concentration in East Asian foundries, and copper winding supply from Chilean mining operations form critical input dependencies. Single-source semiconductor vulnerability in SiC inverter-integrated axle programs creates structural supply risk. Distribution runs through direct OEM-axle manufacturer contracts displacing traditional tier-two relationships, with tier-one suppliers co-locating test facilities near Stuttgart and Munich engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power electronics is replacing silicon IGBT systems as the dominant inverter technology, compressing development cycles and reshaping supplier qualification pathways across passenger and commercial vehicle platforms.
For Market Incumbents: Extend captive motor manufacturing capabilities to defend margin position against rare-earth cost volatility, while accelerating ISO 26262 ASIL-D certification investment to capture premium torque-vectoring nominations. Capacity addition in China's Ningbo corridor secures MIIT content threshold compliance for European OEM export programs. Thermal management IP retention becomes the critical lever as mechanical gearing design commoditizes. For New Entrants and Emerging Players: SiC inverter integration offers a technology-first wedge into mid-size vehicle segments previously served by silicon-based systems, with aftermarket retrofit demand for urban freight electrification in Germany and the Netherlands representing the most penetrable white-space target. Direct fleet operator relationships bypass consolidated OEM sourcing hierarchies. Target India's PLI scheme corridors in Pune and Chennai for assembly investment with lower incumbent density. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified automotive suppliers with captive motor manufacturing and dual-source production footprints. Long-term viability hinges on silicon carbide substrate relationships and torque-vectoring software stacks. Watch NHTSA battery safety proposal finalization as the inflection signal for validation timeline compression and capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Enables higher switching frequencies that reduce motor size for highway-speed efficiency gains. |
| Torque-Vectoring Software Development | Unifies axle control with steer-by-wire architectures for premium platform differentiation. |
| Dual-Source Production Footprint | Addresses fleet operator supply security requirements across North American light-truck programs. |
| Co-Located Validation Facility Investment | Compresses ECE R10 approval timelines with OEM engineering centers in Stuttgart corridor. |
| Rare-Earth Magnet Supply Hedging | Mitigates neodymium and dysprosium price volatility compressing motor manufacturing margins. |
Methodological Framework
Multi-period observation of axle platform nominations, thermal management patent filings, and MIIT catalog entries anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and thermal management R&D leads. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA tailpipe standard dockets, and EU Green Deal implementation reports. Bottom-up segmentation modeling triangulated against top-down OEM electrification commitment disclosures.
Input-output matrices mapped vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs derived from installed capacity expansion trajectories, platform nomination timelines, and fleet electrification mandate compliance schedules. Silicon carbide adoption curves and rare-earth price elasticity assumptions fed sensitivity testing.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, abrupt rare-earth export restrictions, and semiconductor foundry allocation shocks. Forecasts reflect documented assumptions about regulatory timeline adherence and technology cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Engine Piston Ring Set Market